
 US Precast Concrete Market | 2026-2036
US Precast Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
US Precast Concrete Market Outlook
Direct-to-contractor distribution channels are reshaping how precast concrete reaches job sites across the United States. Forterra leverages its vertically integrated manufacturing network to control delivery timelines on large infrastructure bids. High Concrete Group specializes in architectural precast systems for commercial facades in the Mid-Atlantic and Northeast. CRH plc anchors its position through Oldcastle Infrastructure, which dominates the utility and drainage precast segment.
US precast concrete refers to factory-cast structural and architectural elements produced under controlled conditions using Portland cement, aggregates, and steel reinforcement, then transported to construction sites for assembly. The manufacturing process employs steel or fiberglass forms, mechanical vibration, and accelerated curing to achieve compressive strengths exceeding 4,000 psi for load-bearing applications. Reinforced concrete technology leads volume production due to its versatility in beams, columns, and wall panels for multi-story construction. Pre-stressed concrete commands premium positioning in bridge girders and parking structures where span requirements exceed conventional reinforced capacity. Infrastructure end-use represents the fastest-growing demand pool as state DOTs specify precast bridge components for accelerated project delivery.
The Federal Highway Administration mandates AASHTO LRFD specifications for precast bridge elements, while OSHA enforces silica exposure limits during precast manufacturing that influence plant capital investment decisions. ASTM C150 and PCI certification standards govern material quality and dimensional tolerances, creating compliance barriers for non-certified producers. Stakeholders must monitor state-level Buy America waivers and evolving EPA concrete recycling mandates that will determine competitive positioning in public procurement channels.
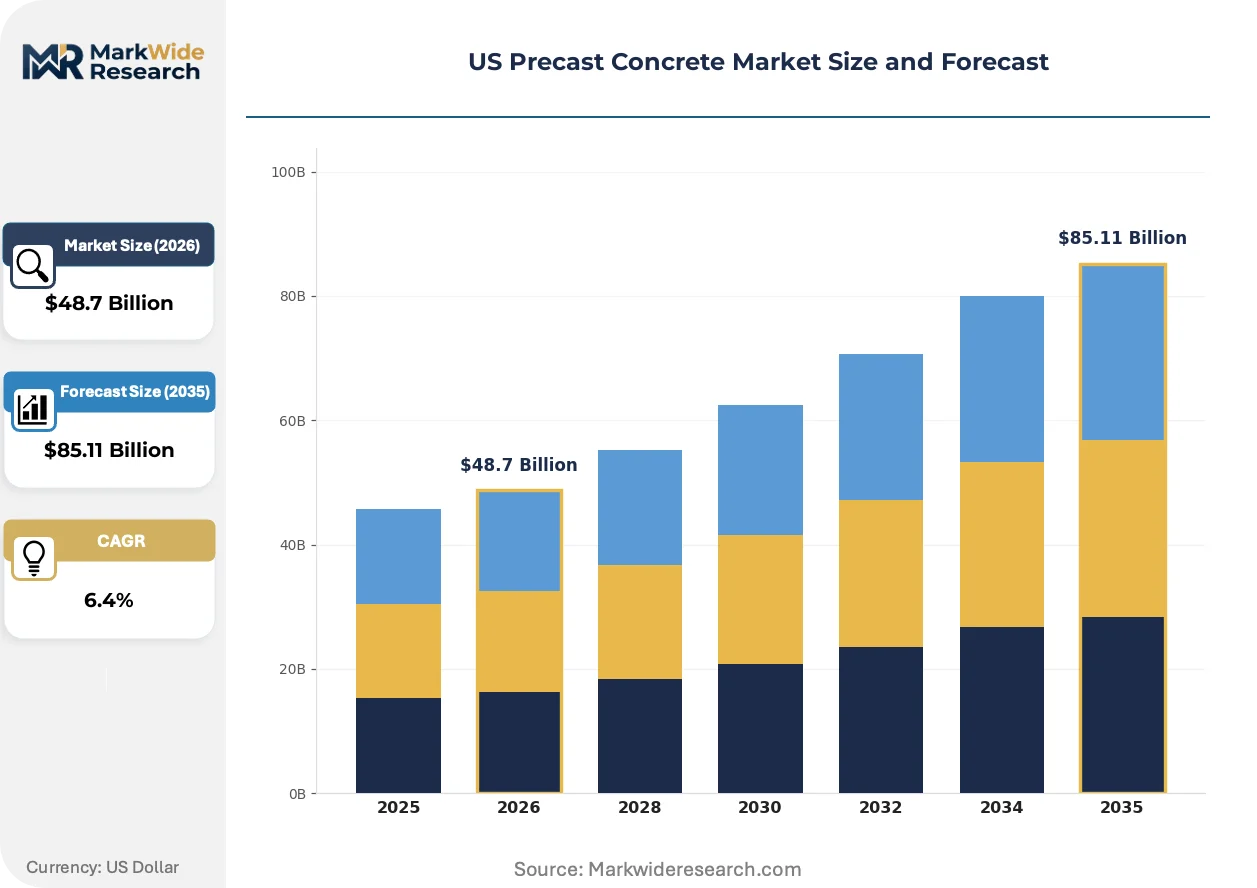
Market Dynamics
Federal infrastructure spending under the Infrastructure Investment and Jobs Act is compressing project delivery timelines and forcing state DOTs toward accelerated bridge construction methods that favor factory-cast components over cast-in-place alternatives.
Growth Catalysts
- IIJA bridge funding:Federal highway appropriations mandate precast deck panels and full-depth precast deck systems for replacement projects, locking in multi-year procurement pipelines for certified producers.
- Urban density mechanics:Population concentration in Texas, California, and Florida generates recurring demand for parking structures, mid-rise residential pods, and commercial facades that exploit precast speed-to-occupancy.
- Accelerated Bridge Construction:State DOTs specify precast pier caps and bulb-tee girders to minimize lane closures, converting time savings into bid evaluation premiums for contractors.
Market Restraints
- Portland cement cost volatility:Energy-intensive clinker production exposes margins to natural gas and electricity price spikes, compressing returns for fixed-price infrastructure contracts.
- Silica compliance capital:OSHA's respirable crystalline silica permissible exposure limit forces plant ventilation upgrades and wet-cutting retrofits that burden smaller regional competitors.
- Site-cast substitution in low-rise:Tilt-up concrete and insulated concrete forms retain cost advantages for single-story industrial and warehouse construction in secondary markets.
Strategic Opportunities
- Carbon-capture concrete:Emerging CO2 mineralization technologies during curing offer pathways to meet EPA embodied carbon mandates for federal procurement preference.
- Seismic retrofit corridors:California and Pacific Northwest bridge replacement cycles create concentrated demand for precast column jackets and cap beam replacements engineered to current AASHTO seismic specifications.
- Direct contractor channels:Bypassing traditional distributor markups through dedicated project logistics teams captures margin and locks out commodity competitors on complex multi-phase developments.
Industry Challenges
- PCI certification backlog:Plant qualification audits and MNL quality system documentation create 12-18 month barriers to entry for new capacity in high-demand regions.
- Precast-erector coordination:Tolerance stacking between factory production and field placement demands specialized rigging crews, constraining project velocity where skilled labor pools are thin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Precast Concrete Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walls, Beams, Columns, Slabs Technology: Autoclaved Aerated Concrete, Pre-stressed Concrete, Reinforced Concrete, Lightweight Concrete End User: Residential Buildings, Commercial Buildings, Infrastructure, Industrial Facilities Application: Construction, Repair, Renovation, Landscaping |
| Companies Covered | Forterra, High Concrete Group, CRH plc, Clark Pacific Corporation, Smith-Midland Corporation, Oldcastle Infrastructure, Metromont Corporation, Gage Brothers, Jensen Precast, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Precast Concrete Market Strategic Shifts
Digital fabrication and connected logistics are compressing the traditional boundaries between precast design, production scheduling, and just-in-time site delivery. These shifts are reconfiguring how contractors evaluate total installed cost.
BIM-to-fabrication workflows are virtualizing the traditional shop drawing exchange between engineers and precast producers. State DOTs in California and Texas now mandate digital twin handoffs for bridge component approval, eliminating paper submittal cycles. This compression is collapsing the front-end engineering timeline from months to weeks on complex curved-girder projects.
EPA enforcement of concrete recycling mandates under evolving solid waste interpretations is pressuring producers to document post-industrial aggregate content. State procurement offices in Florida and Illinois have incorporated recycled content thresholds into bid scoring algorithms. Pre-casters with captive crushing and screening operations are securing preference points that translate to award probability.
Design-build and construction manager-at-risk contracts are consolidating specification authority away from dispersed architectural firms toward integrated delivery teams. These teams prioritize precast systems with proven erection speed and predictable crane schedules over lowest-first-cost alternatives. The shift is most pronounced in Texas medical campus and university housing verticals where occupancy deadlines are immovable.
US Precast Concrete Market Segmentation
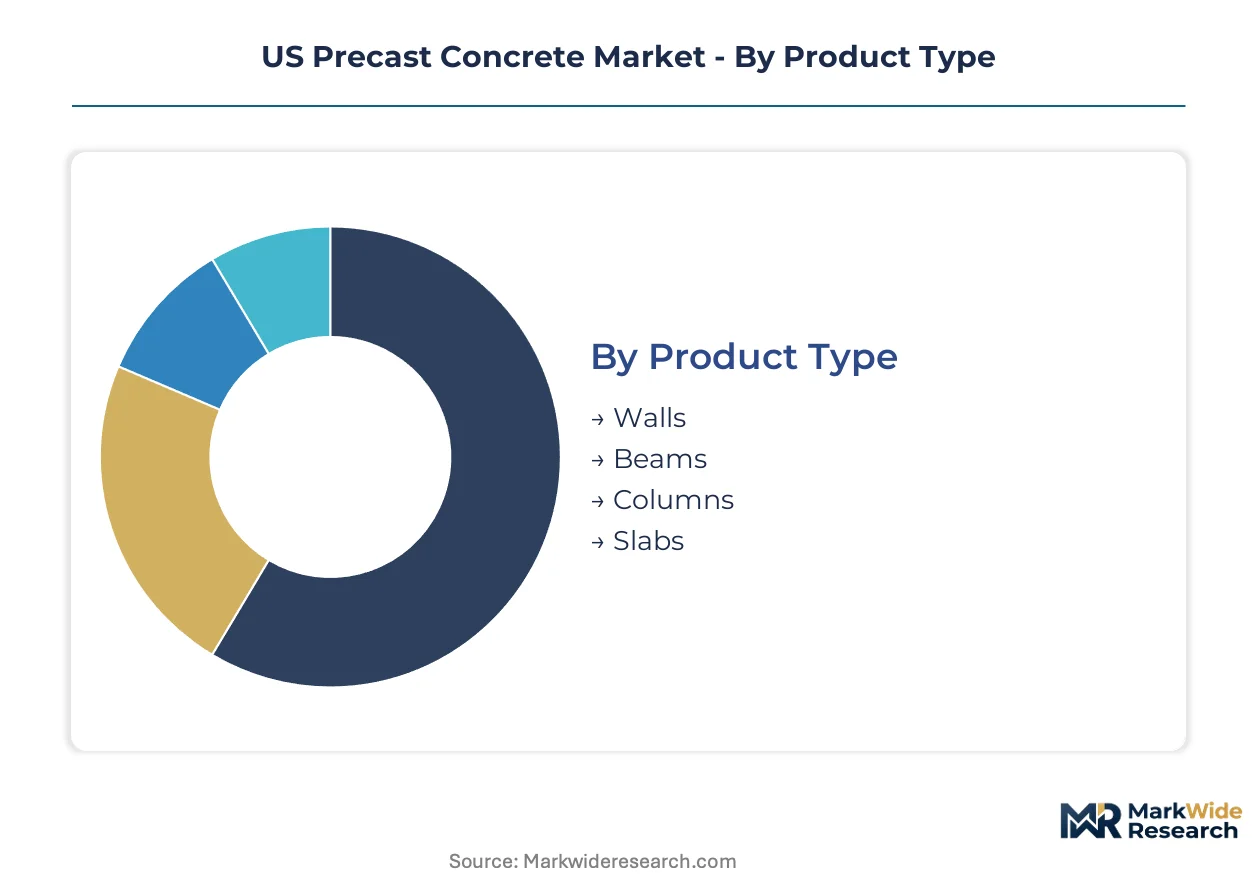
Precast concrete segmentation reveals how specification authority flows through distinct procurement channels. Product type and end-use combinations determine erection sequencing, crane scheduling, and warranty exposure that contractors must price into bids.
Product Type:
After-sales service intensity varies dramatically across structural element categories, with wall panels demanding the most intensive field coordination and tolerance remediation support.
- Walls:Architectural and load-bearing wall panels combine insulation, finishes, and structural capacity in factory-controlled conditions. Demand concentrates in Texas and Florida mid-rise residential pods where speed-to-occupancy compresses construction schedules. These panels require the most intensive post-delivery technical support for alignment and sealing.
- Beams:Long-span structural members exploit pre-stressing technology to achieve strength-to-weight ratios impossible with cast-in-place alternatives. Infrastructure end-use dominates, with state DOTs specifying bulb-tee and box girder profiles for accelerated bridge construction corridors in California and the Pacific Northwest.
- Columns:Square, round, and rectangular precast supports enable rapid vertical frame assembly in commercial and industrial construction. Standardized rebar cage configurations reduce engineering lead times for repeat building typologies.
- Slabs:Hollow-core and solid precast floor and roof decks provide immediate working platforms for subsequent trades. Parking structures and industrial warehouses specify these elements for their span capabilities and fire resistance ratings.
By volume, walls lead. By growth pace, beams are ahead.
Technology:
Technology selection maps directly to performance specifications and project cost tiers, with premium systems commanding engineering premiums for demanding structural applications.
- Reinforced Concrete:Conventional rebar-reinforced castings dominate volume production due to versatility across beam, column, and wall applications. Multi-story commercial construction in urban Texas corridors specifies these systems for their balance of strength and fabrication speed.
- Pre-stressed Concrete:High-tensile strand tensioning before curing enables longer spans and thinner sections than reinforced alternatives. Bridge girders and parking structures in seismic zones command premium positioning for their performance under dynamic loading.
- Autoclaved Aerated Concrete:Aluminum powder reactions create cellular structure yielding exceptional thermal insulation and fire resistance. Lightweight block and panel products serve residential and commercial envelope applications where energy code compliance drives specification.
- Lightweight Concrete:Expanded shale, clay, or slate aggregates reduce dead load for long-span elements and high-rise construction. Structural topping slabs and architectural cladding panels exploit density advantages for crane-limited sites.
Reinforced concrete holds the volume base. Pre-stressed concrete captures the margin expansion.
End User:
End-user concentration determines batch size economics and form reuse rates, with infrastructure buyers driving capital-intensive dedicated production lines.
- Infrastructure:State DOTs, municipal utilities, and federal agencies specify precast for bridge components, drainage structures, and transit system elements. IIJA funding pipelines in Texas, California, and Florida lock in multi-year procurement commitments for certified producers.
- Commercial Buildings:Office, retail, hospitality, and healthcare developers prioritize speed-to-revenue through precast structural frames and architectural envelopes. Urban density mechanics in Sun Belt metros generate recurring demand for parking structures and mixed-use podiums.
- Residential Buildings:Mid-rise multifamily and senior housing projects exploit precast wall panels for repetitive floor plate efficiency. Florida and California seismic and wind-load requirements favor factory quality control over site-cast alternatives.
- Industrial Facilities:Manufacturing plants, distribution centers, and data halls specify precast columns and wall panels for clear-span requirements and rapid enclosure. Tilt-up competition limits penetration in single-story warehouse construction.
Infrastructure commands the project scale. Commercial buildings deliver the repeat order frequency.
Application:
Application context shapes logistics complexity and margin structure, with new construction offering form reuse economies that renovation cannot match.
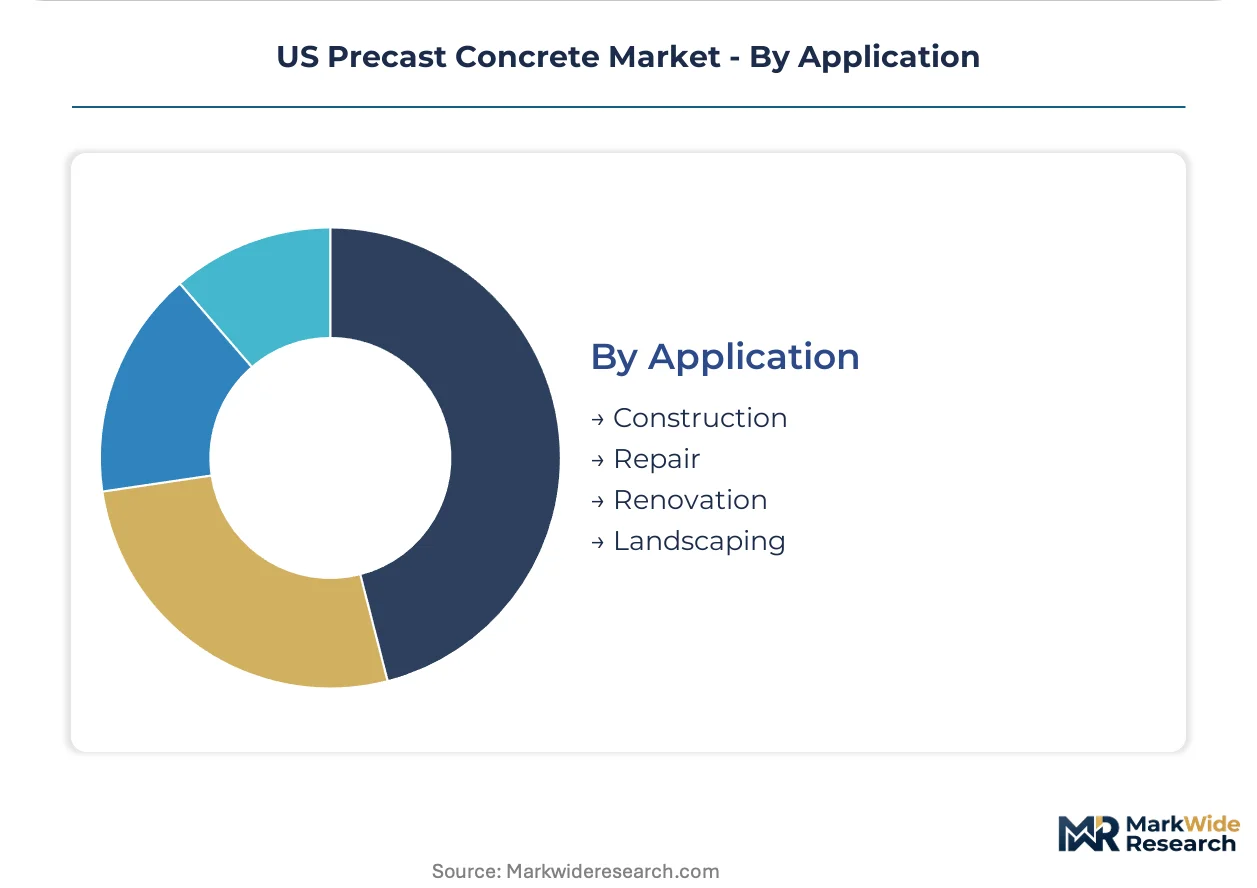
- Construction:Greenfield projects enable optimized production sequencing, just-in-time delivery coordination, and crane schedule certainty. Design-build contracts in Texas medical and university verticals consolidate specification authority around erection speed.
- Repair:Bridge deck replacement and structural strengthening projects demand custom-fit elements fabricated to as-built field measurements. Accelerated construction mandates from state DOTs favor precast for minimized traffic disruption.
- Renovation:Building envelope upgrades and structural modifications require dimensional flexibility and connection detailing adapted to existing conditions. Seismic retrofit corridors in California generate concentrated demand for column jacketing and cap beam replacements.
- Landscaping:Retaining walls, planters, and site furniture exploit precast durability and aesthetic versatility. Municipal and commercial landscape architects specify these elements for installation speed and maintenance predictability.
Construction anchors the volume base. Repair applications are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas precast producers extract pricing premiums from IIJA-funded bridge corridors that California competitors cannot match. Florida's hurricane-code wall panel demand runs on different procurement cycles than Pacific Northwest seismic retrofit timelines. These asymmetries fragment national pricing benchmarks.
Texas
State DOT bridge replacement pipelines and Houston medical campus expansions drive concentrated demand for pre-stressed girders and architectural wall systems. Federal Highway Administration Buy America waivers for select components influence sourcing decisions on border-crossing infrastructure. Dallas-Fort Worth precast clusters serve the I-35 corridor acceleration projects with dedicated production lines.
California
Seismic retrofit mandates and high-speed rail station construction generate specialized demand for ductile column systems and platform components. Caltrans AASHTO LRFD compliance requirements exceed federal baselines, creating certification barriers for out-of-state producers. Los Angeles Basin fabricators dominate the I-5 bridge deck replacement cycle through accelerated construction partnerships.
Florida
Hurricane wind-load codes and senior housing construction cycles sustain demand for insulated wall panels with integral impact resistance. State procurement offices incorporate recycled aggregate thresholds into bid scoring under evolving EPA solid waste interpretations. Tampa-Orlando precast corridors specialize in mid-rise residential pod systems for Sun Belt migration patterns.
Pacific Northwest
Cascadia Subduction Zone seismic upgrades and Columbia River bridge replacements command high-performance precast specifications. Oregon and Washington state DOTs specify carbon-capture concrete pilot projects under federal climate procurement preferences. Seattle-Tacoma fabricators anchor the I-5 corridor retrofit market with specialized erection coordination teams.
Southeast
Georgia and Carolinas distribution center construction and Charleston port expansion projects drive demand for clear-span precast systems. State-level silica compliance enforcement lags federal OSHA timelines, creating temporary cost advantages for smaller regional producers. Atlanta precast clusters serve the I-85 commercial corridor with standardized parking structure modules.
US Precast Concrete Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on narrower specification authority. The US precast concrete market structures around vertically integrated infrastructure platforms, architectural system specialists, and regional structural fabricators. Three archetypes dominate: multi-divisional construction material conglomerates with captive precast capacity; dedicated precasters with PCI-certified plant networks; and regional single-plant operators serving local contractor relationships. Consolidation pressure operates through DOT qualification requirements and IIJA procurement scale thresholds, while differentiation centers on erection speed guarantees and digital twin delivery capabilities.
Among US-based infrastructure specialists, Forterra and Oldcastle Infrastructure exemplify platform-scale positioning through vertically integrated manufacturing networks and federal procurement channel access. High Concrete Group occupies the architectural precast tier with Mid-Atlantic and Northeast geographic concentration. These three anchors demonstrate how scale, specialization, and regional density configure competitive advantage across distinct specification channels.
| Leading Market Players |
|---|
| Forterra |
| High Concrete Group |
| CRH plc |
| Clark Pacific Corporation |
| Smith-Midland Corporation |
| Oldcastle Infrastructure |
| Metromont Corporation |
| Gage Brothers |
| Jensen Precast |
| Others |
Value Chain & Pricing Dynamics
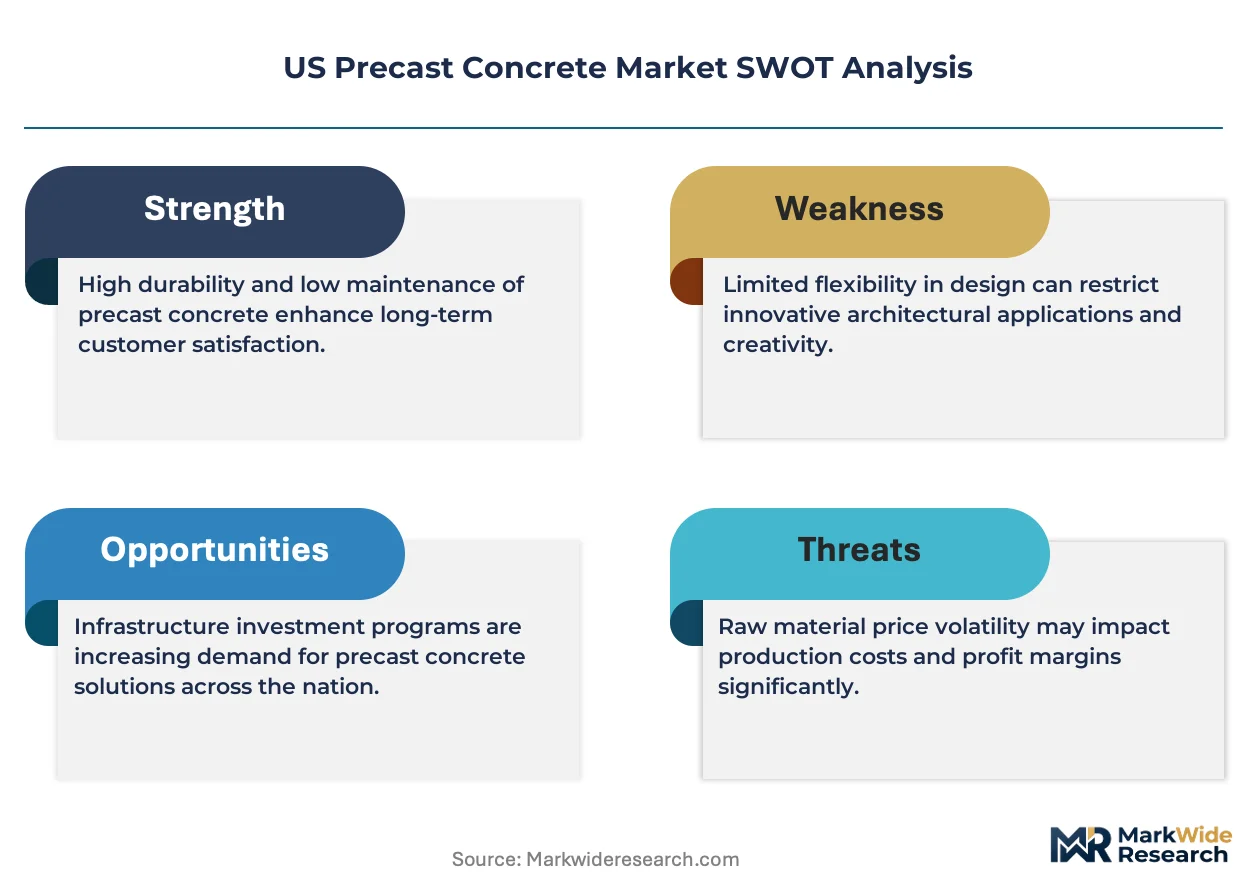
Portland cement cost volatility cascades through precast concrete pricing tiers, widening spreads between PCI-certified premium producers and commodity regional fabricators while compressing margins on fixed-price IIJA infrastructure contracts. Energy-intensive clinker production exposes both ends of the supply chain to natural gas and electricity price spikes, forcing capital allocation decisions between inventory buffering and spot market exposure.
Pricing Analysis
Configured-to-order pricing for custom architectural wall panels commands premiums of 15-25% over standard hollow-core slab quotations, with differentiation anchored in PCI certification grade and project-specific engineering support. Three-tier pricing structure across premium certified, standard commercial, and economy regional producers reflects after-sales service intensity and erection speed guarantees. Cost compression in the economy tier intensifies because tilt-up concrete retains cost advantages for single-story industrial construction. State DOTs exhibit lowest price sensitivity due to IIJA funding certainty, while speculative commercial developers negotiate hardest on standard structural elements.
Supply Chain Analysis
Upstream feedstock concentration in domestic Portland cement production centers on Texas, California, and Pennsylvania, with supplementary cementitious materials drawn from Midwest fly ash sources and Southeast slag processors. Steel rebar and pre-stressing strand hinge on domestic mill capacity and residual import flows from Mexico and Turkey. Single-source vulnerability concentrates in specialized formwork fabrication, where lead times extend when bridge component orders cluster. Distribution runs through direct-to-contractor channels for large infrastructure bids and regional distributor networks for commercial construction, with captive logistics teams capturing margin on complex multi-phase developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precast concrete incumbents face sustained substitution pressure from tilt-up concrete and insulated concrete forms in low-rise commercial construction, requiring defensive positioning around speed-to-occupancy and seismic performance advantages.
For Market Incumbents: Build certification moats by accelerating PCI plant qualification audits in Texas and California corridors before IIJA procurement peaks. Anchor backward integration into captive aggregate crushing operations to secure recycled content preference points under evolving EPA solid waste interpretations. Defend against site-cast substitution by guaranteeing erection speed with dedicated rigging crews on design-build medical campus contracts.
For New Entrants and Emerging Players: Mid-rise residential pods in Florida's Tampa-Orlando corridor represent the most penetrable entry point, with hurricane-code wall panel demand running on procurement cycles detached from infrastructure bidding. Seismic retrofit column jacketing in California offers specialized fabrication niches where AASHTO compliance barriers filter commodity competition. Target design-build contractors directly with BIM-to-fabrication workflow capabilities that collapse engineering timelines.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors PCI-certified platform integrators with DOT qualification depth and federal procurement channel access. Long-term viability rests on carbon-capture concrete pilot positioning and IIJA funding pipeline visibility. Acquisition targets should demonstrate captive erection coordination teams and digital twin delivery capabilities. Watch Caltrans and Texas DOT accelerated construction mandate expansion as the inflection signal for precast penetration rates.
| Strategic Initiative | Industry Significance |
|---|---|
| PCI Certification Expansion | Plant qualification audits in high-demand regions lock out commodity competitors on IIJA-funded bridge projects. |
| Carbon-Capture Concrete Pilot | CO2 mineralization during curing secures preference under federal climate procurement mandates. |
| Direct Contractor Channel Buildout | Bypassing distributor markups captures margin on complex multi-phase medical campus developments. |
| Captive Aggregate Recycling | In-house crushing operations satisfy Florida and Illinois recycled content thresholds in bid scoring. |
| BIM-to-Fabrication Integration | Digital twin handoffs collapse front-end engineering timelines from months to weeks on curved-girder projects. |
Study Parameters
Desk research of PCI certification databases, AASHTO LRFD specification updates, and state DOT procurement records preceded structured interviews with precast plant managers, DOT bridge engineers, commercial construction procurement leads, and specialized erection contractors. Secondary validation drew from EPA enforcement actions on silica exposure limits, FHWA Buy America waiver documentation, and IIJA funding allocation disclosures. Bottom-up production capacity modeling triangulated against top-down infrastructure spending projections across the analysis window.
Assumptions held IIJA bridge appropriation levels and state DOT accelerated construction mandate adoption rates fixed at current trajectory, while varying Portland cement price scenarios and OSHA silica compliance enforcement intensity. Segmentation modeling incorporated product type, technology tier, end-use concentration, and regional procurement cluster dimensions. CAGRs were derived from production capacity expansion schedules mapped against funded project pipelines, with cross-reference to historical form reuse rates and crane schedule density metrics.
Practitioners should monitor Portland cement energy input cost indices and state-level Buy America waiver expansions for early signals of margin compression or sourcing constraint. Forecasts reflect assumptions about federal infrastructure spending continuity and EPA recycling mandate enforcement timelines. Cross-checking against FHWA bridge component shipment data and PCI plant certification backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
Clay Roof Tiles Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
Plumbing Fixtures Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Building Modules Market
Building & Construction Materials
Sound Barriers Market
Building & Construction Materials
Building and Construction Sealants Market
Building & Construction Materials
Europe AAC Blocks and Panels Market