
 North America Dairy Protein Market | 2026-2036
North America Dairy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dairy Protein Market Analytics
Canada's expanding whey processing capacity is rewriting supply dynamics across the North American dairy protein landscape. Glanbia plc leverages its Idaho-based manufacturing footprint to sustain ingredient leadership in specialized nutritional applications. Fonterra Co-operative Group Limited anchors cross-border trade flows through its US distribution infrastructure. Kerry Group PLC differentiates via integrated flavor-protein formulation services targeted at sports beverage manufacturers.
North America dairy protein encompasses milk-derived fractions—whey and casein concentrates, isolates, and hydrolysates—standardized to protein contents ranging from 34% to over 90% on a dry-weight basis, serving functional roles in emulsification, gelation, and nutritional fortification. Whey protein dominates volume throughput due to its superior amino acid profile and rapid absorption kinetics favored by performance nutrition formulators. Casein retains structural importance in bakery and dairy applications where sustained protein release and water-binding capacity command premium positioning. The powder form category captures the majority of industrial procurement owing to extended shelf stability and flexible reconstitution protocols.
The FDA exercises direct oversight of dairy protein labeling claims and GRAS determinations, while USDA grading standards influence ingredient quality benchmarks for domestic and export-bound production. Health Canada and CFIA requirements shape cross-border product registration pathways, particularly for novel protein hydrolysate formats seeking functional food classification. Stakeholders must monitor evolving positions from FSMA preventive controls and anticipated CFIA modernization initiatives that will determine compliance costs for integrated processors.
Market Dynamics
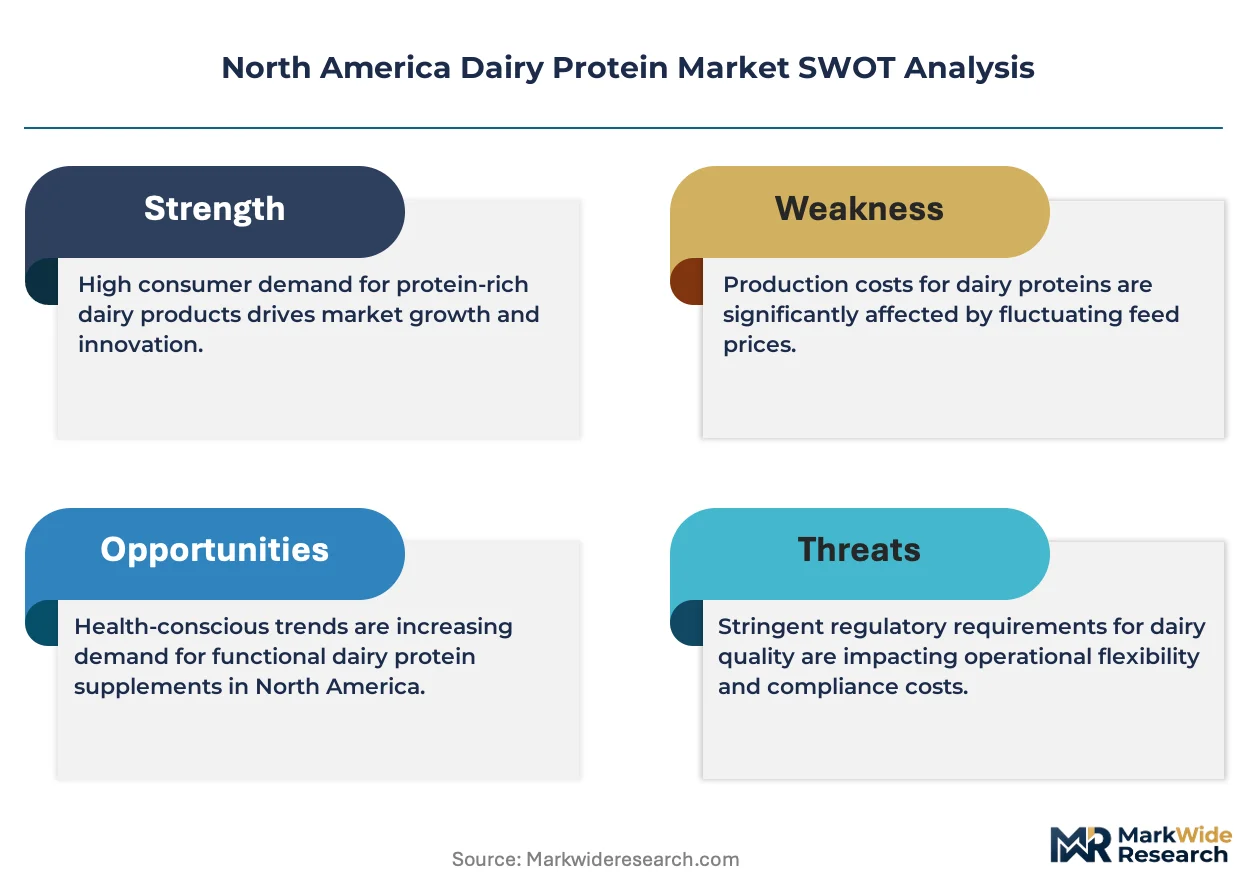
California's Central Valley dairy processing cluster is consolidating whey protein throughput, concentrating supply-side leverage among integrated processors who control both milk sourcing and fractionation capacity. This geographic concentration is reshaping contract pricing structures and forcing downstream formulators to secure multi-year supply agreements.
Growth Catalysts
- Sports nutrition formulation:Performance beverage manufacturers are expanding whey protein isolate procurement for rapid-absorption product lines targeting endurance athletes and CrossFit participants.
- FDA nutrition labeling modernization:Updated serving-size declarations and added-sugar line-item requirements are pushing brands toward cleaner-label protein fortification strategies.
- Canada's whey processing expansion:New fractionation capacity in Quebec and Ontario is diversifying North American supply origins and reducing single-source dependency.
Market Restraints
- Feed cost volatility:Corn and soybean meal price swings directly compress dairy processor margins, with feed representing the largest variable cost in milk production economics.
- Single-region concentration risk:California, Idaho, and Wisconsin collectively control over seventy percent of US whey protein manufacturing capacity, creating weather and regulatory exposure.
- Plant protein substitution:Pea and fava protein isolates are capturing share in mass-market nutrition bars where amino acid completeness is less critical to purchase decisions.
Strategic Opportunities
- Medical nutrition penetration:Sarcopenia-targeted clinical formulations present white space for micellar casein with sustained-release kinetics in long-term care settings.
- Precision fermentation convergence:Whey-identical proteins from microbial biomass are attracting venture funding, potentially decoupling supply from herd size constraints.
- Direct-to-practitioner distribution:Functional medicine clinicians represent an emerging channel for hydrolysate-based gut-health protocols outside conventional retail.
Industry Challenges
- Fractionation engineering talent scarcity:Specialized expertise in membrane separation and chromatographic purification commands premium compensation, constraining capacity expansion timelines.
- FSMA preventive control compliance:Hazard analysis requirements for allergen cross-contact are extending facility validation cycles and raising capital deployment thresholds for brownfield projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dairy Protein Market |
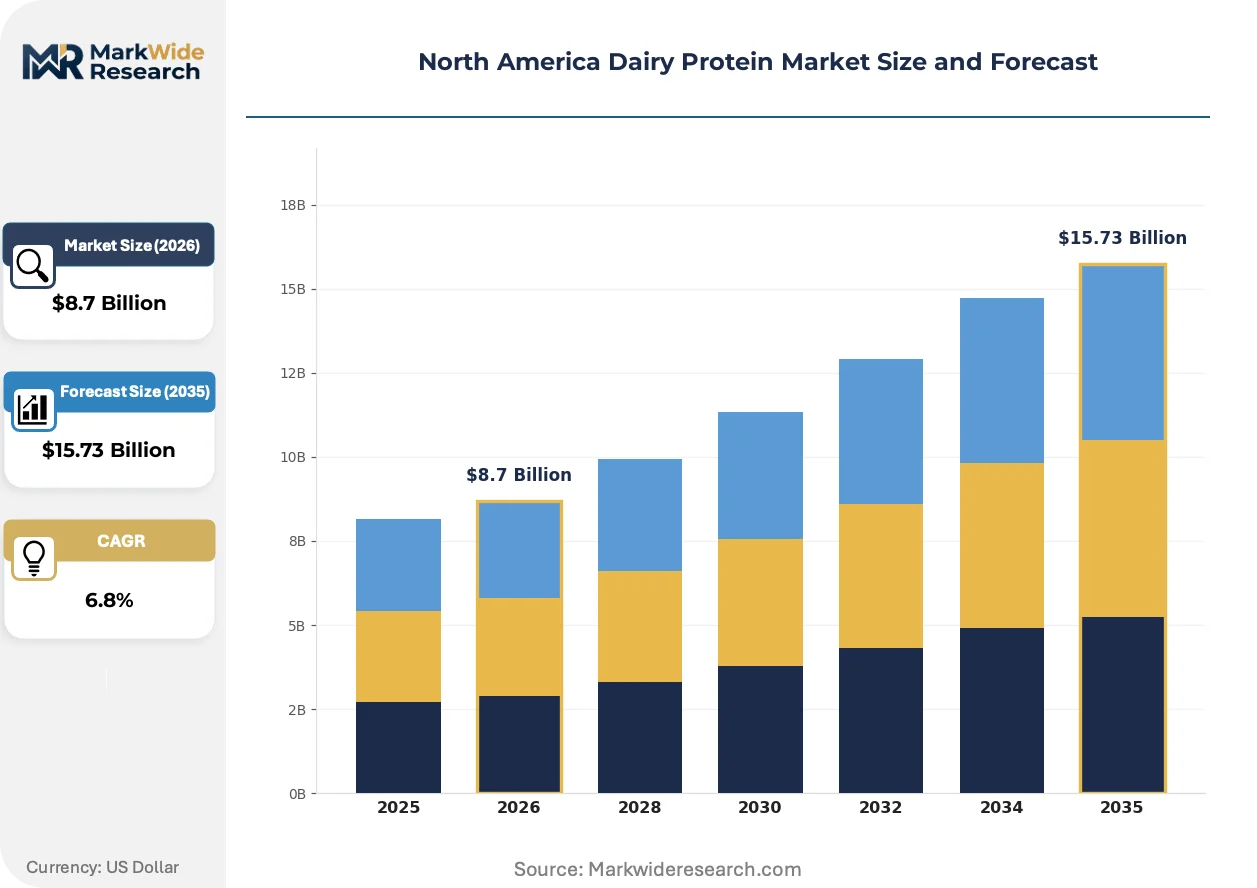
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein, Milk Protein Concentrate, Milk Protein Isolate Form: Powder, Liquid, Solid, Concentrate Application: Food & Beverage, Nutritional Supplements, Bakery, Dairy Products Customer Type: Manufacturers, Retailers, End Consumers, Distributors |
| Companies Covered | Archer Daniels Midland Company, Fonterra Co-operative Group Limited, Kerry Group PLC, Saputo Inc., Arla Foods, Glanbia plc, Dairy Farmers of America, Inc., Royal FrieslandCampina N.V., Lactalis Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dairy Protein Market Evolving Landscape
Digital process control systems are penetrating dairy protein fractionation, enabling real-time compositional monitoring that compresses batch-to-batch variability. This technological shift is redefining quality assurance economics and contract specification tightness.
Membrane filtration technology is digitizing whey protein concentration workflows, replacing manual sampling with inline spectroscopic monitoring. Large-scale processors in Idaho and California are adopting these systems to reduce protein standardization cycles from hours to minutes. The resulting yield precision is digitizing contract compliance, allowing suppliers to guarantee narrower protein content bands and command ingredient premiums.
FDA's updated nutrition labeling rules are mandating dual-column serving disclosures for multi-serving packages, forcing reformulators to rebalance protein fortification levels. Sports nutrition brands are responding by consolidating SKUs and standardizing single-serve packaging formats. The regulation is compressing product development cycles as brands race to relaunch ahead of enforcement deadlines.
Healthcare channel purchasing is consolidating procurement decisions under group purchasing organizations, displacing fragmented distributor relationships. Long-term care operators in the Midwest are centralizing clinical nutrition contracts under national GPO umbrellas. This concentration is compressing supplier margins while rewarding processors with dedicated medical-grade certification and formulary placement capabilities.
North America Dairy Protein Market Segmentation
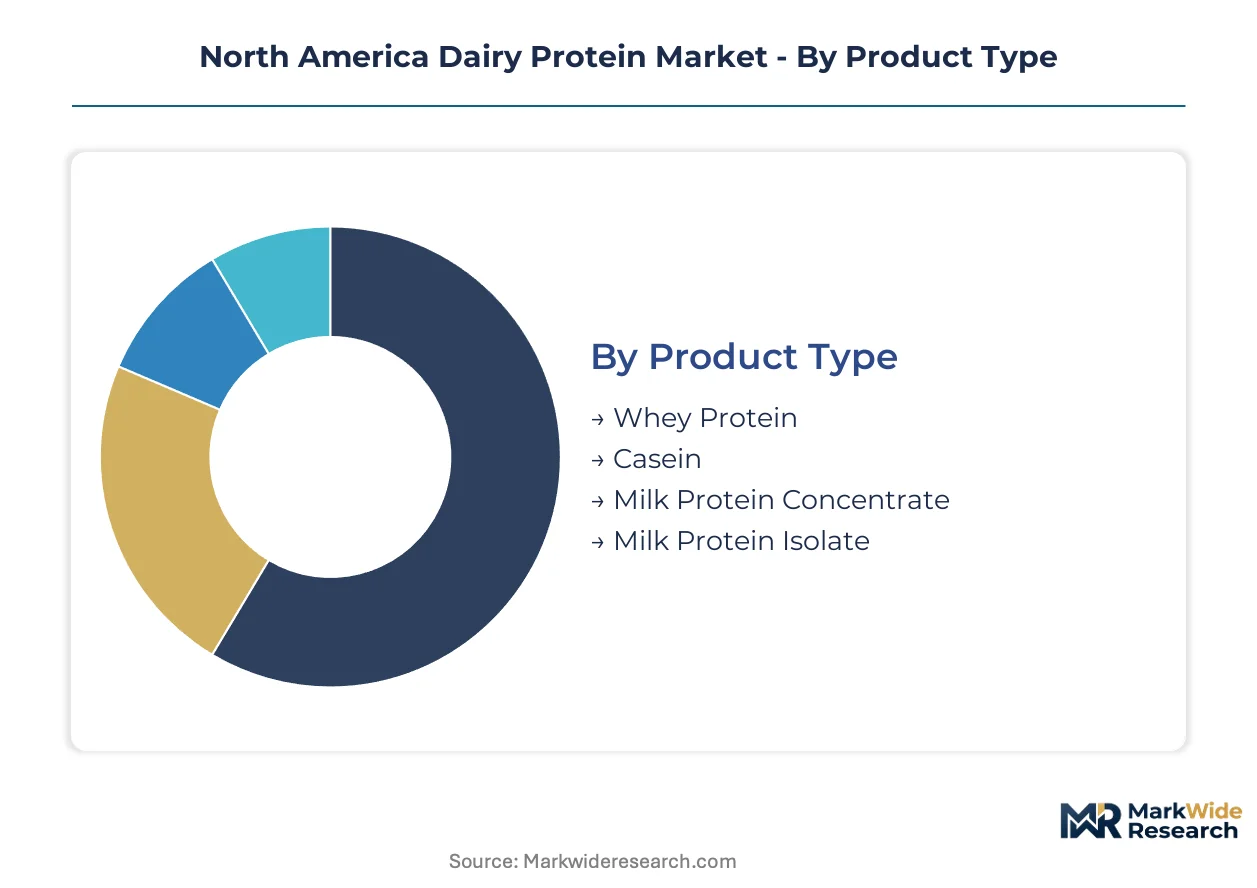
Dairy protein segmentation in North America reflects divergent technical specifications and procurement cycles across industrial channels. Whey protein isolates turn inventory fastest through sports nutrition contract manufacturing, while medical-grade casein hydrolysates move through extended validation timelines. Understanding these velocity differentials shapes working capital deployment and margin capture strategies for fractionation operators.
Product Type:
Cycle times vary dramatically across protein fractions, with rapid-turn whey isolates contrasting against slower-moving micellar casein grades destined for clinical nutrition.
- Whey Protein:Encompasses concentrates, isolates, and hydrolysates standardized to 34-90%+ protein content with rapid absorption kinetics. Sports beverage formulators in California's Central Valley cluster drive procurement velocity for isolate grades targeting CrossFit and endurance athlete segments. FDA nutrition labeling modernization is compressing SKU rationalization timelines for fortified ready-to-drink applications.
- Casein:Micellar and calcium caseinate variants deliver sustained amino acid release through coagulation-resistant structures. Long-term care operators in the Midwest anchor demand for micellar grades in sarcopenia-targeted clinical formulations, though Health Canada novel food pathways slow cross-border hydrolysate registration.
- Milk Protein Concentrate:Combined casein-whey fractions at 40-85% protein content serve cost-sensitive processed cheese and yogurt fortification. Mexican border-state processors leverage MPC for recombined dairy product economics.
- Milk Protein Isolate:90%+ protein content with native casein-whey ratios commands premium positioning in clean-label sports nutrition. Idaho-based integrated processors control majority MPI fractionation capacity.
Whey protein anchors the volume base while milk protein isolate gains share at the steepest rate through premium positioning in single-ingredient sports nutrition.
Form:
Cost tiers separate commodity bulk powders from value-added liquid concentrates and specialized solid formats serving distinct manufacturing infrastructures.
- Powder:Spray-dried and agglomerated variants dominate industrial procurement through extended shelf stability and flexible reconstitution protocols. California and Idaho processors standardize powder protein content bands through inline spectroscopic monitoring systems.
- Liquid:Retentate concentrates and hydrolysate solutions serve ready-to-drink beverage manufacturers with refrigerated supply chain capabilities. Quebec dairy processors are expanding liquid whey processing capacity to capture this channel.
- Solid:Extruded protein crisps and texturized fractions target nutrition bar and snack applications where mouthfeel differentiation commands formulation premiums.
- Concentrate:Intermediate protein streams at 34-80% content serve as blending inputs for standardization and cost optimization in mass-market applications.
Powder forms command the volume base while liquid concentrates expand most quickly through refrigerated sports beverage proliferation.
Application:
Customer maturity separates established food manufacturing from emerging direct-to-consumer channels with divergent technical service requirements.
- Food & Beverage:Emulsification, gelation, and foaming functional properties drive procurement for processed dairy, beverages, and prepared foods. Wisconsin cheese processors anchor demand for functional whey permeates and concentrates.
- Nutritional Supplements:Amino acid profile completeness and bioavailability certification dominate specification requirements. Sports nutrition brands in Utah and Colorado drive isolate and hydrolysate procurement for rapid-absorption product lines.
- Bakery:Water-binding and Maillard browning properties of casein and milk proteins support protein fortification in bread and pastry applications. Regional bakery cooperatives in the Pacific Northwest specify MPC for clean-label positioning.
- Dairy Products:Standardization and yield improvement in cheese, yogurt, and ice cream manufacturing leverage protein concentrates for solids-not-fat replacement.
Food and beverage anchors the volume base while nutritional supplements gain share at the steepest rate through sports and clinical nutrition premiumization.
Customer Type:
Supply concentration varies across integrated manufacturers, fragmented retail channels, and emerging direct-to-practitioner pathways with distinct certification burdens.
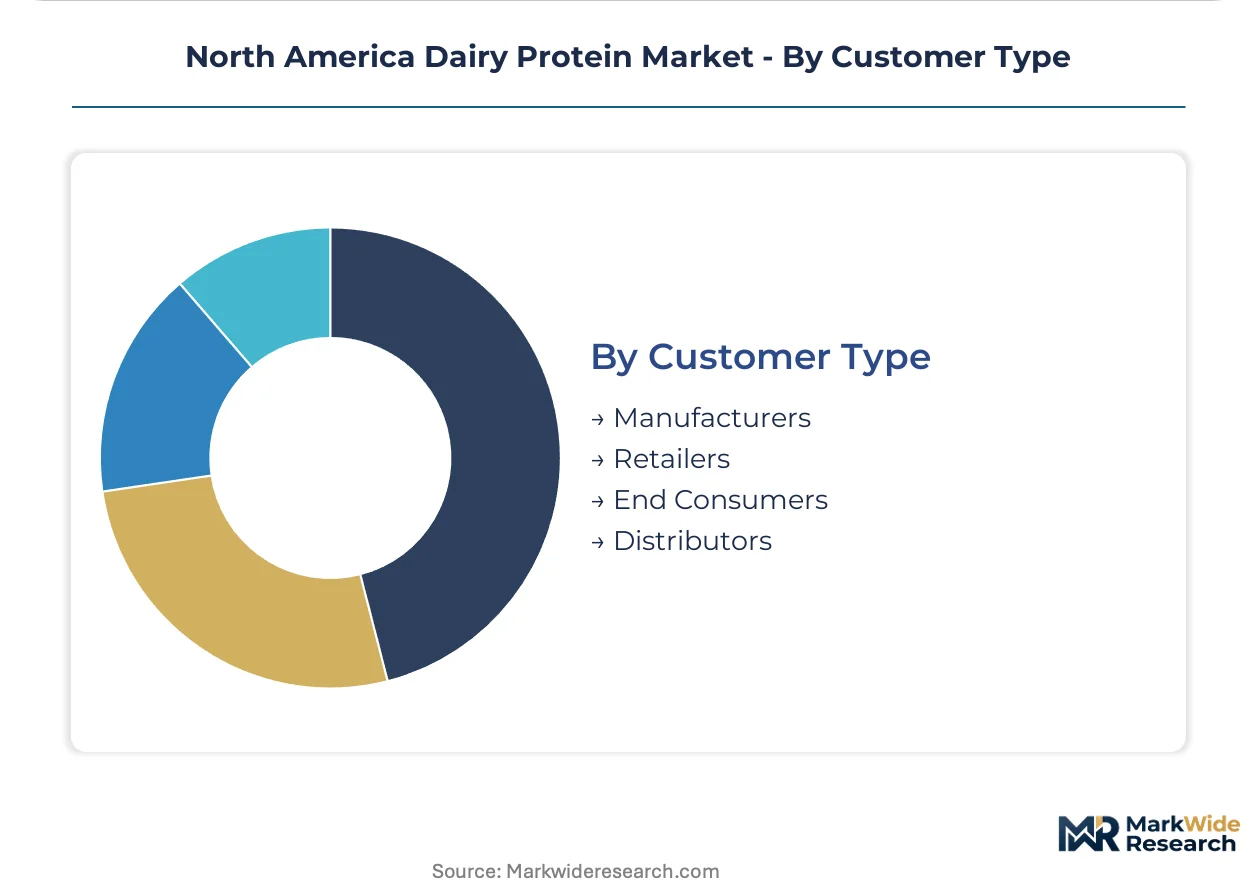
- Manufacturers:Contract beverage, bar, and clinical nutrition producers drive bulk procurement through multi-year supply agreements. Group purchasing organization consolidation in Midwest long-term care is compressing supplier margins while rewarding medical-grade certification capabilities.
- Retailers:Private-label sports nutrition and mass-market protein powder programs demand co-manufacturing partnerships with dedicated packaging and flavor integration services.
- End Consumers:Direct-to-consumer subscription models and practitioner-dispensed clinical protocols represent emerging channels outside conventional distributor relationships.
- Distributors:Ingredient and finished goods wholesalers manage inventory risk and technical service for mid-size formulators lacking direct processor relationships.
Manufacturers anchor the volume base while end consumers gain share at the steepest rate through subscription and practitioner-direct channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Whey protein fractionation capacity clusters in three US states and two Canadian provinces, creating geographic concentration that shapes contract pricing and supply security calculations for downstream formulators.
United States
California's Central Valley dairy processing cluster generates the majority of US whey protein throughput, with Idaho and Wisconsin contributing significant fractionation capacity. FDA nutrition labeling modernization and FSMA preventive controls determine compliance costs for integrated processors operating multi-state facilities. Utah and Colorado sports nutrition brands drive isolate procurement velocity for CrossFit and endurance athlete product lines.
Canada
Quebec and Ontario are expanding whey processing capacity through new fractionation investments that diversify North American supply origins. Health Canada and CFIA requirements govern cross-border product registration, particularly for novel hydrolysate formats seeking functional food classification. Montreal-area processors are capturing liquid whey concentrate demand from refrigerated sports beverage manufacturers.
Mexico
Border-state processors leverage milk protein concentrate for recombined dairy product economics serving domestic and export markets. Mexican federal food safety regulations align with USMCA trade facilitation protocols for dairy ingredient cross-border movement. Jalisco and Nuevo León dairy clusters are upgrading spray-drying capacity to capture powder form procurement from Central American formulators.
North America Dairy Protein Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient supply. The North America dairy protein market structures around integrated processors controlling both milk sourcing and fractionation capacity, alongside specialized ingredient formulators. Three archetypes dominate: herd-integrated fractionators, independent protein refiners, and flavor-protein formulation integrators. Competitive moves concentrate on multi-year supply agreement capture and medical-grade certification acquisition for long-term care channel access.
Among herd-integrated fractionators, Dairy Farmers of America, Inc. and Glanbia plc occupy positions exemplifying captive milk supply advantages, while Fonterra Co-operative Group Limited represents the cross-border trade flow archetype through its US distribution infrastructure. These three companies anchor the supply-side concentration visible in contract pricing dynamics.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Fonterra Co-operative Group Limited |
| Kerry Group PLC |
| Saputo Inc. |
| Arla Foods |
| Glanbia plc |
| Dairy Farmers of America, Inc. |
| Royal FrieslandCampina N.V. |
| Lactalis Group |
| Others |
Value Network & Pricing Analysis
California's Central Valley dairy processing cluster concentrates whey protein fractionation capacity among a handful of integrated processors, positioning these operators to capture margin pools from sports nutrition brands and clinical nutrition formulators downstream. This geographic concentration forces downstream buyers into multi-year supply agreements that lock in volume commitments ahead of price volatility in feed grain markets.
Pricing Analysis
FDA nutrition labeling modernization dictates the pricing tier structure across North American dairy protein procurement, separating medical-grade certified isolates from commodity whey concentrates. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by protein content band, with 90%+ isolates commanding substantial premiums over 34% concentrates. Price differentiation hinges on Health Canada novel food registration status for hydrolysate formats, which compresses margins for unregistered cross-border shipments. Cost compression in commodity whey concentrates is intensifying because Idaho and California processors are standardizing output through inline spectroscopic monitoring that reduces batch variability. Mass-market nutrition bar manufacturers exhibit the highest price sensitivity, while long-term care operators under group purchasing organization contracts prioritize medical-grade certification over per-kilogram cost.
Supply Chain Analysis
USMCA rules of origin and sanitary protocols function as de facto export-control mechanisms limiting unfettered cross-border dairy protein flows between the United States, Canada, and Mexico. Supply concentrates geographically in California, Idaho, and Wisconsin for whey fractionation, with Quebec and Ontario emerging as secondary nodes through new capacity investments. Raw material dependencies center on corn and soybean meal for dairy herd nutrition, membrane filtration equipment for fractionation, and natural gas for spray-drying operations. Single-region concentration risk creates vulnerability to California drought conditions and feed cost volatility that propagates through processor margins. Distribution runs through integrated processor direct sales for large contract manufacturers, supplemented by ingredient distributors serving mid-size formulators lacking captive supply relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fractionation engineering expertise in membrane separation and chromatographic purification has become the binding constraint on capacity expansion timelines, creating acute scarcity premiums for talent and equipment. This capability gap shapes competitive outcomes more than capital availability or raw milk access.
For Market Incumbents: Insulate margin pools by securing captive whey supply through backward integration into dairy herd operations or long-term milk procurement contracts with California and Idaho producers. Invest in medical-grade certification capabilities to capture group purchasing organization consolidation in Midwest long-term care channels, displacing distributors lacking formulary placement expertise. Prioritize inline process control systems that guarantee tighter protein content bands and command ingredient premiums from sports nutrition brands facing FDA relaunch deadlines. For New Entrants and Emerging Players: Build out precision fermentation capabilities for whey-identical proteins to decouple supply from herd size constraints and bypass geographic concentration risk in California and Idaho. Target direct-to-practitioner distribution channels for hydrolysate-based gut-health protocols, where functional medicine clinicians operate outside conventional retail and GPO purchasing structures. Establish co-manufacturing partnerships with Quebec liquid whey processors to serve refrigerated sports beverage proliferation without competing for Idaho and California powder capacity. For Investors and Strategic Acquirers: Capital is best deployed toward herd-integrated fractionators with existing FDA medical-grade certification and established group purchasing organization relationships in long-term care. Over a multi-year horizon, processors controlling both milk sourcing and fractionation capacity will outcompete independent refiners exposed to feed cost volatility and single-source dependency. The signal to watch is venture funding velocity into precision fermentation startups, which would indicate timeline compression for supply decoupling from traditional dairy infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Medical-Grade Certification Investment | FDA and Health Canada registrations unlock group purchasing organization contracts in Midwest long-term care systems. |
| Inline Spectroscopic Monitoring Deployment | Idaho and California processors reduce standardization cycles from hours to minutes, tightening contract specifications. |
| Precision Fermentation Capacity Buildout | Microbial biomass production decouples whey supply from California herd size and drought exposure constraints. |
| Direct-to-Practitioner Channel Development | Functional medicine clinicians in Colorado and Utah represent white-space distribution outside retail and GPO control. |
| Quebec Liquid Whey Processing Expansion | Montreal-area processors capture refrigerated sports beverage demand without competing for Idaho powder capacity. |
Research Methodology
A standing panel of dairy protein fractionation engineers, sports nutrition brand formulators, long-term care procurement directors, and FDA regulatory affairs specialists provided ongoing calibration across primary data collection. This practitioner input was cross-referenced with secondary validation from USDA dairy production statistics, FDA GRAS determination filings, Health Canada novel food registration databases, and USMCA trade flow records. Bottom-up capacity modeling of California, Idaho, and Wisconsin processing facilities was triangulated against top-down demand estimates from sports nutrition and clinical nutrition channel audits.
Scenario-bracketing anchored the analytical framework, with projections tested against alternative feed cost trajectories and precision fermentation adoption curves across the modeling period. Segmentation dimensions included protein fraction type, form factor, application channel, and customer procurement maturity. CAGRs were derived from installed capacity utilization trends and validated against historical price elasticity patterns in whey isolate procurement. Industry-specific forecast inputs incorporated FSMA preventive control compliance cost trajectories and group purchasing organization contract renewal cycles.
Practitioners should monitor feed grain price volatility, Health Canada hydrolysate registration timelines, and venture funding flows into precision fermentation for early signals of forecast deviation. Material shifts in California water allocation policy or FDA enforcement priorities for nutrition labeling would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Maracuja Oil Market
Ingredients
Asia-Pacific Lipids Market
Ingredients
Potato Protein Market
Ingredients
Cocoa Beans Market
Ingredients
Agarwood Oil Market
Ingredients
Rapid-Set Gelatin Market
Ingredients
Halal and Kosher Empty Capsules Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Dried Beet Pulp Market
Ingredients
Bovine Gelatin Market
Ingredients
Fresh Yeast Market
Ingredients
Oak Chips White Extract Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Chlorella Ingredients Market
Ingredients
Egg Phosphatidylcholine Market