
 Compressed Yeast Market | 2026-2036
Compressed Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Compressed Yeast Market Analytics
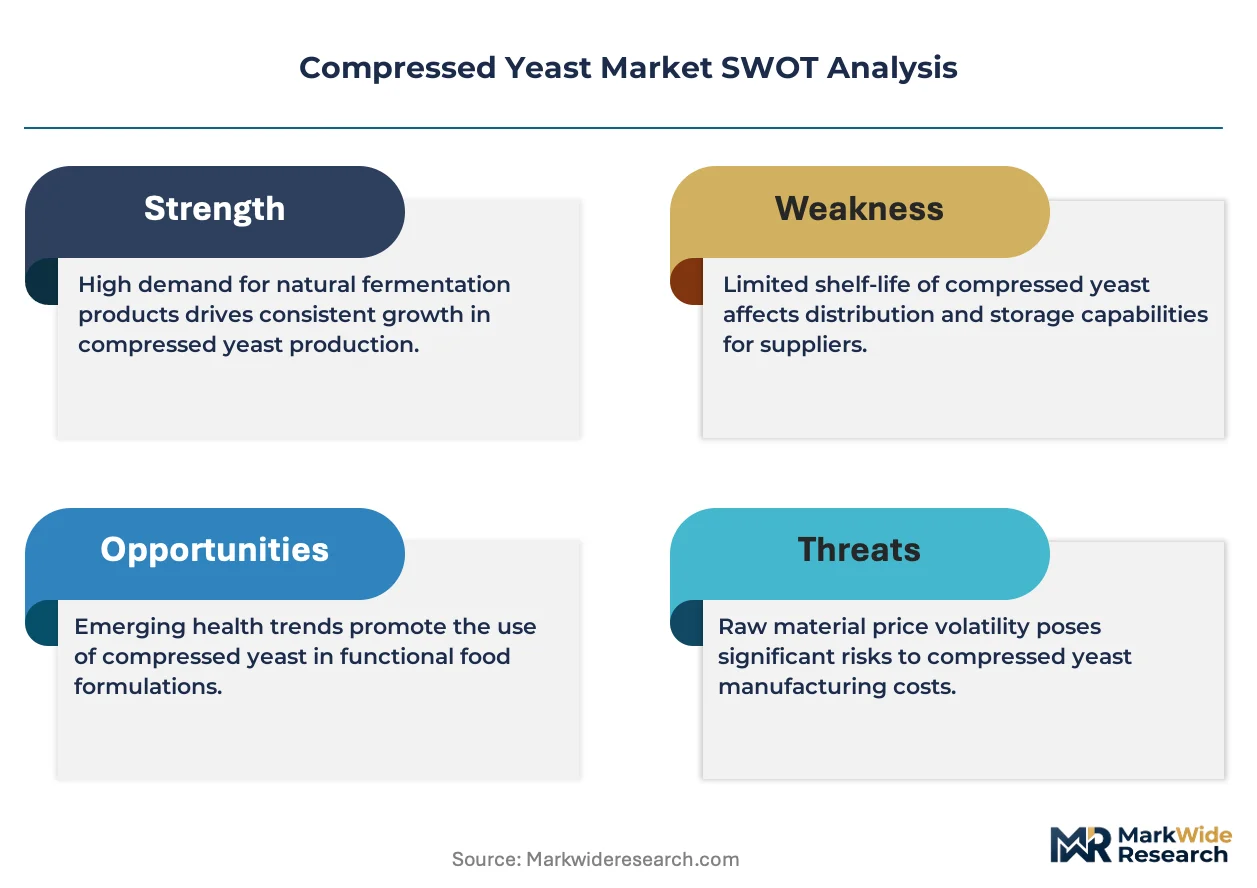
ISO 22000 certification is bifurcating the competitive landscape between multinational suppliers and regional packagers. Lesaffre Group leverages vertical integration from strain development to distribution, sustaining quality consistency across European and Asian operations. Angel Yeast Co., Ltd. anchors its position through geographic dominance in China's fermentation corridor, while Lallemand Inc. differentiates via specialized cold-chain logistics for fresh yeast delivery.
Compressed yeast denotes living Saccharomyces cerevisiae cells preserved in moist cake or crumbled form with approximately 70% water content, requiring refrigerated storage at 0-4°C to maintain viability for leavening and fermentation processes. Industrial bakeries favor instant yeast for operational efficiency and extended ambient stability, while craft breweries drive fastest growth in liquid yeast segments for strain-specific flavor profiling. Fresh yeast retains margin concentration in European artisan channels where traditional proofing methods persist.
FDA food safety standards, EU REACH chemical compliance, and China's GB national food safety standards collectively govern strain approval, labeling, and cold-chain integrity across major supply corridors. Regulatory divergence between FDA's GRAS self-affirmation and EFSA's centralized novel food assessments creates compliance complexity for cross-border suppliers. Stakeholders must monitor evolving carbon-accounting rules for refrigerated transport and strain-genome disclosure requirements that could reshape sourcing strategies and regional manufacturing footprints.
Market Dynamics
EU F-Gas Regulation compliance costs and cold-chain energy intensity are bifurcating supplier economics, favoring integrated strain developers with captive refrigeration networks over regional packagers dependent on third-party logistics.
Growth Catalysts
- Artisan bakery revival:Traditional proofing methods in Germany and France sustain fresh yeast demand despite industrial automation trends elsewhere.
- REACH chemical compliance:Harmonized processing aid standards across EU member states reduce cross-border friction for strain-derived fermentation inputs.
- Craft brewing expansion:Liquid yeast adoption for strain-specific flavor profiling accelerates in North American microbrewery channels.
Market Restraints
- Refrigerated transport energy costs:Diesel-price volatility and carbon-accounting rules compress margins for ambient-stable instant yeast competitors.
- Strain concentration risk:Three suppliers control over 80% of commercial Saccharomyces cerevisiae genetic IP, creating licensing bottlenecks.
- FDA-EFSA regulatory divergence:GRAS self-affirmation versus centralized novel food assessments delay cross-border product registrations by 18-24 months.
Strategic Opportunities
- China's GB standards alignment:National food safety standard revisions create first-mover advantage for cold-chain certified foreign suppliers.
- Plant-based fermentation:Precision-fermentation platforms converge with traditional yeast propagation for alternative protein applications.
- Direct-to-bakery distribution:Bypassing wholesale intermediaries via subscription fresh-yeast delivery locks in artisan customer loyalty.
Industry Challenges
- ISO 22000 certification timelines:12-18 month audit cycles strain mid-tier packagers seeking multinational supply contracts.
- Strain-genome disclosure requirements:Emerging transparency mandates force IP renegotiations with research institutions holding original isolation rights.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressed Yeast Market |
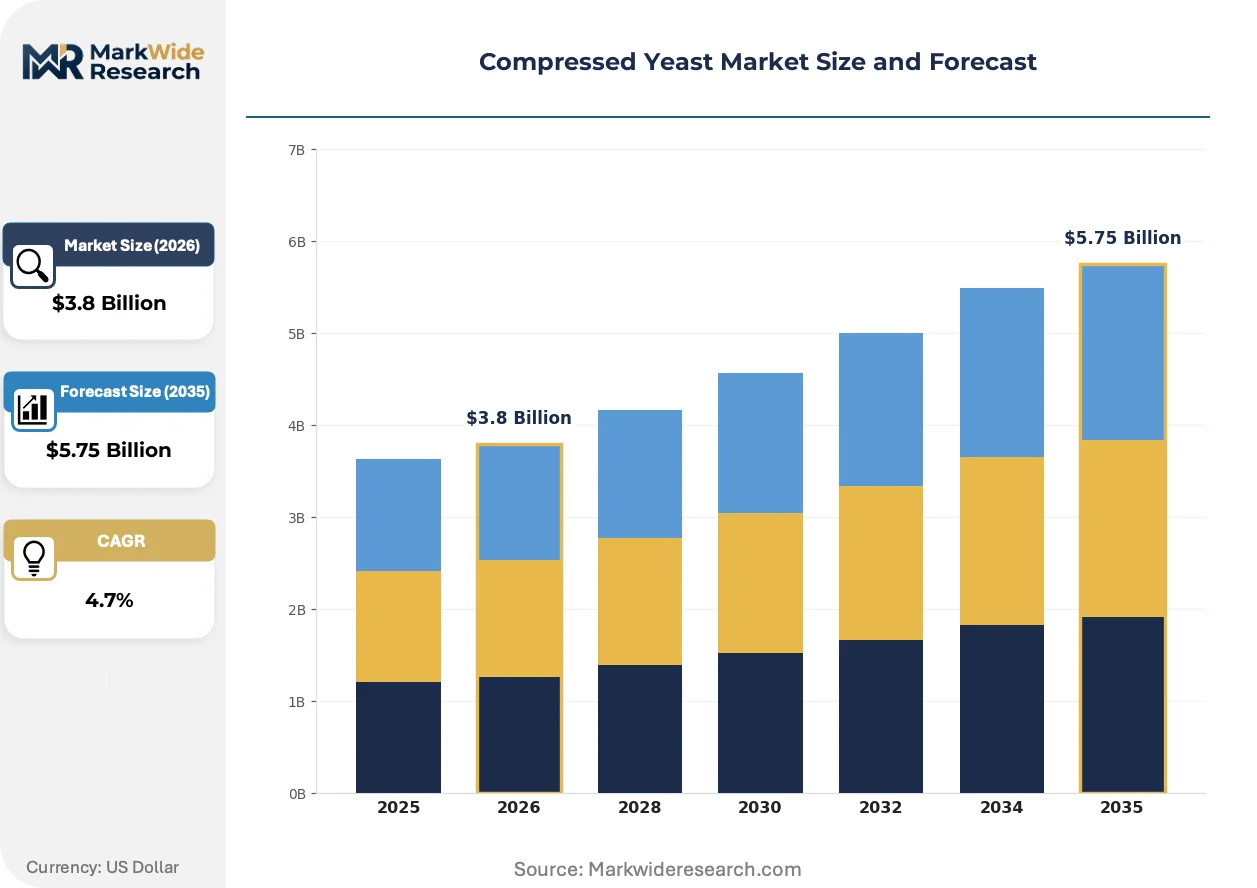
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Dry Yeast, Instant Yeast, Fresh Yeast, Liquid Yeast Application: Baking, Brewing, Fermentation, Biofuel Production End User: Bakeries, Breweries, Food Manufacturers, Household Packaging Type: Bulk Packaging, Sachets, Canisters, Pouches |
| Companies Covered | Lesaffre Group, AB Mauri, Angel Yeast Co., Ltd., Lallemand Inc., Chr. Hansen Holding A/S, Pakmaya, Oriental Yeast Co., Ltd., Associated British Foods plc, Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressed Yeast Market Evolving Landscape
Active dry yeast formulations with ambient stability exceeding 24 months are compressing the addressable market for traditional compressed yeast in industrial baking applications.
Encapsulated live yeast technologies with modified atmosphere packaging is displacing conventional refrigerated cake yeast in Southeast Asian retail channels. Industrial bakeries in Thailand and Vietnam adopt these formats to circumvent cold-chain infrastructure gaps. The displacement accelerates margin compression for fresh yeast specialists lacking R&D capacity in moisture-barrier engineering.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants force cold-chain operators to retrofit transport fleets with CO2 or ammonia systems by 2030. Yeast suppliers dependent on third-party logistics face 15-25% distribution cost escalation during the transition window. German and Dutch manufacturers with in-house refrigerated transport capabilities capture volume from logistics-dependent competitors.
Bakery procurement departments now specify strain-provenance documentation and carbon-intensity certifications in supplier scorecards. French and Italian artisan cooperatives prioritize local strain collections with geographic indication status over commodity yeast. This behavioral pivot fragments procurement volumes and rewards regional micro-propagators with heritage strain libraries.
Compressed Yeast Market Segmentation
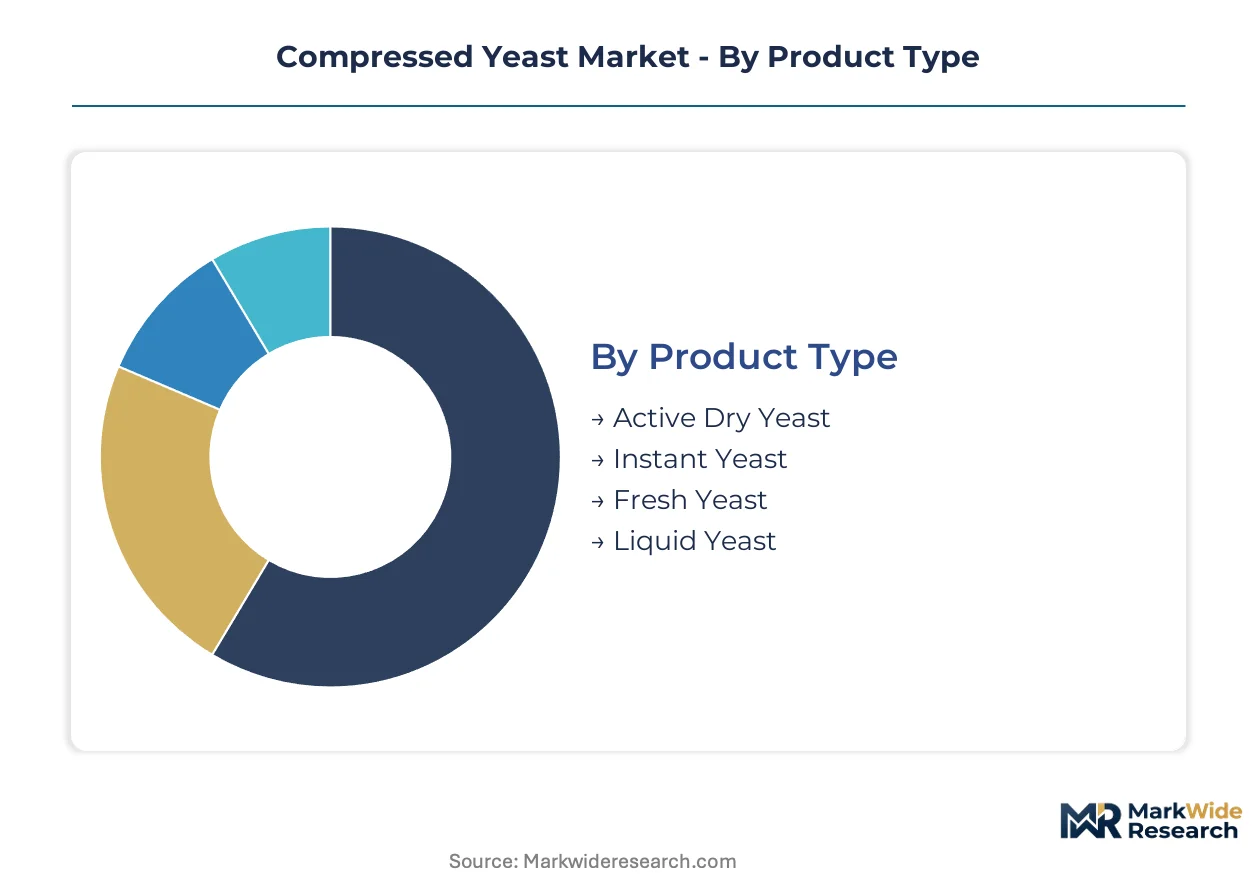
Segmentation in compressed yeast reveals divergent supply chain architectures across product formats. Refrigeration requirements, shelf stability, and end-use technical specifications create distinct competitive arenas with incompatible manufacturing assets.
Product Type:
Domestic production dominates fresh and liquid yeast due to cold-chain constraints, while active dry and instant formats sustain robust export economics from Germany, China, and the United States.
- Active Dry Yeast:Dehydrated Saccharomyces cerevisiae with moisture content below 8%, enabling ambient storage exceeding 24 months. Industrial bakeries in Thailand and Vietnam prioritize this format to circumvent cold-chain infrastructure gaps, compressing margins for fresh yeast specialists lacking moisture-barrier R&D capacity.
- Instant Yeast:Finely milled dried yeast with ascorbic acid additives for rapid rehydration. German and French industrial bakeries favor this format for operational efficiency and extended ambient stability, though artisan channels in these same markets sustain traditional fresh yeast demand.
- Fresh Yeast:Living cells in moist cake form at approximately 70% water content, requiring 0-4°C storage. European artisan cooperatives prioritize this format for traditional proofing methods.
- Liquid Yeast:Suspended cell cultures in propagation media for strain-specific applications. North American craft breweries drive adoption for flavor profiling precision.
Active dry yeast holds the largest share; momentum sits with liquid yeast as craft brewing expands.
Application:
Cost-tier stratification separates commodity-scale industrial users from premium-positioned artisan segments with divergent procurement specifications.
- Baking:Leavening agent for bread, pastry, and confectionery production across industrial and artisan scales. EU F-Gas Regulation compliance costs favor integrated strain developers with captive refrigeration networks over regional packagers dependent on third-party logistics.
- Brewing:Fermentation input for ethanol production and flavor compound generation. Craft brewery procurement departments now specify strain-provenance documentation and carbon-intensity certifications in supplier scorecards.
- Fermentation:Industrial-scale biomass propagation for food ingredients and processing aids. REACH chemical compliance harmonizes processing aid standards across EU member states.
- Biofuel Production:Cellulosic ethanol fermentation using specialized thermotolerant strains. Chinese GB standards alignment creates first-mover advantage for cold-chain certified foreign suppliers entering this application.
Baking commands volume leadership; biofuel production is climbing the fastest as energy transition policies mature.
End User:
Customer-type fragmentation splits procurement between specification-driven industrial buyers and relationship-dependent artisan accounts with incompatible service models.
- Bakeries:Primary consumption channel spanning industrial production facilities and artisan workshops. French and Italian artisan cooperatives prioritize local strain collections with geographic indication status over commodity yeast.
- Breweries:Fermentation process operators from multinational producers to microbrewery startups. Liquid yeast adoption for strain-specific flavor profiling accelerates in North American microbrewery channels.
- Food Manufacturers:Industrial processors of yeast extracts, autolysates, and flavor enhancers. ISO 22000 certification timelines strain mid-tier packagers seeking multinational supply contracts.
- Household:Retail consumers purchasing small-format baking inputs. Encapsulated live yeast technologies with modified atmosphere packaging displace conventional refrigerated cake yeast in Southeast Asian retail channels.
Bakeries represent the dominant demand pool; breweries are gaining share fastest through craft segment expansion.
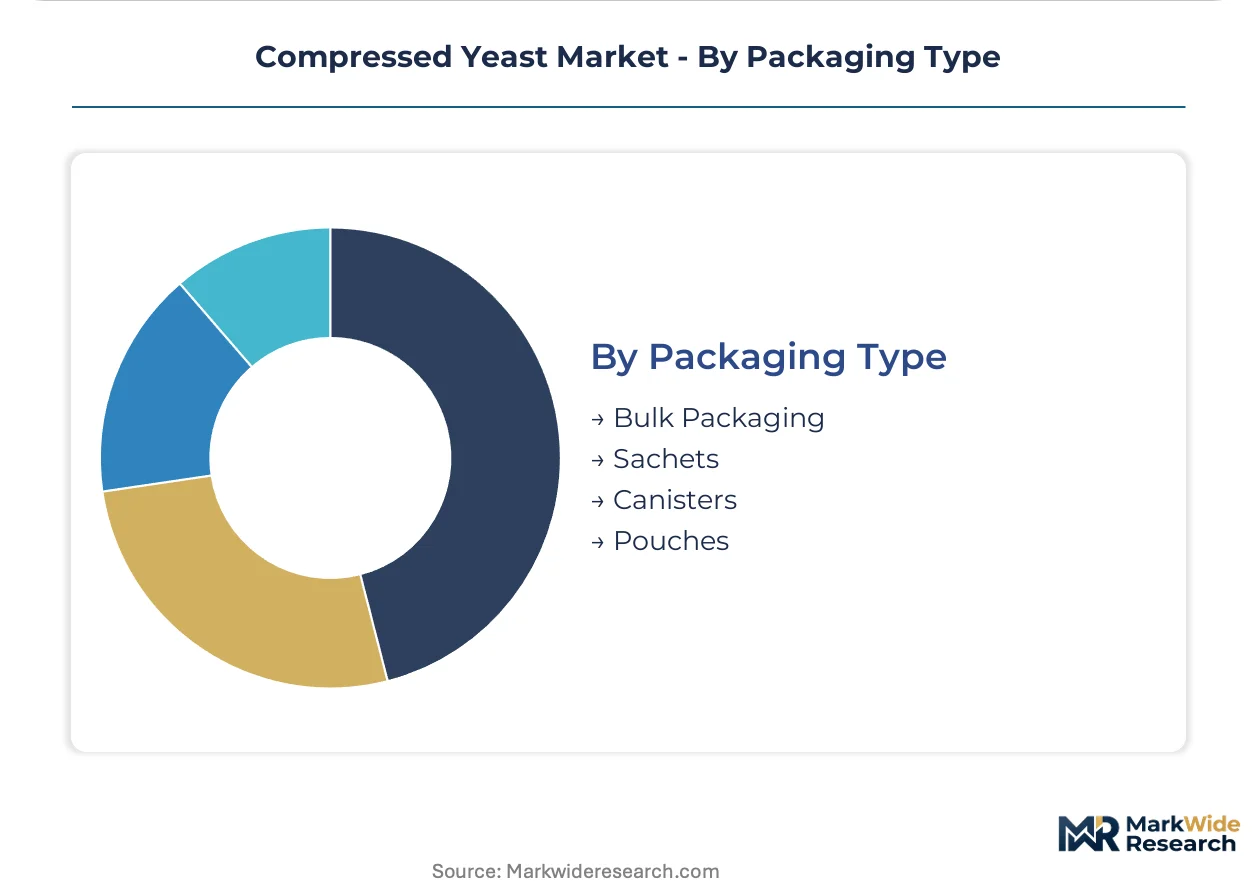
Packaging Type:
Volume-scale economics concentrate in bulk formats while margin capture shifts toward convenience-oriented retail configurations.
- Bulk Packaging:Industrial totes and drums for high-volume bakery and brewery procurement. Direct-to-bakery distribution models bypass wholesale intermediaries via subscription fresh-yeast delivery.
- Sachets:Single-use aluminum-laminate pouches for household and small commercial baking. German and Dutch manufacturers with in-house refrigerated transport capabilities capture volume from logistics-dependent competitors.
- Canisters:Reclosable rigid containers for active dry yeast retail distribution. Ambient stability requirements align with instant yeast formulations.
- Pouches:Flexible film packaging for emerging market retail penetration. Southeast Asian adoption circumvents cold-chain infrastructure gaps.
Bulk packaging leads absolute volume; sachets are expanding most quickly through retail channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phase-down schedules and China's GB standards revisions are redirecting manufacturing footprints toward integrated cold-chain corridors. National subsidy programs for biofuel fermentation capacity are accelerating strain-development investments across Germany, China, and the United States.
Germany
Artisan bakery cooperatives sustain fresh yeast demand through traditional proofing specifications. REACH chemical compliance harmonizes processing aid standards across federal states. The Baden-Württemberg fermentation cluster anchors Lesaffre Group's European strain development and captive refrigerated distribution network.
China
GB national food safety standard revisions create first-mover entry windows for cold-chain certified foreign suppliers. MIIT dual carbon goals pressure diesel-dependent refrigerated transport operators toward fleet electrification. The Yangtze River Delta fermentation corridor concentrates Angel Yeast Co., Ltd. production capacity and instant yeast export volume.
United States
Craft brewery procurement departments specify strain-provenance documentation and carbon-intensity certifications. FDA GRAS self-affirmation procedures accelerate novel strain approvals relative to EFSA centralized assessments. The Pacific Northwest brewing cluster drives liquid yeast adoption for strain-specific flavor profiling.
France
French artisan cooperatives prioritize local strain collections with geographic indication status over commodity yeast inputs. EFSA novel food assessment timelines delay cross-border registrations from GRAS-affirmed US suppliers. The Grand Est region sustains heritage propagation facilities supplying traditional baguerie channels.
Thailand
Industrial bakeries adopt encapsulated live yeast with modified atmosphere packaging to circumvent cold-chain infrastructure gaps. National energy efficiency mandates for commercial refrigeration compress operating margins for fresh yeast specialists. Bangkok metropolitan distribution networks concentrate Southeast Asian retail channel penetration.
Compressed Yeast Market Competitive Landscape
Player mix skews toward vertically integrated strain developers with captive cold-chain assets over logistics-dependent regional packagers. Consolidation concentrates genetic IP licensing power among three suppliers controlling commercial Saccharomyces cerevisiae repositories. Strategic archetypes include heritage strain curators, precision-fermentation platforms, and ambient-stable formulation specialists. Dominant competitive moves encompass backward integration into strain libraries and geographic expansion through direct-to-bakery subscription models.
Within the integrated developer tier, Lesaffre Group and Angel Yeast Co., Ltd. exemplify divergent geographic anchoring strategies—European corridor dominance versus Chinese fermentation scale. Lallemand Inc. occupies a position bridging specialized cold-chain logistics capabilities with North American craft brewery penetration. These three entities represent the licensing bottleneck structure constraining mid-tier propagators seeking multinational supply contracts.
| Leading Market Players |
|---|
| Lesaffre Group |
| AB Mauri |
| Angel Yeast Co., Ltd. |
| Lallemand Inc. |
| Chr. Hansen Holding A/S |
| Pakmaya |
| Oriental Yeast Co., Ltd. |
| Associated British Foods plc |
| Koninklijke DSM N.V. |
| Others |
Value Network & Pricing Analysis
Seven-to-ten-day refrigerated lead times from strain propagation to bakery delivery concentrate pricing power among integrated manufacturers with captive cold-chain networks, while third-party logistics-dependent packagers absorb diesel-price volatility and carbon-accounting compliance costs that compress their margin position against ambient-stable instant yeast competitors.
Pricing Analysis
Certification level creates the primary spread between ISO 22000-accredited multinational suppliers and uncertified regional packagers. Three-tier pricing structure across premium certified, standard commercial, and economy bulk tiers dominates contract negotiations. Pricing pressure stems from EU F-Gas Regulation retrofit costs for refrigerated transport fleets. Artisan cooperatives exhibit lowest price sensitivity due to strain-provenance specifications, while industrial bakeries drive aggressive volume-based negotiations.
Supply Chain Analysis
Inventory turnover of 3-5 days for fresh yeast formats anchors supply chain design around proximity to consumption clusters. Production gravity centers on Germany, China, and the United States as strain development and propagation hubs. Raw material dependencies include molasses feedstock, nitrogen sources, and specialized refrigerants for cold-chain integrity. Single-source vulnerability concentrates in three suppliers controlling commercial Saccharomyces cerevisiae genetic IP. Distribution runs through direct-to-bakery subscription models and wholesale intermediaries serving retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across artisan proofing specifications and industrial efficiency requirements creates white-space opportunities for specialized strain curators and precision-fermentation platforms that escape commodity pricing pressure.
For Market Incumbents: Fortify cold-chain captive networks through fleet electrification aligned with China's MIIT dual carbon goals and EU F-Gas phase-down schedules. Deepen backward integration into heritage strain libraries to defend against geographic indication prioritization by French and Italian artisan cooperatives. Lock in multinational supply contracts through accelerated ISO 22000 certification timelines. For New Entrants and Emerging Players: Differentiate on strain-provenance documentation and carbon-intensity certification to penetrate North American craft brewery procurement scorecards. Target Southeast Asian retail channels with encapsulated live yeast formats that circumvent cold-chain infrastructure gaps. Deploy direct-to-bakery subscription models to bypass wholesale intermediaries and capture artisan loyalty. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because genetic IP licensing bottlenecks and cold-chain capital requirements favor scaled integrated developers over fragmented regional packagers. Acquisition candidates include heritage strain micro-propagators with geographic indication status and precision-fermentation platforms converging with traditional yeast propagation. Watch for carbon-accounting rule finalization as the inflection signal for refrigerated transport cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Libraries | Captures genetic IP licensing revenue from mid-tier propagators seeking multinational contracts. |
| Cold-Chain Fleet Electrification | Aligns with EU F-Gas Regulation phase-down and China's MIIT dual carbon mandates. |
| Direct-to-Bakery Subscription Launch | Locks in artisan customer loyalty bypassing wholesale intermediaries in European markets. |
| Precision-Fermentation Platform Development | Converges traditional propagation with alternative protein applications for plant-based fermentation. |
| Heritage Strain Geographic Indication Certification | Captures premium positioning from French and Italian artisan cooperative procurement priorities. |
Research Methodology
The analysis maps fresh yeast, instant yeast, active dry yeast, and liquid yeast propagation formats, each validated through fermentation process engineers, bakery procurement directors, cold-chain logistics operators, and regulatory compliance officers, combined with customs trade data, EU F-Gas Regulation filings, FDA GRAS affirmation records, and China GB standards documentation, employing bottom-up strain production estimates triangulated against top-down end-use consumption models.
Consistency checks against refrigerated transport cost indices and biofuel fermentation capacity announcements validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product format, application end-use, customer type, and packaging configuration, with CAGRs derived from strain propagation capacity expansion schedules and craft brewery penetration curves anchored in procurement specification trends.
Material uncertainties — regulatory divergence between FDA GRAS and EFSA novel food assessment timelines, diesel-price volatility impacts on refrigerated transport economics, and strain-genome disclosure mandate finalization — sit outside the modeled envelope. Forecasts reflect assumptions regarding cold-chain infrastructure development rates and artisan channel stability. Revision becomes warranted when carbon-accounting rule enforcement crosses thresholds that restructure third-party logistics cost competitiveness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Agar Market
Ingredients
Arrowroot Starch Market
Ingredients
North America Phytosterols Market
Ingredients
Europe Malt Ingredient Market
Ingredients
Pet Food Ingredients Market
Ingredients
Interesterified CBE Market
Ingredients
Starch Market
Ingredients
Sweet Almond Oil Market
Ingredients
Soy Derivatives Market
Ingredients
Middle East and Africa Dairy Ingredients Market
Ingredients
Tuna and Algae Omega-3 Ingredient Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
North America Potato Starch Market
Ingredients
Beverage Ingredients Market
Ingredients
Coconut Flour Market
Ingredients
Global Pulse Flours Market