
 North America Gluten Free Flour Market | 2026-2036
North America Gluten Free Flour Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gluten Free Flour Market Analysis
Canadian oat and pulse milling capacity is rebalancing toward certified gluten-free processing lines to serve North American bakery and food manufacturing demand. Bob's Red Mill Natural Foods leverages its dedicated gluten-free facility in Milwaukie, Oregon to sustain brand trust among celiac and wheat-sensitive households. Ardent Mills competes through its extensive North American grain elevator network, while King Arthur Baking Company differentiates via premium-positioned, test-kitchen-validated gluten-free flour blends for home bakers.
Gluten free flour denotes milled products processed and tested to contain fewer than twenty parts per million of gluten protein, typically manufactured through dedicated equipment or facility protocols using rice, almond, coconut, or chickpea base materials. The product serves commercial bakeries, food manufacturers, restaurants, and households requiring safe alternatives for celiac disease management, wheat allergy avoidance, or discretionary grain-free diets. Rice flour anchors volume across food manufacturing applications due to its neutral flavor profile and functional similarity to wheat in extruded and baked goods. Almond flour commands premium positioning in specialty retail channels and paleo-aligned household segments. Distribution through online retail and supermarkets is expanding fastest as e-commerce penetration and shelf-space allocation for free-from categories deepen across the United States and Canada.
The FDA enforces the Gluten-Free Food Labeling Final Rule, which mandates that products bearing the gluten-free claim must contain less than twenty parts per million of gluten and prohibits the use of wheat, rye, barley, or crossbred hybrids unless processed to remove gluten protein. Health Canada maintains parallel standards through its gluten-free labeling regulations under the Food and Drug Regulations, while the USDA oversees organic-certified gluten-free flour production through its National Organic Program. Stakeholders must monitor evolving allergen threshold science, potential harmonization pressures between FDA and Health Canada testing methodologies, and the commercial implications of front-of-pack labeling initiatives that could reshape consumer purchase criteria across North American retail environments.
Market Dynamics
The FDA's Gluten-Free Food Labeling Final Rule is compressing competitive timelines across North America by mandating sub-20 ppm thresholds and dedicated facility protocols, forcing milling operations to choose between capital-intensive segregation or market exit.
Growth Catalysts
- Celiac Disease Diagnosis Rates:Rising clinical screening in the United States is expanding the addressable patient population requiring certified gluten-free ingredients for strict dietary management.
- Clean Label Migration:Mainstream bakeries are reformulating product lines to capture wheat-sensitive households seeking transparent ingredient sourcing without allergen risk.
- Pulse Flour Innovation:Canadian chickpea and lentil milling infrastructure is pivoting toward gluten-free certification to supply protein-enhanced alternatives for commercial food manufacturing.
Market Restraints
- Input Cost Volatility:Almond flour pricing fluctuates with California drought cycles and water allocation disputes, compressing margins for premium-positioned brands.
- Supply Concentration Risk:United States rice milling clusters in Arkansas and California create geographic vulnerability to climate-driven harvest variability.
- Technical Limitation:Rice flour lacks the elastic protein network of wheat, requiring expensive hydrocolloid additives to achieve comparable baking performance in artisan applications.
Strategic Opportunities
- Mexican Market Underpenetration:Celiac awareness and certified gluten-free retail distribution remain nascent, creating first-mover positioning for compliant importers and local millers.
- Foodservice Channel Expansion:Quick-service restaurant chains are adding gluten-free menu items, generating bulk ingredient demand from centralized commissary kitchens.
- Organic Certification Convergence:The USDA National Organic Program creates dual-certification premiums for producers meeting both gluten-free and organic standards simultaneously.
Industry Challenges
- Certification Timeline Compression:Third-party gluten-free audits and laboratory testing protocols extend new product launch cycles by 4-6 months, delaying revenue recognition.
- Cross-Contamination Control:Shared transportation and storage infrastructure requires expensive segregation investments that smaller regional mills struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gluten Free Flour Market |
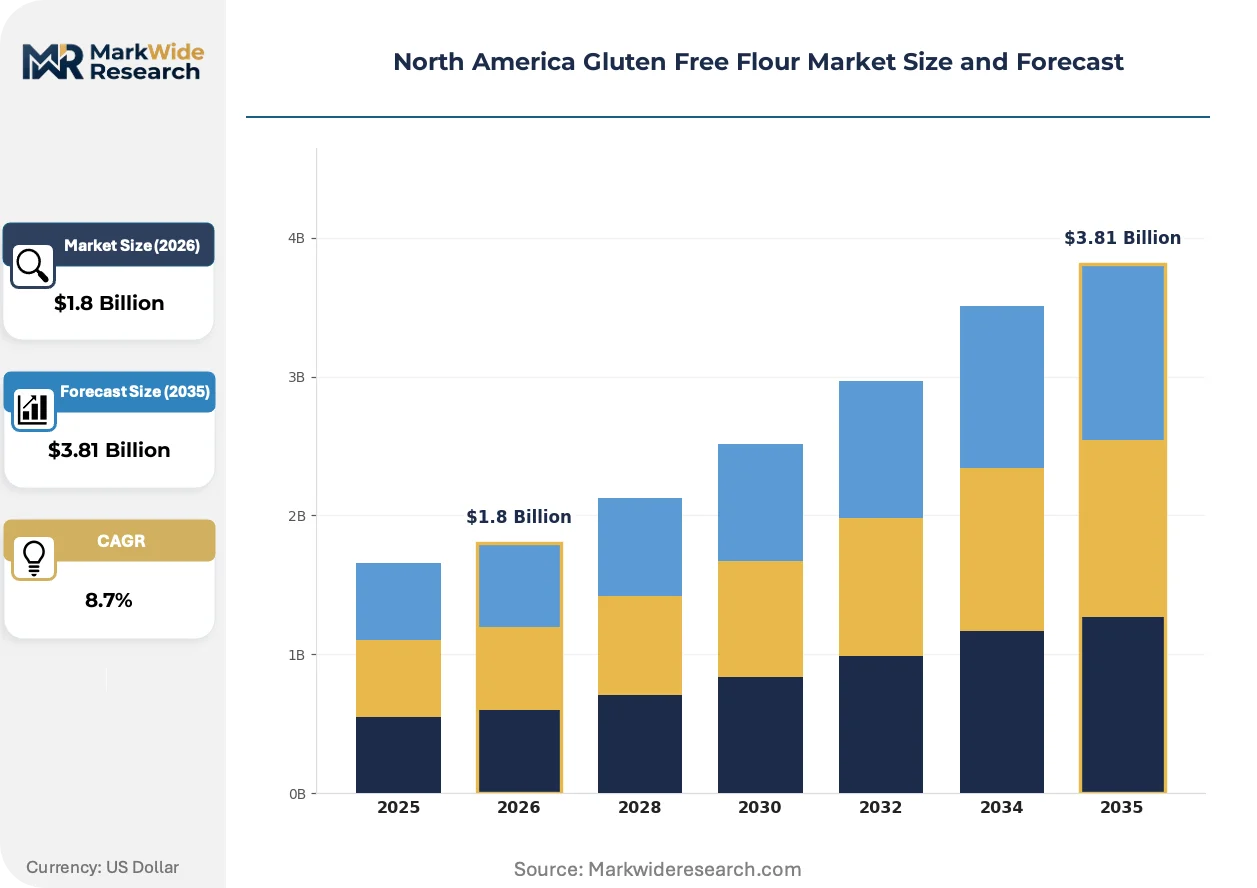
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rice Flour, Almond Flour, Coconut Flour, Chickpea Flour End User: Households, Restaurants, Bakeries, Food Manufacturers Packaging Type: Bags, Boxes, Tubs, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Bob's Red Mill Natural Foods, Inc., Ardent Mills, General Mills, Inc., Enjoy Life Foods LLC, The Scoular Company, Archer Daniels Midland Company, King Arthur Baking Company, Inc., AGRANA Beteiligungs-AG, Associated British Foods Plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gluten Free Flour Market Emerging Trajectories
Processing technology and regulatory enforcement are reshaping how gluten-free flour moves from grain elevator to finished goods, with implications for capital allocation and competitive positioning across the value chain.
Optical sorting and DNA-based contamination detection is electrifying quality assurance protocols in dedicated gluten-free facilities. Large-scale millers are deploying these systems to eliminate manual inspection bottlenecks and reduce batch rejection rates. The technology is compressing the cost gap between certified and conventional flour production, enabling volume expansion into mid-tier retail channels previously served by commodity alternatives.
Health Canada's parallel gluten-free labeling regulations under the Food and Drug Regulations are tightening enforcement symmetry with FDA standards. This regulatory convergence is eliminating dual-compliance burdens for cross-border suppliers while raising barriers for non-compliant importers. Canadian bakery and food manufacturing segments are responding by consolidating procurement around certified North American suppliers rather than lower-cost offshore alternatives.
Direct-to-consumer subscription models are fragmenting traditional grocery channel dominance for specialty flour blends. Home bakers in United States metropolitan markets are bypassing supermarket shelves to access freshly milled, small-batch products with transparent sourcing documentation. This channel rotation is most visible in Pacific Coast and Northeast urban corridors where e-commerce penetration and dietary consciousness concentrate demand.
North America Gluten Free Flour Market Segmentation
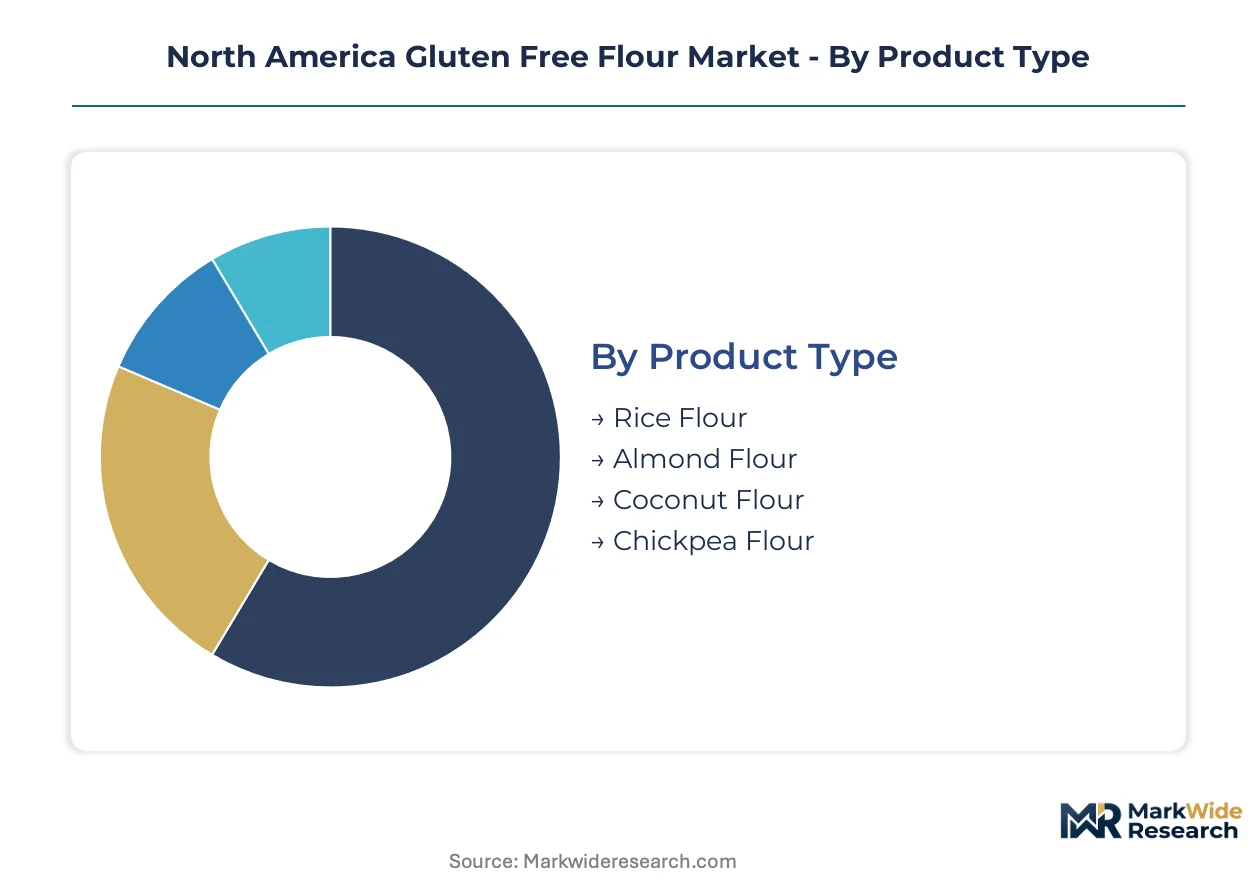
Gluten-free flour segmentation in North America reflects divergent functional requirements across industrial food manufacturing and precision home baking. Product formulation choices directly determine applicable end-use channels, packaging economics, and distribution infrastructure investments.
Product Type:
Technical specifications around protein content, starch gelatinization temperature, and water absorption capacity differentiate milling outputs for distinct application requirements.
- Rice Flour:Milled from white or brown rice with neutral flavor and fine particle size distribution. Arkansas and California milling clusters supply bulk quantities to extruded snack and commercial bakery operations across the United States seeking wheat-like texture without allergen risk.
- Almond Flour:Ground blanched almonds yield high-fat, low-carbohydrate flour with distinctive moisture retention properties. Premium positioning in paleo-aligned household segments and California drought-driven supply volatility constrain volume expansion despite strong price realization.
- Coconut Flour:Defatted coconut meat flour with exceptional fiber density and hygroscopic characteristics. Limited commercial adoption outside specialty health food channels due to pronounced flavor profile and formulation complexity.
- Chickpea Flour:Canadian prairie pulse milling infrastructure is expanding certified gluten-free capacity to serve protein-fortified pasta and alternative meat applications.
Rice flour leads on scale; chickpea flour leads on momentum.
End User:
Procurement sophistication and volume thresholds separate price-sensitive commodity buyers from specification-driven premium purchasers.
- Food Manufacturers:Industrial buyers operate under FDA-validated supplier qualification programs with mandatory lot testing and dedicated facility certification. Extruded cereal, frozen dough, and snack producers in the United States Midwest drive bulk rice flour consumption through long-term supply agreements.
- Bakeries:Artisan and commercial bakery operations require consistent hydration performance and clean label positioning to serve wheat-sensitive clientele. King Arthur Baking Company and regional co-manufacturers validate blends through test kitchen protocols before production scale-up.
- Households:Home bakers purchase smaller format retail packages with transparent sourcing documentation and recipe guidance.
- Restaurants:Foodservice operators source through broadline distributors with limited gluten-free SKU depth relative to retail channels.
Food manufacturers dominate volume throughput; bakeries command the steepest expansion trajectory.
Packaging Type:
Unit economics and contamination risk management shape format selection across channel and customer type.
- Bags:Multi-wall paper and plastic laminate bags dominate retail shelf presence with 1-5 pound capacities. Supermarket channel requirements for stackability and shelf life dating favor this format.
- Bulk Containers:Food manufacturers and large bakery commissaries procure via totes and silo deliveries to minimize per-unit handling costs.
- Boxes:Rigid packaging protects specialty blends during e-commerce fulfillment with premium unboxing experience.
- Tubs:Reclosable plastic containers target high-frequency home bakers with moisture protection and dispensing convenience.
Bulk containers dominate industrial procurement; bags retain retail channel leadership.
Distribution Channel:
Channel selection determines margin structure, brand control, and consumer education investment requirements.
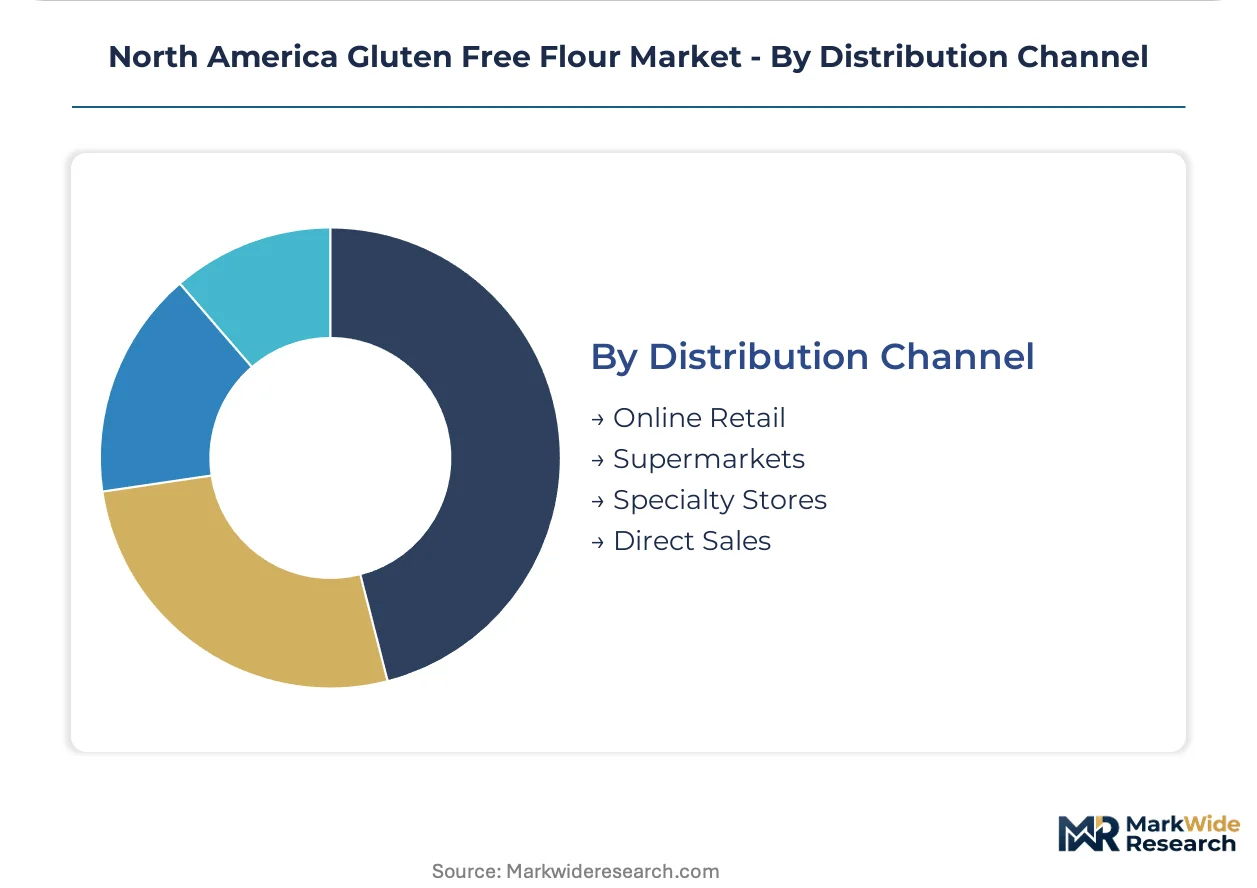
- Online Retail:Direct-to-consumer subscription models and marketplace platforms enable transparent sourcing documentation and fresh milling claims. Pacific Coast and Northeast metropolitan corridors show highest e-commerce penetration for specialty flour blends.
- Supermarkets:Conventional and natural grocery chains are expanding free-from shelf space allocation in response to household dietary diversification.
- Specialty Stores:Independent health food retailers and co-ops maintain curated gluten-free assortments with staff expertise for celiac shoppers.
- Direct Sales:Food manufacturers and large bakery accounts negotiate direct mill relationships to secure volume pricing and supply priority.
Supermarkets anchor volume; online retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as compliance cost differentials between FDA and Health Canada jurisdictions drive facility location decisions. Millers now optimize across sub-20 ppm certification standards while exploiting proximity to raw material clusters.
United States
Celiac diagnosis rates and free-from lifestyle adoption concentrate demand in coastal metropolitan corridors. FDA Gluten-Free Food Labeling Final Rule enforcement mandates sub-20 ppm thresholds and dedicated facility protocols. Arkansas and California rice milling clusters supply bulk extruded snack and commercial bakery operations.
Canada
Pulse flour innovation accelerates as prairie chickpea and lentil infrastructure pivots toward certified gluten-free capacity. Health Canada Food and Drug Regulations maintain parallel labeling standards with FDA, eliminating dual-compliance burdens. Saskatchewan and Manitoba milling operations serve North American protein-fortified pasta manufacturers.
Mexico
Celiac awareness and certified gluten-free retail distribution remain underdeveloped relative to US and Canadian markets. Mexican regulatory frameworks lack equivalent gluten-free labeling enforcement, creating import dependency for compliant ingredients. Mexico City Metro and Nuevo León industrial zones present first-mover positioning for certified importers.
North America Gluten Free Flour Market Vendor Landscape
United States producers anchor scale-driven supply; Canadian specialists hold pulse-flour differentiation. The vendor base stratifies across integrated grain conglomerates, dedicated gluten-free facility operators, and artisan-positioned blend formulators. Strategic archetypes include: legacy millers with elevator network leverage; certified-facility pure-plays competing on contamination control; and test-kitchen-validated brands targeting premium home bakers. Dominant competitive moves encompass capacity expansion into certified processing lines and backward integration into organic-certified raw material sourcing.
Within the dedicated-facility archetype, Bob's Red Mill Natural Foods occupies a position exemplifying brand trust cultivation through segregated Oregon production. Ardent Mills represents scale-driven supply chain leverage across North American grain elevator infrastructure. King Arthur Baking Company anchors the premium-tier vector through test-kitchen validation protocols for home baking applications.
| Leading Market Players |
|---|
| Bob's Red Mill Natural Foods, Inc. |
| Ardent Mills |
| General Mills, Inc. |
| Enjoy Life Foods LLC |
| The Scoular Company |
| Archer Daniels Midland Company |
| King Arthur Baking Company, Inc. |
| AGRANA Beteiligungs-AG |
| Associated British Foods Plc |
| Others |
Supply Flow & Price Mechanics
USDA organic certification gates qualified supply and premium-tier pricing access for gluten-free flour producers, with dual-certified facilities commanding substantial markups over conventional gluten-free alternatives. This environmental-sustainability mandate compresses available supplier pools while concentrating pricing power among compliant millers with captive organic grain sourcing.
Pricing Analysis
Distributor margin layers in North American gluten-free flour range from 15-25% for broadline foodservice distributors to 35-50% for specialty natural channel retailers. Three-tier pricing structure across certified-organic premium, dedicated-facility standard, and commodity-economy levels separates King Arthur Baking Company test-kitchen blends from mass-market rice flour alternatives. Pricing pressure stems from California almond crop volatility and water allocation disputes compressing margins for premium-positioned brands. Food manufacturers exhibit highest price sensitivity through long-term supply agreements, while direct-to-consumer subscription buyers show lowest sensitivity to per-unit premiums.
Supply Chain Analysis
Workforce availability in Arkansas rice milling corridors and Saskatchewan pulse processing zones constrains certified gluten-free capacity expansion despite equipment investments. Supply concentrates in United States rice milling clusters, Canadian prairie pulse infrastructure, and California almond processing facilities. Raw material dependencies include Arkansas long-grain rice, Saskatchewan chickpeas, and California almonds. Single-source vulnerability runs through California water-dependent nut crops. Distribution runs through bulk tote deliveries to food manufacturers, palletized shipments to bakery commissaries, and parcel fulfillment for direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America gluten-free flour market functions as a regulatory compounder, with FDA Gluten-Free Food Labeling Final Rule enforcement creating irreversible demand expansion for certified ingredients across bakery and food manufacturing segments.
For Market Incumbents: Deploy optical sorting and DNA-based contamination detection systems to eliminate manual inspection bottlenecks and defend against emerging pure-play certified-facility competitors. Consolidate procurement relationships with organic-certified grain elevators to secure captive raw material supply. Expand Milwaukie-style dedicated facility footprints into underpenetrated Mexican industrial zones before local millers achieve certification compliance. For New Entrants and Emerging Players: AI-powered supply chain traceability platforms offer technology-first wedge into food manufacturer supplier qualification programs demanding lot-level transparency. Target Mexico City Metro and Nuevo León industrial corridors where certified gluten-free ingredient supply remains import-dependent. Pursue direct sales relationships with quick-service restaurant commissaries seeking bulk gluten-free flour supply without incumbent distributor markups. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale certified-facility millers because FDA and Health Canada regulatory convergence eliminates dual-compliance burdens and raises barriers for offshore competitors. Five-to-ten year viability hinges on organic certification penetration rates and pulse-flour substitution momentum. Monitor Health Canada enforcement intensity as inflection indicator for cross-border supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Gluten-Free Facility Expansion | Arkansas and Saskatchewan milling investments capture FDA and Health Canada compliant supply. |
| Organic Certification Convergence | USDA National Organic Program dual-certification unlocks premium pricing in natural retail channels. |
| Pulse Flour Infrastructure Pivot | Canadian chickpea milling capacity serves protein-fortified pasta manufacturer demand growth. |
| Direct-to-Consumer Channel Development | Pacific Coast subscription models bypass supermarket shelf-space constraints for fresh-milled positioning. |
| Optical Sorting Technology Deployment | DNA-based contamination detection compresses cost gap between certified and conventional flour production. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with grain elevator operators, certified facility quality managers, bakery procurement directors, and food manufacturer R&D formulators with secondary validation. FDA Gluten-Free Food Labeling Final Rule documentation, Health Canada Food and Drug Regulations, USDA National Organic Program standards, and Arkansas and California agricultural statistics anchored supply-side modeling. Bottom-up facility capacity assessments and top-down consumption estimates triangulated market sizing.
Segment-weighting approaches distributed volume and value across rice flour, almond flour, coconut flour, and chickpea flour product types, with further disaggregation by food manufacturer, bakery, household, and restaurant end users. CAGRs derived from trend-line extrapolation of certified facility capacity additions, celiac diagnosis rate trajectories, and clean label reformulation momentum across the projection horizon. Forecast inputs incorporated California water allocation scenarios and Canadian prairie pulse crop yield variability.
The model holds under sustained FDA enforcement intensity and stable almond supply conditions; deviation in Health Canada regulatory harmonization timing or California drought severity would shift capacity expansion trajectories. Forecasts reflect documented assumptions regarding certification audit timeline compression and cross-contamination control technology adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cognitive Ingredients Market
Ingredients
North America and Europe Coconut Derivatives Market
Ingredients
Germany Protein Market
Ingredients
Polydextrose Ingredients Market
Ingredients
Carob Protein Market
Ingredients
Home Baking Ingredients Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Fats and Oils Market
Ingredients
Black Seed Oil Market
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
North America Lipid Market
Ingredients
United States Soy Protein Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
Chickpea Protein Ingredients Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
Fiber Rich Flours Market