
 South America Fermented Ingredients Market | 2026-2036
South America Fermented Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
South America Fermented Ingredients Market Analytics
Direct-to-brewery supply chains for liquid yeast cultures is fragmenting across Brazil and Argentina as craft beverage producers multiply. Novozymes A/S leverages its enzyme technology leadership to serve large-scale ethanol and food processors throughout the region. Kerry Group plc anchors its position through specialized cultures for dairy applications, while Chr. Hansen Holding A/S competes via deep strain libraries tailored to tropical fermentation conditions. Manuchar Brazil controls import logistics for specialty fermentation inputs that domestic producers cannot yet source locally.
Fermented ingredients comprise metabolically active or inactivated microbial biomass, organic acids, enzymes, and flavor compounds produced through controlled anaerobic or aerobic fermentation of carbohydrate substrates, typically operating at pH ranges between 4.0 and 6.5 and temperatures of 25°C to 45°C depending on strain requirements. These inputs serve primarily as bioprocessing catalysts, shelf-life extenders, flavor modulators, and nutritional enhancers across food, pharmaceutical, and cosmetic manufacturing. Yeast dominates volume flows due to Brazil's massive fuel ethanol sector, while enzymes capture premium pricing in dairy and bakery applications where protease and lipase specificity reduces processing costs. Lactic acid bacteria strains are gaining share in meat and dairy as clean-label preservation replaces chemical additives, though fermented grains remain nascent outside artisanal beverage channels.
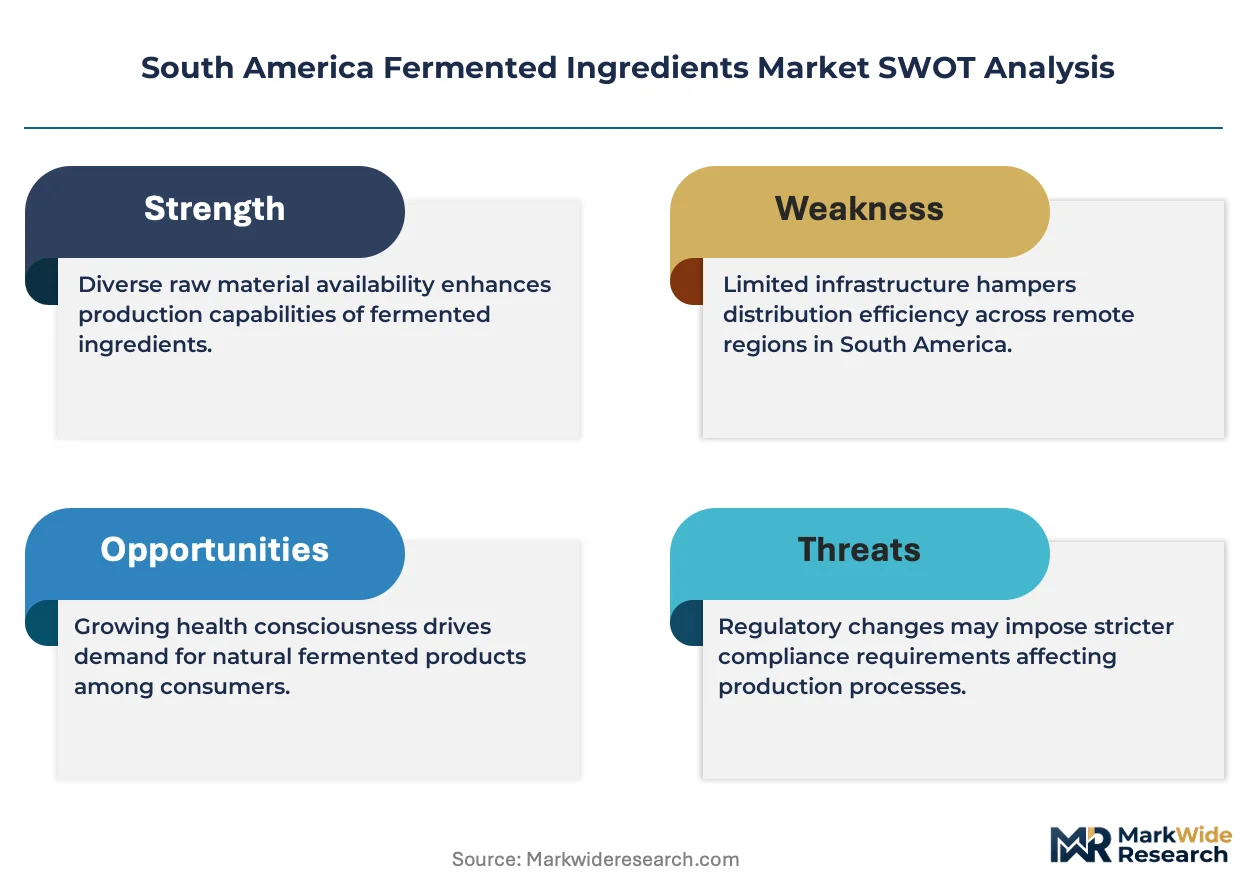
ANVISA governs food-grade microbial culture approvals and labeling standards in Brazil, while Argentina's national food code administered by the Ministry of Health sets parallel requirements for cross-border trade harmonization. Both frameworks are tightening identity preservation and allergen disclosure rules for fermentation-derived inputs, which elevates compliance costs for imported strains but creates openings for domestic culture banks. Stakeholders must track how Mercosur technical committees align microbiological specifications, as divergence between Brazilian and Argentine standards would fragment procurement strategies for pan-regional food manufacturers.
Market Dynamics
ANVISA's tightening identity preservation rules for fermentation-derived inputs are forcing manufacturers to rebuild their strain documentation and supply verification systems from the ground up. This regulatory pressure is compressing margins for imported cultures while creating protected space for domestic culture banks that can demonstrate full traceability.
Growth Catalysts
- Brazil's fuel ethanol sector:Massive yeast demand from biofuel processors anchors volume flows and funds continuous fermentation technology upgrades across the region.
- ANVISA's clean-label push:Evolving additive regulations are redirecting meat and dairy processors toward lactic acid bacteria strains as replacements for chemical preservatives.
- São Paulo's food processing corridor:Concentrated demand from industrial clusters creates efficient distribution economics for liquid culture suppliers.
Market Restraints
- Specialty strain import dependency:Domestic producers cannot yet source thermotolerant cultures locally, exposing buyers to currency volatility and extended lead times.
- Mercosur regulatory divergence risk:Misalignment between Brazilian and Argentine microbiological specifications would fragment procurement strategies for pan-regional manufacturers.
- High-purity enzyme cost structure:Pharmaceutical-grade protease and lipase inputs require capital-intensive downstream processing that limits supplier participation.
Strategic Opportunities
- Argentina's craft beverage expansion:Direct-to-brewery supply chains for liquid yeast cultures are fragmenting as microbreweries multiply outside Buenos Aires.
- Tropical strain adaptation:Deep libraries of heat-tolerant fermentation organisms address processing conditions that standard European cultures cannot survive.
- ANVISA's domestic culture bank incentives:Compliance cost elevation for imported strains creates openings for local biotechnology investments with full regulatory documentation.
Industry Challenges
- Strain characterization expertise shortage:Food manufacturers lack in-house microbiologists capable of validating culture performance under variable tropical conditions.
- Legacy equipment integration:Older dairy and meat processing plants require costly retrofitting to handle precision-controlled fermentation inputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Fermented Ingredients Market |
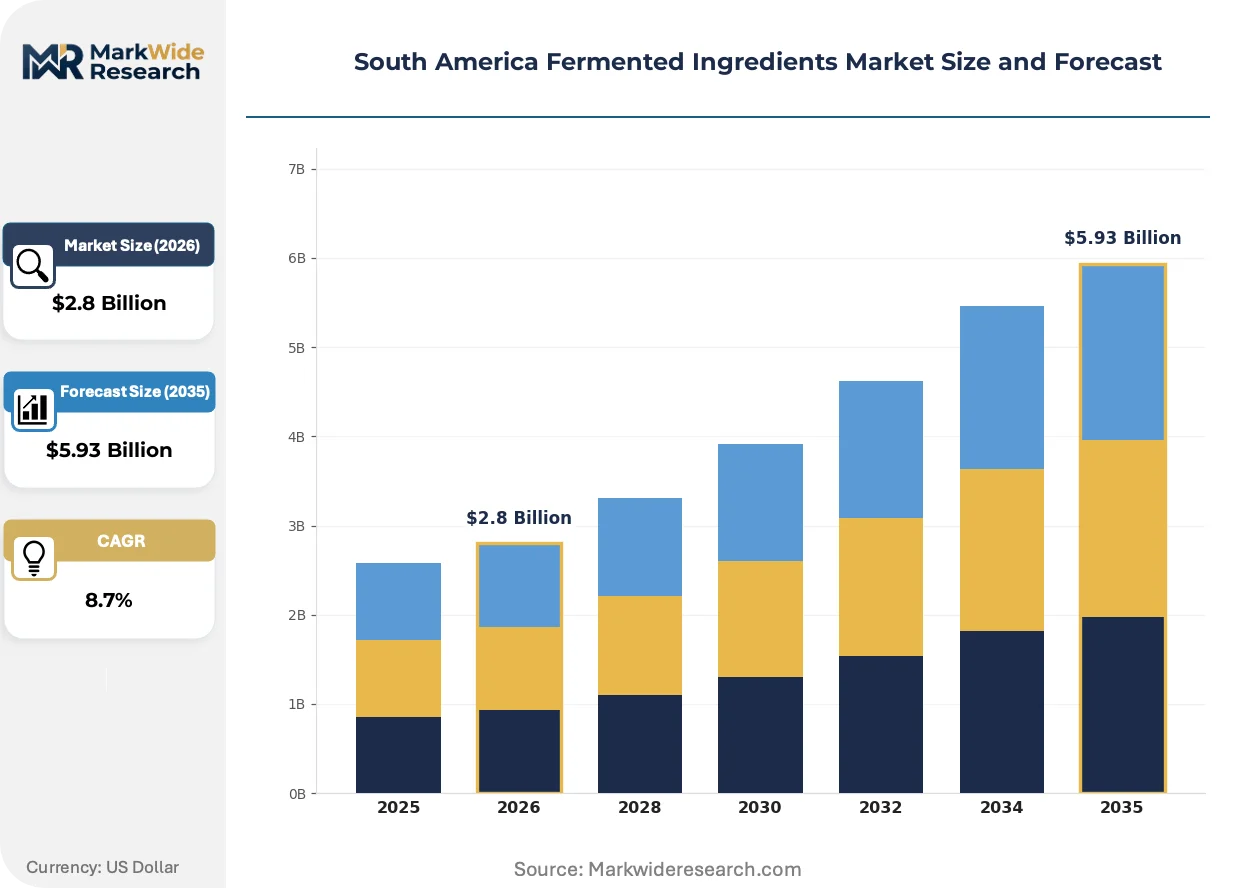
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast, Lactic Acid Bacteria, Enzymes, Fermented Grains Application: Beverages, Dairy Products, Bakery Products, Meat Products End User: Food & Beverage Industry, Pharmaceutical Industry, Cosmetic Industry, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Evonik Industries AG, Novozymes A/S, BASF SE, Kerry Group plc, Dohler Group SE, Chr. Hansen Holding A/S, Lonza Group, Archer Daniels Midland Company, Manuchar Brazil, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Fermented Ingredients Market Evolving Landscape
Continuous fermentation monitoring systems are collapsing the traditional batch-based quality control paradigm. Real-time metabolite sensing and automated pH adjustment are compressing production cycles while reducing contamination risk across dairy and ethanol applications.
Precision fermentation platforms using CRISPR-edited chassis organisms is collapsing the cost structure for high-value enzymes and flavor compounds. Large-scale Brazilian ethanol processors are adopting these systems to co-produce food-grade proteins alongside fuel output. The technology is collapsing the historical separation between commodity biofuel operations and specialty ingredient manufacturing.
ANVISA's 2023 guidance on allergen disclosure for fermentation-derived inputs is tightening labeling requirements for cross-border trade. Food manufacturers must now document residual protein content from culture media, elevating compliance costs for imported strains. Dairy processors in São Paulo state are responding by qualifying domestic culture suppliers with full substrate traceability.
Ingredient buyers are consolidating procurement relationships around suppliers offering integrated technical service support. Small and mid-sized meat processors in Brazil's interior are abandoning spot-market yeast purchases in favor of multi-year contracts bundling strain supply with on-site fermentation optimization. This pattern is most visible in Paraná state's expanding poultry processing belt, where technical service capabilities outweigh unit price in supplier selection.
South America Fermented Ingredients Market Segmentation
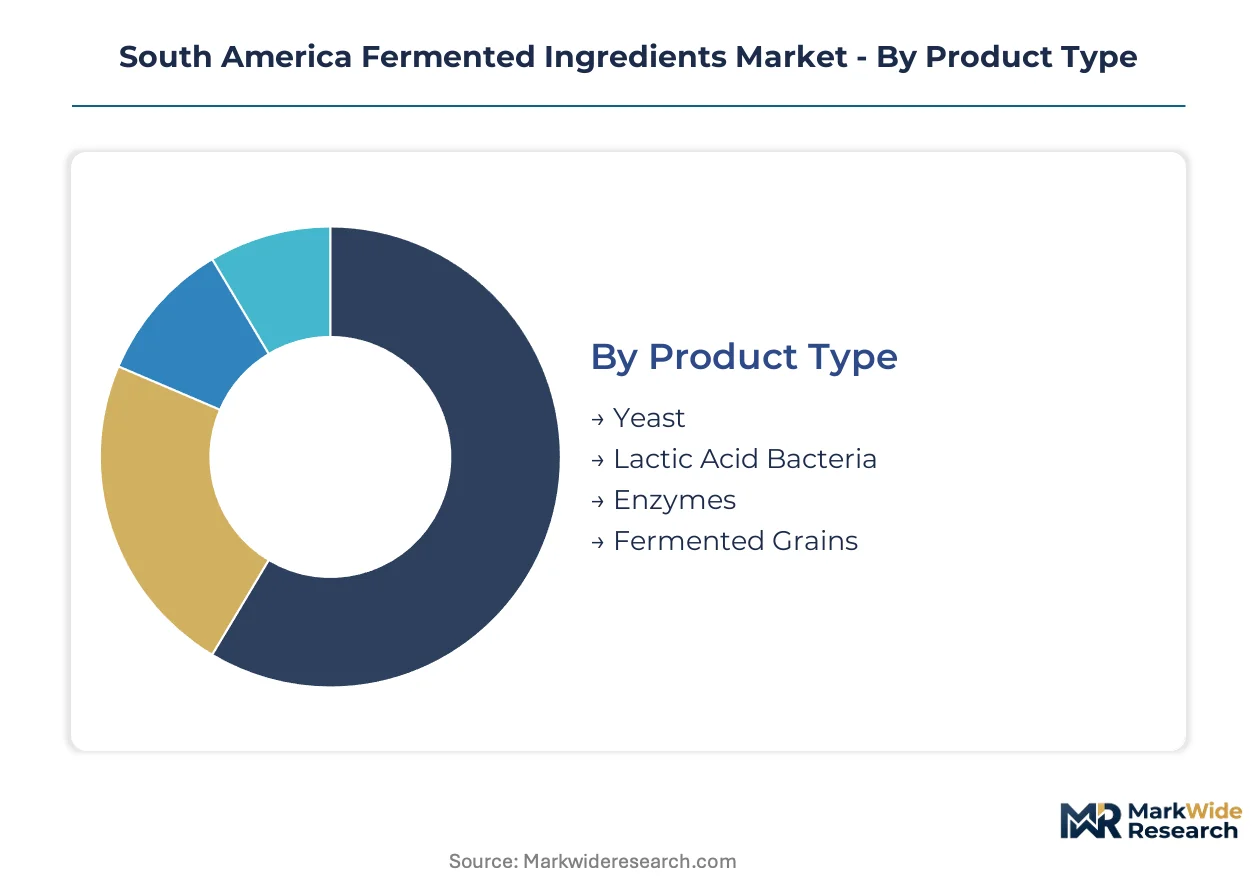
Segmentation in the South America fermented ingredients market reveals distinct technical service and supply chain requirements across product categories. Manufacturers configure their distribution and support infrastructure differently depending on whether they serve bulk ethanol processors or precision-dependent dairy and meat operations.
Product Type:
After-sales technical support intensity varies dramatically across product types, with enzymes and specialty cultures requiring on-site fermentation optimization while commodity yeast operates through simpler volume contracts.
- Yeast:Metabolically active Saccharomyces cerevisiae strains dominate biomass volumes, with thermotolerant variants engineered for Brazil's fuel ethanol sector where continuous fermentation systems demand consistent performance under elevated temperatures. ANVISA's documentation requirements for imported active dry yeast are pushing processors toward domestic culture banks with full substrate traceability.
- Lactic Acid Bacteria:Defined-strain cultures of Lactobacillus and Lactococcus species deliver clean-label preservation in meat and dairy applications, with demand concentrating in São Paulo state's industrial corridor as processors replace chemical additives. ANVISA's evolving additive regulations are accelerating qualification of domestic suppliers capable of demonstrating full regulatory documentation.
- Enzymes:Protease, lipase, and amylase preparations command premium pricing where specificity reduces processing costs.
- Fermented Grains:Koji-derived and malt-based inputs remain concentrated in artisanal beverage channels.
By volume, yeast leads. By growth pace, lactic acid bacteria is ahead.
Application:
Application segments diverge sharply in their fermentation control requirements, with beverages and dairy demanding precision temperature management while meat processing emphasizes pathogen inhibition.
- Beverages:Craft breweries and fuel ethanol processors drive differentiated yeast requirements, with microbreweries across Brazil and Argentina fragmenting supply chains toward direct-to-producer liquid culture delivery.
- Dairy Products:Cheese and yogurt manufacturers anchor demand for defined-strain mesophilic and thermophilic cultures, with São Paulo state's processing clusters creating efficient distribution economics for suppliers offering integrated technical service.
- Bakery Products:Baker's yeast and dough conditioning enzymes serve industrial and artisanal channels.
- Meat Products:Fermented sausages and cured meats utilize lactic acid bacteria for pH reduction and shelf-life extension.
Beverages generate the highest absolute volumes. Dairy applications show the steepest expansion trajectory as clean-label preservation gains regulatory tailwinds.
End User:
End user segments stratify by technical sophistication, with pharmaceutical and nutraceutical buyers imposing purity standards that food manufacturers rarely match.
- Food & Beverage Industry:Massive yeast offtake from biofuel processors funds regional fermentation infrastructure, while meat and dairy processors drive culture innovation through ANVISA-compliant clean-label reformulation.
- Pharmaceutical Industry:High-purity enzyme inputs require capital-intensive downstream processing that limits supplier participation to specialized manufacturers with GMP certification.
- Cosmetic Industry:Fermented extracts and organic acids serve active ingredient formulations.
- Nutraceuticals:Probiotic strains and postbiotic compounds target supplement applications.
Food and beverage dominates procurement volumes. Nutraceuticals is expanding most quickly as consumer positioning shifts toward gut health.
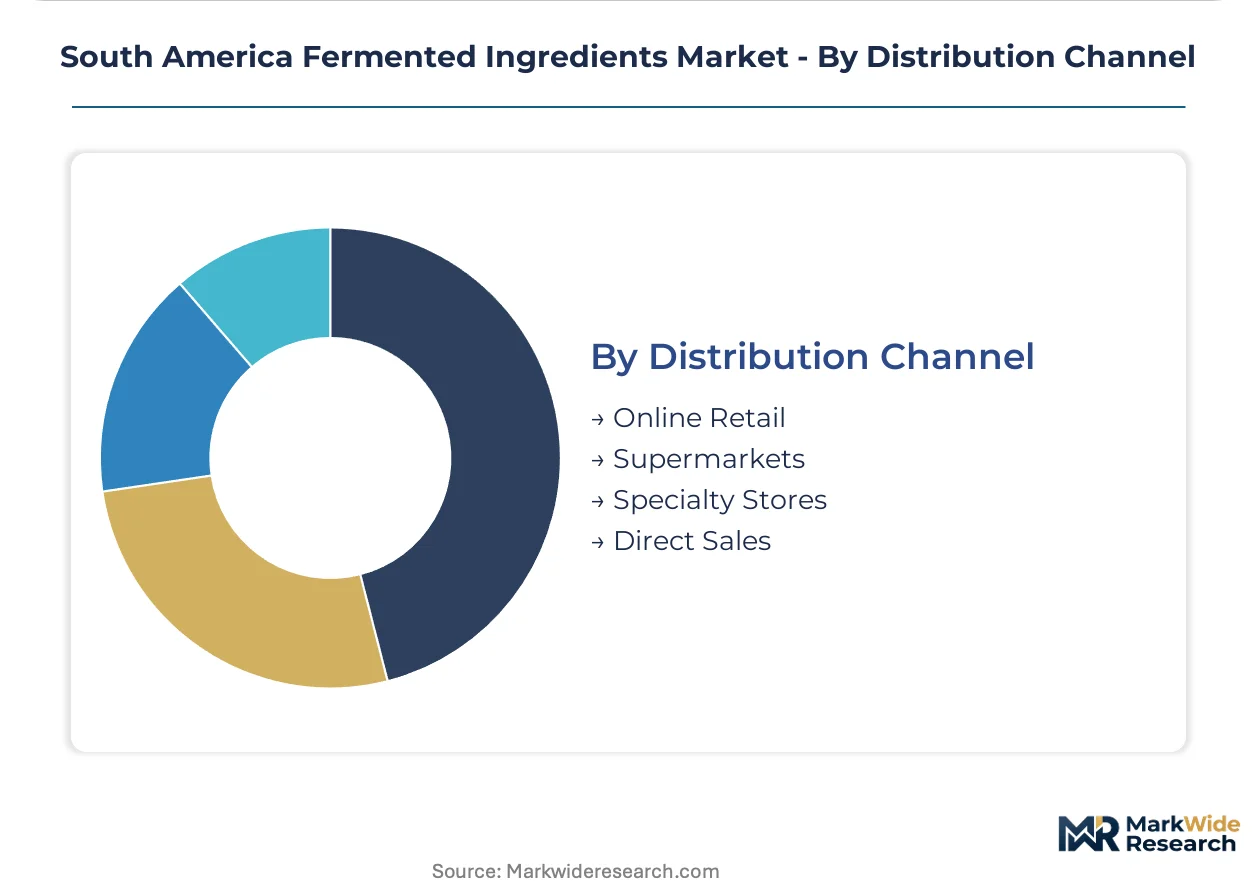
Distribution Channel:
Distribution channel selection reflects buyer scale and technical support requirements, with large processors bypassing intermediaries while smaller operators rely on specialized retail.
- Direct Sales:Multi-year contracts bundling strain supply with on-site fermentation optimization are displacing spot-market purchases among mid-sized meat processors in Paraná state's poultry belt.
- Specialty Stores:Regional distributors serving craft beverage producers maintain liquid yeast culture inventories with cold-chain integrity.
- Online Retail:E-commerce platforms serve small-scale artisanal producers with packaged dried cultures.
- Supermarkets:Mass-market retail channels carry limited consumer-facing fermentation starter kits.
Direct sales captures the largest transaction values. Online retail is gaining share fastest among emerging craft producers outside major industrial corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA governs the dominant Brazilian market for fermented ingredients, with regulatory decisions in São Paulo reverberating across Mercosur trade corridors and shaping procurement strategies throughout the continent.
Brazil
São Paulo state's food processing clusters generate concentrated demand for lactic acid bacteria and precision fermentation enzymes. ANVISA's evolving identity preservation rules are compressing margins for imported cultures while protecting domestic culture banks with full substrate traceability. Paraná state's expanding poultry belt is consolidating procurement around multi-year contracts bundling strain supply with on-site technical service.
Argentina
Craft beverage producers are fragmenting liquid yeast supply chains beyond Buenos Aires as microbreweries multiply across Córdoba and Mendoza provinces. The national food code administered by the Ministry of Health maintains parallel requirements to Brazilian standards, though Mercosur technical committees are working to harmonize microbiological specifications. Domestic culture suppliers are qualifying under tighter allergen disclosure frameworks to capture cross-border dairy processing demand.
Chile
Wine producers in the Central Valley are adopting thermotolerant yeast strains engineered for elevated fermentation temperatures. The country's national pharmaceutical regulator maintains strict GMP certification requirements for high-purity enzyme inputs serving nutraceutical applications. Santiago's biotechnology corridor is attracting precision fermentation investments targeting co-production of food-grade proteins alongside traditional outputs.
Colombia
Dairy processors in the Bogotá savanna are replacing chemical preservatives with clean-label lactic acid bacteria cultures as consumer preferences shift. The national food and drug surveillance institute is tightening documentation requirements for imported fermentation-derived inputs, elevating compliance costs for European and North American suppliers. Medellín's emerging food technology cluster is developing domestic strain characterization capabilities to reduce import dependency.
Peru
Traditional fermented beverage producers in the Andean highlands are scaling artisanal grain fermentation methods toward industrial volumes. The country's health ministry is developing national standards for microbial culture safety that align with Codex Alimentarius guidelines. Lima's coastal processing belt is importing specialized thermotolerant strains for dairy applications that domestic suppliers cannot yet manufacture locally.
South America Fermented Ingredients Market Competitive Landscape
Specialized enzyme technology providers and integrated culture suppliers split the market into distinct competitive spheres. Consolidation pressure is intensifying around technical service capabilities rather than commodity volume, with mid-sized meat and dairy processors abandoning spot-market purchases for bundled optimization contracts. Three archetypes dominate: multinational biotechnology platforms with deep strain libraries, regional distribution specialists controlling import logistics, and domestic culture banks leveraging regulatory documentation advantages. Capacity expansion and strategic partnerships represent the dominant competitive moves, particularly where precision fermentation platforms require capital-intensive downstream processing infrastructure.
Among European biotechnology platforms, Novozymes A/S and Chr. Hansen Holding A/S exemplify the enzyme technology and specialized culture archetypes respectively. Novozymes occupies a position as the regional anchor for large-scale ethanol and food processing applications, while Chr. Hansen represents the tropical strain adaptation specialist with libraries engineered for heat-tolerant fermentation conditions. Kerry Group plc sits within the integrated technical service tier, anchoring dairy culture supply through specialized fermentation optimization bundled with strain delivery. Manuchar Brazil exemplifies the regional logistics archetype, controlling import channels for specialty inputs that domestic producers cannot yet source locally.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Novozymes A/S |
| BASF SE |
| Kerry Group plc |
| Dohler Group SE |
| Chr. Hansen Holding A/S |
| Lonza Group |
| Archer Daniels Midland Company |
| Manuchar Brazil |
| Others |
Value Network & Pricing Analysis
Undercapacity in Brazil's domestic thermotolerant culture production is compressing margins for imported strains while elevating pricing power for local culture banks with full ANVISA documentation. This utilization imbalance forces large meat and dairy processors toward multi-year contracts bundling technical service with strain supply, while smaller buyers absorb spot-market volatility.
Pricing Analysis
Price spreads between European-imported specialty enzymes and domestically sourced lactic acid bacteria cultures exceed threefold across São Paulo's industrial corridor. Three-tier pricing structure across premium pharmaceutical-grade enzymes, standard food-grade cultures, and economy bulk yeast segments reflects certification burden and downstream processing intensity. Cost compression in the premium tier is intensifying as Brazilian ethanol processors adopt precision fermentation platforms for co-production. Small-scale craft beverage producers exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize purity grades over unit economics.
Supply Chain Analysis
Export-control restrictions on CRISPR-edited chassis organisms limit precision fermentation technology flows into Brazilian biotechnology investments. Supply concentration centers on Denmark and the Netherlands for specialty enzymes, with Argentina and Chile emerging as alternative culture sourcing nodes. Raw material dependencies span molasses substrates for yeast propagation, defined growth media for bacterial cultures, and pharmaceutical-grade filtration membranes. Single-source vulnerability runs through thermotolerant strain imports that domestic producers cannot yet replicate. Distribution runs through direct sales channels for large processors and specialty cold-chain distributors for craft beverage segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against chemical preservative reformulation as ANVISA tightens additive regulations. Incumbents must navigate the threat of synthetic biology alternatives displacing traditional fermentation inputs.
For Market Incumbents: Entrench position through backward integration into domestic culture banking capabilities that satisfy ANVISA's identity preservation rules. Acquire or partner with São Paulo-state biotechnology laboratories to secure full substrate traceability documentation. Expand technical service teams in Paraná's poultry belt to lock in multi-year contract renewals before competitors match bundled optimization offerings.
For New Entrants and Emerging Players: Mid-sized dairy processors in Colombia's Bogotá savanna represent the most penetrable entry point for clean-label lactic acid bacteria cultures with full regulatory documentation. Argentina's craft beverage corridor outside Buenos Aires offers white-space for direct-to-brewery liquid yeast distribution with cold-chain differentiation. Pursue regulatory qualification ahead of volume scaling to capture ANVISA-compliant procurement shifts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation platforms as Brazilian ethanol processors repurpose existing infrastructure for food-grade protein co-production. Five-to-ten-year viability favors integrated technical service providers over pure commodity culture suppliers. Target acquisition archetypes include domestic culture banks with complete ANVISA documentation and tropical strain adaptation capabilities. Monitor Mercosur technical committee harmonization progress as the signal for pan-regional procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Culture Bank Expansion | ANVISA's identity preservation rules protect qualified local suppliers from import competition. |
| Precision Fermentation Platform Adoption | Brazilian ethanol processors leverage existing infrastructure for food-grade protein co-production. |
| Technical Service Bundling | Paraná poultry processors prioritize fermentation optimization over spot-market unit pricing. |
| Tropical Strain Library Development | Heat-tolerant organisms address processing conditions European cultures cannot survive. |
| Mercosur Regulatory Harmonization | Alignment between Brazilian and Argentine standards enables pan-regional procurement consolidation. |
Research Methodology
Desk research of ANVISA regulatory filings, Mercosur technical committee protocols, and Brazilian customs trade data preceded structured interviews with fermentation technology directors, dairy processing plant managers, craft brewery procurement leads, and specialty enzyme distribution channel partners. Bottom-up volume estimates derived from ethanol processor capacity disclosures and culture supplier shipment patterns were cross-validated against top-down market sizing from industrial biotechnology investment flows.
Forecast assumptions held Brazilian biofuel policy support and ANVISA clean-label regulatory trajectory constant while varying currency volatility exposure and Mercosur harmonization timing. Segmentation modeling spanned product type, application, and end-user industry with regional production cluster as an additional dimension. CAGRs were computed from annualized growth rate analysis across the projection horizon, incorporating strain qualification timelines and processor retrofitting cycles as industry-specific inputs.
Practitioners should monitor ANVISA guidance updates and Mercosur technical committee divergence signals for early indicators of procurement strategy disruption. Cross-checking against Brazilian industrial biotechnology investment databases and ethanol sector capacity utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
China Corn Glucose Market
Ingredients
Beetroot Powder Market
Ingredients
Avocado Oil Market
Ingredients
Medium-Chain Triglyceride (MCT) Fat Market
Ingredients
Pepsin Market
Ingredients
Specialty Flours Market
Ingredients
Moringa Ingredients Market
Ingredients
Prenatal Vitamin Ingredients Market
Ingredients
China Gelatin Market
Ingredients
Pea Hull Fiber Market
Ingredients
Fermented Ingredients Market
Ingredients
All Purpose Flour Market
Ingredients
Food Grade Cassia Gum Powder Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Roasted Grain Ingredients Market
Ingredients
Low Calorie Oil Market