
 Food Delivery Logistic Market | 2026-2036
Food Delivery Logistic Market Size, Share, and Industry Trends Forecast 2026-2036
Food Delivery Logistic Market Analysis
Grocery store delivery is shifting toward same-day and instant fulfillment models, pulling refrigerated fleet capacity away from traditional restaurant channels. C.H. Robinson Worldwide, Inc. leverages its digital freight platform to match temperature-controlled loads across fragmented carrier networks. Schneider National, Inc. sustains dedicated cold-chain routes through proprietary fleet tracking infrastructure. Deutsche Bahn AG anchors European intermodal food logistics with rail-linked cold storage terminals in Germany and the Netherlands.
Food delivery logistics encompasses the temperature-controlled transportation, warehousing, and last-mile distribution infrastructure that moves prepared meals and perishable groceries from production points to end consumers within defined freshness windows, typically requiring maintenance of sub-5°C cold chain integrity for dairy, seafood, and ready-to-eat categories. The primary commercial purpose centers on minimizing spoilage-related losses while compressing order-to-door cycle times to under thirty minutes for on-demand segments. Scheduled delivery methods dominate margin pools through predictable route density and lower per-unit dispatch costs, while on-demand methods capture the fastest expansion as urban consumers prioritize immediacy over planned purchasing. Mobile apps lead technology adoption by integrating order placement, real-time tracking, and digital payment into unified interfaces that reduce coordination friction between restaurants, drivers, and customers.
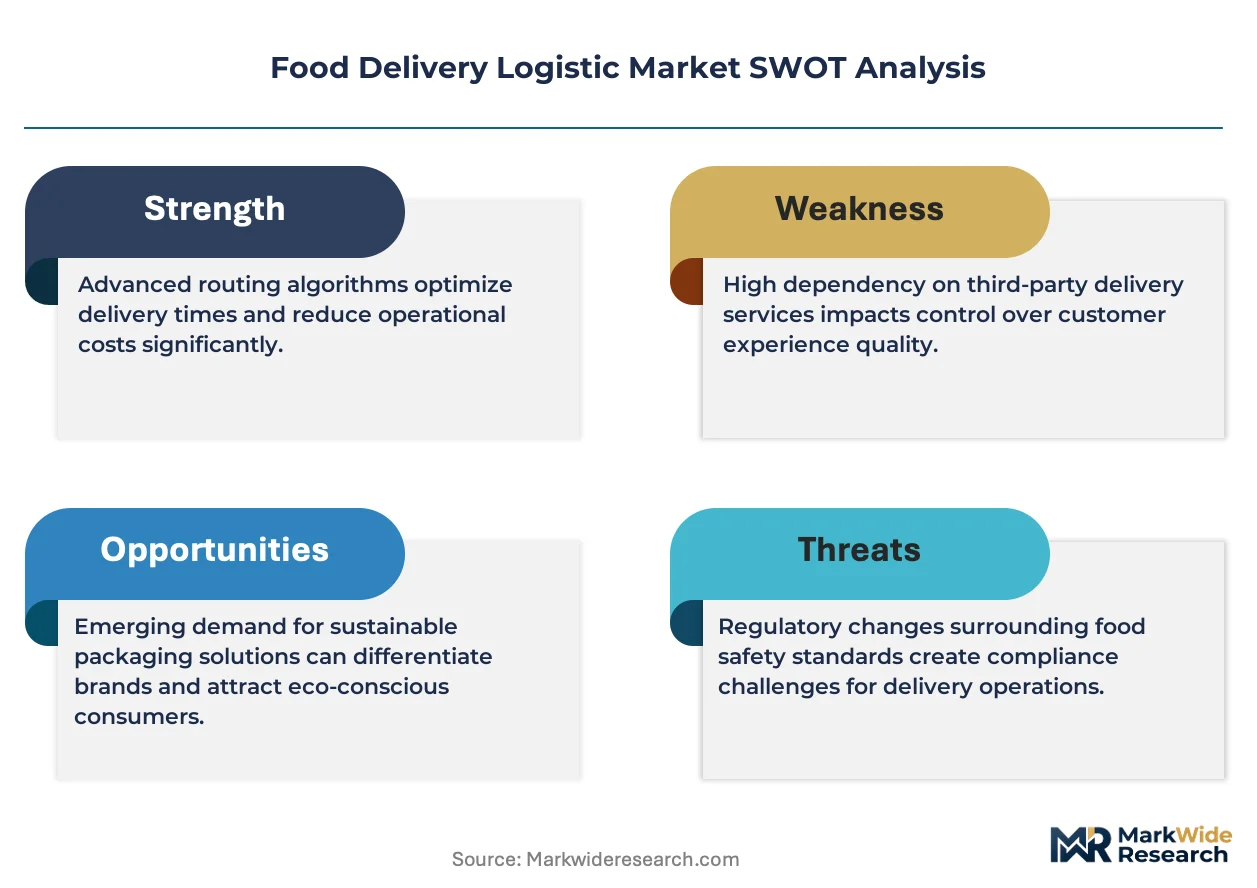
The US Department of Transportation enforces hours-of-service rules that constrain driver availability for extended last-mile routes, while the FDA's Food Safety Modernization Act mandates documented temperature controls throughout transportation. The EU Green Deal's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in delivery vehicle cooling units, forcing fleet operators to retrofit or replace equipment. India's FSSAI mandates hygiene ratings for cloud kitchens and delivery partners, shaping market access for logistics providers serving unbranded food preparers. Stakeholders must monitor how refrigerant transition timelines and driver shortage regulations interact to reshape total cost structures across short-haul and long-haul food distribution networks.
Market Dynamics
Dark kitchen proliferation and refrigerated fleet fragmentation are compressing route density economics while pulling cold-chain capacity toward grocery instant fulfillment. Operators now compete for the same driver pools and vehicle assets across meal and perishable categories.
Growth Catalysts
- Smartphone penetration corridors:Urban India, Brazil, and Indonesia are generating concentrated order volumes as middle-class expansion meets mobile-first commerce infrastructure.
- FSSAI hygiene mandates:India's food safety regulator is certifying cloud kitchens and delivery partners, creating compliant market access for logistics providers serving unbranded preparers.
- Route optimization platforms:GPS tracking and dispatch algorithms are compressing order-to-door cycle times below thirty minutes in on-demand segments.
Market Restraints
- Refrigerant transition costs:The EU Green Deal's F-Gas Regulation is forcing fleet operators to retrofit hydrofluorocarbon cooling units or replace equipment entirely.
- Driver availability constraints:US Department of Transportation hours-of-service rules limit extended last-mile route coverage and compress dispatch windows.
- Cold-chain integrity requirements:FDA Food Safety Modernization Act documentation mandates raise compliance overhead for temperature-controlled transportation.
Strategic Opportunities
- Rail-linked intermodal hubs:Deutsche Bahn AG's cold storage terminals in Germany and the Netherlands demonstrate European freight-rail integration for long-haul food distribution.
- Digital freight matching:Temperature-controlled load platforms can aggregate fragmented carrier networks across scheduled and on-demand segments.
- Dark kitchen network density:Restaurant chains are expanding production-only facilities that reduce last-mile distance and enable dedicated fleet deployment.
Industry Challenges
- Refrigerant retrofit timelines:Fleet operators face compressed equipment replacement schedules as F-Gas phase-down deadlines approach.
- Cross-segment capacity competition:Grocery same-day fulfillment is diverting refrigerated vehicles from traditional restaurant channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Delivery Logistic Market |
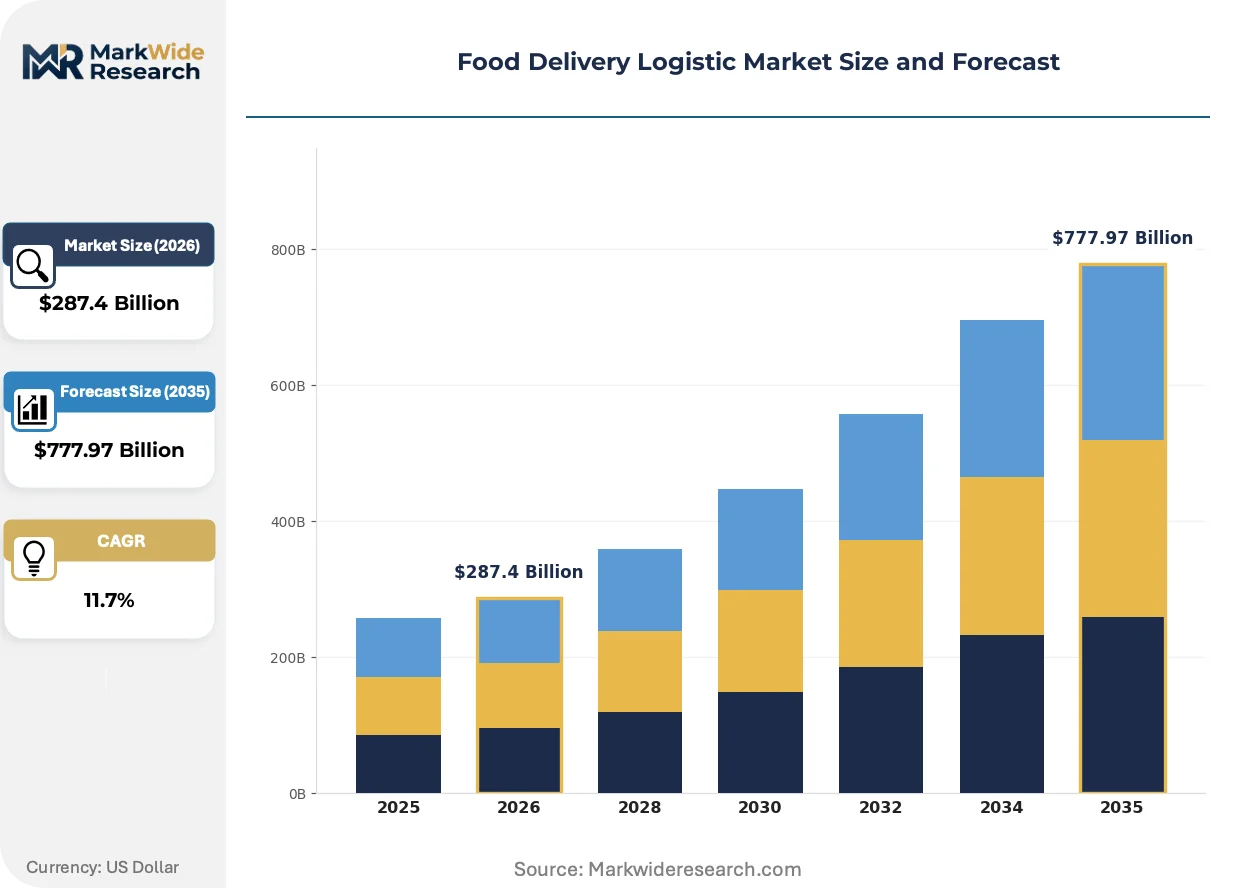
| Market Size in 2026 | $287.4 Billion |
| Market Size in 2035 | $777.97 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Method: On-demand, Scheduled, Hybrid, Bulk End User: Restaurants, Grocery Stores, Meal Kit Services, Catering Companies Technology: Mobile Apps, Website Platforms, GPS Tracking, Payment Solutions Vehicle Type: Bicycles, Motorcycles, Vans, Trucks |
| Companies Covered | Alliance Shippers, Inc., Hellmann Worldwide Logistics, C.H. Robinson Worldwide, Inc., CaseStack, Inc., Bender Group, Schneider National, Inc., Echo Global Logistics, Inc., Henningsen Cold Storage Co., Deutsche Bahn AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Delivery Logistic Market Emerging Trajectories
Real-time visibility infrastructure and regulatory compliance automation are redefining operational baselines. Fleet operators now differentiate through predictive temperature management and dynamic route orchestration rather than asset ownership alone.
AI-powered demand forecasting is converging with dynamic fleet repositioning. Dark kitchen operators in São Paulo and Jakarta deploy predictive algorithms to pre-stage delivery capacity before lunch and dinner rushes. This convergence is compressing idle time and raising vehicle utilization rates above traditional scheduled delivery benchmarks.
The EU F-Gas Regulation is accelerating natural refrigerant adoption in delivery vehicle cooling systems. Fleet operators face retrofit deadlines that compress capital planning cycles. Cold-chain logistics providers serving Benelux and German corridors are prioritizing CO2 and propane-based units to maintain market access.
Urban consumers now prioritize immediacy over planned purchasing in meal and grocery categories. On-demand delivery platforms displace scheduled weekly shopping in São Paulo, Mumbai, and Jakarta metropolitan zones. This behavioral pivot is fragmenting order sizes and forcing logistics networks to optimize for trip density rather than load consolidation.
Food Delivery Logistic Market Segmentation
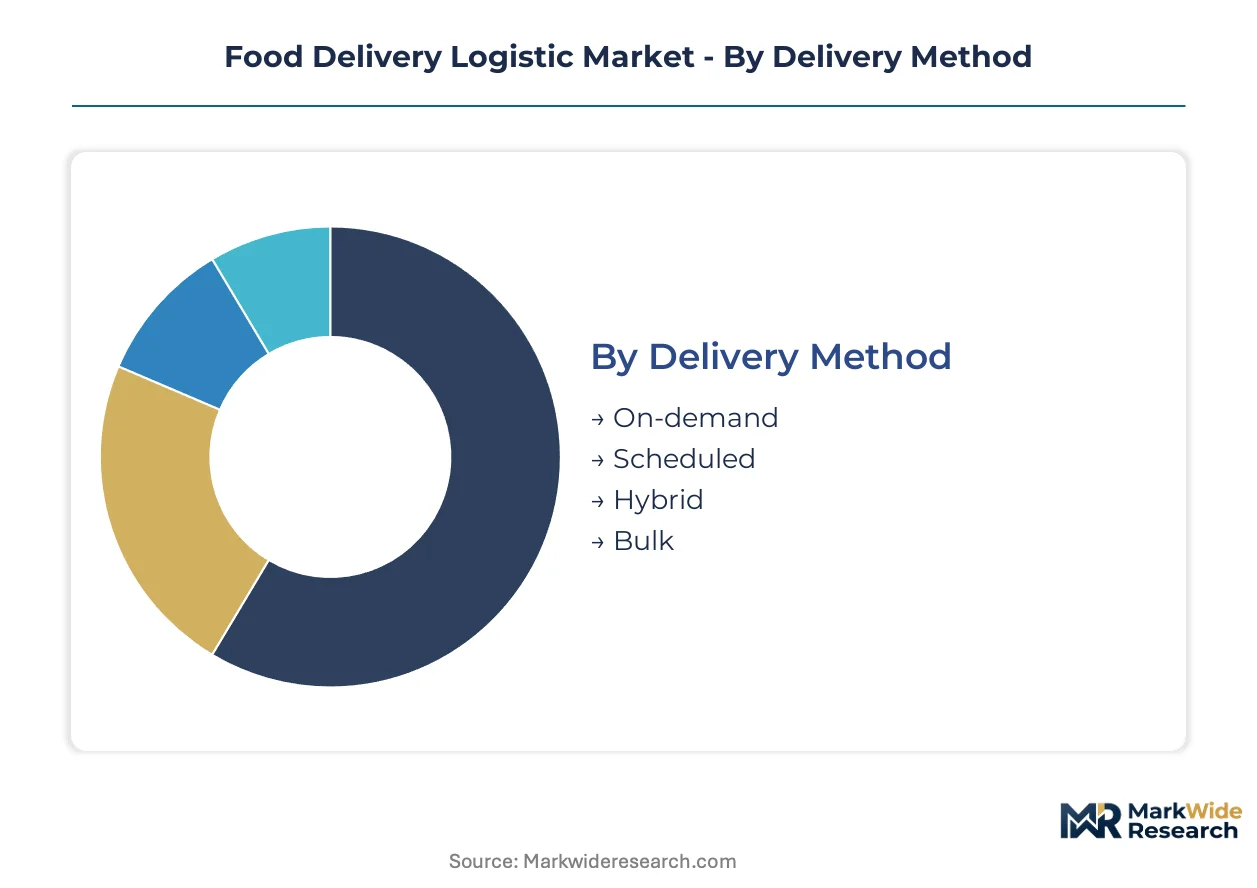
Food delivery logistics operators configure fleet and technology stacks around distinct service velocity requirements and payload characteristics. Segmentation reveals how capital intensity, regulatory exposure, and margin structures diverge across operational models.
Delivery Method:
Buyers in this category differentiate by tolerance for planning versus immediacy, which dictates fleet utilization economics and driver compensation structures.
- On-demand:Point-to-point dispatch within thirty-minute windows requires dense driver pools and real-time algorithmic routing. Urban corridors in India, Brazil, and Indonesia concentrate order volumes where smartphone penetration meets middle-class expansion.
- Scheduled:Pre-booked time slots enable batch consolidation and predictable route density, yielding lower per-unit dispatch costs. Restaurant chains and grocery stores leverage this method for margin preservation in non-peak hours.
- Hybrid:Combines scheduled base loads with on-demand surge capacity to balance utilization and responsiveness. Operators in São Paulo and Jakarta deploy predictive algorithms to pre-stage capacity before lunch and dinner rushes.
- Bulk:Large-format catering and institutional contracts prioritize load consolidation over speed. Catering companies and corporate cafeterias drive demand for refrigerated trucks with multi-drop route optimization.
Volume sits with scheduled delivery; growth tilts toward on-demand as urban consumers prioritize immediacy over planned purchasing.
End User:
Payload temperature requirements and order frequency patterns separate commercial buyers in this dimension.
- Restaurants:Prepared meals demand sub-5°C cold chain integrity for dairy, seafood, and ready-to-eat categories. Dark kitchen proliferation is pulling refrigerated fleet capacity toward production-only facilities that reduce last-mile distance.
- Grocery Stores:Perishable inventory requires continuous temperature documentation under FDA Food Safety Modernization Act mandates. Same-day and instant fulfillment models are diverting refrigerated vehicles from traditional restaurant channels.
- Meal Kit Services:Subscription-based prepared ingredient boxes combine ambient, chilled, and frozen segments in single shipments. Weekly delivery cycles favor scheduled routing with insulated packaging over active refrigeration.
- Catering Companies:Event-driven volume spikes necessitate surge fleet access and flexible driver pools. Bulk delivery windows accommodate load consolidation but require precise timing coordination.
Restaurants anchor current fleet deployment; grocery instant fulfillment is climbing the fastest as refrigerated capacity reallocates toward perishable e-commerce.
Technology:
Integration depth with customer-facing interfaces and back-end dispatch systems defines technology adoption tiers.
- Mobile Apps:Unified interfaces for order placement, real-time tracking, and digital payment reduce coordination friction between restaurants, drivers, and customers. Urban India and Indonesia show concentrated adoption where mobile-first commerce infrastructure dominates.
- Website Platforms:Browser-based ordering captures desktop users and corporate procurement workflows with higher average order values. Meal kit services and catering companies favor this channel for subscription management.
- GPS Tracking:Real-time visibility infrastructure enables dynamic route orchestration and predictive arrival estimates. Fleet operators differentiate through location intelligence rather than asset ownership alone.
- Payment Solutions:Digital wallet integration and split-payment features reduce cash-handling overhead and driver safety risks. Brazil's PIX instant payment system accelerates adoption in São Paulo metropolitan zones.
Mobile apps command the largest user base; GPS tracking infrastructure is gaining share fastest as operators compete on delivery precision.
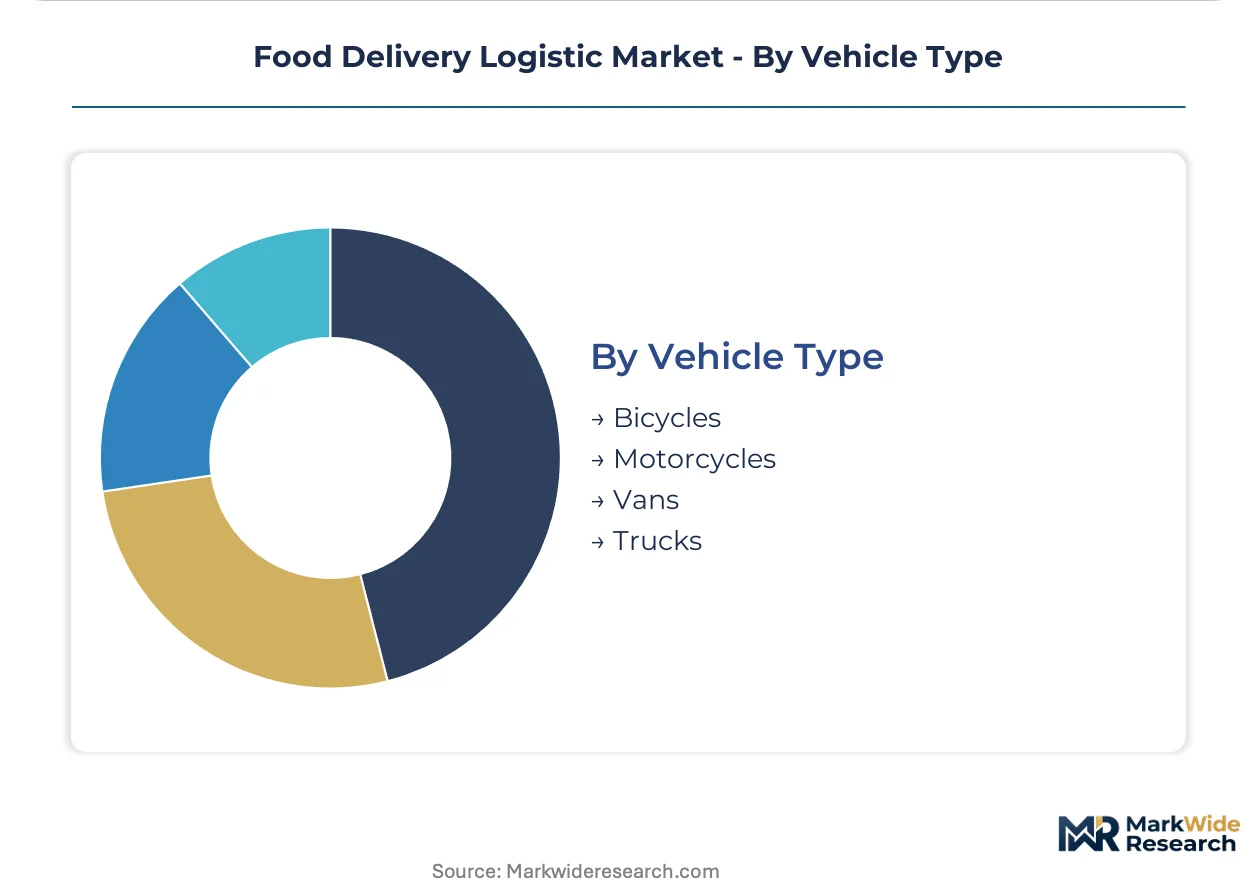
Vehicle Type:
Payload capacity, regulatory access, and refrigerant technology requirements segment fleet composition.
- Bicycles:Zero-emission last-mile coverage in dense urban cores with limited parking and congestion charging. EU Green Deal F-Gas Regulation pressures operators toward human-powered options in Benelux and German city centers.
- Motorcycles:Maneuverability through traffic-constrained corridors with insulated box attachments for short-haul temperature maintenance. Jakarta and Mumbai rely heavily on two-wheeler fleets for sub-thirty-minute delivery windows.
- Vans:Mid-capacity refrigerated units with CO2 and propane-based cooling systems replacing hydrofluorocarbon equipment. Retrofit deadlines under EU F-Gas phase-down timelines compress capital planning cycles.
- Trucks:Long-haul intermodal capacity with rail-linked cold storage terminals anchoring European food distribution networks. Deutsche Bahn AG's German and Netherlands facilities demonstrate freight-rail integration for scheduled bulk movement.
Motorcycles dominate urban last-mile volume; vans are expanding most quickly as refrigerant transitions force fleet modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in São Paulo, Mumbai, and Jakarta are concentrating cold-chain infrastructure investment where smartphone penetration and middle-class expansion converge. These corridors generate disproportionate order volumes for on-demand food delivery logistics.
United States
Urban corridors in California and Texas drive refrigerated fleet deployment for grocery instant fulfillment. The FDA's Food Safety Modernization Act mandates documented temperature controls throughout transportation. Los Angeles and Dallas metropolitan zones witness dark kitchen proliferation pulling dedicated delivery capacity toward production-only facilities.
Germany
Rail-linked intermodal hubs anchor European long-haul food distribution networks. The EU Green Deal's F-Gas Regulation forces fleet operators to retrofit hydrofluorocarbon cooling units or replace equipment entirely. Deutsche Bahn AG's cold storage terminals in the Netherlands corridor demonstrate freight-rail integration for scheduled bulk movement.
India
Maharashtra and Karnataka states generate concentrated order volumes as mobile-first commerce infrastructure penetrates urban middle-class households. FSSAI hygiene ratings for cloud kitchens and delivery partners shape compliant market access for logistics providers. Mumbai and Bangalore metropolitan zones deploy predictive algorithms to pre-stage delivery capacity before lunch and dinner rushes.
Brazil
São Paulo's metropolitan zone anchors Latin American demand for sub-thirty-minute delivery windows. ANVISA, the country's national health regulatory agency, oversees food safety compliance for delivery operations. PIX instant payment integration accelerates digital wallet adoption across two-wheeler fleet networks.
Indonesia
Jakarta and Surabaya urban corridors concentrate Southeast Asian order volumes where motorcycle fleets dominate last-mile density. The national food and drug regulator enforces hygiene standards for cloud kitchen certification. Predictive demand forecasting algorithms compress idle time and raise vehicle utilization rates above traditional scheduled delivery benchmarks.
Food Delivery Logistic Market Vendor Landscape
Top-tier vendors anchor integrated digital freight platforms, while mid-tier specialists compete on temperature-controlled niche coverage. The vendor base stratifies across asset-heavy fleet operators, technology-enabled brokers, and rail-intermodal infrastructure providers. Three archetypes dominate: digital freight matchers aggregating fragmented carrier networks, dedicated cold-chain operators with proprietary tracking infrastructure, and intermodal rail specialists anchoring long-haul distribution. Competitive moves center on refrigerant transition compliance and dark kitchen network partnerships.
Among North American logistics providers, C.H. Robinson Worldwide, Inc. and Schneider National, Inc. occupy positions within the digital freight and dedicated fleet archetypes respectively. Deutsche Bahn AG represents European rail-intermodal infrastructure concentration. These entities exemplify how geographic specialization and regulatory compliance capabilities differentiate positioning across fragmented cold-chain markets.
| Leading Market Players |
|---|
| Alliance Shippers, Inc. |
| Hellmann Worldwide Logistics |
| C.H. Robinson Worldwide, Inc. |
| CaseStack, Inc. |
| Bender Group |
| Schneider National, Inc. |
| Echo Global Logistics, Inc. |
| Henningsen Cold Storage Co. |
| Deutsche Bahn AG |
| Others |
Supply Flow & Price Mechanics
Restaurant chains and grocery retailers with high-frequency ordering patterns anchor pricing power in contract-based long-term offtake agreements. These volume-committed buyers extract rate concessions from fleet operators while spot-market shippers absorb premium pricing for sub-thirty-minute dispatch windows.
Pricing Analysis
Lead-time compression commands premium positioning in food delivery logistics, with on-demand slots pricing at multiples above scheduled batch routes. Three-tier pricing structure across premium, standard, and economy levels separates urgent restaurant dispatch from consolidated grocery windows and bulk catering contracts. Price differentiation hinges on temperature certification grade and geographic delivery density, with FDA Food Safety Modernization Act documentation adding compliance overhead that operators pass through to price-sensitive independent restaurants. Cost compression in the mid-tier scheduled segment is intensifying because grocery same-day fulfillment is diverting refrigerated capacity from traditional meal channels.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for cold-chain infrastructure and the EU Green Deal's F-Gas Regulation are reshaping sourcing toward local refrigerant equipment manufacturers and natural-cooling system providers. Refrigerated vehicle assembly concentrates in Germany, Japan, and China, with CO2 and propane-based cooling units drawing from specialized component ecosystems in the Netherlands and South Korea. Fleet operators face single-source vulnerability in compressor technology where European retrofit deadlines compress equipment availability. Distribution runs through hub-and-spoke cold storage terminals anchored by rail-linked intermodal facilities in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food delivery logistics is becoming a vertical-integration race as operators pursue captive control over dark kitchen real estate to lock in route density. Upstream integration into production-only facilities reduces last-mile distance and secures dedicated fleet deployment against grocery-sector competition.
For Market Incumbents: Acquire dark kitchen network assets in São Paulo, Mumbai, and Jakarta metropolitan zones to defend route density against grocery instant fulfillment entrants. Secure CO2-based refrigeration equipment through backward integration into European cooling system suppliers before F-Gas retrofit deadlines eliminate hydrofluorocarbon alternatives. Reinforce driver pool retention through predictive algorithm deployment that compresses idle time below competitor benchmarks. For New Entrants and Emerging Players: Unbranded cloud kitchens in secondary Indian and Indonesian cities present the most penetrable buyer archetype for compliant logistics access under FSSAI hygiene mandates. Target scheduled bulk catering contracts in Brazil's corporate cafeteria segment where PIX instant payment integration reduces cash-handling overhead. Pursue white-label fleet technology licensing to regional carriers lacking proprietary GPS tracking infrastructure. For Investors and Strategic Acquirers: The window for entry favors digital freight matchers with temperature-controlled load aggregation capabilities across fragmented carrier networks. Mid-tier cold-chain specialists with proprietary tracking infrastructure represent priority acquisition targets as refrigerant transition timelines compress capital planning cycles. Watch for inflection signals in natural refrigerant adoption rates across Benelux and German fleet operator procurement disclosures.| Strategic Initiative | Industry Significance |
|---|---|
| Dark Kitchen Network Acquisition | Production-only facilities in São Paulo and Mumbai reduce last-mile distance below thirty-minute thresholds. |
| Natural Refrigerant Fleet Retrofit | CO2 and propane-based cooling units maintain EU market access under F-Gas phase-down deadlines. |
| Predictive Demand Algorithm Deployment | Pre-staged capacity before lunch rushes raises vehicle utilization above scheduled delivery benchmarks. |
| Rail-Linked Intermodal Hub Investment | Deutsche Bahn AG's German and Netherlands terminals demonstrate long-haul cold-chain anchoring. |
| Digital Freight Platform Integration | Temperature-controlled load matching aggregates fragmented carrier networks across on-demand segments. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this food delivery logistics analysis. Fleet operator dispatch records, FSSAI hygiene certification databases, and EU F-Gas compliance disclosures provided volume and regulatory validation. Primary interviews with cold-chain logistics directors, restaurant procurement managers, dark kitchen operators, and refrigerated vehicle fleet supervisors combined with bottom-up and top-down triangulation across customs import data and transportation association membership records.
Reconciliation of fleet deployment statistics, route optimization platform adoption metrics, and refrigerated vehicle registration data shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include delivery method velocity tiers, end-user payload temperature requirements, technology integration depth, and vehicle type refrigerant classifications. CAGRs derived from trend extrapolation of smartphone penetration corridors, middle-class expansion patterns, and regulatory compliance cost trajectories. Dark kitchen network density and grocery instant fulfillment capacity diversion served as industry-specific forecast inputs.
Revisions become necessary when refrigerant transition timelines accelerate, driver availability regulations tighten, or grocery-sector refrigerated capacity competition intensifies beyond modeled assumptions. Forecasts reflect documented assumptions about urban corridor order volume concentration and regulatory enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Germany Same Day Delivery Market
Logistics and Shipping
Global 3PL in Cold Chain Logistics Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
North America Freight Brokerage Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
Middle East Freight Forwarding Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
Iraq Air Freight Transport Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market
Logistics and Shipping
Europe Courier Market
Logistics and Shipping
France Parcel Market
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
Vietnam Freight and Logistics Market