
 Magnesium Wheel Market | 2026-2036
Magnesium Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Wheel Market Analysis
High-strength AZ91E and WE43 alloy specifications is rotating the market toward aerospace-grade material thresholds. BBS Kraftfahrzeugtechnik AG leverages German forging heritage to command premium motorsport channels. Enkei Corporation anchors Asian supply through vertically integrated casting and machining operations. HRE Performance Wheels differentiates via bespoke forged configurations for supercar OEM programs.
Magnesium wheels are structural components cast or forged from magnesium-aluminum-zinc alloys, typically achieving 25-35% mass reduction versus comparable aluminum designs while maintaining fatigue thresholds above 120 MPa; their primary purpose is unsprung weight reduction to improve vehicle handling response and fuel efficiency. Forged wheels capture the highest margin pools due to grain-structure integrity and defect rates below 0.5%, while cast wheels dominate unit volume through OEM scale economies. Automotive applications lead absolute demand, though aerospace qualification timelines for magnesium alloys are shortening as MEE and FAA harmonize flammability testing protocols.
NHTSA enforces FMVSS 138 tire pressure monitoring and wheel integrity standards that shape magnesium wheel design validation cycles in the United States. EPA corporate average fuel economy requirements indirectly accelerate magnesium adoption by assigning weight-reduction credits. The EU Green Deal and REACH restrictions on hexavalent chromium surface treatments are forcing European suppliers toward plasma electrolytic oxidation finishes. Stakeholders must monitor evolving FAA airworthiness directives for magnesium alloys in landing gear applications, as certification expansion would unlock substantial aerospace volume.
Market Dynamics
Automakers' mass reduction mandates under NHTSA CAFE standards and EPA emissions frameworks are compressing design cycles for magnesium wheel architectures, forcing alloy specifications toward aerospace-grade fatigue thresholds.
Growth Catalysts
- EPA fuel economy credits:Weight-reduction incentives in the United States accelerate OEM procurement of forged magnesium architectures for performance vehicle lines.
- Germany's motorsport production clusters:Concentrated forging expertise around Stuttgart and Baden-Württemberg anchors premium wheel supply for European automakers.
- Plasma electrolytic oxidation:REACH-compliant surface finishing technologies replace hexavalent chromium treatments, enabling European market access.
Market Restraints
- Magnesium ingot price volatility:Primary magnesium supply concentration in China creates input cost instability for Western forging operations.
- FAA certification timelines:Extended airworthiness qualification protocols for magnesium alloys in landing gear applications delay aerospace volume expansion.
- Aluminum wheel substitution:Cast aluminum designs retain cost advantages in mass-market OEM segments, constraining magnesium penetration below premium tiers.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives for advanced materials manufacturing attract magnesium wheel investment into domestic supply chains.
- Electric vehicle unsprung mass targets:Battery-heavy architectures in EV platforms create new demand for lightweight wheel solutions across premium and mid-market segments.
- MEE-FAA harmonization:Aligned flammability testing protocols between China's Ministry of Ecology and Environment and the FAA compress aerospace qualification pathways.
Industry Challenges
- Aerospace metallurgical certification:Specialized fatigue testing and grain-structure documentation requirements strain quality assurance capacity at mid-tier suppliers.
- Forging press capex intensity:Large-diameter magnesium wheel production requires 8,000-tonne-plus hydraulic presses with limited secondary market availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Wheel Market |
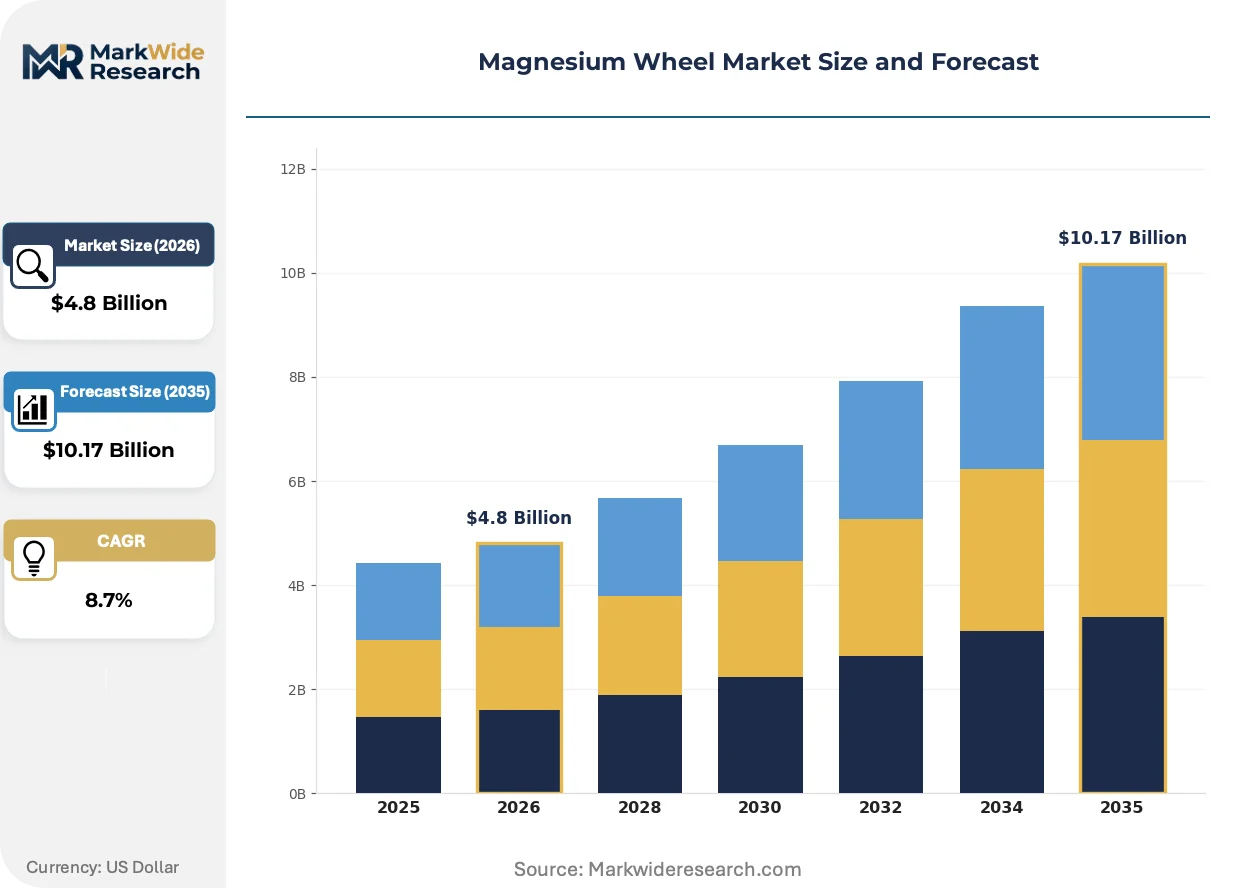
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloy Wheels, Cast Wheels, Forged Wheels, Custom Wheels Application: Automotive, Aerospace, Motorcycle, Sports Equipment End User: OEMs, Aftermarket Retailers, Racing Teams, Enthusiasts Manufacturing Stage: Raw Materials, Design, Production, Quality Control |
| Companies Covered | Rays Engineering Ltd., Forgeline, BBS Kraftfahrzeugtechnik AG, Schmidt Revolution GmbH, American Racing Equipment Inc., OZ Racing, HRE Performance Wheels, Alpina Burkard Bovensiepen GmbH, Enkei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Wheel Market Emerging Trajectories
Material science advances and regulatory harmonization are restructuring competitive advantage around alloy pedigree and surface treatment compliance rather than scale economies alone.
Forging process technology is bifurcating the market between aerospace-grade grain structures and automotive-scale production. Closed-die precision forging with real-time temperature control enables defect rates below 0.5% in motorsport applications. Tier-one suppliers are consolidating around German and Japanese forging heritage while casting operations commoditize at volume.
REACH restrictions on hexavalent chromium surface treatments are mandating plasma electrolytic oxidation and ceramic conversion coatings across European supply chains. ECHA enforcement timelines accelerate supplier transition costs. Wheel finishers with in-house PEO capacity capture margin pools previously held by external plating operations.
Fleet procurement of magnesium wheels for high-performance rental and subscription vehicle programs is compressing traditional retail channel dominance. Direct OEM specification for forged architectures displaces aftermarket distribution in premium segments. This pattern concentrates in Germany and California where performance EV fleets operate at scale.
Magnesium Wheel Market Segmentation
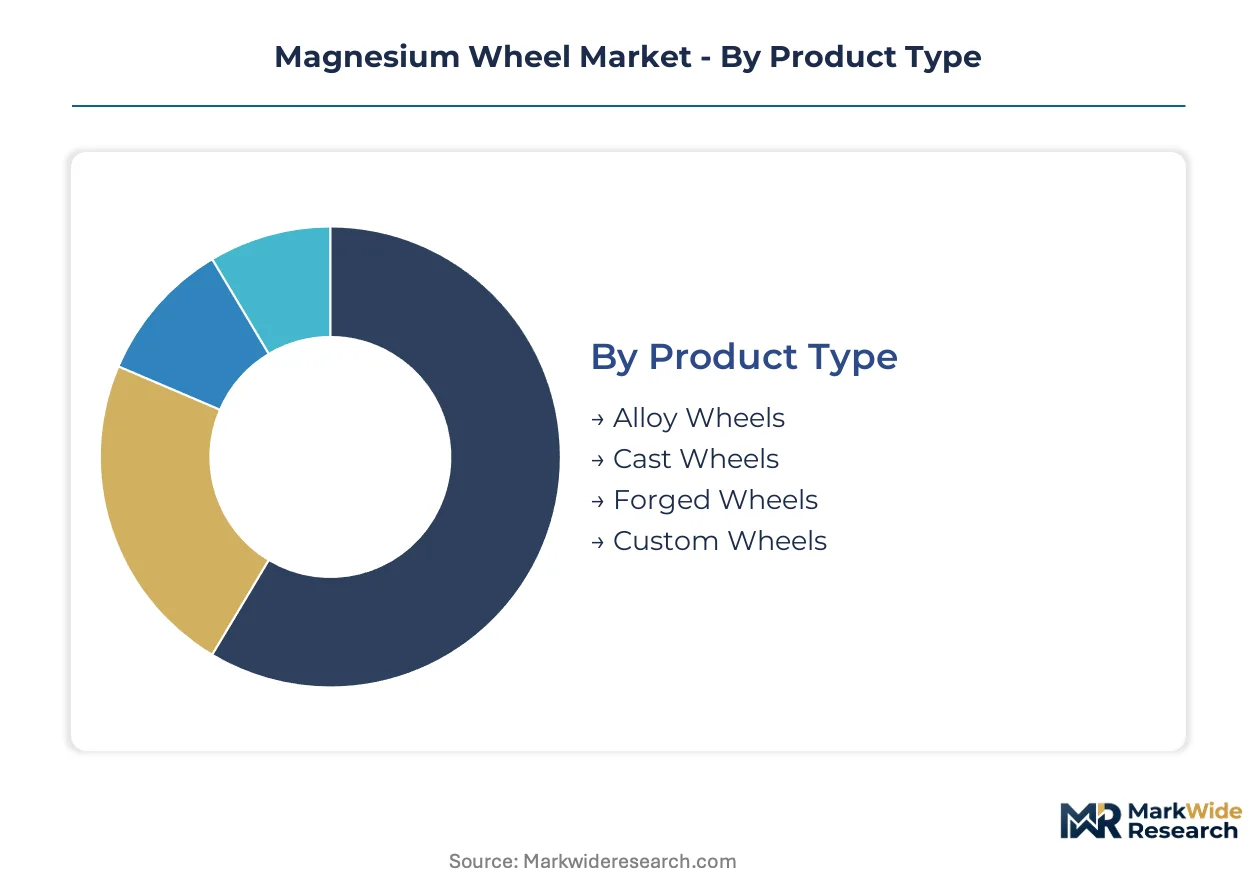
Magnesium wheel segmentation reveals how margin pools concentrate around manufacturing complexity and end-use certification requirements. Product type and application categories show the clearest divergence between volume-scale operations and premium-forged architectures.
Product Type:
Forged wheels command the highest margin pools due to grain-structure integrity and aerospace-grade fatigue thresholds, while cast wheels dominate absolute unit volume through OEM scale economies.
- Forged Wheels:Closed-die precision forging with real-time temperature control achieves defect rates below 0.5% and fatigue thresholds above 120 MPa. Demand concentrates in Germany's motorsport production clusters around Stuttgart, where BBS Kraftfahrzeugtechnik AG serves premium automotive OEM programs under NHTSA wheel integrity standards.
- Cast Wheels:Gravity and low-pressure die casting processes utilize AZ91E magnesium-aluminum-zinc alloys for 25-35% mass reduction versus aluminum. Volume demand centers on mid-market automotive OEMs in China and India seeking EPA fuel economy credit compliance through weight reduction.
- Alloy Wheels:High-strength WE43 and AE44 alloy specifications rotate production toward aerospace-grade material thresholds with enhanced creep resistance.
- Custom Wheels:Bespoke forged configurations serve supercar OEM programs and racing teams requiring application-specific load ratings.
Forged wheels hold installed capacity in European and Japanese forging heritage sites. Cast wheels are rotating up the share rankings in Asian automotive supply chains.
Application:
Automotive applications generate absolute revenue concentration, though aerospace qualification timelines are compressing as MEE and FAA harmonize flammability testing protocols.
- Automotive:OEM procurement of forged magnesium architectures accelerates under NHTSA CAFE standards and EPA emissions frameworks, with weight-reduction credits driving specification in performance vehicle lines. Demand clusters in Germany, Japan, and California where EV unsprung mass targets create new procurement urgency.
- Aerospace:Landing gear applications require specialized fatigue testing and grain-structure documentation under FAA airworthiness directives. Extended certification protocols delay volume expansion, though MEE-FAA alignment is shortening qualification pathways for Chinese and Western suppliers simultaneously.
- Motorcycle:Lightweight wheel solutions target racing and premium street segments where unsprung mass reduction improves handling response.
- Sports Equipment:Bicycle and competitive racing wheel applications leverage magnesium's specific strength advantages in non-regulated consumer markets.
Automotive holds installed capacity across German and Japanese production clusters. Aerospace is climbing the fastest as certification harmonization unlocks new supplier qualification pathways.
End User:
OEM procurement channels are displacing aftermarket distribution in premium segments as fleet operators and subscription vehicle programs compress traditional retail dominance.
- OEMs:Direct specification of forged magnesium wheels for high-performance vehicle lines concentrates procurement power with tier-one automakers pursuing mass reduction targets. EPA fuel economy credits and NHTSA mandates accelerate adoption in United States premium segments.
- Racing Teams:Motorsport applications demand real-time defect monitoring and batch traceability beyond standard automotive quality protocols.
- Aftermarket Retailers:Distribution channels face margin compression as OEM specification expands and fleet procurement centralizes wheel decisions.
- Enthusiasts:Individual procurement persists in custom and restoration segments with lower volume but higher per-unit customization requirements.
OEMs hold installed capacity through long-term supply agreements. Racing teams are gaining share fastest as motorsport certification becomes a pathway to aerospace qualification.
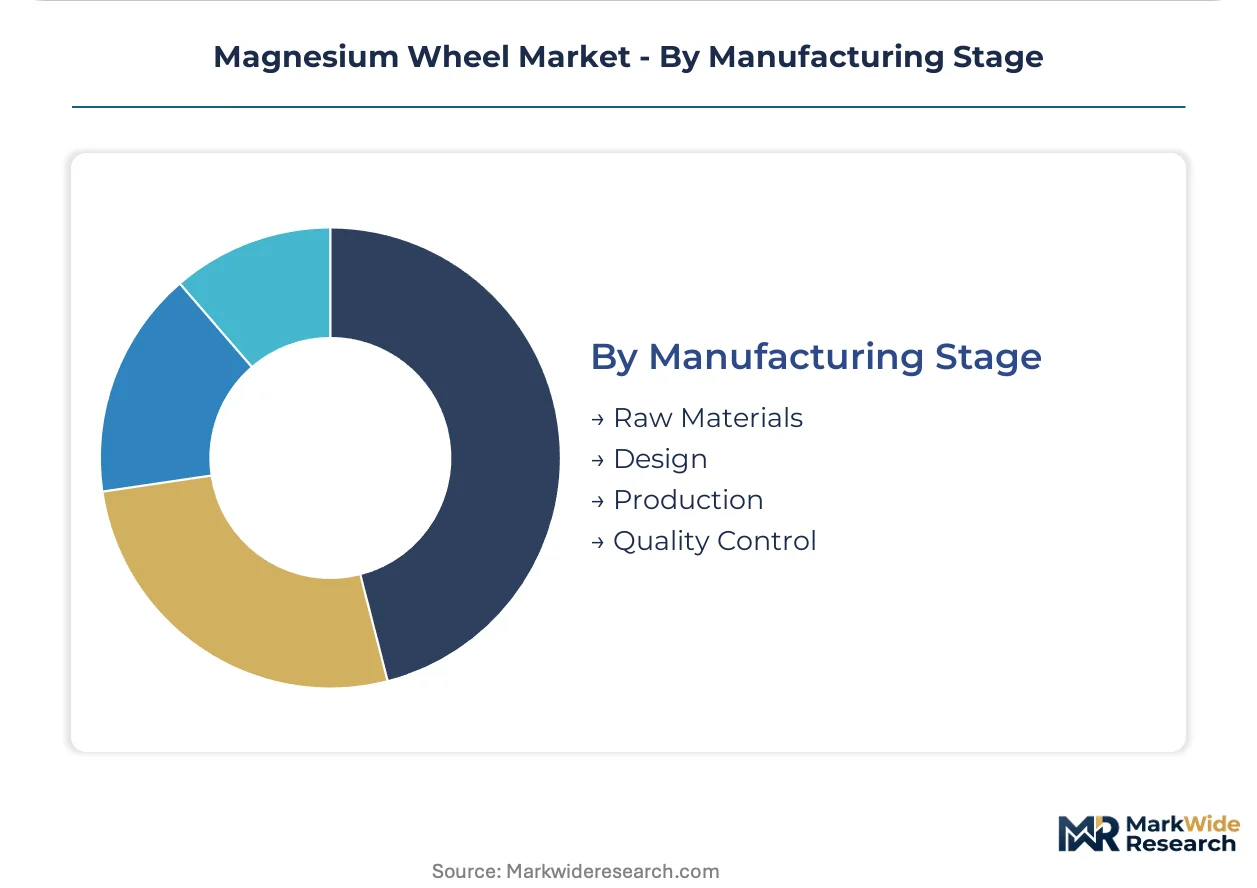
Manufacturing Stage:
Quality control and production stages capture margin concentration through specialized metallurgical certification and forging press capacity constraints.
- Production:Large-diameter magnesium wheel forging requires 8,000-tonne-plus hydraulic presses with limited secondary market availability, creating capacity bottlenecks for mid-tier suppliers.
- Quality Control:Aerospace metallurgical certification demands specialized fatigue testing and grain-structure documentation that strains quality assurance capacity.
- Raw Materials:Primary magnesium supply concentration in China creates input cost instability for Western forging operations.
- Design:CAD-integrated forging simulation and topology optimization reduce material waste and accelerate design validation cycles.
Production holds installed capacity in German and Japanese forging heritage sites. Quality control is rotating up the share rankings as aerospace qualification requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics shape regional positioning in magnesium wheels. China dominates primary magnesium ingot supply, creating input dependencies for Western forging operations. Germany and Japan maintain finished wheel export surpluses through heritage forging expertise.
United States
NHTSA CAFE standards and EPA fuel economy credits accelerate OEM procurement of forged magnesium architectures for performance vehicle lines. The Inflation Reduction Act assigns weight-reduction incentives to domestic EV production. California's premium EV fleet operators centralize procurement decisions, compressing traditional aftermarket channels.
Germany
Baden-Württemberg's motorsport production clusters anchor European supply for premium automotive and racing segments. REACH restrictions on hexavalent chromium surface treatments mandate plasma electrolytic oxidation finishes across supplier networks. Stuttgart-area forging heritage sites command premium margin pools through closed-die precision capabilities.
China
Primary magnesium smelting concentration in Shaanxi and Shanxi provinces creates input cost leverage over Western wheel manufacturers. MEE flammability testing protocols are harmonizing with FAA standards, shortening aerospace qualification pathways. Yangtze River Delta casting operations supply mid-market automotive OEMs seeking mass reduction economies.
Japan
METI industrial policy supports advanced materials manufacturing for automotive lightweighting targets. JIS alloy specifications align with aerospace-grade fatigue thresholds in forging operations. Aichi Prefecture's integrated casting and machining facilities serve Asian OEM supply chains through vertically controlled production.
India
PLI scheme production-linked incentives attract magnesium wheel investment into domestic auto component supply chains. BIS quality standards are evolving to accommodate aerospace-grade alloy specifications. Tamil Nadu and Maharashtra automotive corridors concentrate forging capacity expansion for export-oriented OEM programs.
Magnesium Wheel Market Vendor Landscape
Concentration sits with heritage forging specialists and vertically integrated Asian manufacturers. The vendor base separates into three functional tiers: aerospace-grade precision forgers serving motorsport and supercar OEMs, volume-scale casting operations supplying mid-market automotive programs, and alloy specialists bridging both segments. Strategic moves center on capacity expansion into India's PLI corridors and in-house plasma electrolytic oxidation finishing to capture REACH-compliant margin pools.
Within the heritage-forging tier, BBS Kraftfahrzeugtechnik AG and Schmidt Revolution GmbH exemplify German production cluster dominance, while Enkei Corporation anchors Asian supply through integrated casting and machining operations. These three represent distinct competitive archetypes: European motorsport heritage, specialized forging craftsmanship, and vertically scaled manufacturing.
| Leading Market Players |
|---|
| Rays Engineering Ltd. |
| Forgeline |
| BBS Kraftfahrzeugtechnik AG |
| Schmidt Revolution GmbH |
| American Racing Equipment Inc. |
| OZ Racing |
| HRE Performance Wheels |
| Alpina Burkard Bovensiepen GmbH |
| Enkei Corporation |
| Others |
Supply Flow & Price Mechanics
NHTSA wheel integrity standards gate both supplier qualification and price differentiation simultaneously, forcing tier-one automakers to pay premiums for certified forging capacity while mid-tier suppliers absorb margin compression from extended validation cycles. EPA fuel economy credits amplify this bifurcation by concentrating procurement power with OEMs who can monetize weight-reduction compliance.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on certification grade and volume scale. Price differentiation separates aerospace-grade fatigue documentation from automotive-scale production, with forged architectures commanding substantial premiums over cast alternatives. Cost compression in mid-market casting segments intensifies because aluminum wheel substitution erodes magnesium's value proposition below premium tiers. Fleet operators and subscription vehicle programs exhibit lowest price sensitivity due to centralized procurement decisions, while aftermarket retailers face acute margin pressure from OEM channel displacement.
Supply Chain Analysis
Primary magnesium smelting concentration in Shaanxi and Shanxi provinces creates input leverage over Western forging operations. Raw material supply draws from Chinese ingot producers, German forging heritage sites, and Japanese vertically integrated casting facilities. Single-source vulnerability runs through China's dominance of primary magnesium extraction, exposing Western wheel manufacturers to tariff exposure and commodity price volatility. Distribution feeds from tier-one OEM direct specification channels, with aftermarket retail networks contracting as fleet procurement centralizes wheel decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The magnesium wheel market is recovering from aerospace certification delays as MEE-FAA harmonization compresses qualification timelines and unlocks new volume pathways. This cyclical inflection concentrates margin capture with suppliers possessing in-house plasma electrolytic oxidation capacity and established forging press infrastructure.
For Market Incumbents: Shield margin pools by deepening backward integration into REACH-compliant surface finishing and securing long-term supply agreements with Chinese primary magnesium producers. Aluminum wheel substitution in mass-market segments and extended FAA certification timelines for landing gear applications threaten volume expansion, making in-house PEO capacity the critical defensive lever against European regulatory enforcement. For New Entrants and Emerging Players: MEE-FAA harmonized flammability testing protocols compress aerospace qualification pathways for qualified suppliers. India's PLI scheme corridors offer the most penetrable geography, with Tamil Nadu and Maharashtra automotive corridors concentrating forging capacity expansion for export-oriented OEM programs. Target EV unsprung mass reduction mandates as the primary go-to-market angle, positioning forged architectures for battery-heavy platform procurement. For Investors and Strategic Acquirers: REACH enforcement timelines reshaping the acquisition landscape favor targets with certified PEO finishing capacity and established relationships with Stuttgart-area motorsport production clusters. Long-term viability hinges on aerospace qualification expansion and EV platform penetration across premium and mid-market segments. Monitor FAA airworthiness directive updates for magnesium alloys in landing gear applications as the definitive inflection signal for aerospace volume unlock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PEO Finishing | Captures REACH-compliant margin pools previously held by external plating operations in Germany. |
| Capacity Expansion in India's PLI Corridors | Positions suppliers for export-oriented OEM programs targeting EV unsprung mass reduction mandates. |
| Aerospace Metallurgical Certification Investment | Unlocks FAA landing gear volume as MEE-FAA harmonization shortens qualification pathways. |
| Long-term Magnesium Ingot Supply Agreements | Mitigates Chinese primary supply concentration and input cost volatility for Western forging operations. |
| OEM Direct Specification Partnerships | Displaces aftermarket retail channels as California and German fleet operators centralize procurement. |
Methodological Framework
The analysis maps forged wheel architectures, cast wheel volume operations, aerospace qualification pathways, and surface treatment compliance segments, each validated through procurement directors at tier-one automakers, forging operations managers, regulatory affairs specialists, and aftermarket distribution executives. Primary interview findings triangulate against customs and trade data, NHTSA FMVSS filings, ECHA REACH enforcement documentation, and SEC 10-K disclosures from publicly traded suppliers. Bottom-up alloy specification modeling and top-down OEM procurement volume estimates converge through iterative stakeholder validation.
Consistency checks validate volume and value outputs against IHS Markit vehicle production databases, EPA fuel economy credit utilization reports, and FAA airworthiness directive tracking systems across the projection horizon. The analytical framework models segmentation across manufacturing process, end-use application, alloy specification grade, and regional regulatory cluster. CAGRs derive from compounding annual procurement growth assumptions tied to EV platform rollout schedules and aerospace certification timeline compression, with sensitivity testing around magnesium ingot price volatility and aluminum substitution thresholds.
Decision-makers should treat outputs as directional under base assumptions of sustained NHTSA CAFE enforcement and MEE-FAA regulatory harmonization; material deviation in FAA certification timelines or Chinese export policy would warrant model refresh. Practitioners should keep alternative scenarios live as REACH enforcement intensity and EV unsprung mass target evolution reshape supplier qualification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
Commercial Vehicles Tires Market
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
Saudi Arabia Tire Market
Tires and Wheels
Global Automotive Tires Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Brazil Automotive Tire Market
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Tire Cord Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Automotive All-Season Tire Market
Tires and Wheels
Indirect Tire Pressure Monitoring System Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Tire Bead Wire Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
North Commercial Vehicle Tire Pressure Monitoring Systems Market