
 Automatic Steering System Market | 2026-2036
Automatic Steering System Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Steering System Market Insights
The aftermarket distribution network for steering components is rewriting competitive access rules across emerging automotive hubs. Robert Bosch GmbH leverages its sensor integration capabilities to dominate replacement channels in Europe. ZF Friedrichshafen AG anchors its position through captive supply of rack-and-pinion assemblies to German OEMs. JTEKT Corporation competes on precision manufacturing scale for electric power steering columns.
An automatic steering system integrates electromechanical actuators, torque sensors, and control modules to translate driver or algorithmic input into wheel angle adjustment with millimeter-level accuracy. These systems serve collision avoidance, lane-keeping, and fully autonomous trajectory control in on-highway and off-highway applications. Electronic Power Steering occupies the largest installed base due to its fuel efficiency advantage over hydraulic architectures, while Steer-by-Wire represents the fastest-growing product category as redundancy requirements tighten for Level 4 automation. Autonomous Steering technology commands the highest engineering investment intensity, though Lane Keeping Assist generates broader volume penetration across passenger vehicle segments.
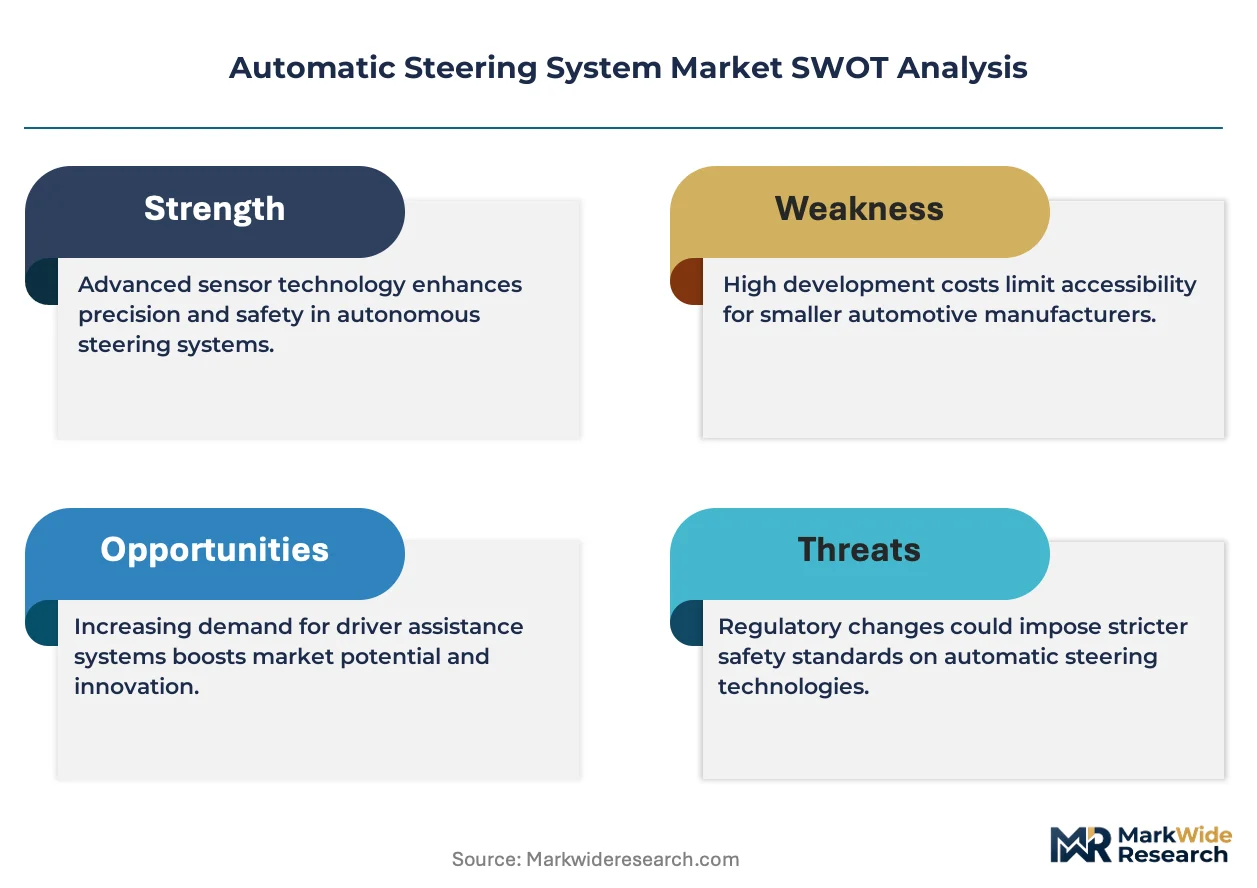
The UN Economic Commission for Europe administers R79 and R157 regulations governing automatic steering and lane-keeping system performance, directly shaping OEM homologation timelines and sensor fusion requirements. The EU AI Act imposes risk-classification obligations on autonomous steering algorithms, compelling suppliers to document decision transparency and fail-safe protocols. The EPA and NHTSA in the United States enforce parallel emissions-linked steering efficiency standards and automated driving system safety assessments. Stakeholders must monitor regulatory divergence between European type-approval frameworks and emerging Chinese GB standards for intelligent connected vehicles.
Market Dynamics
The Automatic Steering System Market is reconfiguring around the UN R157 regulatory mandate for Automated Lane Keeping Systems, which is compressing homologation timelines and forcing Tier-1 suppliers to pre-certify sensor fusion architectures before OEM platform integration begins.
Growth Catalysts
- EU AI Act risk classification:The regulation's high-risk system designation for autonomous steering algorithms is compelling suppliers to document decision transparency protocols, creating first-mover advantage for compliance-ready vendors in German and French OEM supply chains.
- Commercial fleet electrification:Electric power steering architectures deliver fuel efficiency gains that fleet operators in California and Texas are monetizing through EPA emissions credit trading, accelerating replacement cycles in heavy-duty segments.
- Steer-by-Wire redundancy engineering:The technology's elimination of mechanical steering columns enables cabin packaging flexibility that luxury EV manufacturers in Japan are exploiting for interior space differentiation.
Market Restraints
- Rare earth magnet supply concentration:Torque sensor and actuator production depends on neodymium processing concentrated in Chinese refining facilities, exposing European and North American supply chains to export quota volatility.
- UN R79 homologation complexity:The regulation's functional safety requirements for Electronic Power Steering systems extend certification timelines by 18-24 months for non-captive suppliers lacking prior OEM validation relationships.
- Hydraulic steering residual demand:Off-highway construction equipment in emerging markets continues specifying hydraulic architectures due to field-service infrastructure, limiting EPS penetration in agricultural and mining applications.
Strategic Opportunities
- India automotive manufacturing localization:The PLI scheme for advanced automotive technology components is attracting steering system suppliers to establish assembly operations serving domestic OEMs and export markets.
- Sensor fusion convergence:Integration of LiDAR point clouds with steering control modules is creating new value pools for suppliers possessing both hardware and algorithmic capabilities.
- Aftermarket channel digitization:E-commerce platforms for replacement steering components are bypassing traditional distributor markups in Brazilian and Mexican independent repair sectors.
Industry Challenges
- Functional safety engineering talent scarcity:ISO 26262 certification expertise is concentrated among senior engineers at German and Japanese Tier-1s, constraining expansion capacity at mid-tier suppliers.
- Legacy vehicle integration complexity:Retrofitting automatic steering capabilities onto platforms lacking CAN-FD bandwidth requires gateway module redevelopment that consumes disproportionate R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Steering System Market |
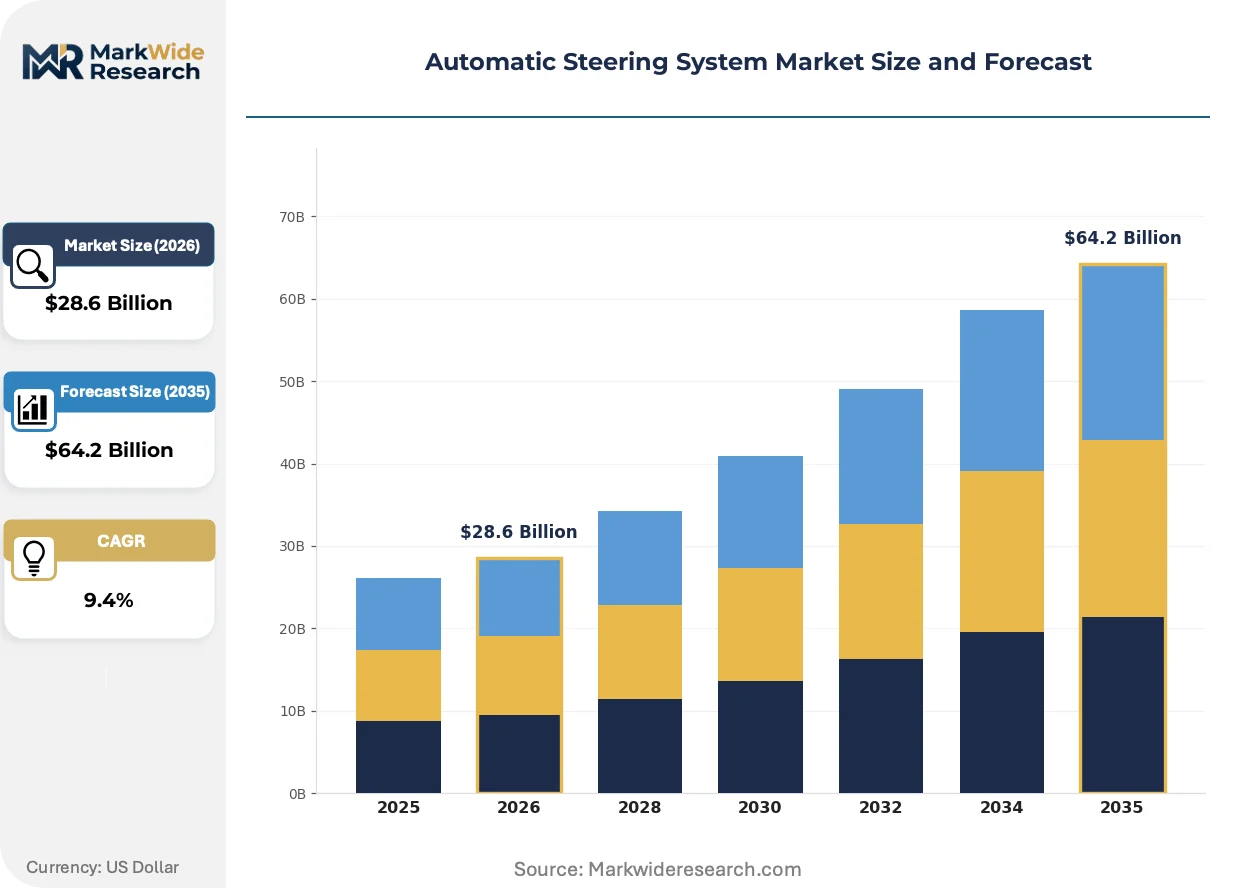
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Power Steering, Hydraulic Steering, Hybrid Steering, Steer-by-Wire Technology: Active Steering, Adaptive Steering, Lane Keeping Assist, Autonomous Steering End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy Machinery Installation: OEM Installation, Aftermarket Installation, Retrofitting, Integration with Autonomous Systems |
| Companies Covered | ZF Friedrichshafen AG, JTEKT Corporation, Robert Bosch GmbH, Nexteer Automotive, NSK Ltd, DENSO Corporation, Mando Corporation, Hyundai Mobis, Trimble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Steering System Market Trends and Innovations
Software-defined steering architectures are dissolving the traditional boundary between mechanical hardware and electronic control, enabling over-the-air calibration updates that alter vehicle handling characteristics without physical component replacement.
Steer-by-Wire systems are digitizing the final mechanical link between driver input and wheel articulation, replacing column shafts with redundant electromechanical actuators. Premium EV manufacturers in Germany and California are deploying this architecture for packaging and crash safety advantages. The technology is digitizing supplier value capture from hardware sales toward software licensing and feature subscription models.
The EU AI Act's high-risk system obligations are mandating algorithmic explainability documentation for autonomous steering functions, forcing engineering teams to retrofit decision-logging capabilities into legacy control architectures. Suppliers serving Stellantis and Volkswagen Group platforms are absorbing compliance costs through dedicated AI governance functions. Lane-keeping and automated parking systems face the steepest documentation burdens under the Act's conformity assessment procedures.
Fleet procurement managers are consolidating steering system sourcing through vehicle-as-a-service contracts that bundle hardware, maintenance, and software updates into per-mile pricing. This model is displacing component-level purchasing in North American commercial vehicle segments. California-based logistics operators are piloting these arrangements for Class 8 tractor units with automated lane-keeping capabilities.
Automatic Steering System Market Segmentation
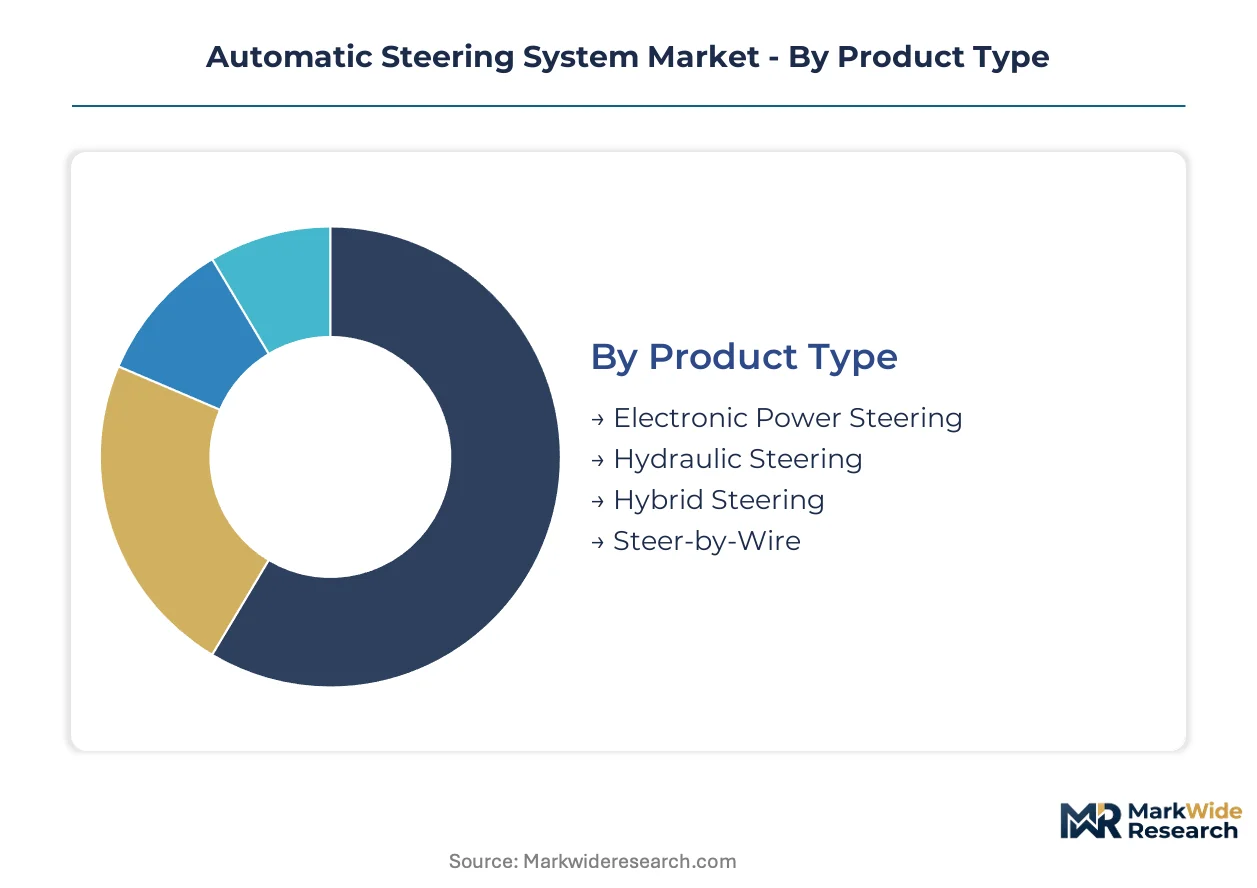
Automatic steering systems fragment across hardware architectures, control intelligence levels, and customer procurement patterns. Each dimension carries distinct margin profiles and replacement cycle dynamics that reshape supplier resource allocation.
Product Type:
Replacement cycles stretch from 8-12 years for hydraulic architectures to 3-5 years for software-intensive steer-by-wire modules, compressing revenue recognition timelines for advanced product lines.
- Electronic Power Steering:Brushless motor-driven rack assist architectures dominate passenger vehicle production due to 3-4% fuel efficiency gains over hydraulic alternatives. Fleet operators in California monetize these savings through EPA emissions credit trading, accelerating retrofit demand in medium-duty segments. EPS dominates installed base. Steer-by-Wire is where expansion concentrates.
- Hydraulic Steering:Engine-driven pump systems with recirculating ball or rack-and-pinion linkages persist in off-highway equipment where field-service infrastructure supports mineral oil maintenance. Mining operators in Western Australia specify these architectures for ambient temperature resilience above 50°C, constraining electrification timelines in heavy industrial applications.
- Hybrid Steering:Dual-mode architectures combine electric assist with hydraulic backup for commercial vehicle redundancy requirements. Demand clusters in German long-haul trucking where UN R79 mandates functional safety redundancy.
- Steer-by-Wire:Fully electronic actuation eliminating mechanical steering columns enables cabin packaging flexibility that luxury EV manufacturers exploit for interior space differentiation. Redundant sensor arrays and ISO 26262 ASIL-D certification requirements extend development cycles to 36-48 months.
Electronic Power Steering dominates installed base. Steer-by-Wire is where expansion concentrates.
Technology:
Cost tiers stratify sharply, with Lane Keeping Assist modules priced 60-70% below Autonomous Steering systems requiring LiDAR fusion and triple-redundant compute.
- Active Steering:Variable ratio systems modulate steering response based on vehicle speed, tightening ratios at parking speeds for maneuverability. BMW and Mercedes-Benz deploy these systems in executive sedans where urban parking frequency justifies hardware cost premiums.
- Adaptive Steering:Learning algorithms adjust assist levels based on driver behavior patterns and road surface conditions. Japanese OEMs integrate these functions with camera-based road condition detection for highway comfort differentiation.
- Lane Keeping Assist:Camera-centered lane departure warning with corrective torque application generates the broadest volume penetration across mass-market passenger segments. Regulatory mandates in Germany and Japan accelerate standard-fit adoption in compact vehicle classes. Lane Keeping Assist dominates installed base. Autonomous Steering is where expansion concentrates.
- Autonomous Steering:Full trajectory planning with sensor fusion across radar, LiDAR, and camera inputs commands the highest engineering investment intensity. UN R157 compliance for Automated Lane Keeping Systems compresses homologation timelines and forces pre-certification of sensor fusion architectures.
Lane Keeping Assist dominates installed base. Autonomous Steering is where expansion concentrates.
End User:
Volume concentration tilts toward passenger vehicles, but margin extraction concentrates in commercial fleet contracts bundling hardware with predictive maintenance software.
- Passenger Vehicles:Mass-market sedans and SUVs generate the largest absolute unit demand, with EPS penetration exceeding 90% in developed markets. Electrification mandates in California and the EU accelerate replacement of residual hydraulic systems in entry segments.
- Commercial Vehicles:Class 8 tractors and delivery vans drive fleet procurement consolidation through vehicle-as-a-service contracts. California-based logistics operators pilot per-mile pricing models that bundle automated lane-keeping capabilities with maintenance obligations. Commercial Vehicles dominate installed base. Heavy Machinery is where expansion concentrates.
- Two-Wheelers:Electric scooter and motorcycle applications deploy compact EPS units for urban maneuverability, with Indian and Southeast Asian OEMs driving cost-down requirements through high-volume sourcing.
- Heavy Machinery:Construction and mining equipment specify ruggedized steering actuators with IP6K9K sealing for dust and pressure-wash resistance. Autonomous haulage trials in Western Australian iron ore operations validate steer-by-wire architectures for 24/7 unmanned operation.
Passenger Vehicles dominate installed base. Heavy Machinery is where expansion concentrates.
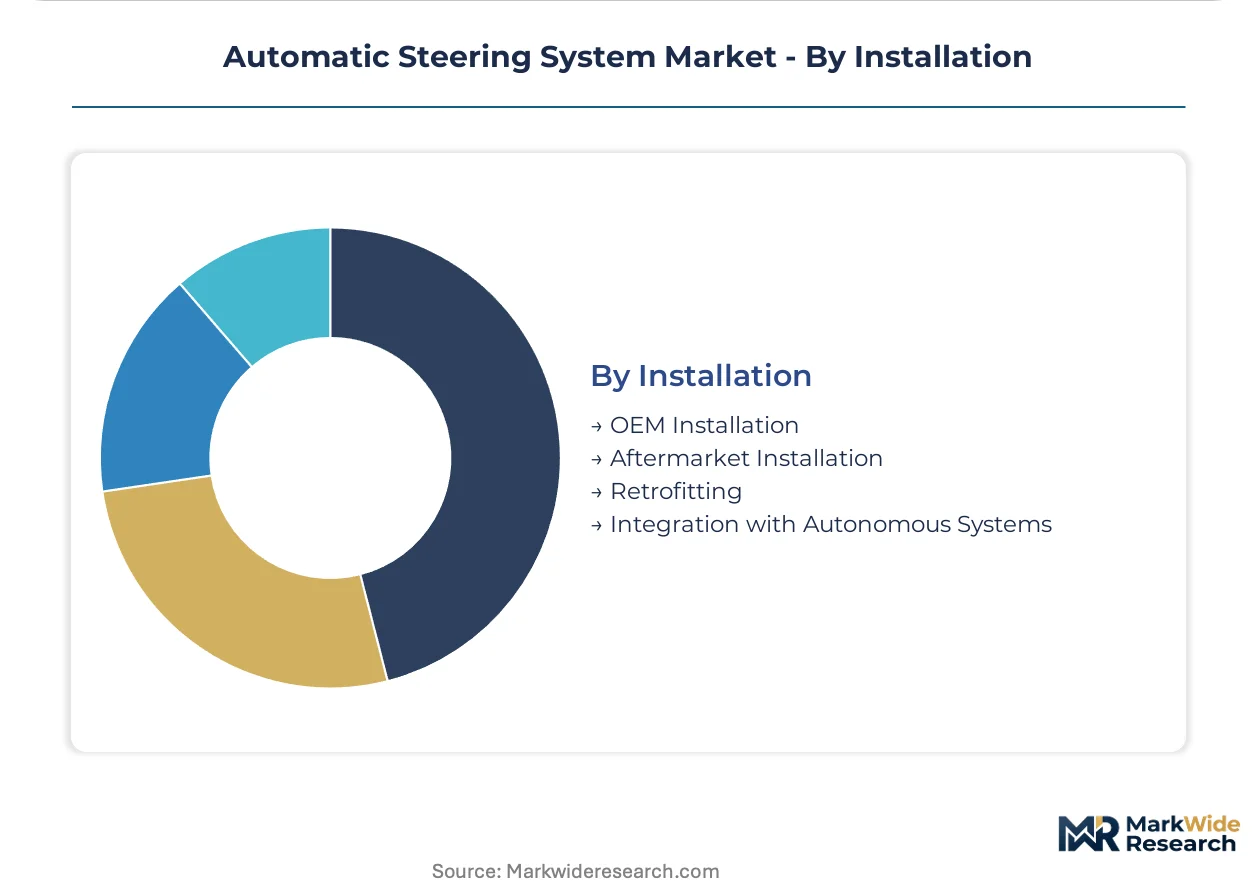
Installation:
Channel economics diverge sharply, with OEM captive supply locking in 7-10 year platform commitments while aftermarket digitization erodes traditional distributor markups.
- OEM Installation:Tier-1 suppliers contract directly with vehicle manufacturers for platform-specific steering system development, with German and Japanese OEMs maintaining longest-standing validation relationships. Robert Bosch GmbH and ZF Friedrichshafen AG anchor European supply through multi-generational contracts.
- Aftermarket Installation:Independent repair channels in Brazil and Mexico face e-commerce platform disruption as direct-to-installer procurement bypasses traditional distributor networks. Sensor calibration requirements for EPS systems constrain true DIY penetration.
- Retrofitting:Legacy vehicle integration demands gateway module redevelopment for CAN-FD bandwidth conversion, consuming disproportionate R&D resources relative to unit economics. California fleet operators retrofit Class 8 tractors for automated lane-keeping compliance. OEM Installation dominates installed base. Integration with Autonomous Systems is where expansion concentrates.
- Integration with Autonomous Systems:Full-stack autonomous vehicle programs require steering system suppliers to deliver ASIL-D certified actuators with deterministic latency below 10 milliseconds. Waymo and Cruise qualification programs in Arizona and California validate supplier capabilities for Level 4 deployment.
OEM Installation dominates installed base. Integration with Autonomous Systems is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's automotive component export corridor, channeling precision steering assemblies to assembly plants across Northern Europe and beyond.
United States
California fleet operators pilot per-mile pricing for Class 8 tractors with automated lane-keeping. NHTSA enforces automated driving system safety assessments that compress supplier validation timelines. Detroit-Warren-Dearborn MSA concentrates OEM engineering centers where Tier-1 suppliers co-locate for platform development.
Germany
Long-haul trucking mandates under UN R79 accelerate hybrid steering adoption for functional safety redundancy. KBA administers type-approval frameworks that pre-certify sensor fusion architectures before OEM integration. Stuttgart and Munich anchor development clusters where Robert Bosch GmbH and ZF Friedrichshafen AG maintain multi-generational validation relationships.
Japan
Luxury EV manufacturers exploit steer-by-wire cabin packaging flexibility for interior space differentiation. METI oversees JIS standards harmonization with UN R157 lane-keeping performance requirements. Nagoya-Toyota corridor concentrates precision manufacturing scale for electric power steering columns.
India
Domestic OEMs and export markets attract steering system assembly under the PLI scheme for advanced automotive technology components. BIS implements intelligent connected vehicle standards that diverge from European type-approval frameworks. Tamil Nadu and Gujarat host emerging manufacturing nodes serving Southeast Asian aftermarket channels.
China
Neodymium refining concentration for torque sensor production exposes supply chains to export quota volatility. GB standards for intelligent connected vehicles create regulatory divergence from UN Economic Commission for Europe frameworks. Yangtze River Delta clusters integrate LiDAR point clouds with steering control modules for autonomous vehicle programs.
Automatic Steering System Market Competitive Landscape
On the supply side, the industry is consolidating around sensor integration capabilities and captive OEM relationships. Tier-1 suppliers with multi-generational platform contracts dominate volume allocation, while mid-tier specialists compete on aftermarket channel access. Two strategic archetypes prevail: integrated electromechanical actuator manufacturers and sensor fusion algorithm developers. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers pre-certify architectures ahead of UN R157 homologation deadlines.
Within the integrated actuator tier, ZF Friedrichshafen AG exemplifies the German engineering-centric model through its rack-and-pinion captive supply position. JTEKT Corporation represents Japanese precision manufacturing scale for steering column architectures. Robert Bosch GmbH anchors European aftermarket distribution through sensor integration capabilities that span replacement channels.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| JTEKT Corporation |
| Robert Bosch GmbH |
| Nexteer Automotive |
| NSK Ltd |
| DENSO Corporation |
| Mando Corporation |
| Hyundai Mobis |
| Trimble |
| Others |
Pricing and Supply Chain Analysis
Neodymium refining concentration in Chinese processing facilities anchors torque sensor and actuator production costs, concentrating margin capture downstream with Tier-1 suppliers possessing captive OEM relationships. This upstream chokepoint feeds directly into pricing power stratification across steering system tiers.
Pricing Analysis
Volume-discount tiering separates ASIL-D certified steer-by-wire modules from standard EPS units, with certification grade and fleet contract scale driving price differentiation. Three-tier pricing structure across premium steer-by-wire, standard EPS, and residual hydraulic architectures reflects engineering investment intensity. Pricing pressure stems from fleet procurement consolidation through vehicle-as-a-service contracts bundling hardware with predictive maintenance. Commercial vehicle operators exhibit highest price sensitivity due to per-mile cost accounting, while luxury EV manufacturers prioritize cabin packaging flexibility over unit economics.
Supply Chain Analysis
Robert Bosch GmbH, ZF Friedrichshafen AG, and JTEKT Corporation hold dominant contract-manufacturing capacity for precision electromechanical actuators across Germany, Japan, and China. Rare earth magnet supply draws from Chinese refining facilities, with torque sensors and brushless motors sourcing neodymium and dysprosium. Single-source vulnerability in rare earth processing exposes European and North American supply chains to export quota volatility. Distribution runs through OEM captive supply agreements locking 7-10 year platform commitments, alongside aftermarket digitization eroding traditional distributor markups in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic steering system market sits in early-cycle expansion as UN R157 homologation mandates compress adoption timelines across commercial fleet segments. Steer-by-wire penetration in luxury EV platforms signals technology maturation ahead of broader volume deployment.
For Market Incumbents: Entrench multi-generational validation relationships with German and Japanese OEMs through pre-certified sensor fusion architectures ahead of homologation deadlines. Deepen captive supply positions in rack-and-pinion assemblies to defend against emerging Chinese LiDAR-steering integration specialists. Prioritize ISO 26262 ASIL-D certification investment as the primary lever for platform lock-in.
For New Entrants and Emerging Players: India's Tamil Nadu and Gujarat manufacturing corridors offer underpenetrated assembly capacity serving domestic OEMs and Southeast Asian aftermarket channels. Target heavy machinery autonomous haulage trials in Western Australian mining operations where ruggedized steer-by-wire demand outpaces established supplier coverage. Pursue sensor fusion algorithm licensing as the go-to-market angle bypassing capital-intensive actuator manufacturing.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier specialists possessing ISO 26262 certification expertise and existing OEM validation relationships rather than greenfield technology development. Long-term viability hinges on regulatory compliance moats widening through EU AI Act documentation requirements. Watch fleet vehicle-as-a-service contract penetration rates as the inflection signal for steer-by-wire volume scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Pre-certifies sensor fusion architectures for UN R157 homologation ahead of OEM platform integration. |
| Rare Earth Magnet Supply Agreement | Secures neodymium processing allocation from Chinese refiners mitigating export quota volatility exposure. |
| Vehicle-as-a-Service Partnership | Bundles steer-by-wire hardware with predictive maintenance software for California Class 8 fleet operators. |
| India PLI Scheme Manufacturing Footprint | Establishes assembly operations in Tamil Nadu serving domestic OEMs and Southeast Asian export markets. |
| LiDAR-Steering Control Integration | Captures value pools from autonomous vehicle programs requiring sub-10 millisecond deterministic latency. |
Research Methodology
Operator-level perspectives from Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and fleet operations directors anchored the qualitative base. Primary interview insights combined with secondary validation from UN ECE regulatory filings, EPA emissions credit trading records, vehicle production databases, and IHS Markit registration data. Bottom-up unit demand modeling triangulated against top-down market sizing across technology and end-user segments.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product architecture, control intelligence level, end-user procurement pattern, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating technology substitution rates, fleet electrification timelines, and homologation deadline impacts. Forecast inputs included neodymium price volatility indices and commercial vehicle miles-traveled projections.
Practitioners should monitor rare earth export quota announcements, UN R157 pre-certification completion rates, and fleet VaaS contract signings for early signals of forecast revision. Quarterly review of ASIL-D certification backlogs and steer-by-wire platform launch delays is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Autonomous Navigation Sensing System Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
North America Autonomous Navigation Market
Autonomous Vehicles
Autonomous Commercial Vehicles Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Autonomous Vehicle Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Singapore Autonomous Navigation Market
Autonomous Vehicles
Autonomous Taxi Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Self-Driving Cars and Trucks Market
Autonomous Vehicles
Battery-Electric Self-Driving Car Market
Autonomous Vehicles
China Autonomous Navigation Market