
 Autonomous Ride-Sharing Services Market | 2026-2036
Autonomous Ride-Sharing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Ride-Sharing Services Market Outlook
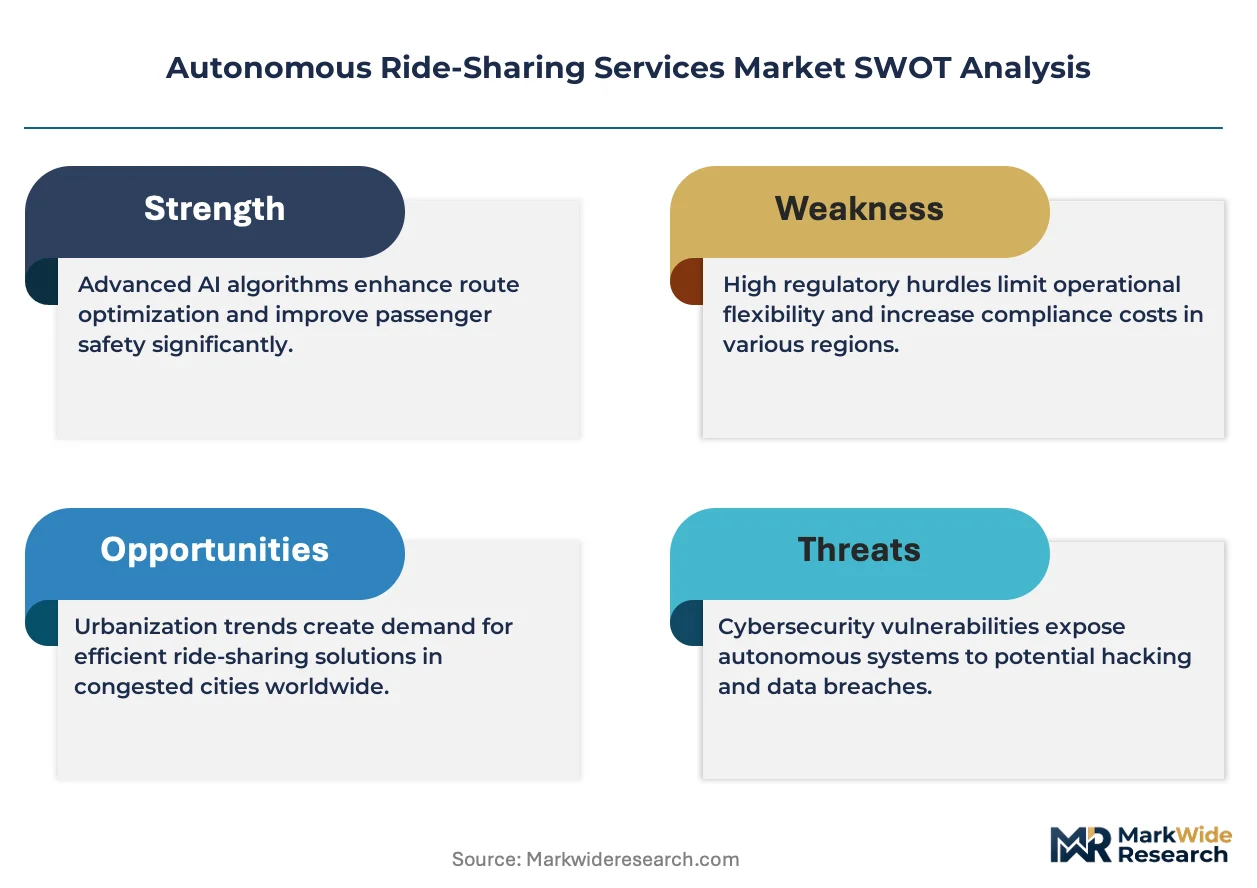
Corporate fleet managers and institutional transit buyers are gaining share as private consumer adoption is bifurcating between price-sensitive occasional users and high-frequency commuters. Waymo LLC leverages its vertically integrated sensor stack to sustain operational cost advantages across Phoenix and San Francisco. Baidu Apollo anchors its position through extensive mapping infrastructure and municipal partnerships in Chinese megacities. Zoox Inc. differentiates via purpose-built bi-directional vehicle architecture designed exclusively for dense urban ride-sharing.
Autonomous ride-sharing services deploy self-driving vehicles through centralized dispatch platforms that integrate lidar, radar, and camera perception stacks with real-time route optimization algorithms operating at sub-50-millisecond latency. On-demand service type dominates current transaction volume, though subscription models capture superior unit economics and customer lifetime value. Pooling services exhibit the fastest expansion trajectory as algorithms improve multi-passenger routing efficiency. Passenger cars constitute the primary vehicle type deployed, while van segments attract growing interest from airport and corporate campus operators seeking higher per-trip capacity.
The NHTSA in the United States, the EU AI Act and CE marking requirements in Europe, and MIIT autonomous vehicle standards in China collectively establish the compliance perimeter for commercial deployment, with safety validation protocols directly determining market entry timelines. The FAA maintains oversight for emerging air taxi integrations that several operators now pilot. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of capital allocation and partnership strategy.
Market Dynamics
Algorithmic route optimization at sub-50-millisecond latency is compressing fleet operating costs and redrawing competitive boundaries between centralized dispatch platforms and legacy taxi networks.
Growth Catalysts
- EU AI Act compliance frameworks:Standardized safety validation protocols across European testing corridors are accelerating operator licensing timelines and reducing regulatory uncertainty for fleet deployments.
- Lidar sensor cost curves:Solid-state lidar manufacturing scale-up is collapsing per-unit hardware expenses and enabling economically viable robotaxi density in urban cores.
- Municipal transit agency procurement:Public-private partnerships for first-mile-last-mile connectivity are generating dedicated lane access and preferential curb allocation in Chinese and German megacities.
Market Restraints
- High-definition mapping dependency:Proprietary map maintenance requirements lock operators into continuous data collection expenditures that scale with fleet geography.
- Edge case liability exposure:NHTSA incident reporting mandates create open-ended legal frameworks that delay insurer participation and inflate per-mile coverage costs.
- Remote operator labor pools:Teleoperation fallback systems require trained human monitors, constraining 24/7 service availability in markets with tight technical labor supply.
Strategic Opportunities
- Airport ground transportation:Fixed-route, geofenced campus environments offer contained operational domains with predictable demand patterns and premium pricing tolerance.
- Subscription mobility bundles:Monthly fixed-fee models integrating autonomous ride-sharing with public transit passes are capturing superior customer lifetime value versus per-trip pricing.
- Pooling algorithm maturation:Dynamic multi-passenger routing is opening shared-ride economics that undercut single-occupancy vehicle ownership in dense metropolitan corridors.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 certification expertise concentrates at Tier-1 automotive suppliers, forcing operators to compete for limited validation talent.
- Vehicle-to-infrastructure integration:Legacy traffic signal systems lack standardized V2X communication protocols, requiring costly municipal retrofit coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Ride-Sharing Services Market |
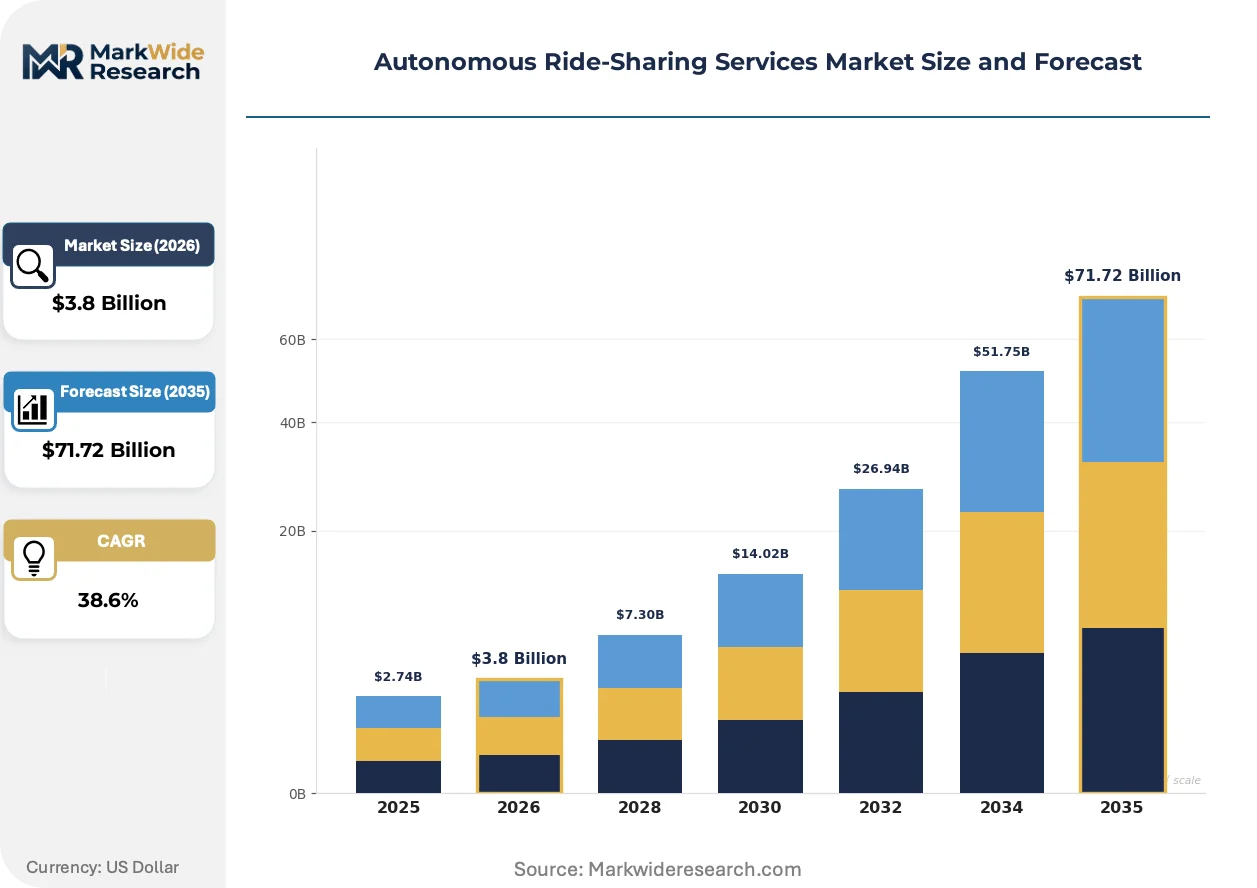
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $71.72 Billion |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Demand, Pooling, Subscription, Corporate Vehicle Type: Passenger Cars, Vans, Buses, SUVs Platform: Mobile App, Web Portal, API Integration, Embedded Systems End User: Private Users, Companies, Institutions, Government |
| Companies Covered | Waymo LLC, Baidu Apollo, Cruise LLC, Zoox Inc., Motional, Pony.ai, AutoX, Aurora Innovation Inc, WeRide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Ride-Sharing Services Market Strategic Shifts
Perception stack architectures are fragmenting as camera-first approaches challenge multi-sensor fusion, while regulatory sandboxes in key jurisdictions compress commercialization timelines for qualified operators.
Camera-dominant perception systems leveraging transformer-based neural networks are displacing lidar-heavy configurations in controlled operational design domains. Fleet operators in Phoenix and San Francisco are deploying vision-primary stacks for highway and suburban scenarios, reducing hardware bill-of-materials by eliminating rotating sensor heads. This sensor simplification is compressing maintenance intervals and enabling faster vehicle turnaround between shifts.
The EU AI Act's risk-based classification system for autonomous transport is mandating conformity assessment procedures that favor established automotive suppliers over software-native entrants. European operators must document training data provenance and algorithmic decision logic, creating compliance overhead that advantages vertically integrated hardware-software stacks. German testing corridors are responding with dedicated regulatory liaison offices to streamline certification pathways.
Corporate campus shuttle procurement is migrating from capital purchase toward mobility-as-a-service contracts with guaranteed uptime service level agreements. Facility managers at technology parks and hospital complexes are unbundling vehicle ownership from operational responsibility, transferring fleet management to specialized autonomous operators. This shift is most visible in the United States, where property developers embed ride-sharing access into lease agreements as amenity differentiation.
Autonomous Ride-Sharing Services Market Segmentation
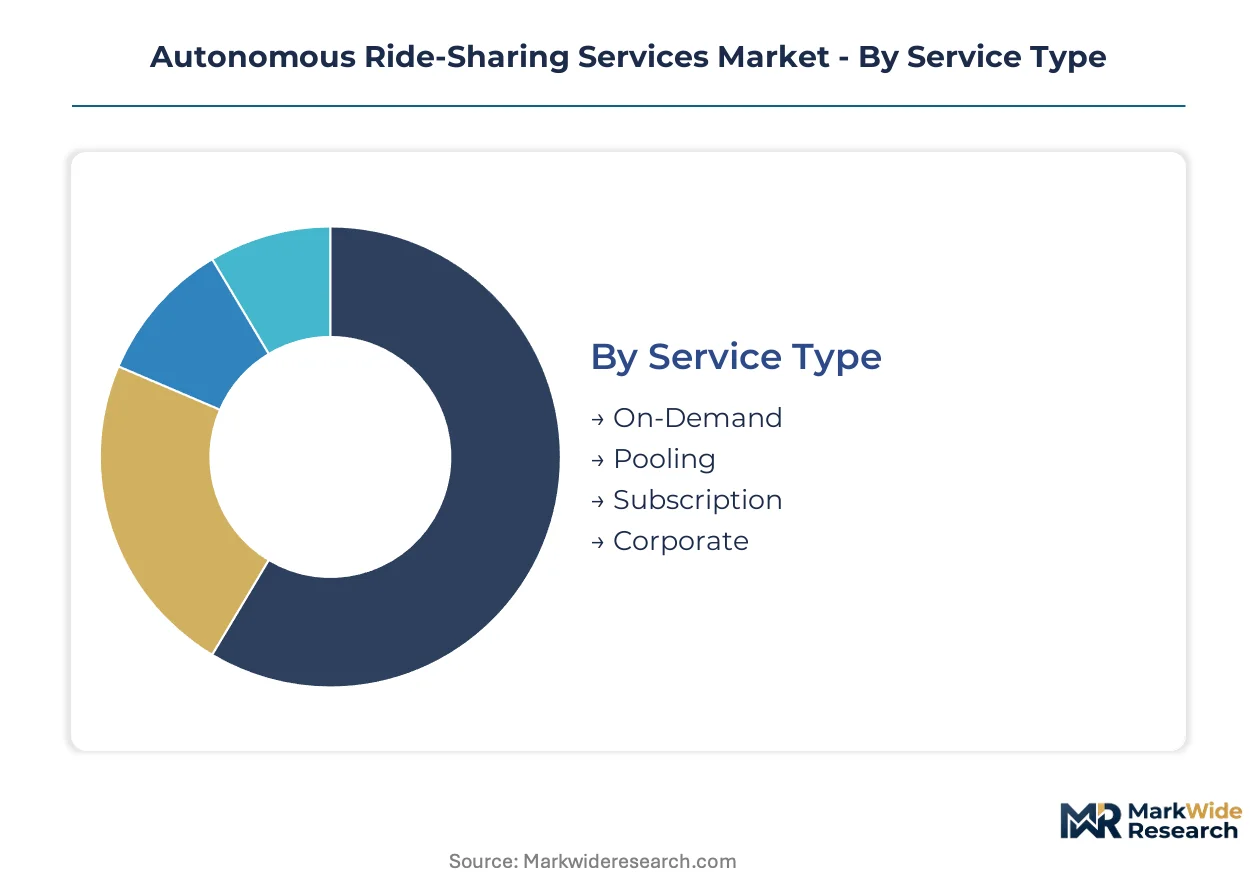
Segmentation in autonomous ride-sharing services determines capital allocation, fleet composition, and regulatory compliance pathways. Each dimension shapes how operators configure dispatch algorithms, negotiate municipal partnerships, and structure pricing models.
Service Type:
NHTSA incident reporting thresholds and EU AI Act risk classifications create divergent compliance burdens across service modalities.
- On-Demand:Immediate dispatch through mobile interfaces dominates transaction volume in Phoenix and San Francisco corridors. Fleet operators compress wait times below three minutes through predictive positioning algorithms, though per-mile economics struggle against pooling alternatives in dense Chinese megacities.
- Pooling:Multi-passenger routing algorithms match riders with sub-50-millisecond latency, collapsing per-seat costs below single-occupancy thresholds. Municipal transit agencies in Germany prioritize pooled services for first-mile-last-mile connectivity, securing dedicated lane access as procurement condition.
- Subscription:Monthly fixed-fee bundles integrate with public transit passes, capturing superior customer lifetime value through predictable utilization patterns.
- Corporate:Guaranteed uptime service level agreements transfer fleet management risk from campus facility managers to specialized operators.
On-Demand handles the majority of throughput; Pooling is climbing the fastest on share.
Vehicle Type:
Hardware bill-of-materials and sensor maintenance intervals stratify fleet economics across form factors.
- Passenger Cars:Sedan and hatchback configurations anchor urban robotaxi deployments, with solid-state lidar integration collapsing per-unit sensor costs. Waymo and Baidu Apollo concentrate passenger car density in operational design domains spanning Arizona, California, and Chinese testing corridors.
- Vans:Higher per-trip capacity attracts airport ground transportation operators and corporate campus managers seeking premium pricing tolerance in contained geofenced environments.
- Buses:Fixed-route shuttle configurations serve first-mile-last-mile connectivity contracts with municipal transit agencies.
- SUVs:Elevated seating positions and expanded cargo capacity address accessibility requirements and luggage-intensive airport segments.
Passenger Cars absorb the dominant capital deployment; Vans show the steepest expansion trajectory among commercial buyers.
Platform:
Dispatch latency and integration architecture determine operator competitiveness against legacy ride-hailing networks.
- Mobile App:Consumer-facing interfaces with real-time vehicle tracking and dynamic pricing dominate private user acquisition in United States and Chinese markets.
- Web Portal:Corporate travel managers and institutional procurement officers prefer browser-based booking with centralized billing reconciliation.
- API Integration:Direct system-to-system connectivity enables travel management companies and hospitality platforms to embed autonomous ride-sharing into broader mobility bundles.
- Embedded Systems:Vehicle-native dispatch without intermediary devices supports accessibility-focused deployments and reduced smartphone dependency.
Mobile App captures the private consumer base; API Integration is gaining share fastest among enterprise technology stacks.
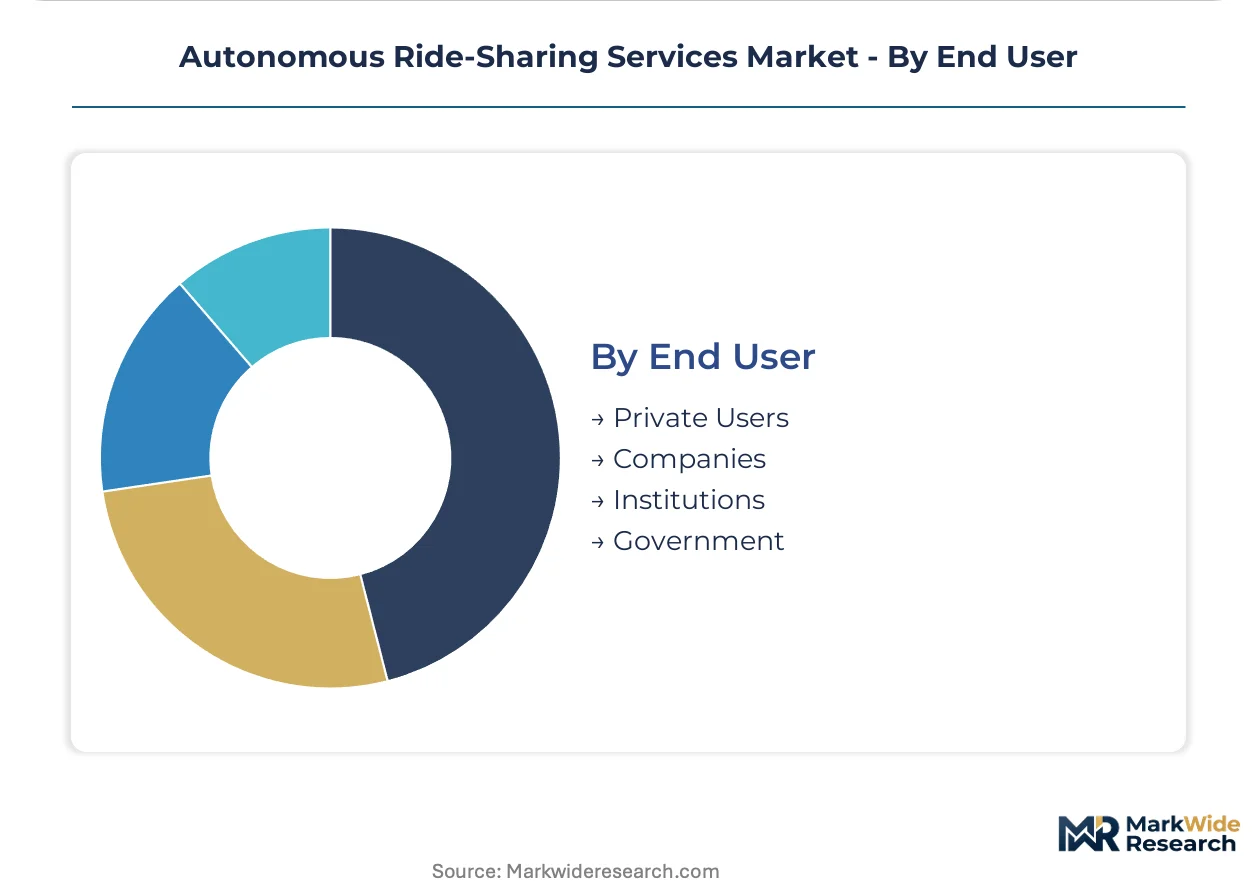
End User:
Procurement authority and risk tolerance differentiate buyer segments across municipal, corporate, and individual demand pools.
- Private Users:Individual consumers bifurcate between price-sensitive occasional riders and high-frequency commuters seeking subscription bundles. German and Chinese megacities show strongest density among daily-use subscribers.
- Companies:Technology parks and hospital complexes in the United States are unbundling vehicle ownership from operational responsibility, embedding ride-sharing access into lease agreements as amenity differentiation.
- Institutions:University campuses and medical centers specify guaranteed uptime SLAs, transferring fleet management to specialized autonomous operators with dedicated maintenance protocols.
- Government:Municipal transit agencies in China and Germany generate preferential curb allocation and dedicated lane access through public-private partnership structures.
Private Users generate the highest transaction velocity; Government procurement is expanding most quickly as fiscal frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate Highway System and municipal fiber backbones in the United States anchor early commercial density, while China's 5G-enabled smart city corridors and Germany's autobahn testing infrastructure accelerate parallel deployment tracks.
United States
Waymo and Cruise concentrate robotaxi operations across Phoenix and San Francisco, leveraging NHTSA autonomous vehicle guidelines to compress licensing timelines. The FAA maintains oversight for emerging air taxi integrations that several operators now pilot. California's regulatory sandbox generates preferential curb allocation for pooled services in dense metropolitan corridors.
China
Baidu Apollo and Pony.ai deploy across Beijing and Shanghai megacities, exploiting MIIT autonomous vehicle standards and extensive mapping infrastructure. Municipal transit agencies generate dedicated lane access through public-private partnership structures. The Yangtze River Delta cluster exhibits the strongest operational density for van-based airport ground transportation.
Germany
The EU AI Act's risk-based classification system mandates conformity assessment procedures favoring established automotive suppliers. German testing corridors maintain dedicated regulatory liaison offices to streamline certification pathways. Munich and Stuttgart anchor fleet deployments targeting corporate campus shuttle procurement with guaranteed uptime service level agreements.
United Kingdom
London's congestion charging zone creates pricing tolerance for premium autonomous services targeting financial district commuters. The national transport regulator coordinates with local authorities on geofenced operational design domains. Cambridge and Oxford host validation partnerships between university research clusters and Tier-1 automotive suppliers.
Japan
METI funding frameworks support robotaxi pilots in Tokyo and Osaka metropolitan areas, with Olympic corridor infrastructure repurposed for commercial testing. The country's national automotive regulator coordinates functional safety validation with ISO 26262 certification requirements. Nagoya's industrial belt concentrates lidar sensor manufacturing scale-up for solid-state cost reduction.
Autonomous Ride-Sharing Services Market Competitive Environment
Listed leaders compete with private specialists across capital access and regulatory navigation, producing a tiered structure where vertically integrated stacks challenge modular sensor-as-a-service configurations. The vendor base concentrates around three strategic archetypes: technology-native platform operators, legacy automotive spin-offs, and municipal partnership specialists. Dominant competitive moves include strategic partnerships for mapping data access and portfolio diversification into subscription mobility bundles.
Within the technology-native tier, Waymo LLC and Zoox Inc. exemplify vertically integrated hardware-software configurations, while Baidu Apollo anchors the geography-specific partnership archetype. These three occupy positions spanning sensor stack ownership, purpose-built vehicle architecture, and municipal transit agency procurement channels respectively.
| Leading Market Players |
|---|
| Waymo LLC |
| Baidu Apollo |
| Cruise LLC |
| Zoox Inc. |
| Motional |
| Pony.ai |
| AutoX |
| Aurora Innovation Inc |
| WeRide |
| Others |
Value Chain & Pricing Dynamics
Fleet-scale sensor procurement at ten-thousand-unit volumes compresses lidar unit economics and establishes price floors that exclude sub-scale operators from profitable deployment in Phoenix and San Francisco corridors. Solid-state manufacturing scale-up in Nagoya and Shenzhen feeds directly into robotaxi fleet economics, with per-mile pricing power concentrating among operators who anchor long-term supplier contracts.
Pricing Analysis
Volume-discount tiering structures separate municipal transit agency procurement from private consumer subscriptions across the United States and Chinese markets. Pricing stratifies across premium guaranteed-uptime, standard on-demand, and economy pooled tiers, with differentiation driven by ISO 26262 certification grade and after-sales service bundling. Pricing pressure stems from solid-state lidar cost compression collapsing hardware depreciation schedules. Corporate campus buyers exhibit lowest price sensitivity due to SLA-embedded amenity positioning, while occasional private users in European markets resist subscription commitments without per-trip parity.
Supply Chain Analysis
Japan and China anchor solid-state lidar fabrication, with Taiwan supplying precision optical components for perception stack integration. Raw material dependencies center on rare-earth elements for laser emitters, silicon carbide substrates for thermal management, and high-purity gallium arsenide for photodetector arrays. Single-source vulnerability concentrates in solid-state lidar ASIC design houses with captive foundry relationships. Distribution runs through Tier-1 automotive supplier channels into fleet operator integration facilities, bypassing traditional aftermarket infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous ride-sharing constitutes a high-growth disruption justified by EU AI Act compliance frameworks compressing commercial deployment timelines across European testing corridors.
For Market Incumbents: Shield market position through backward integration into solid-state lidar supply and captive mapping infrastructure in operational design domains. Waymo-style vertical sensor stack ownership defends against modular sensor-as-a-service entrants. Prioritize ISO 26262 certification investment to maintain procurement eligibility under NHTSA and EU AI Act safety validation protocols.
For New Entrants and Emerging Players: CE marking fast-track pathways through German regulatory liaison offices open first-mover positioning in Munich and Stuttgart corporate campus shuttle contracts. White-space targets include airport ground transportation geofenced environments and municipal first-mile-last-mile partnerships in Chinese megacities. Go-to-market execution should anchor API-first integration with travel management platforms rather than direct consumer acquisition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated hardware-software stacks over modular perception-component suppliers. Long-term viability concentrates on operators with demonstrated sub-50-millisecond dispatch latency and municipal procurement channel access. Watch regulatory sandbox expansion in California and Yangtze River Delta clusters as inflection signal for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Stack Vertical Integration | Captive lidar supply secures cost advantages against modular competitors in Phoenix deployments. |
| Municipal Partnership Structuring | Dedicated lane access in Chinese and German megacities generates preferential curb allocation. |
| Subscription Mobility Bundle Launch | Public transit pass integration captures superior customer lifetime value in dense metropolitan corridors. |
| Regulatory Sandbox Certification | EU AI Act conformity assessment streamlines European licensing timelines for qualified operators. |
| Pooling Algorithm Investment | Dynamic multi-passenger routing undercuts single-occupancy vehicle ownership economics. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with fleet operations directors, municipal transit procurement officers, functional safety engineers, and lidar component sourcing managers; and secondary validation against NHTSA autonomous vehicle filings, MIIT standards documentation, EU AI Act regulatory texts, and SEC disclosures from publicly traded operators. Bottom-up fleet deployment counts triangulated against top-down addressable market sizing across service type, vehicle type, and end-user segmentation dimensions.
Across the projection horizon, the analytical framework modeled service type adoption curves, vehicle type capital deployment patterns, platform integration complexity tiers, and regional regulatory cluster divergence. CAGRs derived from logistic diffusion curves fitted to operational fleet density thresholds, with inputs including sensor cost curve trajectories, municipal partnership penetration rates, and teleoperation labor availability constraints.
Underlying assumptions cover EU AI Act implementation timelines, solid-state lidar manufacturing yield improvements, and NHTSA incident reporting threshold stability, with deviation risk concentrated in regulatory divergence between jurisdictions and functional safety engineer scarcity. Recalibration cycles align with material shifts in autonomous vehicle safety validation protocols and municipal procurement framework maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
US Autonomous Car Market
Autonomous Vehicles
Autonomous Parking System Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
Connected Vehicle Market
Autonomous Vehicles
Autonomous Driving Technology Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Singapore Autonomous Navigation Market
Autonomous Vehicles
Fully Autonomous Driving Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market
Autonomous Vehicles
Automotive Lidar Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Driverless Cab Service Market
Autonomous Vehicles
Global Driverless Car Market