
 Self-Driving Cars and Trucks Market | 2026-2036
Self-Driving Cars and Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Driving Cars and Trucks Market Intelligence
Software-defined subscription layers for over-the-air autonomous feature upgrades is recalibrating how OEMs monetize vehicle platforms. Tesla, Inc. leverages its vertically integrated full-self-driving software stack to capture recurring revenue per unit. Waymo LLC sustains its position through fleet-scale robotaxi operations in mapped urban domains. NVIDIA Corporation anchors the compute layer with Drive Orin and Thor platforms that power perception pipelines across multiple OEM programs.
Self-driving cars and trucks integrate lidar arrays, radar units, camera-based computer vision, and sensor fusion controllers to perceive environments and execute driving decisions without human intervention; these systems typically process inputs through neural networks running on dedicated AI accelerators with sub-50-millisecond reaction latency for collision avoidance. Passenger cars dominate current deployment volumes, though heavy trucks attract concentrated investment from logistics providers seeking lane-keep automation on interstate corridors. Sensor fusion architectures command premium engineering margins due to redundancy requirements, while lidar costs are compressing through solid-state designs that enable broader vehicle integration.
NHTSA's Federal Motor Vehicle Safety Standards and EPA tailpipe regulations jointly determine which autonomous configurations achieve type approval for US roadways, while California's Department of Motor Vehicles operates the nation's most granular autonomous vehicle testing permit framework that shapes real-world data accumulation strategies. The EU AI Act and UN ECE R79/R157 add compliance dimensions for any platform seeking transatlantic homologation. Stakeholders must monitor how fragmented state-level liability frameworks evolve alongside federal preemption debates that will determine deployment velocity and insurance cost structures.
Market Dynamics
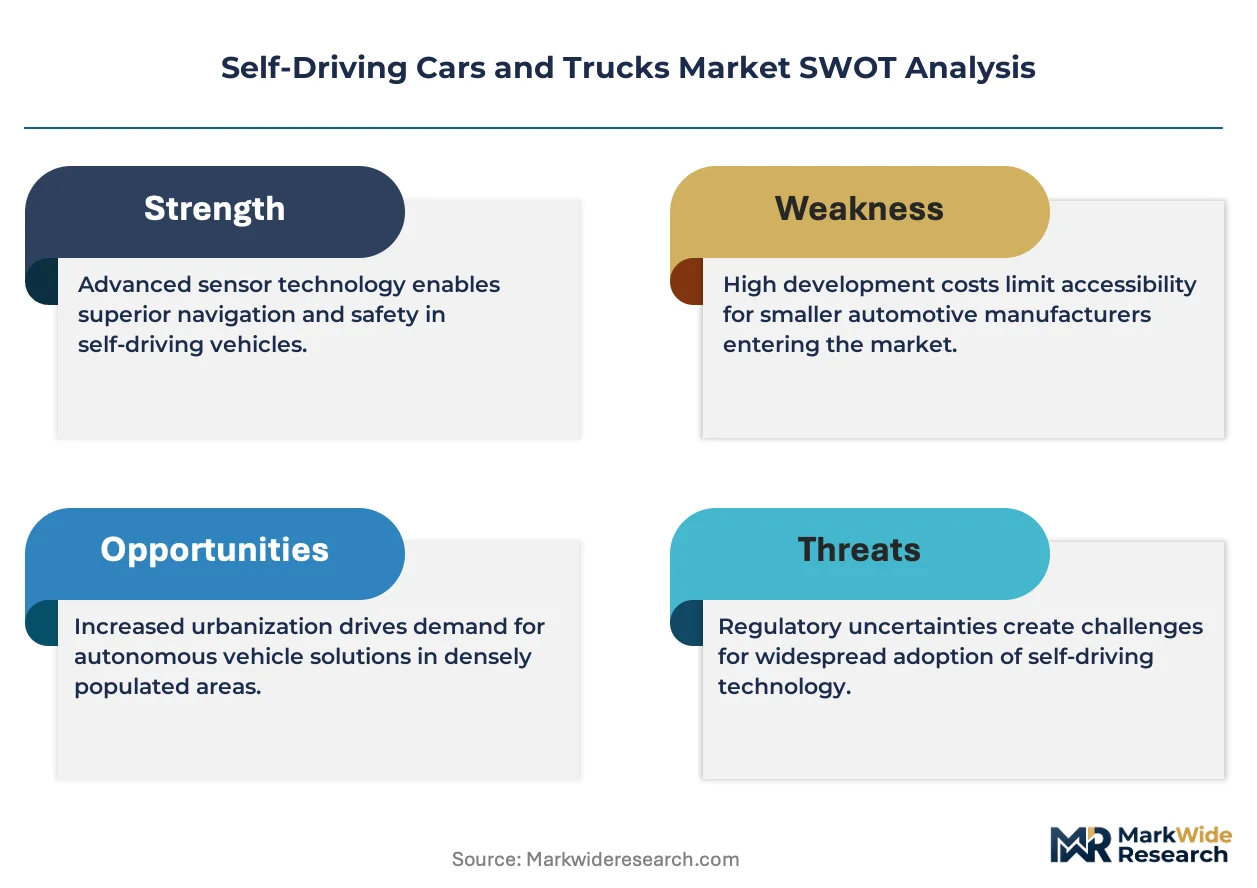
Software-defined vehicle architectures are compressing hardware refresh cycles and shifting value capture toward recurring feature subscriptions, forcing tier-one suppliers to renegotiate long-term supply agreements.
Growth Catalysts
- California DMV Testing Permits:The state's granular autonomous vehicle testing framework accelerates real-world data accumulation for urban robotaxi deployment.
- Logistics Provider Investment:Freight carriers are expanding pilot programs for lane-keep automation across interstate corridors in the United States.
- Solid-State Lidar Maturation:Advances in solid-state lidar designs compress sensor costs and enable broader integration into production vehicle platforms.
Market Restraints
- Sensor Cost Volatility:Lidar array and AI accelerator chip pricing remains sensitive to semiconductor fabrication capacity constraints in East Asian foundry networks.
- Regulatory Fragmentation:Divergent state-level liability frameworks in the United States create insurance cost uncertainty that slows fleet deployment decisions.
- Technical Edge-Case Gaps:Neural network perception systems struggle with adverse weather conditions and unstructured construction zones, limiting operational design domains.
Strategic Opportunities
- Underpenetrated Rural Freight Corridors:Long-haul trucking routes between secondary US markets present first-mover advantages for hub-to-hub autonomous convoy systems.
- EU AI Act Compliance Services:The European Union's risk-based AI governance framework creates demand for third-party algorithmic audit and certification capabilities.
- Over-the-Air Monetization:Feature-on-demand software layers enable OEMs to capture recurring revenue from safety and convenience upgrades post-purchase.
Industry Challenges
- Perception Engineering Talent Scarcity:The shortage of specialists in sensor fusion and neural network optimization constrains development velocity across OEM programs.
- Homologation Timeline Compression:Simultaneous pursuit of NHTSA Federal Motor Vehicle Safety Standards approval and UN ECE R157 certification strains regulatory affairs teams.
- Legacy Fleet Integration Complexity:Retrofitting autonomous capabilities onto existing commercial truck platforms requires custom mechanical and electrical interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Driving Cars and Trucks Market |
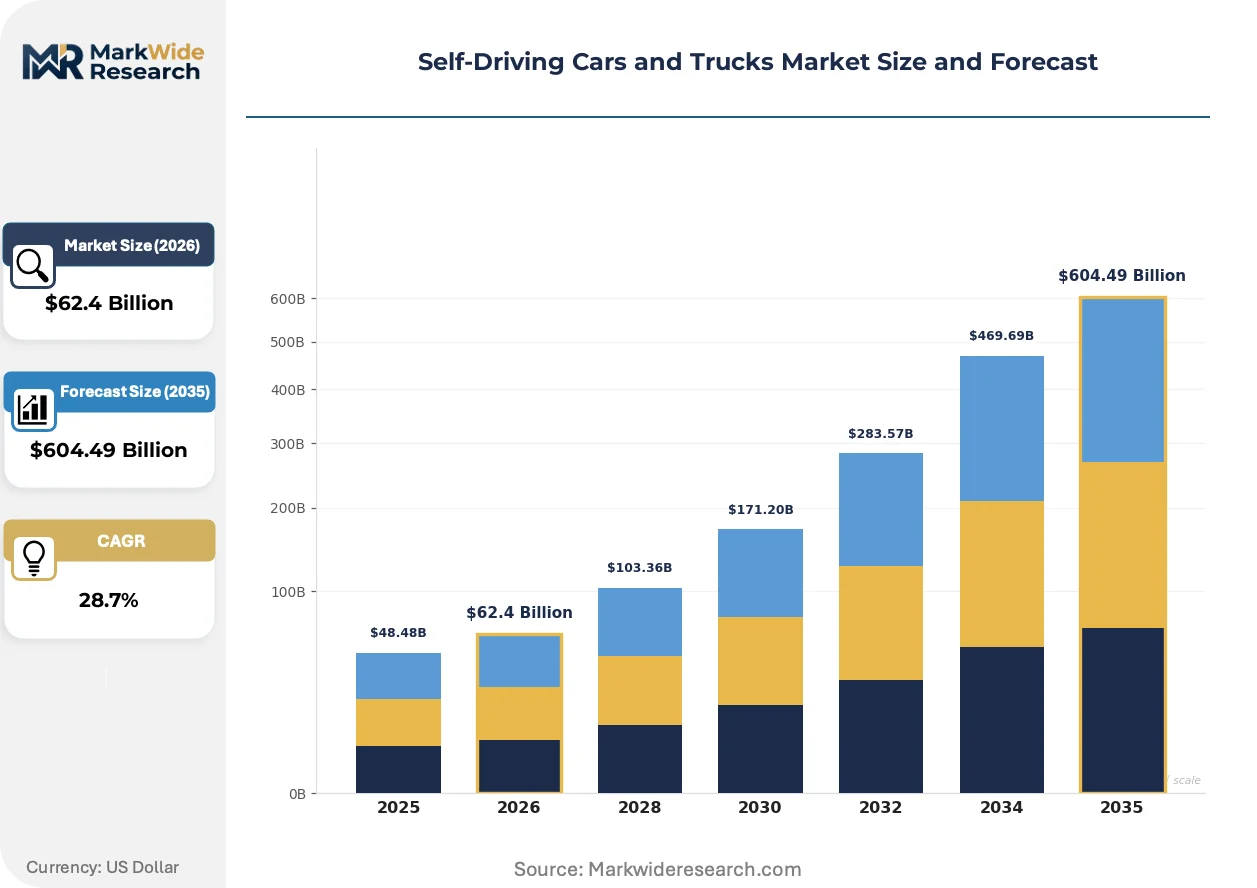
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $604.49 Billion |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Light Trucks, Heavy Trucks, Buses Technology: Lidar, Radar, Computer Vision, Sensor Fusion End User: Public Transportation, Logistics Providers, Ride-Sharing, Personal Use Integration Level: Fully Autonomous, Semi-Autonomous, Driver-Assisted, Remote Controlled |
| Companies Covered | Waymo LLC, Tesla, Inc., Cruise LLC, Zoox, Inc., Aurora Innovation, NVIDIA Corporation, General Motors Company, Mercedes-Benz Group AG, Toyota Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Driving Cars and Trucks Market Strategic Shifts & Innovations
Edge computing architectures and federated learning protocols are redistributing processing loads away from centralized cloud infrastructure, altering how autonomous systems train, update, and validate in production environments.
Sensor fusion is decentralizing perception computation across distributed vehicle nodes rather than central domain controllers. Tier-one suppliers are adopting zonal architectures that place AI accelerators adjacent to camera and radar units. This topology reduces wiring harness complexity and enables faster reaction latency for collision avoidance systems.
The EU AI Act's risk-based classification system for autonomous vehicle algorithms is forcing OEMs to implement formalized model governance and documentation protocols. High-risk AI systems must demonstrate conformity with transparency and human oversight requirements. European manufacturers are responding by establishing dedicated algorithmic audit functions within quality assurance departments.
Fleet procurement patterns are fragmenting as logistics providers bypass traditional dealer networks to negotiate direct software licensing agreements with technology vendors. Large freight operators now specify autonomous feature sets independently of chassis suppliers. This disintermediation is most pronounced among US-based asset-heavy carriers operating dedicated long-haul corridors.
Self-Driving Cars and Trucks Market Segmentation
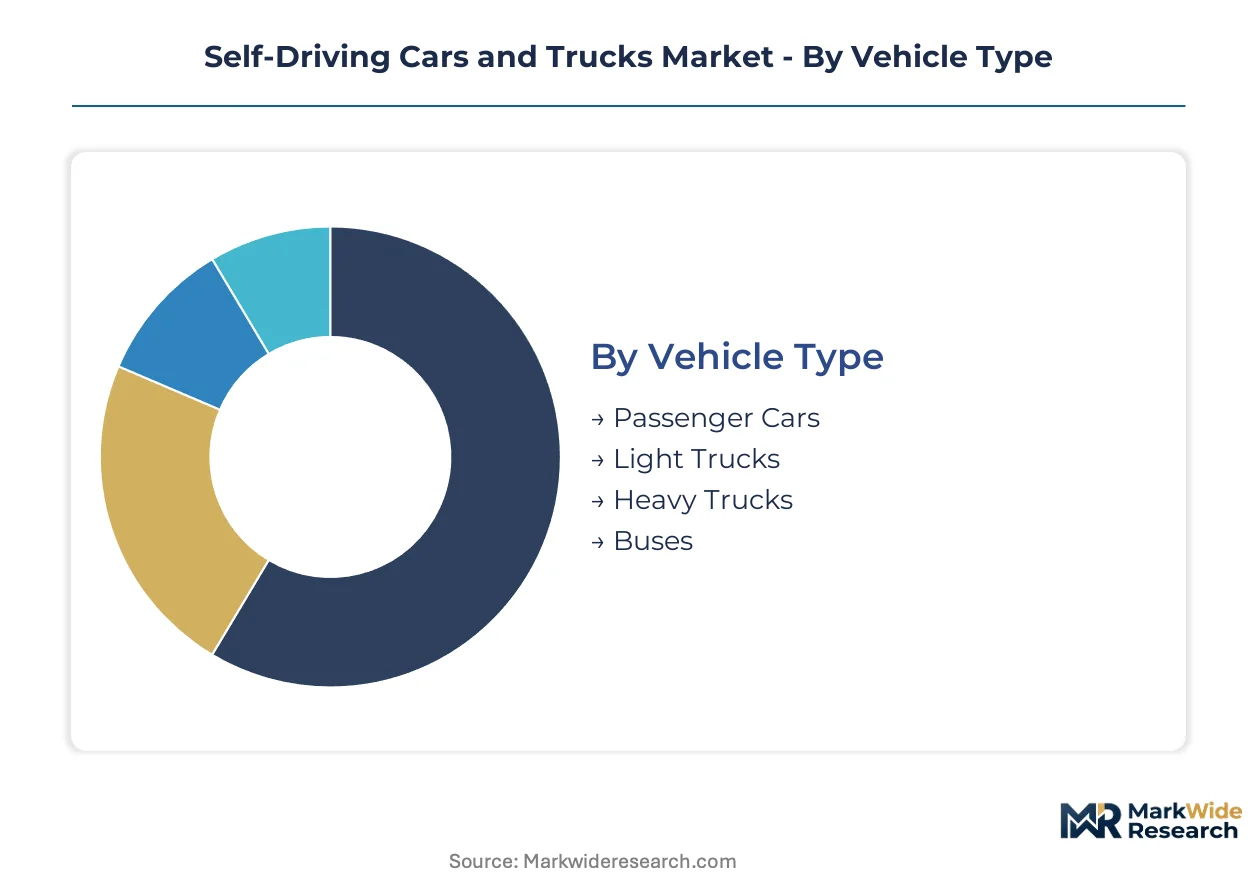
Self-driving vehicle platforms demand granular segmentation to align hardware configurations with distinct operational design domains and monetization models. Each dimension—vehicle type, sensor technology, end-use application, and automation level—carries unique engineering requirements and regulatory pathways that determine deployment velocity.
Vehicle Type:
Upgrade cycles vary dramatically across vehicle classes, with commercial platforms refreshing on accelerated timelines driven by utilization intensity and total cost of ownership calculations.
- Passenger Cars:Urban robotaxi fleets dominate current deployment volumes, with California and Arizona permitting frameworks enabling accumulation of real-world miles for neural network training. NHTSA's evolving FMVSS interpretations for occupant protection in driverless configurations create homologation bottlenecks.
- Heavy Trucks:Lane-keep automation on interstate freight corridors attracts concentrated logistics investment, with hub-to-hub convoy systems reducing per-mile labor costs across routes between Dallas, Atlanta, and Chicago. Solid-state lidar integration enables 24-hour continuous operation without driver fatigue constraints.
- Light Trucks:Last-mile delivery platforms in suburban zones blend passenger-car sensor densities with commercial durability requirements.
- Buses:Fixed-route public transit applications leverage predictable geofenced corridors for early-stage autonomous deployment.
Passenger cars sit at the top of the volume ranking, with heavy trucks climbing the fastest.
Technology:
Cost tiers separate mature sensing modalities from emerging fusion architectures commanding premium engineering margins.
- Sensor Fusion:Multi-modal perception stacks combining lidar, radar, and camera inputs deliver redundancy for safety-critical urban operations, with zonal compute architectures reducing wiring complexity. California DMV testing permit holders accumulate validation data specifically for fused perception edge cases.
- Lidar:Solid-state designs compress unit costs below legacy mechanical spinning arrays, enabling broader OEM integration into production vehicle platforms. East Asian foundry capacity constraints create intermittent supply volatility for specialized photonic components.
- Computer Vision:Camera-based neural networks anchor cost-optimized driver-assistance features across mass-market vehicle segments.
- Radar:Frequency-modulated continuous-wave units provide all-weather velocity detection complementary to optical sensors.
Sensor fusion commands the highest engineering margins, with lidar gaining share fastest as solid-state manufacturing scales.
End User:
Application-specific operational design domains dictate sensor suite specifications and software validation requirements.
- Logistics Providers:Freight carriers negotiate direct software licensing agreements bypassing traditional dealer networks, specifying autonomous feature sets independent of chassis suppliers. Interstate corridor operators prioritize lane-centering and platooning capabilities over complex urban maneuvering.
- Ride-Sharing:Robotaxi services in mapped urban domains require sub-50-millisecond reaction latency for collision avoidance in dense pedestrian environments. Waymo's fleet-scale operations in Phoenix and San Francisco establish performance benchmarks for the segment.
- Public Transportation:Fixed-route bus systems leverage geofenced operational domains with reduced perception complexity.
- Personal Use:Consumer adoption remains constrained by liability framework uncertainty and feature subscription pricing models.
Logistics providers sit at the top of the volume ranking, with ride-sharing expanding most quickly in mapped urban zones.
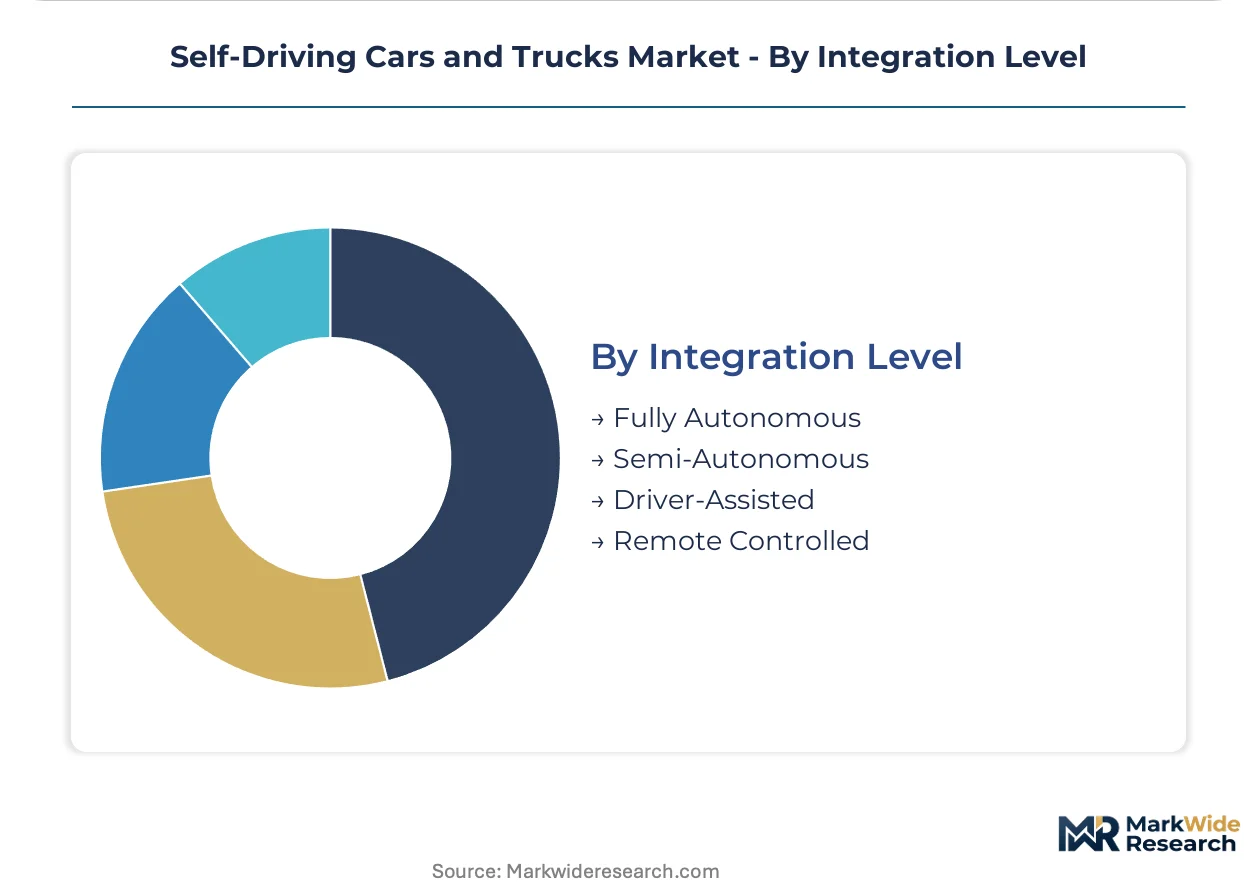
Integration Level:
Maturity gradients separate production-ready assistance features from experimental fully autonomous configurations awaiting regulatory type approval.
- Driver-Assisted:Level 2 systems combining adaptive cruise control with lane-keeping dominate current production volumes, with Tesla's Full Self-Driving subscription demonstrating recurring revenue potential. NHTSA FMVSS compliance pathways for these configurations are well-established.
- Fully Autonomous:Level 4 urban robotaxi and highway trucking platforms require California DMV driverless deployment permits or equivalent state authorizations. UN ECE R157 certification adds compliance dimensions for transatlantic homologation ambitions.
- Semi-Autonomous:Level 3 conditional automation permits driver disengagement in specific operational design domains with recall requirements.
- Remote Controlled:Teleoperation backup systems enable deployment in constrained geofences with human oversight for edge cases.
Driver-assisted systems sit at the top of the volume ranking, with fully autonomous configurations steepest in expansion trajectory pending regulatory clarity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains denser autonomous vehicle testing infrastructure than Germany, though Chinese deployment volumes now exceed both markets combined. National regulatory frameworks determine where capital concentrates for real-world validation.
United States
California's DMV testing permits and Arizona's regulatory sandbox attract fleet-scale robotaxi operations from technology developers. NHTSA's Federal Motor Vehicle Safety Standards govern type approval for driverless configurations. Silicon Valley technology clusters and Phoenix metro zones accumulate the majority of real-world autonomous miles.
China
Domestic technology champions deploy robotaxi services across Beijing, Shanghai, and Shenzhen with municipal government coordination. MIIT administers connected vehicle standards and intelligent vehicle road testing regulations. Yangtze River Delta manufacturing bases integrate solid-state lidar into production vehicle platforms at compressed cost points.
Germany
Luxury OEMs pursue Level 3 conditional automation for highway deployment with KBA type approval pathways. UN ECE R157 certification enables transnational homologation across EU member states. Bavaria's automotive engineering corridor hosts validation facilities for sensor fusion systems.
Japan
Keiretsu-affiliated manufacturers target Level 4 mobility services for aging rural populations with METI subsidy programs. JIS standards govern autonomous system safety requirements. Nagoya's Chubu manufacturing belt concentrates lidar component fabrication for Asian supply networks.
South Korea
Conglomerate technology divisions supply AI accelerators and camera modules to global OEM programs. MFDS-equivalent transport ministry frameworks regulate autonomous vehicle testing permits. Seoul Capital Area smart city initiatives deploy geofenced autonomous shuttle services.
Self-Driving Cars and Trucks Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated technology stacks commanding premium positioning in software-defined architectures. The vendor base organizes around three strategic archetypes: full-stack developers owning perception-to-execution pipelines, compute layer suppliers anchoring multi-OEM programs, and traditional automotive OEMs retrofitting autonomous capabilities onto existing platforms. Dominant competitive moves include direct software licensing agreements that bypass dealer networks and sensor cost compression through solid-state manufacturing scale.
Within the full-stack developer tier, Waymo LLC and Tesla, Inc. represent contrasting monetization models for autonomous capabilities. NVIDIA Corporation anchors the compute layer supplier archetype through its Drive platform deployments across multiple OEM programs. Aurora Innovation occupies a position among developers targeting heavy truck automation for logistics corridors.
| Leading Market Players |
|---|
| Waymo LLC |
| Tesla, Inc. |
| Cruise LLC |
| Zoox, Inc. |
| Aurora Innovation |
| NVIDIA Corporation |
| General Motors Company |
| Mercedes-Benz Group AG |
| Toyota Motor Corporation |
| Others |
Cost & Logistics Intelligence
Sensor-tier bifurcation between fused multi-modal stacks and camera-only configurations creates divergent margin profiles across autonomous vehicle programs. Premium perception architectures command recurring software licensing fees while commodity vision systems compete on hardware bill-of-materials compression. This tier divergence manifests in procurement patterns where logistics providers negotiate direct compute-layer agreements independent of chassis suppliers.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for AI accelerator chips that anchor autonomous perception pipelines. The dominant pricing structure separates hardware-enabled base features from over-the-air subscription tiers for advanced autonomy capabilities. Price differentiation rests on certification grade—California DMV driverless deployment permits versus standard driver-assistance homologation—and volume scale for fleet procurement contracts. Pricing pressure stems from solid-state lidar manufacturing scale in Chinese Yangtze River Delta facilities compressing sensor costs. Logistics providers exhibit highest price sensitivity due to total cost of ownership calculations per freight-mile, while luxury passenger OEMs absorb premiums for differentiated autonomous branding.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan for advanced semiconductor fabrication and China for solid-state lidar component integration. Geographic supply concentration clusters in Taiwan, South Korea, and Japan for AI accelerators; China for lidar assembly; and Germany for automotive-grade sensor validation. Raw material dependencies span rare earth elements for lidar photonics, high-purity silicon wafers for neural network processors, and specialized copper alloys for zonal compute housing. Supply chain risk centers on tariff exposure for cross-border semiconductor shipments amid evolving US-China trade frameworks. Distribution runs through direct OEM procurement teams and tier-one supplier consortiums rather than traditional aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software-defined subscription layers as hardware costs compress through solid-state sensor manufacturing scale. Premium-tier shifts toward fully autonomous configurations create pricing power for validated perception stacks.
For Market Incumbents: Lock in sensor fusion engineering talent through captive R&D centers in Bavaria and California to defend against perception pipeline specialists poaching technical teams. Secure long-term offtake agreements for AI accelerator capacity at Taiwan foundries before logistics providers exhaust available wafer starts. Vertical integration into solid-state lidar component fabrication mitigates supply volatility from Chinese assembly networks. For New Entrants and Emerging Players: Solid-state lidar cost-down engineering presents a technology-first wedge for penetrating the rural freight corridor segment where incumbent coverage remains sparse. Target hub-to-hub trucking routes between Dallas and Atlanta where regulatory clarity exceeds urban robotaxi complexity. Pursue direct software licensing agreements with asset-heavy carriers bypassing dealer network disintermediation. For Investors and Strategic Acquirers: Consolidation pressure builds where tier-one suppliers lack algorithmic audit capabilities for EU AI Act compliance pathways. Long-term viability favors developers owning full perception-to-execution pipelines rather than modular component suppliers. Acquisition target archetypes include zonal compute architecture specialists and federated learning protocol engineers. Watch California DMV driverless deployment permit issuance velocity as inflection indicator for regulatory risk recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables recurring revenue capture from over-the-air autonomy feature upgrades post-purchase. |
| Sensor Fusion Patent Portfolio Expansion | Defends margin position against camera-only cost competitors in mass-market segments. |
| EU AI Act Compliance Certification | Unlocks transatlantic homologation pathways for high-risk algorithmic systems under risk-based governance. |
| Solid-State Lidar Manufacturing Scale-Up | Compresses unit costs below mechanical spinning arrays for broader OEM platform integration. |
| Direct Fleet Licensing Agreement | Bypasses dealer network disintermediation to capture logistics provider procurement decisions. |
Research Approach
Direct dialogue with OEM platform engineers, tier-one supplier procurement leads, California DMV regulatory affairs officers, and logistics provider fleet technology directors grounded qualitative assessment. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standards filings, EPA emissions certification databases, UN ECE R157 homologation records, and vehicle production registration data. Bottom-up triangulation across sensor unit shipment estimates and top-down reconciliation against fleet deployment permits anchored volume assumptions.
Segmentation outputs across vehicle type, automation level, sensor technology tier, and end-use application dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from regression analysis against historical permit issuance velocity and fleet trial expansion patterns. Industry-specific forecast inputs incorporated solid-state lidar cost curves and AI accelerator foundry capacity expansion timelines.
The model holds under stable regulatory preemption interpretations; deviation in state-level liability framework fragmentation or NHTSA automated vehicle guidance revisions would shift deployment velocity assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Blind Spot Detection Market
Autonomous Vehicles
AI in Transportation Market
Autonomous Vehicles
Self-Driving Truck Market
Autonomous Vehicles
In-Vehicle AI Robot Market
Autonomous Vehicles
Autonomous Taxi Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Automotive Predictive Technology Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Autonomous Parking System Market
Autonomous Vehicles
Norway Autonomous Navigation Market
Autonomous Vehicles
Italy Autonomous Navigation Market
Autonomous Vehicles
HD Map for Autonomous Vehicle Market
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
Autonomous Driving Component Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
Automotive AI Market