
 Global Drone Software Market | 2026-2036
Global Drone Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drone Software Market Foresight
Modular flight control bundling is recalibrating how agricultural producers and construction firms evaluate total cost of ownership across drone fleets. Skydio leverages autonomous navigation stacks to differentiate its enterprise offerings from hardware-centric rivals. PrecisionHawk anchors its position through specialized data analytics pipelines for precision agriculture workflows. AirMap controls geofencing and airspace authorization APIs that operators increasingly treat as essential infrastructure.
Drone software encompasses the embedded and cloud-based programs that govern flight dynamics, sensor fusion, real-time telemetry, and post-mission data processing for unmanned aerial systems. These platforms integrate Kalman filtering for state estimation, MAVLink protocols for command transmission, and photogrammetric engines to transform multispectral imagery into actionable orthomosaics for commercial and government end users. Cloud-based deployment is capturing expanding margin pools as operators prioritize distributed processing and fleet-scale mission orchestration over localized installations. Image processing solutions within the solution/offering dimension are registering the fastest uptake as thermal and LiDAR payloads proliferate across infrastructure inspection and disaster management applications.
The FAA's Part 107 framework and BVLOS waiver pathways in the United States, EASA's U-space regulatory package across EU member states, and CAAC's evolving low-altitude economy policies in China collectively determine where commercial operators can deploy at scale and what software certification thresholds apply. These regulatory architectures directly shape demand for compliance-integrated platforms that embed automatic airspace deconfliction and audit-ready flight logging. Stakeholders must monitor which jurisdictions advance beyond visual line of sight at scale, as this regulatory sequencing will dictate where software vendors should prioritize localization investments and certification partnerships.
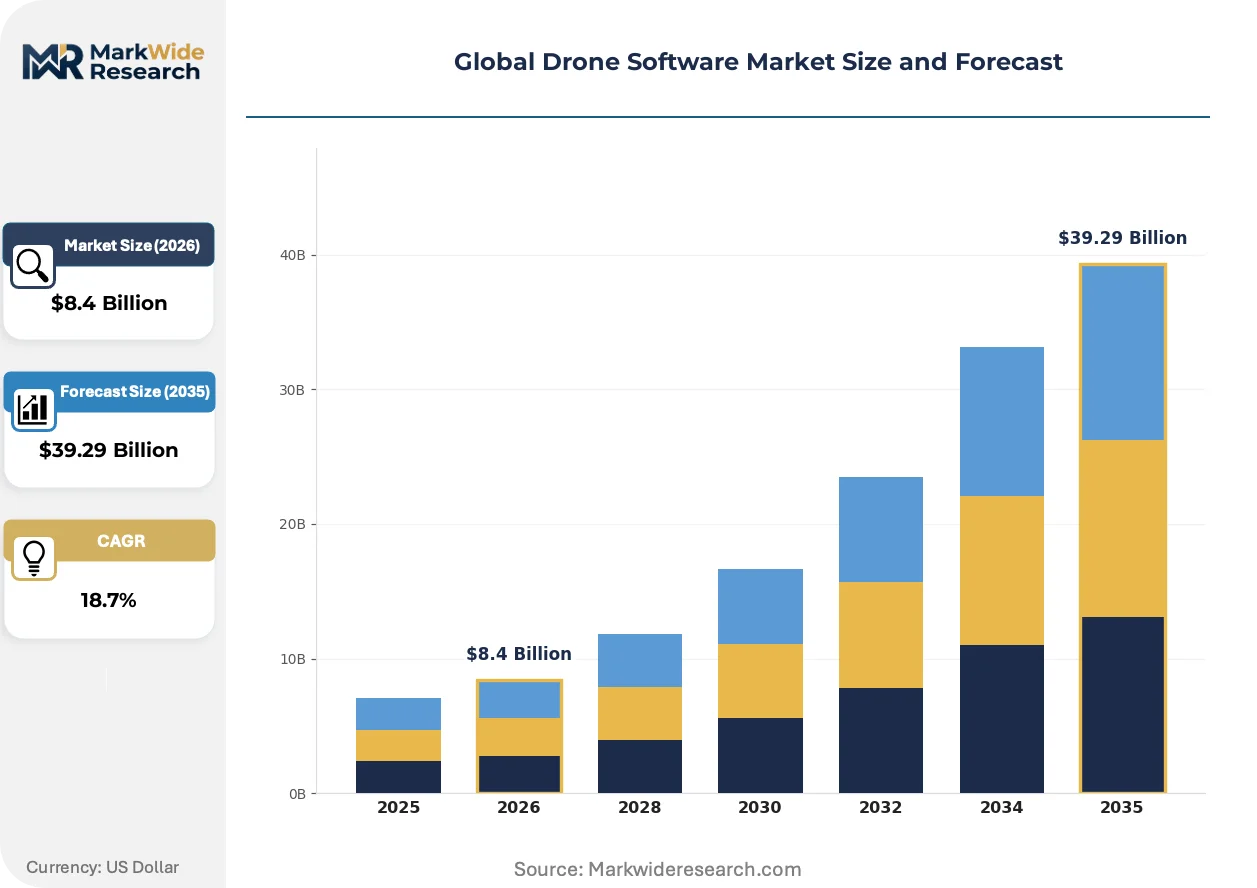
Market Dynamics
Beyond visual line of sight waivers from the FAA are compressing deployment timelines for commercial operators while fragmenting vendor certification requirements across jurisdictions. This regulatory sequencing is forcing software providers to embed automatic airspace deconfliction modules and audit-ready flight logging as core platform features rather than optional add-ons.
Growth Catalysts
- Precision agriculture workflows:Agricultural producers in the United States and Germany are expanding multispectral imaging deployments for crop health monitoring, creating sustained demand for photogrammetric processing engines.
- EASA U-space corridors:The European Union's dedicated low-altitude airspace framework is enabling scaled commercial operations across member states, accelerating adoption of geofencing and authorization APIs.
- Edge computing architectures:Real-time sensor fusion and onboard Kalman filtering are reducing latency for infrastructure inspection missions, particularly across thermal and LiDAR payload categories.
Market Restraints
- Specialized talent scarcity:Shortages of embedded systems engineers with MAVLink protocol expertise are extending development cycles and inflating compensation costs for flight control stack customization.
- Input concentration in semiconductor supply:Dependence on a limited supplier base for high-performance GPUs used in neural network inference creates vulnerability for autonomous navigation vendors.
- Regulatory fragmentation:Divergent certification thresholds between the FAA Part 107 framework and CAAC low-altitude economy policies force redundant compliance investments for multi-jurisdiction operators.
Strategic Opportunities
- Disaster management applications:Emergency response agencies in Australia are piloting thermal imaging integration for wildfire perimeter mapping, opening new procurement channels outside traditional commercial verticals.
- 5G network slicing:Convergence of cellular connectivity with command-and-control link redundancy is enabling urban air mobility trials in Chinese smart cities with dedicated U-space infrastructure.
- Outcome-based service models:Construction firms are shifting from perpetual licenses to per-acre data processing subscriptions, creating recurring revenue pools for analytics-anchored platforms.
Industry Challenges
- ISO 21384 compliance timelines:Certification for civil unmanned aircraft systems requires extensive documentation of software verification processes, delaying market entry for new entrants by 12-18 months.
- Legacy fleet integration friction:Operators with mixed-vendor hardware face API incompatibility when consolidating telemetry streams into unified fleet management dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drone Software Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Solution/Offering: Flight Control, Data Analytics, Image Processing, Navigation Systems, Communication Management End User: Agricultural Producers, Construction Firms, Emergency Responders, Surveying Experts, Media Companies Application: Precision Agriculture, Infrastructure Inspection, Disaster Management, Topographic Mapping, Aerial Photography |
| Companies Covered | Insitu, PrecisionHawk, Skydio, Ondas Holdings, Draganfly, Drone Harmony, AirMap, Votix, Altitude Angel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drone Software Market Shifts & Advancements
Software-defined flight control is displacing hardware-centric architectures as the primary axis of vendor differentiation. This shift is compressing margins for pure-play hardware manufacturers while expanding addressable market for modular, API-first platforms.
Containerized mission planning architectures are decentralizing compute loads from ground stations to distributed edge nodes. Agricultural cooperatives in the United States are adopting these microservices-based deployments to orchestrate hundred-unit fleets without centralized infrastructure investment. This topology is compressing total cost of ownership for precision agriculture operators while fragmenting vendor lock-in patterns.
EASA's U-space regulatory package is mandating automatic airspace deconfliction for all commercial operations above 120 meters across EU member states. This requirement is accelerating procurement of geofencing-integrated platforms by infrastructure inspection providers in Germany and France. Vendors are responding by embedding real-time NOTAM ingestion and dynamic geofence adjustment as standard capabilities.
Subscription-based data processing contracts are displacing perpetual software licenses in the construction and mining verticals. Equipment leasing firms in Australia are bundling photogrammetric analytics with drone hardware rentals, capturing margin pools previously held by standalone software vendors. This unbundling is most visible in open-pit mining operations where volumetric survey frequency drives recurring consumption patterns.
Global Drone Software Market Segmentation
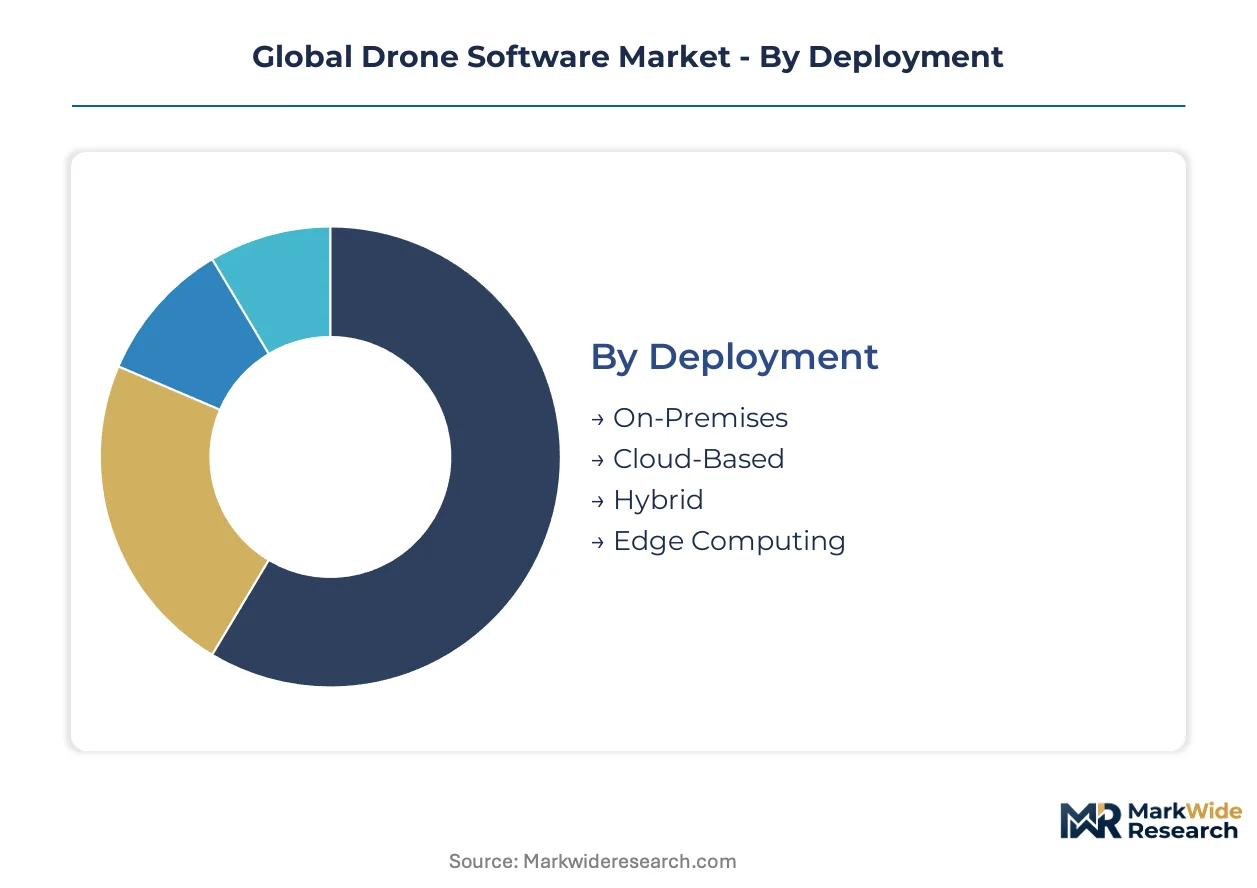
Drone software segmentation reveals how deployment architectures, solution stacks, and end-use requirements fragment procurement patterns across commercial and government verticals. Understanding these divides helps vendors calibrate platform modularity against customer integration depth.
Deployment:
Deployment architecture determines where compute loads reside — from centralized servers to distributed edge nodes — shaping latency profiles and infrastructure investment requirements for operators.
- Cloud-Based:Distributed processing environments enable fleet-scale mission orchestration without localized hardware investment. Agricultural producers in the United States prioritize these deployments for multispectral data pipelines across hundred-unit operations.
- Edge Computing:Onboard sensor fusion and real-time Kalman filtering reduce command latency for time-critical missions. Infrastructure inspection providers in Germany adopt these architectures for thermal and LiDAR payload integration where millisecond response matters.
- On-Premises:Localized installations serve operators with stringent data sovereignty requirements or intermittent connectivity.
- Hybrid:Split architectures balance sensitive processing locally with burst compute in cloud environments.
Cloud-based deployments lead volumes today; edge computing is gaining share fastest.
Solution/Offering:
Solution specialization tracks where software vendors capture margin — from commoditized flight control to high-value analytics engines.
- Image Processing:Photogrammetric engines transform thermal, LiDAR, and multispectral inputs into actionable orthomosaics. Emergency responders in Australia pilot these tools for wildfire perimeter mapping where rapid terrain reconstruction saves operational hours.
- Data Analytics:Specialized pipelines convert raw telemetry into predictive insights for crop health and structural degradation. Construction firms in Germany subscribe to per-acre processing models that displace perpetual licenses.
- Flight Control:Embedded stacks govern attitude stabilization and waypoint execution across autopilot hardware.
- Navigation Systems:Autonomous path planning modules enable BVLOS operations with dynamic obstacle avoidance.
- Communication Management:Link redundancy and protocol translation ensure command integrity across heterogeneous fleet hardware.
Flight control commands installed base today; image processing climbs the fastest as payload diversity expands.
End User:
End-user categories reflect divergent procurement authority — from centralized agricultural cooperatives to fragmented media production houses.
- Agricultural Producers:Cooperatives and individual operators deploy multispectral imaging for crop health monitoring, creating sustained demand for subscription-based analytics platforms.
- Construction Firms:Equipment leasing companies bundle photogrammetric software with hardware rentals, capturing recurring revenue through volumetric survey contracts.
- Emergency Responders:Agencies prioritize thermal integration for search-and-rescue and disaster perimeter mapping outside traditional commercial channels.
- Surveying Experts:Licensed professionals require centimeter-grade georeferencing and audit-ready flight logging for regulatory compliance.
- Media Companies:Production houses demand cinematic flight paths and real-time video streaming for broadcast and entertainment content.
Agricultural producers anchor volume today; emergency responders expand most quickly as civil defense budgets reallocate.
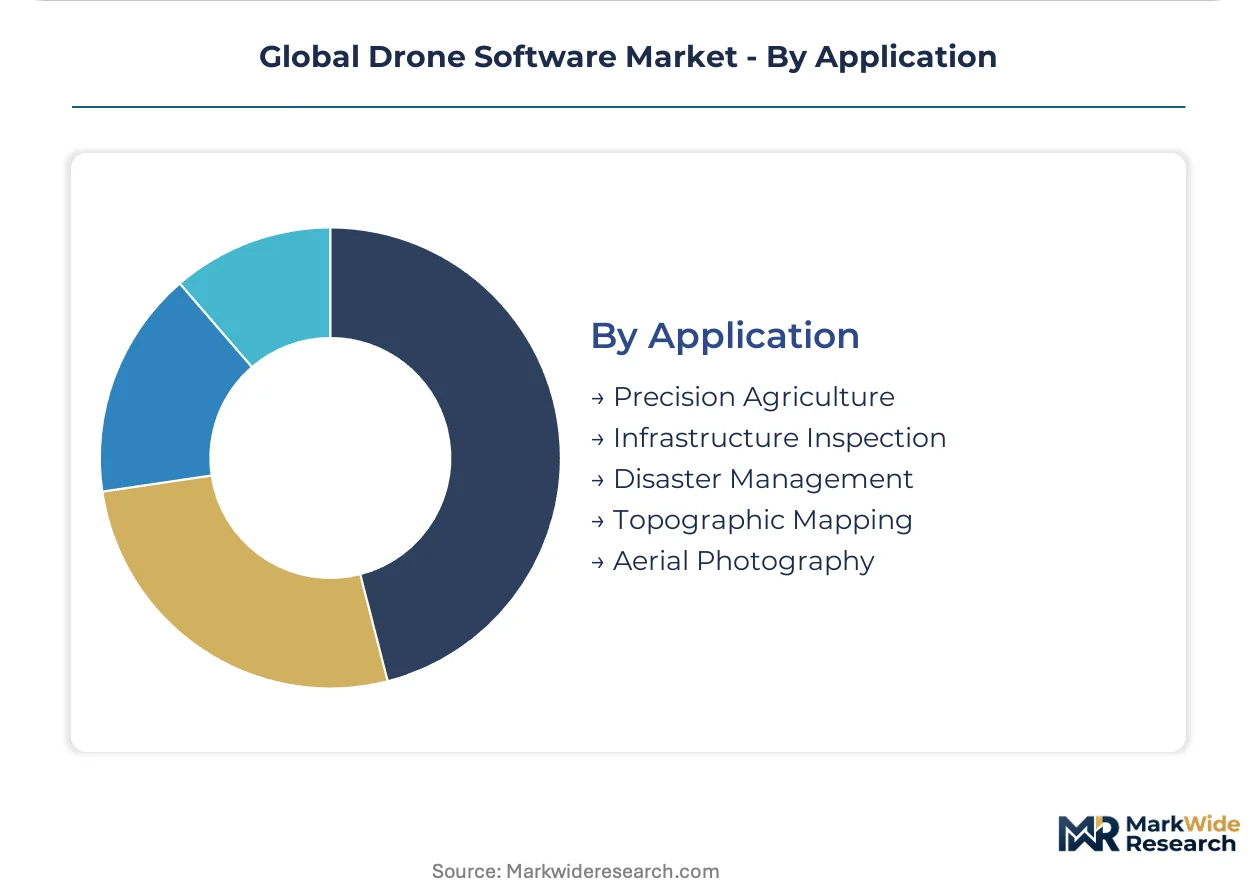
Application:
Application segmentation tracks mission type — each imposing distinct sensor, endurance, and regulatory requirements on software configuration.
- Precision Agriculture:Crop health monitoring and variable-rate application guidance dominate current deployments. Operators in the United States and Germany drive adoption through multispectral vegetation index processing.
- Infrastructure Inspection:Power line, pipeline, and structural assessment missions require automated defect detection algorithms. EASA U-space corridors in France and Germany accelerate procurement of geofencing-integrated platforms for these operations.
- Disaster Management:Rapid damage assessment and supply chain disruption mapping emerge as procurement priorities for government agencies.
- Topographic Mapping:High-precision elevation models support mining volumetrics and construction earthworks planning.
- Aerial Photography:Cinematic and commercial imaging applications demand stabilized gimbal control and HDR processing pipelines.
Precision agriculture leads deployment volumes today; disaster management shows steepest expansion trajectory as climate adaptation budgets grow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The drone software industry traces its commercial roots to United States military unmanned systems development in the early 2000s, with civilian applications scaling through FAA regulatory frameworks established in subsequent decades.
United States
Agricultural cooperatives in the Midwest deploy multispectral imaging across hundred-unit fleets for crop health monitoring. The FAA's Part 107 remote pilot certification and expanding BVLOS waiver pathways compress deployment timelines for commercial operators. California's Central Valley anchors precision agriculture software demand, while Texas energy corridors drive infrastructure inspection platform procurement.
China
CAAC's low-altitude economy policies accelerate urban air mobility trials in smart cities with dedicated U-space infrastructure. Yangtze River Delta technology clusters host autonomous navigation stack development for enterprise drone fleets. Shenzhen's hardware-software integration ecosystem supplies modular flight control systems to agricultural producers across domestic and Southeast Asian markets.
Germany
EASA's U-space regulatory package mandates automatic airspace deconfliction for commercial operations above 120 meters, accelerating geofencing platform adoption. Bavaria's industrial automation corridor concentrates infrastructure inspection providers procuring thermal and LiDAR-integrated software. North Rhine-Westphalia's construction firms shift toward per-acre data processing subscriptions, displacing perpetual licenses.
Australia
Emergency response agencies pilot thermal imaging integration for wildfire perimeter mapping, opening procurement channels outside traditional commercial verticals. The country's civil aviation safety framework enables beyond visual line of sight operations for disaster management applications. Queensland's mining belt drives volumetric survey software demand through equipment leasing bundled with photogrammetric analytics.
United Kingdom
London's financial and insurance technology cluster incubates outcome-based service models for construction and infrastructure verticals. The Civil Aviation Authority's regulatory sandbox approach attracts geofencing and authorization API developers establishing European headquarters. Scotland's offshore energy sector procures automated defect detection algorithms for pipeline and platform inspection missions.
Global Drone Software Market Competitive Landscape
The competitive structure tilts toward modular, API-first platforms displacing hardware-centric architectures. Tiered vendor concentration persists: autonomous navigation specialists command premium positioning, data analytics pipelines anchor mid-market share, and geofencing infrastructure providers capture recurring revenue through airspace authorization dependencies. Dominant competitive moves include strategic partnerships with semiconductor suppliers for GPU access and portfolio diversification into subscription-based processing contracts.
Within the autonomous navigation tier, Skydio exemplifies software-defined differentiation through embedded obstacle avoidance stacks. PrecisionHawk occupies a position among analytics-anchored platforms serving agricultural workflows with specialized data pipelines. AirMap represents the geofencing infrastructure archetype, controlling airspace authorization APIs that operators treat as essential compliance infrastructure.
| Leading Market Players |
|---|
| Insitu |
| PrecisionHawk |
| Skydio |
| Ondas Holdings |
| Draganfly |
| Drone Harmony |
| AirMap |
| Votix |
| Altitude Angel |
| Others |
Supply & Pricing Matrix
GPU spot-price volatility on the Shanghai Electronics Exchange cascades through neural-network inference chip procurement into software licensing tiers, compressing margins for autonomous navigation vendors while inflating subscription rates for cloud-based fleet management platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement patterns, with premium tiers anchored by ISO 21384 certification compliance and dedicated airspace API access while economy tiers strip geofencing modules to hit agricultural cooperative budgets. Price differentiation rests on embedded systems customization depth and after-sales telemetry support intensity. Cost compression in the standard tier is intensifying because construction firms demand per-acre processing models that displace perpetual licenses. Agricultural producers in the United States exhibit highest price sensitivity; infrastructure inspection providers in Germany show lowest sensitivity due to EASA-mandated compliance requirements.
Supply Chain Analysis
Domestic-content mandates under China's low-altitude economy policies are reshaping sourcing, forcing multinational vendors to localize Kalman filtering algorithm development within Yangtze River Delta technology clusters. Component supply concentrates in Taiwan for high-performance GPUs, South Korea for memory modules, and China for flight control hardware integration. Raw material dependencies include silicon wafers, rare earth magnets for motor assemblies, and lithium-polymer cells for extended endurance platforms. Single-source vulnerability in neural-network accelerator chips creates procurement risk for autonomous navigation stack vendors. Distribution runs through Shenzhen hardware-software integration hubs into agricultural cooperative procurement channels across Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Drone Software Market functions as a geographic-arbitrage play: EASA's U-space corridors enable scaled European operations at compliance costs below FAA BVLOS waiver timelines in the United States, rewarding vendors with dual-certification capabilities.
For Market Incumbents: Lock in semiconductor supplier partnerships for GPU allocation priority as autonomous navigation stacks face input concentration risk. Anchor recurring revenue through subscription-based data processing contracts that displace perpetual licenses in construction and mining verticals. Defend against modular API-first entrants by embedding automatic airspace deconfliction as core platform infrastructure rather than optional add-ons. For New Entrants and Emerging Players: EASA's U-space regulatory package in the European Union opens a window for geofencing-integrated platform launches without FAA certification delays. Target disaster management applications in Australia where thermal imaging integration for wildfire perimeter mapping sits outside incumbent vendor strongholds. Pursue equipment-leasing bundling partnerships that capture recurring photogrammetric analytics revenue from mining volumetrics demand in Queensland. For Investors and Strategic Acquirers: Consolidation pressure builds where analytics-anchored platforms lack autonomous navigation capabilities and face margin compression from software-defined flight control displacement. Long-term viability favors vendors with dual-use military-civilian technology transfer pathways and established certification partnerships with national aviation authorities. Target acquisition candidates with embedded edge-computing architectures and real-time sensor fusion IP. Watch BVLOS waiver approval velocity at the FAA as the signal indicating where localization investments should concentrate.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures displace hardware-centric flight control stacks across agricultural cooperative fleets. |
| Strategic Partnership | Semiconductor supplier alliances secure GPU allocation for neural-network inference in autonomous navigation systems. |
| Acquisition of Specialist Firm | Geofencing infrastructure capabilities anchor compliance-integrated offerings under EASA U-space mandates. |
| Geographic Expansion | Localization investments in Yangtze River Delta clusters align with CAAC low-altitude economy policy requirements. |
| Product Launch | Containerized mission planning microservices reduce total cost of ownership for hundred-unit precision agriculture operations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with flight control engineers at autonomous navigation vendors, procurement leads at agricultural cooperatives, regulatory affairs specialists at geofencing platform providers, and infrastructure inspection operations managers with secondary validation against FAA BVLOS waiver databases, EASA U-space implementation timelines, CAAC low-altitude economy policy documents, and semiconductor trade flow customs records. Bottom-up fleet deployment estimates and top-down software revenue aggregates were cross-referenced for triangulation.
Segment-weighting approaches distributed value across deployment architecture, solution specialization, end-user procurement authority, and application mission type throughout the projection horizon. Cloud-based versus edge-computing deployment splits, image processing versus flight control solution margins, and agricultural versus emergency responder end-user growth trajectories were modeled separately before reconciliation. CAGRs were derived from fitted adoption curves calibrated against regulatory sequencing milestones and payload technology diffusion patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory reversals in BVLOS authorization timelines or sustained GPU supply disruptions from Taiwan Strait logistics interruptions. Forecasts reflect assumptions regarding EASA U-space corridor rollout schedules and CAAC smart-city infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Enterprise Drone Management Solutions Market
UAV
Drone Data Management Market
UAV
Fixed Wing Military Drones Market
UAV
Global Drone Autopilots Market
UAV
UAV GNSS Antenna Market
UAV
Commercial Drone-Enabled Services Market
UAV
Global Drone Services Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Stratospheric Flying Drone Market
UAV
UAV Payload Market
UAV
Combat Drone Market
UAV
Middle-East and Africa Drones Market
UAV
Drone Delivery Services Market
UAV
Global Drone Data Services Market
UAV
Global Target Drone Market
UAV
Global Renewable Drones Market