
 Stratospheric Flying Drone Market | 2026-2036
Stratospheric Flying Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Stratospheric Flying Drone Market Insights
Modular payload architecture is decoupling airframe procurement from sensor and communications packages, letting buyers configure mission-specific stacks without vendor lock-in. AeroVironment leverages its long-standing Pentagon relationships to sustain defense revenue while branching into environmental monitoring. Skydio dominates small-unit autonomous navigation, while Kratos Defense & Security Solutions anchors military-grade stratospheric programs with hardened communication links.
Stratospheric flying drones operate at altitudes between 60,000 and 100,000 feet, where thin atmosphere demands lightweight composite structures and solar-electric or hydrogen fuel cell propulsion for multi-week endurance. These platforms serve as persistent pseudo-satellites for telecommunications relay, border surveillance, and atmospheric data collection. Solar-powered configurations lead the drone type category due to proven multi-day flight records, while hydrogen fuel cell variants represent the fastest-growing subsegment as energy density improvements extend operational range. Within applications, telecommunications draws the largest procurement volumes, though disaster management commands premium pricing for rapid-deployment contracts.
The FAA governs U.S. airspace access through Certificate of Authorization processes that constrain commercial stratospheric operations below military and research priority lanes. EASA's developing high-altitude UAS framework in Europe is reshaping product certification requirements, forcing manufacturers to demonstrate deconfliction algorithms and fault-tolerant communications. Japan's METI has issued draft guidance for beyond-visual-line-of-sight stratospheric flights, opening civilian telecom trials. Stakeholders must track which regulator moves first on unified traffic management standards, as that jurisdiction will likely set the template for global export compliance.
Market Dynamics
Modular payload architecture is fragmenting vendor power by decoupling airframe procurement from mission-specific sensor and communications stacks, forcing manufacturers to compete on integration speed rather than proprietary ecosystem lock-in.
Growth Catalysts
- FAA Streamlined Certification:The FAA's Certificate of Authorization pathways for high-altitude unmanned systems compress commercial deployment timelines and reduce regulatory friction for persistent pseudo-satellite operations.
- Telecom Operator Procurement:Japanese and South Korean carriers are expanding solar-powered platform procurement for rural connectivity gaps, creating anchor demand for multi-week endurance systems.
- Hydrogen Fuel Cell Advances:Energy density improvements in hydrogen fuel cell propulsion are extending operational range beyond solar-electric limitations, opening polar and winter missions.
Market Restraints
- Lightweight Composite Input Costs:Carbon fiber and advanced polymer supply concentration in East Asian manufacturing clusters exposes airframe producers to freight volatility and tariff exposure.
- Airspace Access Hierarchy:FAA priority lanes reserve stratospheric corridors for military and research operators, constraining commercial flight density below economically viable thresholds.
- Geostationary Satellite Substitution:LEO constellation deployments by SpaceX and Amazon's Project Kuiper threaten to undercut pseudo-satellite pricing for telecommunications relay applications.
Strategic Opportunities
- Disaster Response Premium Contracts:Rapid-deployment stratospheric platforms command pricing multiples in emergency telecommunications restoration, particularly in Pacific Ring of Fire nations.
- Atmospheric Data Collection:Climate monitoring agencies represent an underpenetrated buyer segment requiring standardized sensor packages for ozone and aerosol measurement.
- METI Beyond-Visual-Line-of-Sight Framework:Japan's draft civilian flight guidance opens telecom trials without military coordination requirements, creating a regulatory template for regional adoption.
Industry Challenges
- Aerostructure Engineering Talent Scarcity:The intersection of high-altitude aerodynamics and lightweight materials expertise concentrates in a handful of defense-adjacent research institutions, constraining workforce scaling.
- Deconfliction Algorithm Certification:EASA's fault-tolerant communications mandates require extensive flight-hour documentation for autonomous traffic management systems, extending product validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stratospheric Flying Drone Market |
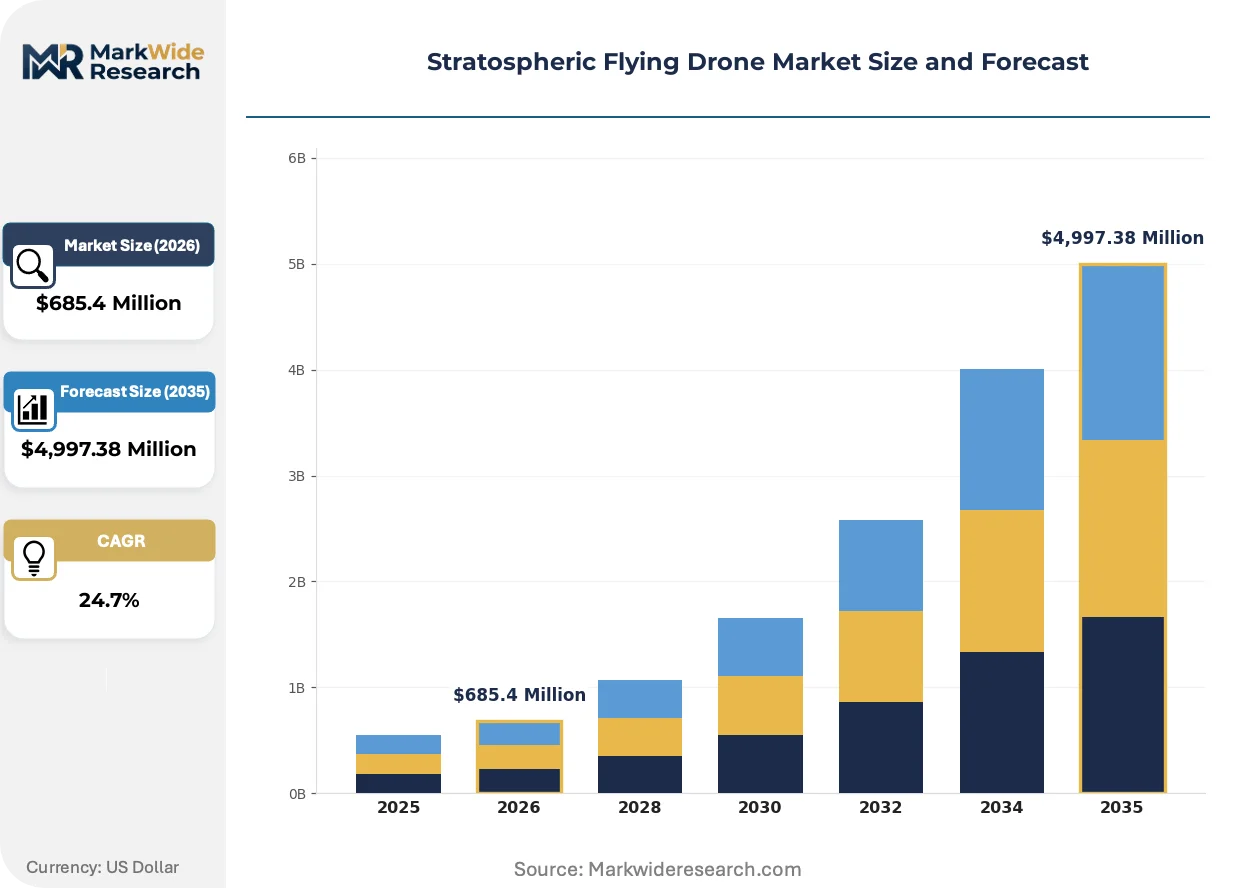
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $4,997.38 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drone Type: High-Altitude Long Endurance, Solar-Powered, Battery-Powered, Hydrogen Fuel Cell, Hybrid Application: Environmental Monitoring, Telecommunications, Surveillance, Disaster Management, Scientific Research End User: Telecom Operators, Government Agencies, Research Institutions, Security Firms, Weather Forecasting Organizations Deployment Mode: Autonomous, Remote Controlled, Semi-Autonomous, Networked Swarm, Manual Override |
| Companies Covered | Quantum Systems, Ascent AeroSystems, AeroVironment, Red Cat Holdings, Ondas Holdings, Skydio, Kratos Defense & Security Solutions, Skyfish, Jouav, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stratospheric Flying Drone Market Trends and Innovations
Three forces are restructuring competitive advantage in stratospheric platforms: propulsion technology diversification, regulatory framework fragmentation across jurisdictions, and buyer procurement model evolution toward mission-specific leasing.
Perovskite-silicon tandem solar cell technology is expanding into stratospheric drone energy systems by delivering higher conversion efficiency in low-light, high-altitude conditions. Telecom operators in Japan and South Korea are adopting these configurations for winter operations where traditional silicon arrays underperform. The technology is expanding into previously uneconomical seasonal markets and compressing the performance gap with hydrogen alternatives.
EASA's developing high-altitude UAS framework is mandating deconfliction algorithms and fault-tolerant communications for product certification. European manufacturers must now demonstrate autonomous traffic management capabilities before market entry. Stratospheric telecommunications platforms face the steepest compliance burden, with several consortia accelerating software development to meet draft requirements.
Defense and research agencies are consolidating procurement around flight-hour leasing rather than platform ownership, transferring operational risk to manufacturers. This shift favors vendors with in-house maintenance networks and rapid payload reconfiguration capabilities. The model is most visible in the western United States, where test range proximity enables quick turnaround contracts near Mojave and Edwards Air Force Base clusters.
Stratospheric Flying Drone Market Segmentation
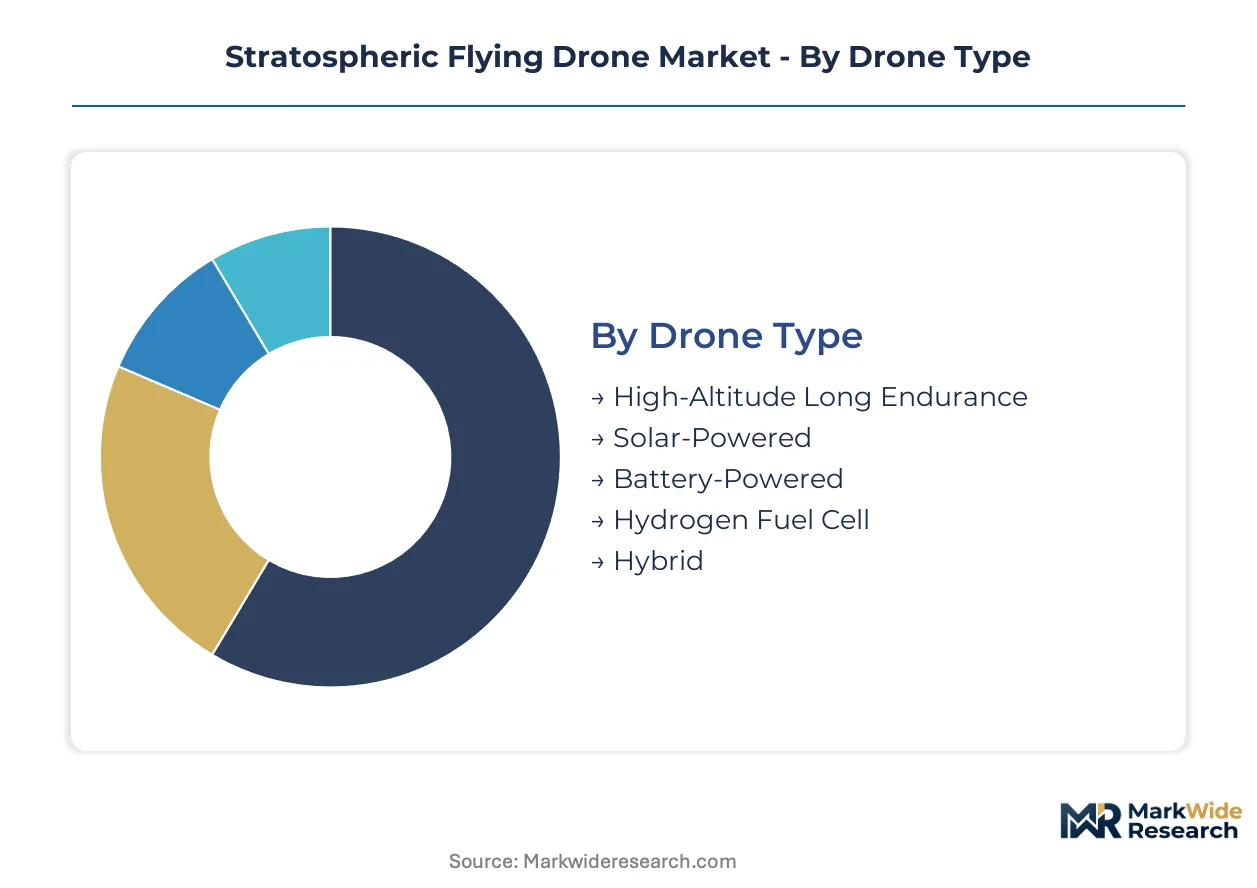
Stratospheric platform procurement splits between standalone systems for single-mission contracts and integrated fleet architectures where airframes slot into multi-node networks. Buyers configure around endurance requirements, payload modularity, and regulatory compliance pathways rather than purchasing standardized units.
Drone Type:
Integration depth varies sharply across propulsion architectures, with solar-electric and hydrogen fuel cell systems embedding into persistent pseudo-satellite networks while battery-powered units serve discrete, retrievable missions.
- Solar-Powered:Photovoltaic arrays on lightweight composite wings deliver multi-week endurance for telecommunications relay and atmospheric monitoring. Japanese and South Korean carriers anchor procurement volumes for rural connectivity gaps, drawn by proven flight records and declining per-hour operational costs.
- Hydrogen Fuel Cell:Proton-exchange membrane stacks achieve higher energy density than batteries, extending range into polar latitudes and winter operations where solar flux drops. The subsegment is climbing the fastest as fuel cell stack weight reductions and cold-start reliability improvements open seasonal markets previously closed to stratospheric platforms.
- High-Altitude Long Endurance:Purpose-built airframes optimized for 60,000-100,000 foot operations with redundant control systems and hardened avionics. Defense contractors dominate procurement for border surveillance missions.
- Battery-Powered:Lithium-sulfur and solid-state configurations serve short-duration scientific sampling where rapid climb rates and payload flexibility outweigh endurance requirements. Research institutions in the western United States cluster procurement near Mojave test ranges.
- Hybrid:Dual-mode systems combining solar generation with hydrogen storage for overnight operations, targeting telecom operators requiring 24/7 coverage without ground infrastructure dependency.
Solar-powered configurations lead volumes today; hydrogen fuel cell variants are gaining share fastest.
Application:
Cost tier stratification separates premium-priced rapid-deployment contracts from volume-driven persistent service agreements, with disaster response and telecommunications occupying opposite ends of the pricing spectrum.
- Telecommunications:Persistent pseudo-satellite relay for rural broadband and emergency backup commands the largest procurement volumes. Japanese carriers under METI guidance are expanding fleet procurement for mountainous terrain and island chains where fiber deployment remains uneconomical.
- Disaster Management:Rapid-deployment stratospheric platforms restore cellular connectivity within hours of infrastructure damage. Pacific Ring of Fire nations pay pricing multiples for pre-positioned contracts guaranteeing four-hour activation windows.
- Environmental Monitoring:Standardized sensor packages track ozone concentrations, aerosol distributions, and greenhouse gas fluxes. Climate research agencies represent an underpenetrated buyer segment with growing procurement standardization.
- Surveillance:Military and security applications demand hardened communication links and encrypted data transmission, with procurement concentrated near Edwards Air Force Base and affiliated test ranges.
- Scientific Research:Atmospheric physics and astronomy missions require payload modularity for instrument swapping between flights, favoring vendors with rapid reconfiguration capabilities.
Telecommunications commands the steepest expansion trajectory; disaster management captures the highest margin per flight hour.
End User:
Customer type determines contract structure, with government agencies favoring cost-plus development agreements while telecom operators shift toward flight-hour leasing to transfer operational risk.
- Telecom Operators:NTT Docomo, SK Telecom, and rural carriers in Japan and South Korea are consolidating procurement around multi-year service contracts rather than platform ownership, requiring vendors to maintain in-house maintenance networks.
- Government Agencies:Defense departments and border control authorities specify hardened communication links and fault-tolerant autonomy, with FAA Certificate of Authorization pathways constraining vendor selection to established defense contractors.
- Research Institutions:Universities and national laboratories prioritize payload modularity and rapid turnaround, clustering procurement near Mojave and Edwards test ranges where airspace access is pre-coordinated.
- Security Firms:Private sector surveillance contractors demand encrypted data transmission and autonomous deconfliction capabilities, with EASA's developing high-altitude UAS framework reshaping product certification requirements for European market entry.
- Weather Forecasting Organizations:Meteorological agencies require standardized sensor packages for upper-atmosphere data collection, with procurement concentrated in nations lacking satellite meteorology capabilities.
Government agencies anchor current procurement volumes; telecom operators are shifting contract structures fastest toward operational leasing.
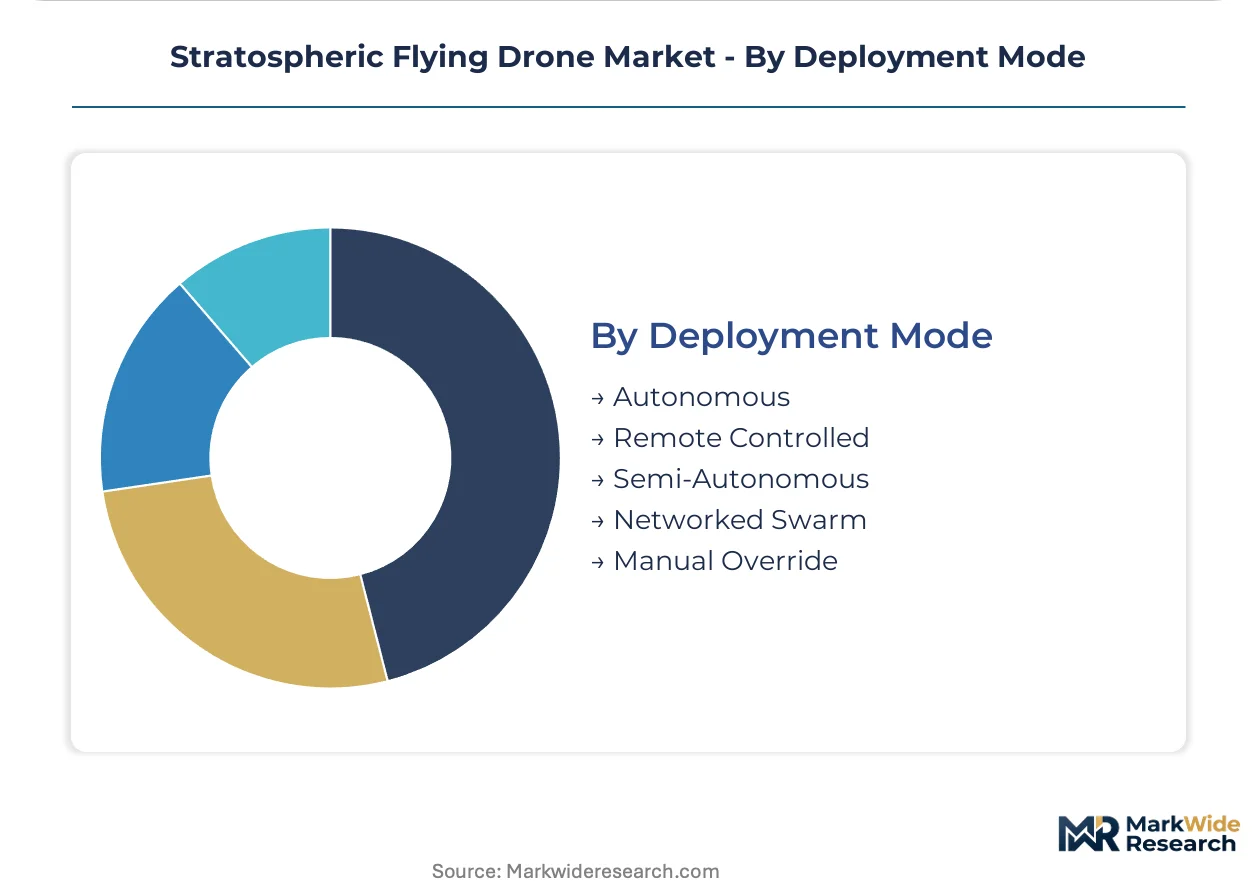
Deployment Mode:
Maturity gradients separate fully certified autonomous systems from developmental networked swarm architectures, with regulatory approval timelines determining commercial availability.
- Autonomous:Pre-programmed flight paths with minimal ground intervention enable multi-week endurance missions. EASA mandates deconfliction algorithms and fault-tolerant communications for certification, extending validation cycles for European market entry.
- Semi-Autonomous:Human oversight for critical decision points balances operational autonomy with regulatory compliance, dominating current commercial deployments under FAA Certificate of Authorization frameworks.
- Remote Controlled:Beyond-visual-line-of-sight operation via satellite link serves missions requiring real-time tasking changes, with Japan's METI draft guidance enabling civilian trials without military coordination.
- Networked Swarm:Coordinated multi-platform formations for distributed sensing and resilient communications remain in demonstration phase, with defense research contracts driving technology maturation near Edwards Air Force Base.
- Manual Override:Pilot intervention capability for emergency recovery satisfies insurance and liability requirements, embedded as backup in most commercial systems regardless of primary autonomy level.
Autonomous systems lead commercial deployment today; networked swarm architectures are advancing through demonstration contracts fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The stratospheric flying drone industry traces its operational lineage to the western United States, where Cold War-era aerospace infrastructure at Mojave and Edwards Air Force Base established the test range protocols and airspace access frameworks that now govern high-altitude unmanned systems worldwide.
United States
The FAA's Certificate of Authorization pathways compress commercial deployment timelines for persistent pseudo-satellite operations. Defense contracts cluster near Edwards Air Force Base in California, where hardened communication links and fault-tolerant autonomy systems undergo validation. Flight-hour leasing models now dominate procurement, transferring operational risk from government agencies to manufacturers with rapid turnaround capabilities.
Japan
NTT Docomo and rural carriers anchor regional procurement volumes for mountainous terrain and island chain connectivity gaps. METI's draft guidance for beyond-visual-line-of-sight stratospheric flights enables civilian telecom trials without military coordination requirements. Perovskite-silicon tandem solar cell adoption is expanding into previously uneconomical winter markets as carriers seek multi-week endurance systems.
South Korea
SK Telecom drives solar-powered platform procurement for rural broadband deployment where fiber infrastructure remains uneconomical. The national regulator has aligned certification requirements with emerging EASA fault-tolerant communications standards, accelerating product validation for European export compliance. Seoul-based maintenance networks support the shift toward operational leasing contracts.
Germany
EASA's developing high-altitude UAS framework mandates deconfliction algorithms and autonomous traffic management capabilities for market entry. Stuttgart and Munich aerospace clusters concentrate engineering talent for lightweight composite structures and hydrogen fuel cell propulsion integration. Several consortia are accelerating software development to meet draft certification requirements.
United Kingdom
Climate research agencies represent growing procurement demand for standardized atmospheric sensor packages tracking ozone concentrations and aerosol distributions. The Civil Aviation Authority is harmonizing certification pathways with EASA's fault-tolerant communications mandates. Oxford and Cambridge research institutions cluster near pre-coordinated airspace corridors for rapid payload reconfiguration missions.
Stratospheric Flying Drone Market Competitive Landscape
Premium-margin players sit above commodity-margin players across defense certification and multi-week endurance capabilities. The vendor base fragments between established Pentagon contractors with hardened communication expertise and emerging specialists in autonomous navigation and rapid payload reconfiguration. Three archetypes dominate: defense-anchored integrators with airspace access privileges, solar-electric endurance specialists, and hydrogen propulsion innovators. Competitive moves concentrate on strategic partnerships for regulatory compliance acceleration and geographic expansion into METI-guided Japanese telecom trials.
Within the defense-contractor archetype, Kratos Defense & Security Solutions and AeroVironment exemplify established Pentagon relationships that sustain revenue while branching into environmental monitoring. Skydio occupies a distinct position in small-unit autonomous navigation, representing the navigation-software specialist tier. These three companies illustrate how vendor power is fragmenting as modular payload architecture decouples airframe procurement from mission-specific sensor stacks.
| Leading Market Players |
|---|
| Quantum Systems |
| Ascent AeroSystems |
| AeroVironment |
| Red Cat Holdings |
| Ondas Holdings |
| Skydio |
| Kratos Defense & Security Solutions |
| Skyfish |
| Jouav |
| Others |
Pricing and Supply Chain Analysis
High-altitude aerodynamics and lightweight composite engineering talent concentrates in defense-adjacent research clusters near Mojave and Edwards Air Force Base, creating labor-cost differentials that widen pricing spreads between premium defense-certified systems and commercial-tier platforms.
Pricing Analysis
Flight-hour leasing models now dominate procurement structures, transferring operational risk from government agencies and telecom operators to manufacturers with rapid turnaround capabilities. Price differentiation rests on certification grade—FAA Certificate of Authorization pathways command substantial premiums over experimental permits—and payload modularity depth. Cost compression in battery-powered research tiers intensifies as lithium-sulfur cell production scales, while hydrogen fuel cell configurations capture pricing power from seasonal market exclusivity. Telecom operators in Japan and South Korea exhibit lowest price sensitivity due to rural connectivity gap urgency; research institutions near Mojave test ranges drive hardest bargain negotiations.
Supply Chain Analysis
Single-source vulnerability sits with carbon fiber prepreg manufacturing concentrated in Japan, South Korea, and select US defense contractors, exposing airframe producers to freight volatility and tariff exposure. Raw material dependencies center on aerospace-grade carbon fiber, perovskite-silicon tandem solar cells, and proton-exchange membrane fuel cell stacks. Supply chain risk manifests through East Asian manufacturing cluster concentration and dual-use export control restrictions on hardened avionics components. Distribution runs through direct manufacturer-to-operator contracts for defense and telecom verticals, with research institutions procuring via national laboratory consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where persistent pseudo-satellite endurance specifications and fault-tolerant autonomy certifications command widening premiums over commodity drone platforms.
For Market Incumbents: Deploy modular payload architecture roadmaps to decouple airframe refresh cycles from sensor obsolescence, countering LEO constellation substitution threats from SpaceX and Amazon's Project Kuiper. Deepen hydrogen fuel cell integration capabilities ahead of polar and winter mission demand inflections. Anchor defense revenue through Edwards Air Force Base proximity while branching into METI-guided Japanese telecom trials. For New Entrants and Emerging Players: Direct-to-operator digital sales channels bypass incumbent Pentagon relationship moats for commercial-tier environmental monitoring and rapid-deployment disaster response contracts. White-space concentrates in atmospheric data collection for climate agencies lacking standardized sensor procurement frameworks. Target Pacific Ring of Fire nations with pre-positioned emergency telecommunications restoration offerings. For Investors and Strategic Acquirers: Valuations sit cheapest among hydrogen propulsion innovators with demonstrated cold-start reliability and fuel cell stack weight reduction trajectories. Long-term viability hinges on regulatory template adoption—whichever jurisdiction moves first on unified traffic management standards will set global export compliance requirements. Watch EASA deconfliction algorithm certification timelines as inflection signal for European market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite-Silicon Tandem Cell Integration | Expands addressable seasonality for Japanese carriers operating in low-light winter conditions. |
| Hydrogen Fuel Cell Stack Weight Reduction | Opens polar latitudes previously closed to solar-electric endurance limitations. |
| Deconfliction Algorithm Certification Investment | Accelerates EASA market entry for autonomous traffic management capabilities. |
| Flight-Hour Leasing Model Expansion | Captures telecom operator shift from platform ownership toward operational risk transfer. |
| METI Regulatory Template Alignment | Positions vendors for regional adoption of Japan's beyond-visual-line-of-sight civilian framework. |
Research Methodology
Direct dialogue with stratospheric platform engineering directors, FAA certification specialists, telecom procurement leads at NTT Docomo and SK Telecom, and climate research agency instrument scientists grounded qualitative findings in operational constraints. Secondary validation drew from FAA Certificate of Authorization filings, EASA high-altitude UAS framework drafts, METI guidance documents, and national laboratory procurement records. Bottom-up segment sizing triangulated against top-down market construction across propulsion architecture, application vertical, and end-user contract structure dimensions.
Bottom-up modeling built from individual platform unit economics, flight-hour leasing rate trajectories, and regional procurement pipeline visibility, while top-down analysis cross-checked against macro aerospace and telecommunications infrastructure investment flows. Segmentation dimensions spanned drone type, application, end user, and deployment mode maturity, with propulsion technology diversification and regulatory framework fragmentation tracked as cross-cutting dynamics. CAGRs derived from installed base growth, replacement cycle compression, and pricing power evolution in premium-tier specifications.
Regulatory approval delays, LEO constellation deployment acceleration, and composite material supply disruptions are the dominant revision risks to modeled outcomes. Forecasts embed assumptions on airspace access liberalization timelines and hydrogen fuel cell reliability maturation curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Home Security Drone Market
UAV
Industrial Drones Market
UAV
Autonomous Aircraft Cameras Market
UAV
Drone Inspection Service Market
UAV
GCC Drone Pilot Training Market
UAV
Asia-Pacific Drone Software Market
UAV
Fuel Cell UAV Market
UAV
Global VTOL UAV Market
UAV
Asia-Pacific Tethered Drone Market
UAV
Global Multirotor UAV Market
UAV
Ultra Micro Drone Market
UAV
Latin America Small UAV Market
UAV
Global Smartphone Controlled Drone Market
UAV
Drone Flight Controller System Market
UAV
Portable Drone Market
UAV
Global Stratospheric UAV Payload Technology Market