
 Delivery Drones Market | 2026-2036
Delivery Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Delivery Drones Market Intelligence
A divergence in capital allocation for proprietary logistics networks versus open-platform hardware manufacturing is bifurcating the competitive landscape. Zipline International Inc. specializes in integrated healthcare delivery systems, particularly in Africa and the United States. Wing Aviation LLC focuses on last-mile delivery for retail and food in specific suburban testbeds. Meanwhile, Amazon.com, Inc. develops its Prime Air service as a vertically integrated component of its e-commerce fulfillment infrastructure.
Delivery drones are unmanned aerial vehicles (UAVs) engineered for the autonomous transport of goods, typically under 10 kg. These systems utilize advanced navigation and sensor suites for safe operation in complex airspace, aiming to automate last-mile logistics. Multi-rotor designs currently lead the food delivery application due to their vertical takeoff and landing capabilities in dense urban environments. Hybrid models, which blend VTOL with efficient fixed-wing flight, represent the fastest-growing product type for longer-range pharmaceutical transport.
Regulatory frameworks from the Federal Aviation Administration (FAA) in the United States and the European Union Aviation Safety Agency (EASA) are critical. These bodies define the certification pathways for aircraft and the operational rules for beyond visual line of sight (BVLOS) flights, directly controlling market access. Stakeholder success now depends on securing operational approvals within these evolving unmanned traffic management systems and addressing public perception regarding safety and privacy.
Market Dynamics
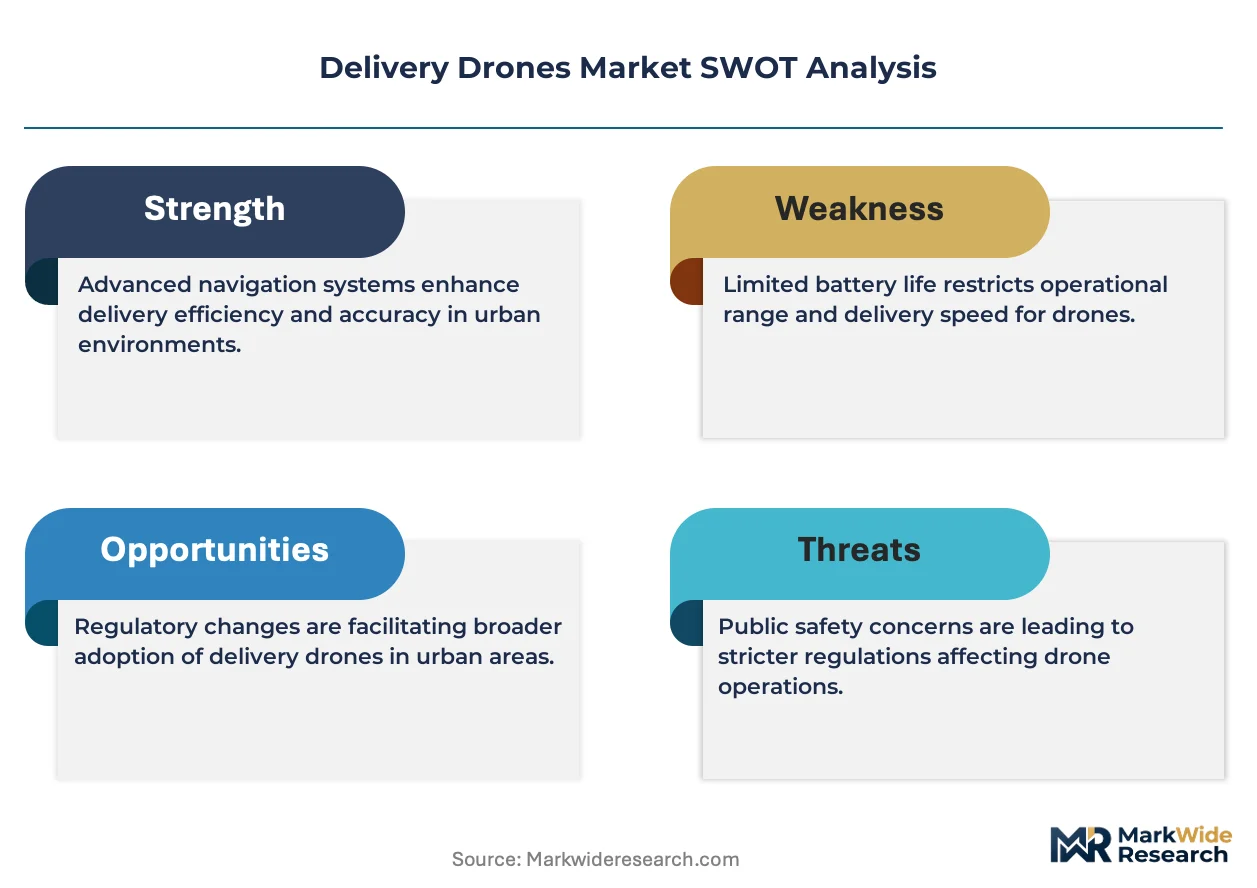
The central force is the tension between rapid technological advancement in autonomous flight and the cautious pace of regulators like the FAA and EASA in certifying these systems for widespread public operation.
Growth Catalysts
- BVLOS Regulations:Evolving rules from the FAA for beyond visual line of sight (BVLOS) operations unlock longer routes, enabling expansion into suburban and rural markets.
- Pharmaceutical Demand:The need to transport time-sensitive medical goods provides a critical use case in regions with poor ground infrastructure, including parts of Africa.
- Hybrid VTOL Systems:Hybrid aircraft designs blend vertical takeoff with efficient fixed-wing flight, enabling longer-range missions for medical and commercial cargo.
Market Restraints
- High Capital Costs:Significant upfront investment for drone fleets and ground control infrastructure creates a high barrier to entry for smaller logistics operators.
- Technical Limitations:Current battery technology constrains payloads, typically under 10 kg, and limits flight times, restricting both range and the types of goods delivered.
- Regulatory Fragmentation:Inconsistent certification pathways between key aviation authorities like the FAA and EASA create uncertainty and delay widespread commercial deployment.
Strategic Opportunities
- Underpenetrated Geographies:Southeast Asia's archipelagos offer an opportunity for inter-island delivery of e-commerce and medical goods, bypassing congested freight routes.
- Middle-Mile Logistics:Drones can shuttle goods between suburban fulfillment centers and urban micro-hubs, creating a new middle-mile application beyond last-mile delivery.
- 5G Network Integration:Integrating with 5G networks provides low-latency communication for high-density unmanned traffic management systems needed in urban airspace.
Industry Challenges
- Public Acceptance and Safety:Overcoming public concerns over noise, privacy from onboard cameras, and safety risks from operations over populated areas remains a major hurdle.
- System Integration Complexity:Integrating autonomous drone platforms with existing enterprise resource planning (ERP) and warehouse management systems (WMS) is a significant technical and operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Delivery Drones Market |
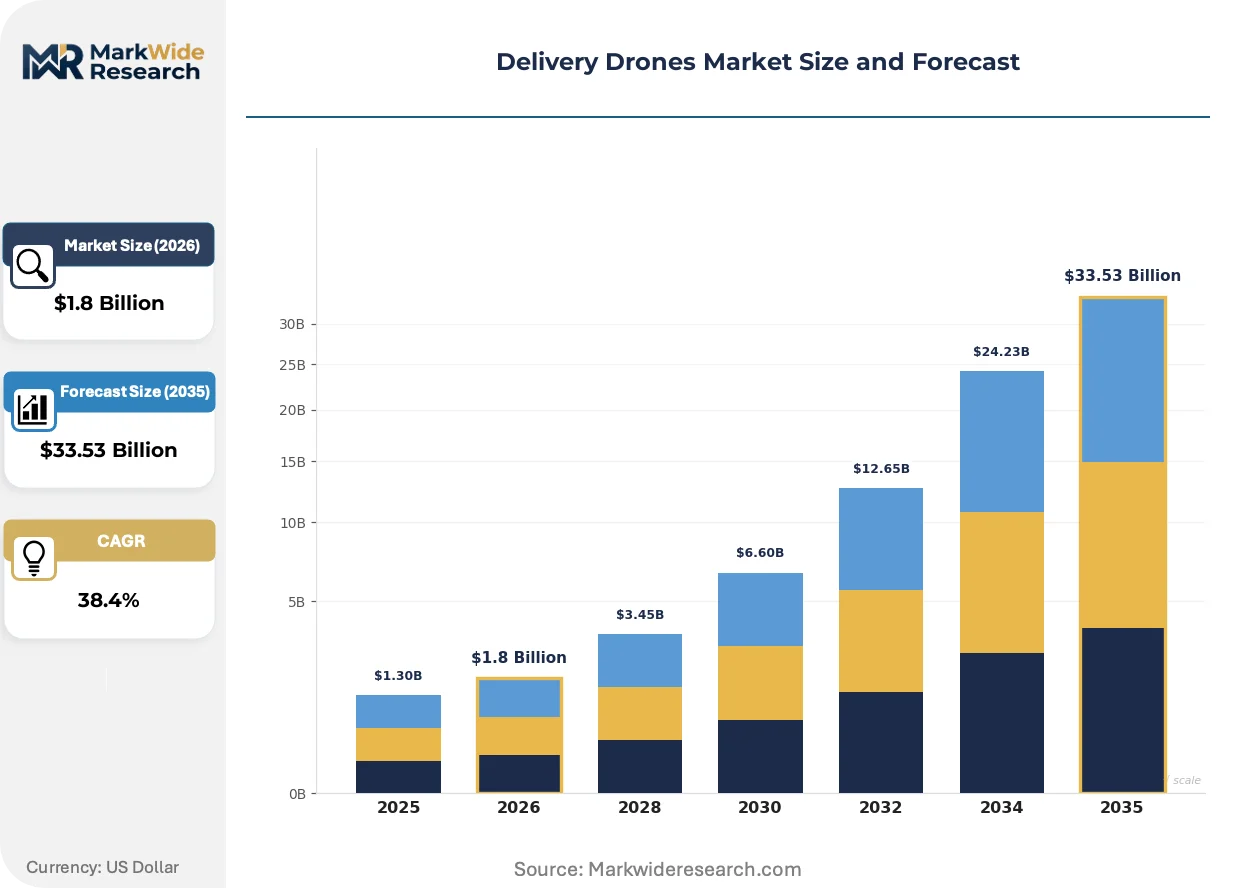
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $33.53 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Rotor, Fixed-Wing, Hybrid, Single-Rotor, Tethered Application: E-Commerce, Food Delivery, Pharmaceutical Transport, Postal Service, Industrial Supply Payload Capacity: Up to 2 kg, 2-5 kg, 5-10 kg, Above 10 kg End User: Logistics Companies, Healthcare Providers, Retailers, Manufacturing Plants, Government Agencies |
| Companies Covered | Zipline International Inc., Wing Aviation LLC, Amazon.com, Inc., United Parcel Service of America, Inc., Matternet Inc., Wingcopter GmbH, SZ DJI Technology Co., Ltd., FedEx Corporation, Airbus SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Delivery Drones Market Strategic Shifts & Innovations
Operational focus is shifting from technology demonstration to proving commercial viability. The primary trend involves integrating drone networks into existing logistics chains to automate specific segments of the supply route, from warehouse to consumer.
Onboard sense-and-avoid systems, combining LiDAR, radar, and computer vision, provide real-time obstacle detection for safe navigation. Healthcare and retail logistics providers are adopting these systems to meet safety requirements for urban and suburban flights. This advanced sensor fusion is fragmenting the market by creating a premium tier of certified, autonomous aircraft distinct from less-capable models.
The European Union Aviation Safety Agency (EASA) has established a risk-based regulatory framework with distinct 'specific' and 'certified' operational categories. This structure creates a clear pathway for companies to gain approval for complex operations like BVLOS flights in populated areas. Drone operators targeting Europe now align hardware and safety cases with EASA’s Specific Operations Risk Assessment (SORA) methodology.
A shift from outright drone purchase to a 'Drones-as-a-Service' (DaaS) model is gaining traction among end-users. This subscription-based approach allows retailers and healthcare providers to access delivery capabilities without the high upfront capital investment and operational overhead. This service-oriented procurement model is most visible in the United States and Australia for last-mile food and pharmacy deliveries.
Delivery Drones Market Segmentation
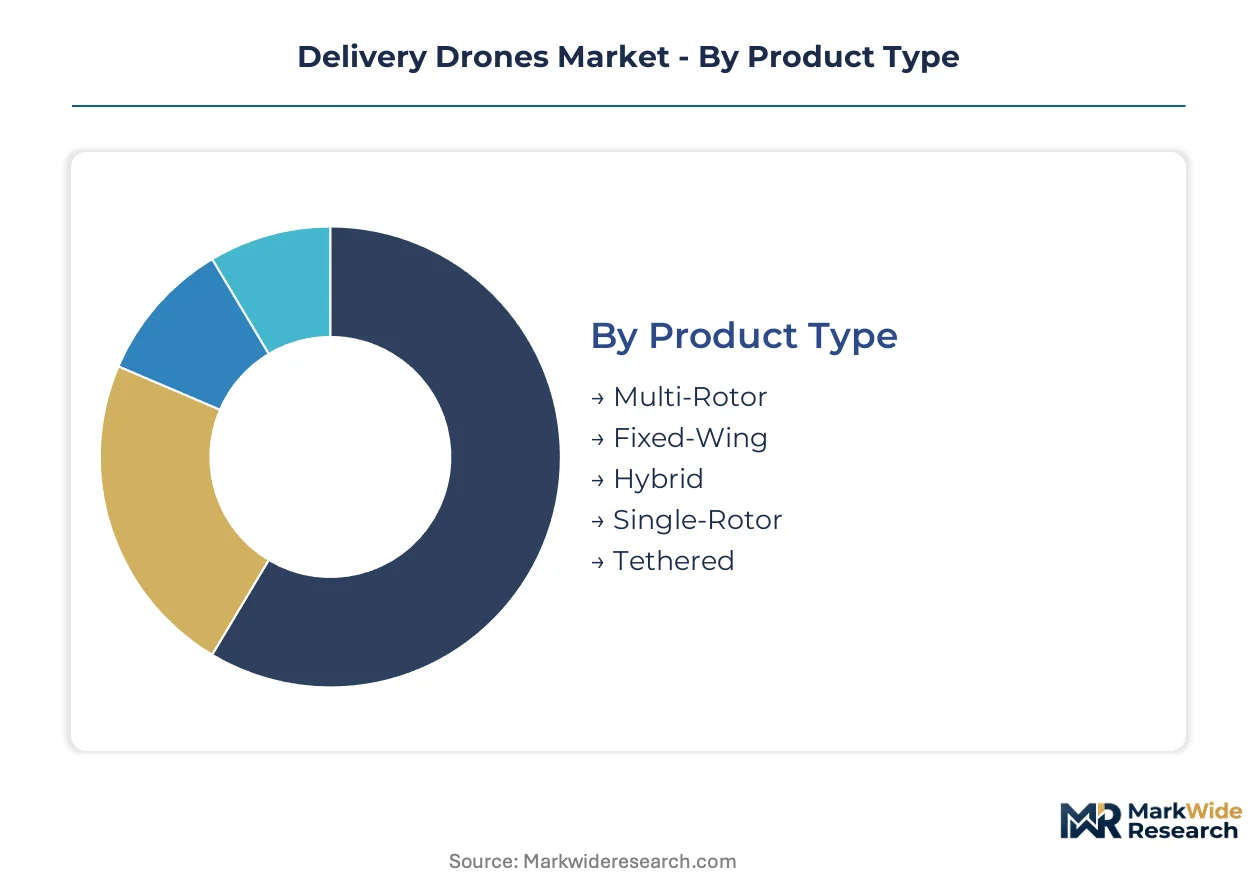
The Delivery Drones Market segmentation provides a granular view of distinct operational requirements shaping product development and service deployment. Understanding these categories reveals where technological innovation intersects with specific end-user needs and regulatory compliance. This analysis highlights specialized capabilities required for diverse delivery missions.
Product Type:
Substitution pressure is most pronounced for traditional ground-based last-mile delivery, as drone product types offer novel operational efficiencies and speed, challenging existing paradigms.
- Hybrid:These aircraft integrate VTOL with efficient fixed-wing flight for longer ranges and higher speeds. Demand concentrates in pharmaceutical transport for time-sensitive medical supplies across Australia and parts of Africa.
- Multi-Rotor:Featuring multiple propellers, these drones excel in precision hovering and vertical maneuverability within urban spaces. Food delivery applications in United States testbeds primarily utilize these designs.
- Fixed-Wing:These drones use a single wing for lift, requiring a runway for takeoff, offering extended range and endurance.
- Single-Rotor:Similar to helicopters, these designs use one large rotor for lift, capable of heavier payloads.
- Tethered:Connected to a ground station, these drones receive continuous power and data, primarily used for extended surveillance.
Multi-Rotor designs retain volume leadership in current last-mile operations; Hybrid models hold the steepest expansion curve for longer-range logistics.
Application:
The cost tier for delivery drone applications varies, influenced by cargo value, urgency, and operational complexity. High-value goods justify premium pricing, while bulk deliveries seek cost-efficiency.
- Pharmaceutical Transport:This application involves rapid delivery of medical supplies, vaccines, and samples, often to remote or emergency locations. Demand is strong in parts of Africa for critical integrated healthcare delivery systems.
- E-Commerce:Drones facilitate last-mile delivery of online retail purchases, aiming to reduce delivery times and operational costs. Amazon.com, Inc. develops Prime Air targeting suburban areas in the United States.
- Food Delivery:This segment transports prepared meals from restaurants to consumers, primarily within urban and suburban areas.
- Postal Service:Drones supplement traditional postal networks by delivering mail and small packages to remote or difficult-to-access locations.
- Industrial Supply:This application delivers spare parts or critical components to industrial sites, enhancing operational continuity.
Pharmaceutical Transport commands the highest margin potential; E-Commerce applications drive the largest volume demand.
Payload Capacity:
Payload capacity dictates the volume of goods a delivery drone can transport, influencing operational efficiency and the types of cargo economically delivered.
- 2-5 kg:This range suits many last-mile operations, accommodating most food orders, small e-commerce packages, and medical supplies. Demand concentrates in suburban regions of the United States and Australia.
- 5-10 kg:Drones in this category transport larger e-commerce parcels or bulkier medical equipment, expanding middle-mile logistics. These systems shuttle goods between suburban fulfillment centers and urban micro-hubs.
- Up to 2 kg:This lighter payload is suitable for express delivery of very small, high-value items like documents or specific medical samples.
- Above 10 kg:This heavy-lift capacity emerges for specialized industrial logistics or bulk cargo, requiring powerful drone designs.
The 2-5 kg segment offers broad operational flexibility; the 5-10 kg segment is expanding most quickly for middle-mile applications.
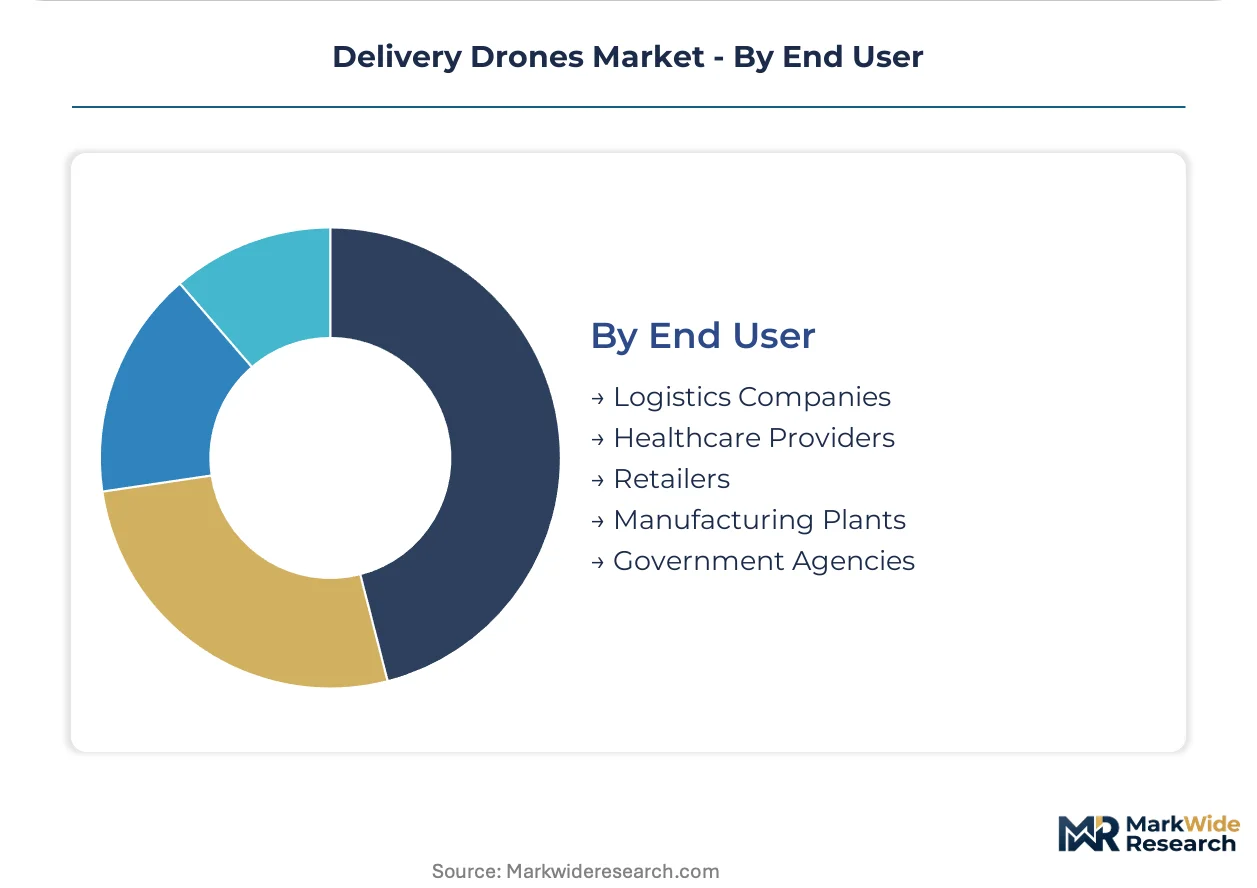
End User:
Different end-user types drive distinct requirements for drone delivery systems, ranging from large-scale logistical integration to specialized, high-urgency medical transport.
- Logistics Companies:These entities integrate drone technology into existing supply chains to enhance last-mile efficiency and access hard-to-reach areas. They seek DaaS models to avoid high upfront capital costs in the United States.
- Healthcare Providers:Hospitals, clinics, and pharmaceutical distributors utilize drones for rapid, secure transport of time-sensitive medical goods like organs, blood, and vaccines. Zipline specializes in integrated healthcare delivery systems in Africa and the United States.
- Retailers:E-commerce giants and local businesses deploy drones for direct-to-consumer delivery, aiming for faster shipping and improved customer satisfaction.
- Manufacturing Plants:Drones support internal logistics by transporting parts, tools, and samples between different sections of a large facility.
- Government Agencies:Public sector entities use drones for disaster relief, surveillance, and delivering critical supplies.
Logistics Companies represent the largest strategic investment in drone delivery infrastructure; Healthcare Providers demonstrate the highest value-per-delivery use case.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for delivery drones varies significantly; time-sensitive pharmaceutical transport often justifies premium pricing, while high-volume e-commerce applications require cost-efficiency. This divergence shapes regional investment, with some areas prioritizing rapid medical deliveries and others focusing on broad consumer logistics. Regulatory environments also influence market development across continents.
United States
United States demand for delivery drones is strong in last-mile food delivery and e-commerce, with significant interest from logistics companies. The Federal Aviation Administration (FAA) continually refines BVLOS regulations, enabling expanded operational areas for drone services. Suburban testbeds across states like North Carolina and Texas are actively deploying drone delivery for retail and food.
Australia
Australian demand concentrates in suburban and rural regions where ground logistics are less efficient, particularly for medical supplies and small e-commerce packages. The Civil Aviation Safety Authority (CASA) provides frameworks for safe drone integration into existing airspace, facilitating commercial deployments. Regional centers in Queensland and Victoria are experiencing increased drone activity for pharmacy and food deliveries.
Germany
German demand for delivery drones is driven by a focus on logistics innovation and the potential for efficient pharmaceutical distribution across Europe. The European Union Aviation Safety Agency (EASA) establishes a clear risk-based regulatory framework, defining pathways for complex BVLOS operations. Research and development hubs in Bavaria and North Rhine-Westphalia are advancing drone technology for commercial applications.
Rwanda
Rwanda demonstrates high demand for delivery drones in critical pharmaceutical transport, especially for reaching remote or underserved medical facilities. The Rwanda Civil Aviation Authority (RCAA) has proactively supported drone operations, creating an enabling environment for rapid medical logistics. Zipline’s integrated healthcare delivery systems operate from distribution centers near Kigali, serving numerous clinics daily.
Delivery Drones Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the delivery drones market, creating a bifurcated competitive landscape. The market exhibits a tiered structure, with integrated logistics giants contrasting with specialized hardware manufacturers and service providers. Strategic archetypes include vertically integrated e-commerce players, dedicated healthcare delivery system providers, and last-mile logistics specialists. Companies pursue strategic partnerships and technology licensing to expand their operational footprints and overcome regulatory hurdles, while some focus on geographic expansion.
Specialists in integrated delivery systems, Zipline International Inc. and Wing Aviation LLC, exemplify focused operational models for specific use cases. Zipline International Inc. anchors the healthcare delivery segment, demonstrating advanced capabilities in medical logistics in Africa and the United States. Wing Aviation LLC occupies a position as a last-mile delivery provider for retail and food, primarily in suburban testbeds. Amazon.com, Inc. sits within the vertically integrated e-commerce fulfillment archetype, developing its Prime Air service as an in-house capability.
| Leading Market Players |
|---|
| Zipline International Inc. |
| Wing Aviation LLC |
| Amazon.com, Inc. |
| United Parcel Service of America, Inc. |
| Matternet Inc. |
| Wingcopter GmbH |
| SZ DJI Technology Co., Ltd. |
| FedEx Corporation |
| Airbus SE |
| Others |
Cost & Logistics Intelligence
Operational scale in drone fleet deployment and manufacturing directly influences supply concentration among integrated logistics providers, thereby establishing competitive price floors for delivery services. This concentration also impacts hardware costs for new entrants.
Pricing Analysis
After-sales service contracts and software licenses for unmanned traffic management systems drive significant lifetime value for drone manufacturers. The Drones-as-a-Service (DaaS) model represents the dominant pricing structure, offering subscription-based access to delivery capabilities. Price differentiation stems from certification levels (e.g., FAA BVLOS approvals) and specialized payload capacities for medical transport. Pricing pressure stems from increasing competition among DaaS providers and the push for operational efficiency. Logistics companies, seeking to avoid high capital expenditures, exhibit the highest price sensitivity for DaaS offerings.
Supply Chain Analysis
China, the United States, and Germany anchor the manufacturing and advanced component supply for delivery drones. Raw material dependencies include specialized lightweight composites, high-performance lithium-ion batteries, and precision sensor suites (LiDAR, radar). Single-source vulnerability for advanced navigation sensors presents a structural supply chain risk. Distribution runs primarily through direct sales to large logistics operators and healthcare providers, alongside DaaS models for smaller end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The delivery drones market requires a strong substitution defense, as incumbents must navigate the threat from established ground-based logistics networks and evolving automated vehicle technologies.
For Market Incumbents: Compound investment in securing BVLOS operational approvals from regulators like the FAA and EASA to expand service areas. Deepen integration capabilities with existing enterprise resource planning (ERP) and warehouse management systems (WMS) to automate supply chain segments. This strategy addresses the cautious regulatory pace and technical integration complexity. Strategic partnerships for 5G network integration represent a critical lever for high-density urban operations.
For New Entrants and Emerging Players: Anchor in underpenetrated geographies, such as Southeast Asia's archipelagos, for inter-island e-commerce and medical deliveries. Target the middle-mile logistics segment, shuttling goods between suburban fulfillment centers and urban micro-hubs. Develop specialized Drones-as-a-Service (DaaS) offerings to mitigate high upfront capital costs for potential clients. This approach leverages the demand for time-sensitive medical goods in regions with poor ground infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Drones-as-a-Service (DaaS) providers with established operational track records. The market exhibits long-term viability driven by the automation of last-mile and middle-mile logistics. Acquisition targets should include specialized DaaS providers holding extensive operational approvals in key regions like the United States or Australia. Widespread FAA and EASA BVLOS approvals for urban airspace serve as a key signal to watch for accelerated market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in BVLOS Certification | Securing FAA and EASA approvals unlocks longer routes, expanding operational reach for delivery drones. |
| Develop Hybrid VTOL Platforms | Blending fixed-wing efficiency with VTOL capabilities extends range for pharmaceutical transport applications. |
| Integrate with 5G Networks | Low-latency 5G communication is essential for high-density unmanned traffic management in urban airspace. |
| Expand Drones-as-a-Service (DaaS) | This subscription model reduces capital expenditure for end-users, facilitating broader adoption in logistics. |
| Target Middle-Mile Logistics | Shuttling goods between fulfillment centers and micro-hubs creates a new high-volume application for drones. |
Research Approach
Initial hypotheses were tested against primary input from drone manufacturers' R&D leads, logistics operators' procurement managers, aviation regulators, and healthcare supply chain managers. Secondary validation involved reviewing publications from the FAA and EASA, company financial reports, and industry association analyses. This approach utilized both bottom-up and top-down triangulation.
Variance decomposition isolated growth drivers across the analysis window, informing the quantitative model. The segmentation dimensions modeled included product type, application, payload capacity, end user, and regional regulatory environment. Compound annual growth rates were derived from historical data and projected market trends. Regulatory approval timelines for BVLOS operations and battery energy density improvements served as key forecast inputs.
Underlying assumptions cover technological maturity and regulatory progression, with deviation risk concentrated in unforeseen regulatory delays or shifts in public acceptance. Forecasts reflect these assumptions. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
North America Drone Software Market
UAV
US Commercial Drone Market
UAV
Rc Helicopter Market
UAV
Tethered Drones Market
UAV
UAV Lidar Market
UAV
Global Smartphone Controlled Drone Market
UAV
Global Smart Commercial Drones Market
UAV
Global Electric Drone Market
UAV
Aerial Smart Weapons Market
UAV
Fixed-Wing VTOL UAV Market
UAV
UAV Battery Market
UAV
Asia Pacific Commercial Drone Market
UAV
Utility Drone Market
UAV
Tactical UAV Market
UAV
Drone Leasing Market
UAV
Europe Drone Light Shows Market