
 Electric Glider Market | 2026-2036
Electric Glider Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Glider Market Foresight
Buyer concentration in the electric glider market is shifting from fragmented individual hobbyists toward institutional procurement by flight schools and aerospace research programs. Pipistrel leverages its Slovenian manufacturing base to dominate the self-launcher segment across European training academies. Diamond Aircraft Industries anchors the motor glider category through its Austrian engineering heritage and established certification pathways. Jonker Sailplanes competes in the high-performance sailplane niche with advanced composite construction techniques refined in South Africa.
An electric glider is a fixed-wing aircraft equipped with an electric propulsion system for self-launching or sustaining flight, typically employing lithium-ion battery packs driving compact motors with outputs between 30 and 100 kilowatts, designed primarily for recreational aviation, pilot training, and aerodynamic research with minimal noise and zero direct emissions. The fixed-wing segment leads unit shipments due to simpler airframe economics and established certification frameworks, while the self-launcher category captures the fastest growth as battery energy density improves and clubs retire aging two-stroke engines. Carbon fiber construction commands the premium material tier, with margin pools concentrating in integrated battery-airframe designs where advanced controls and battery management systems merge into proprietary platforms.
The FAA governs type certification and operational standards for electric aircraft in the United States, while EASA oversees CS-LSA and CS-UAS frameworks that determine market access across European Union member states. The EU Green Deal and national noise abatement regulations in Germany, France, and Switzerland directly shape procurement timelines for clubs replacing fossil-fuel fleet assets. Stakeholders must monitor battery certification pathways and evolving airworthiness standards for novel energy storage systems as regulators reconcile electric propulsion with decades-old glider operational norms.
Market Dynamics
Battery energy density improvements are compressing the cost-performance gap between electric self-launchers and fossil-fuel alternatives, forcing flight schools and clubs across Germany, France, and the United States to accelerate fleet replacement timelines under tightening noise and emissions ordinances.
Growth Catalysts
- Europe's F-Gas Regulation:This framework phases down hydrofluorocarbon use in aviation systems, compelling German and French gliding centers to retire two-stroke self-launchers and procure zero-emission electric alternatives.
- Lithium-sulfur prototypes:Emerging battery chemistries promise weight reductions of 30-40% versus current lithium-ion packs, enabling longer soaring ranges and reducing airframe ballast requirements for training missions.
- Rhön and Wasserkuppe modernization:Germany's premier gliding clusters are executing fleet renewals under national sustainability mandates, creating concentrated demand for certified electric trainers.
Market Restraints
- Lithium supply concentration:Battery cell production clusters in East Asia create import dependency and price volatility for European airframe integrators lacking captive cathode supply.
- CS-LSA certification timelines:EASA's evolving airworthiness standards for novel energy storage systems extend type approval cycles, freezing capital deployment for manufacturers awaiting production certificates.
- Grid infrastructure gaps:Rural airfields in the Alps and Pyrenees lack high-capacity charging installations, limiting operational radius for electric self-launchers at altitude-intensive training sites.
Strategic Opportunities
- Aerodynamic research contracts:University aerospace programs in Switzerland and Austria are soliciting silent electric platforms for boundary-layer and laminar-flow studies, opening institutional procurement channels beyond recreational aviation.
- Battery-airframe integration:Structural battery concepts that merge energy storage with load-bearing wing elements promise 15-20% mass savings, creating differentiation for composite specialists.
- EU Green Deal procurement incentives:Member state recovery funds earmark decarbonization grants for aviation training infrastructure, subsidizing club-level electric fleet acquisitions.
Industry Challenges
- Power electronics engineering scarcity:The intersection of aviation safety culture and automotive-scale battery management expertise remains thinly staffed, constraining development velocity for integrated propulsion systems.
- Legacy tow-plane dependency:Electric self-launchers must interoperate with conventional aerotow operations at mixed fleets, requiring dual-mode pilots and complicating training curriculum redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Glider Market |
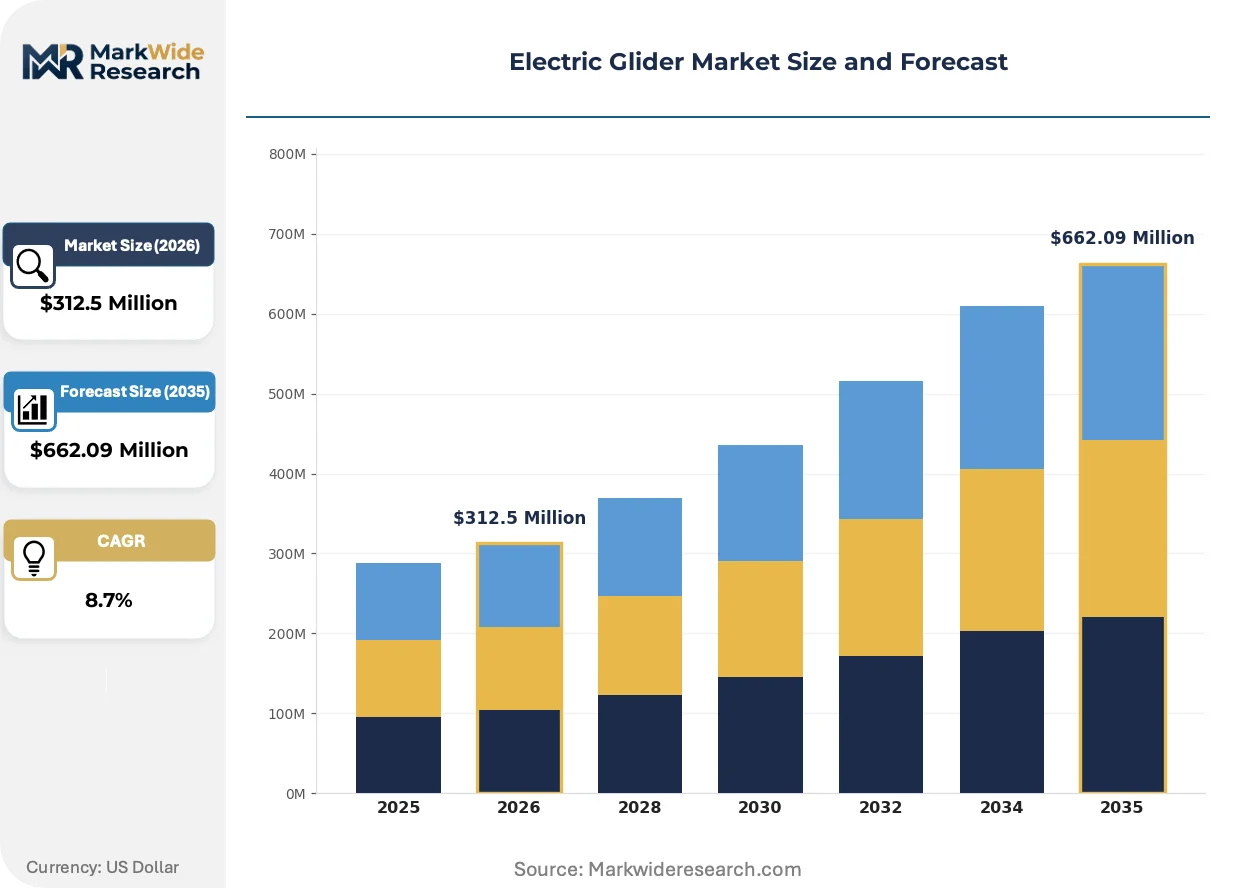
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Sailplane, Motor Glider, Self-Launcher End User: Aerospace Manufacturers, Hobbyists, Aerodynamics Researchers, Flight Schools Material: Composite, Carbon Fiber, Aluminum, Wood Technology: Electric Propulsion, Battery Management, Aerodynamic Designs, Advanced Controls |
| Companies Covered | STEMME, Alisport, Pipistrel, EuroSportAircraft, Europa Aircraft, Diamond Aircraft Industries, Aeros, ICARO 2000, Jonker Sailplanes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Glider Market Shifts & Advancements
Propulsion architecture decisions are locking in competitive positions for the next certification cycle, as airframe designers bet on motor placement, battery packaging, and thermal management configurations that will define operational economics through 2035.
Lithium-sulfur chemistry is absorbing development resources from solid-state alternatives in the glider segment due to superior gravimetric energy density. Slovenian and Austrian manufacturers are flight-testing sulfur cathode packs in modified self-launchers, targeting 400 Wh/kg cell-level performance. This technology is absorbing margin pressure from airframe weight reduction programs, enabling lighter wing structures that improve glide ratios.
Europe's F-Gas Regulation is tightening refrigerant restrictions for ground support equipment and auxiliary systems, indirectly raising operational compliance costs for conventional motor gliders. German flight schools are responding by bundling electric self-launcher purchases with solar hangar installations to secure operational permits. The regulation is accelerating depreciation schedules for fossil-fuel assets in the Alps corridor.
Training contracts are consolidating around multi-aircraft fleet deals rather than single-unit hobbyist sales. French and Swiss aeroclubs are pooling procurement through regional associations to negotiate volume pricing and shared charging infrastructure. This shift is visible in the Rhône-Alpes and Bavaria clusters, where three-club consortia now dominate order pipelines.
Electric Glider Market Segmentation
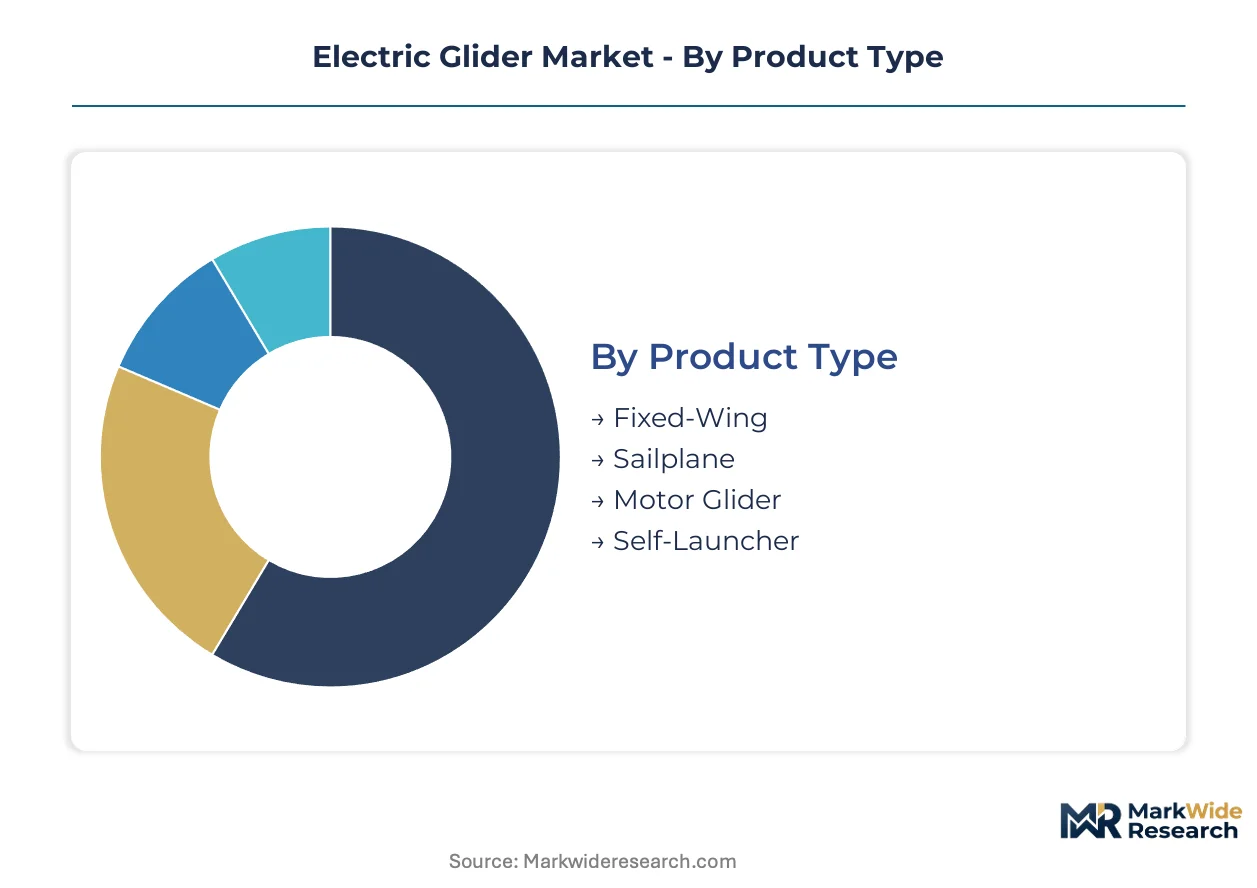
Segmentation in the electric glider market reveals how battery-airframe integration and certification pathways split procurement decisions across training institutions and research programs. Each dimension exposes different margin pools and technical barriers that shape competitive positioning.
Product Type:
Supply concentration clusters around airframe architectures that simplify certification and reduce manufacturing complexity for European producers.
- Fixed-Wing:Conventional rigid-wing designs with integrated electric motors mounted on the nose or tail. German flight schools in Rhön and Wasserkuppe favor these for standardized training curricula under EASA CS-LSA frameworks.
- Sailplane:Unpowered or sustainer-motor configurations optimized for pure soaring performance. Alpine clubs in Switzerland and France procure these for altitude-intensive instruction where aerotow operations remain economically viable.
- Motor Glider:Hybrid architectures with retractable propulsion systems enabling self-launch and cruise assistance. Demand concentrates among Austrian and Slovenian manufacturers serving cross-border training contracts.
- Self-Launcher:Purpose-built electric propulsion delivering full climb capability without external tow. Battery energy density improvements are compressing weight penalties, accelerating fleet replacement at noise-restricted sites.
Today's leader: Fixed-Wing. Tomorrow's challenger: Self-Launcher.
End User:
Procurement volume tiers separate institutional buyers with multi-aircraft fleet deals from fragmented individual purchasers.
- Aerospace Manufacturers:Systems integrators sourcing airframes for avionics testing and propulsion validation. These buyers demand configurable battery bays and open-architecture flight control interfaces.
- Hobbyists:Individual owners purchasing single units through dealer networks. This segment shrinks as club-based ownership models and fractional programs expand across France and Germany.
- Aerodynamics Researchers:University laboratories in Switzerland and Austria acquiring silent platforms for boundary-layer studies. EU Green Deal research grants are expanding this procurement channel.
- Flight Schools:Certified training academies replacing fossil-fuel fleets under national sustainability mandates. German and French institutions dominate order pipelines through regional purchasing consortia.
Flight Schools command current volume. Aerodynamics Researchers are climbing the fastest.
Material:
Margin pools concentrate in integrated structural-battery concepts where material choice directly determines energy storage packaging efficiency.
- Composite:Glass-fiber and hybrid laminates balancing cost against weight targets. Slovenian manufacturers leverage these for mid-market trainers serving Eastern European clubs.
- Carbon Fiber:High-modulus woven prepregs enabling thin wing sections and embedded battery compartments. Premium tier positioning at Austrian engineering houses serving competitive soaring segments.
- Aluminum:Conventional metal construction for legacy airframe retrofits and repair markets. Limited growth as clubs prioritize weight reduction for electric range extension.
- Wood:Traditional spruce and plywood structures for vintage restoration and experimental builds. Niche demand persists in heritage-preservation programs at German museums.
Carbon Fiber owns premium positioning. Composite materials are gaining share fastest.
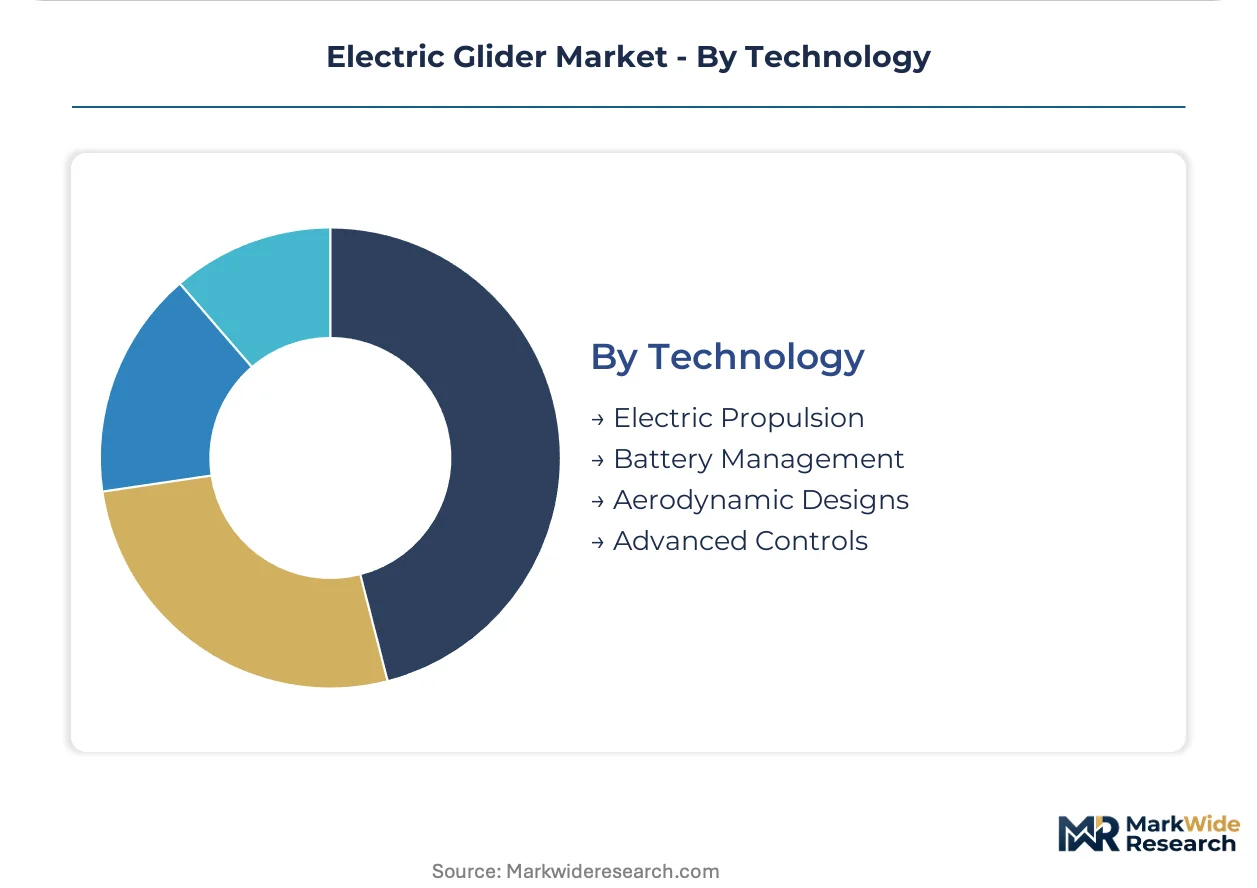
Technology:
Development resources are concentrating where aviation safety culture intersects with automotive-scale battery expertise.
- Electric Propulsion:Compact motors generating 30-100 kilowatt outputs with direct-drive or reduction-gear configurations. Pipistrel and Diamond Aircraft Industries compete on motor placement and thermal management architectures.
- Battery Management:Cell balancing, thermal runaway prevention, and state-of-charge algorithms certified to DO-178C software standards. EASA's evolving airworthiness requirements extend development timelines for novel chemistries.
- Aerodynamic Designs:Laminar-flow airfoils and winglets optimized for low-speed handling during electric climb phases. Research contracts from Swiss Federal Institute of Technology validate prototype configurations.
- Advanced Controls:Fly-by-wire interfaces and envelope protection systems integrating propulsion and flight control laws. These systems differentiate integrated platforms from retrofitted conventional gliders.
Electric Propulsion anchors current investment. Battery Management systems present the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands procurement volume through Rhön and Wasserkuppe gliding centers, while France concentrates demand in the Alps corridor where noise ordinances reshape fleet economics.
United States
Flight schools in California and Florida expand electric trainer acquisitions as the FAA streamlines certification pathways for light-sport electric aircraft. State-level sustainability mandates in California accelerate depreciation of fossil-fuel self-launchers. The Southwest training corridor from Arizona to Texas sees concentrated club procurement under regional noise abatement agreements.
Germany
Rhön and Wasserkuppe gliding centers execute fleet renewals under national sustainability mandates, creating Europe's densest electric self-launcher demand cluster. The F-Gas Regulation phases down hydrofluorocarbon use, compelling clubs to retire two-stroke engines. Bavarian and Hesse flight schools pool procurement through regional associations to negotiate volume pricing.
France
Alpine aeroclubs in the Rhône-Alpes region replace conventional motor gliders as EU Green Deal recovery funds subsidize decarbonization grants. National noise regulations tighten operational permits for fossil-fuel assets at altitude-intensive sites. Three-club consortia in Provence-Alpes-Côte d'Azur dominate order pipelines through shared charging infrastructure investments.
Switzerland
Swiss Federal Institute of Technology research contracts drive institutional procurement for silent electric platforms used in boundary-layer studies. Cantonal environmental regulations in Vaud and Bern accelerate club fleet electrification timelines. The Alpine training corridor between Zurich and Geneva concentrates aerodynamic research demand alongside recreational aviation.
Austria
Cross-border training contracts with German and Czech clubs sustain demand for motor gliders with retractable propulsion systems. National aviation authority alignment with EASA CS-LSA frameworks streamlines type approval for Slovenian and Austrian manufacturers. Styrian and Upper Austrian flight schools modernize under federal sustainability procurement guidelines.
Electric Glider Market Competitive Landscape
Slovenian and Austrian producers anchor the integrated propulsion tier; South African and Italian specialists hold positions in high-performance composite construction. The vendor base splits between consolidated airframe integrators with captive battery partnerships and fragmented component suppliers serving retrofit markets. Three archetypes dominate: full-system integrators controlling motor-battery-flight control stacks, composite airframe houses licensing propulsion from third parties, and research-platform builders serving university contracts. Competitive moves concentrate on battery-airframe integration partnerships and CS-LSA certification pre-positioning ahead of regulatory finalization.
Within the full-system integrator tier, Pipistrel and Diamond Aircraft Industries exemplify geographic anchoring strategies—Slovenian and Austrian engineering heritage respectively—while Jonker Sailplanes occupies a position in the high-performance research-platform niche. These three names represent how competitive positioning locks in through propulsion architecture decisions: nose-mounted versus tail-mounted motor placement, integrated versus modular battery packaging, and thermal management configurations that will define operational economics through the forecast window. Each exemplifies a distinct archetype without claiming specific market share or revenue figures.
| Leading Market Players |
|---|
| STEMME |
| Alisport |
| Pipistrel |
| EuroSportAircraft |
| Europa Aircraft |
| Diamond Aircraft Industries |
| Aeros |
| ICARO 2000 |
| Jonker Sailplanes |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap airframe specialists in Slovenia and Austria anchor production clusters, translating engineering heritage into pricing discipline that resists commoditization despite battery cost volatility from East Asian cell suppliers.
Pricing Analysis
Capacity additions in Germany's Rhön and Wasserkuppe training corridors are reshaping price floors for certified electric self-launchers. Three-tier pricing structure across premium carbon-fiber integrated platforms, standard composite trainers, and economy retrofit kits captures buyer heterogeneity. Pricing pressure stems from lithium supply volatility transmitted through battery pack costs, compressing margins at the standard tier. Flight schools exhibit highest price sensitivity due to pooled procurement volumes, while aerodynamics research programs at Swiss Federal Institute of Technology accept premium positioning for configurable open-architecture platforms.
Supply Chain Analysis
Lithium-ion cell supply rests on South Korean and Chinese cathode production clusters, with Japanese electrolyte specialists providing critical additives. German and Austrian airframe integrators source carbon-fiber prepregs from domestic autoclave facilities, while power electronics modules draw from Taiwanese semiconductor packaging houses. Single-source vulnerability concentrates in high-nickel cathode formulations subject to export licensing shifts. Distribution runs through regional flight school consortia in Bavaria and Rhône-Alpes, bypassing traditional dealer networks for fleet-scale transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-airframe integration advances are expanding margin pools as structural battery concepts eliminate redundant mass, enabling premium-tier positioning even as cell costs compress.
For Market Incumbents: Anticipate certification timeline risks from EASA's evolving CS-LSA standards for novel energy storage systems by pre-positioning production certificates before regulatory finalization. Deepen backward integration into battery management system firmware to defend against automotive-scale suppliers encroaching on aviation safety-critical applications. Lock in multi-year fleet contracts with German regional purchasing consortia to secure volume visibility. For New Entrants and Emerging Players: Direct-to-academy digital sales channels bypass entrenched dealer networks serving hobbyist segments. Target aerodynamics research contracts at Austrian and Swiss university laboratories as the most penetrable institutional entry point, where EU Green Deal grants subsidize first-unit acquisitions. Lead with open-architecture flight control interfaces that appeal to aerospace manufacturers validating proprietary avionics. For Investors and Strategic Acquirers: Valuations sit cheapest among composite airframe houses lacking captive propulsion partnerships, presenting consolidation targets for full-system integrators. Long-term viability favors platforms with certified battery-airframe integration rather than retrofit-dependent business models. Watch lithium-sulfur prototype flight-test milestones as the signal indicating technology inflection and competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Airframe Integration Partnership | Merges energy storage with load-bearing wing structures, cutting mass for Slovenian and Austrian manufacturers. |
| CS-LSA Certification Pre-Positioning | Secures production certificates ahead of EASA finalization, locking German flight school procurement timelines. |
| Regional Purchasing Consortium Engagement | Captures volume pricing through Bavarian and Rhône-Alpes three-club alliances replacing fragmented hobbyist sales. |
| Lithium-Sulfur Prototype Flight Testing | Validates 400 Wh/kg cell performance, enabling lighter wing designs at Alpine training sites. |
| Solar Hangar Infrastructure Bundling | Combines aircraft delivery with charging installations to secure operational permits under Europe's F-Gas Regulation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from flight school fleet managers, EASA certification engineers, lithium-cell procurement leads at airframe integrators, and aerodynamics research directors at Swiss and Austrian universities. Secondary validation drew from EASA CS-LSA framework documents, FAA light-sport aircraft filings, EU Green Deal recovery fund disbursement records, and customs data on carbon-fiber prepreg imports. Bottom-up unit shipment tallies from German and French gliding centers triangulated against top-down market value estimates.
Historical reference periods anchored the projection horizon through documented fleet replacement cycles at Rhön and Wasserkuppe gliding centers. Segmentation dimensions modeled include airframe architecture, end-user procurement tier, material construction class, and propulsion technology maturity. CAGRs derived from slope analysis of battery energy density improvement curves applied to fleet economics. Industry-specific inputs incorporated EASA certification timeline assumptions and lithium-sulfur chemistry readiness pathways.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery architectures would alter the outlook. Forecasts reflect assumptions about regulatory finalization timelines, cathode supply concentration, and flight school capital allocation priorities. A small set of named triggers—EASA CS-LSA publication dates, lithium-sulfur prototype certification milestones, and EU Green Deal grant disbursement velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone Leasing Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Drone-As-A-Service Market
UAV
Tethered Drones Market
UAV
Asia Pacific Small UAV Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
North America Tactical UAV Market
UAV
Multirotor Drones Market
UAV
Middle-East and Africa Drones Market
UAV
Global Drone Autopilots Market
UAV
Aerial Smart Weapons Market
UAV
Solar-Powered UAV Market
UAV
Drone Lens Market
UAV
Inspection Drones in Confined Space Market
UAV
Global Electric Drone Market
UAV
Small Drone Market