
 Small Drone Market | 2026-2036
Small Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Small Drone Market Analysis
FAA Part 107 remote pilot certification is redrawing competitive boundaries for commercial operators in the United States. DJI leverages its Shenzhen-based manufacturing depth to sustain price-performance advantages across consumer and enterprise tiers. Skydio, Inc. specializes in autonomous navigation systems that differentiate its offerings for infrastructure inspection and public safety applications. AeroVironment, Inc. anchors its position in defense-adjacent segments where ITAR compliance and government contracting channels create distinct barriers.
Small drones are unmanned aerial vehicles typically weighing under 25 kilograms, powered by lithium-polymer battery packs and controlled through GPS-stabilized flight controllers with redundant IMU arrays for attitude determination. Their primary commercial purpose spans aerial data acquisition, payload delivery, and remote sensing across industries requiring spatial intelligence without manned aviation costs. Commercial drones lead current revenue pools where enterprise procurement cycles favor durability and software integration over hardware specifications. Delivery drones represent the fastest-expanding application segment as last-mile logistics operators pilot autonomous drop networks in controlled airspace corridors. LiDAR-equipped platforms command premium positioning within surveying and infrastructure inspection workflows where point-cloud accuracy determines contract viability.
FAA regulations in the United States govern beyond-visual-line-of-sight waivers and night operation permissions that directly gate commercial scalability for service providers. EASA framework requirements across European Union member states mandate CE marking and specific noise-emission thresholds that shape product design cycles for manufacturers targeting transatlantic distribution. China's CAAC coordinates with MIIT on low-altitude economy zone designations that concentrate flight testing and commercial deployment permissions around designated urban corridors. Stakeholders must monitor evolving detect-and-avoid mandates and airspace management system integrations that will determine which technology architectures achieve operational certification at scale.
Market Dynamics
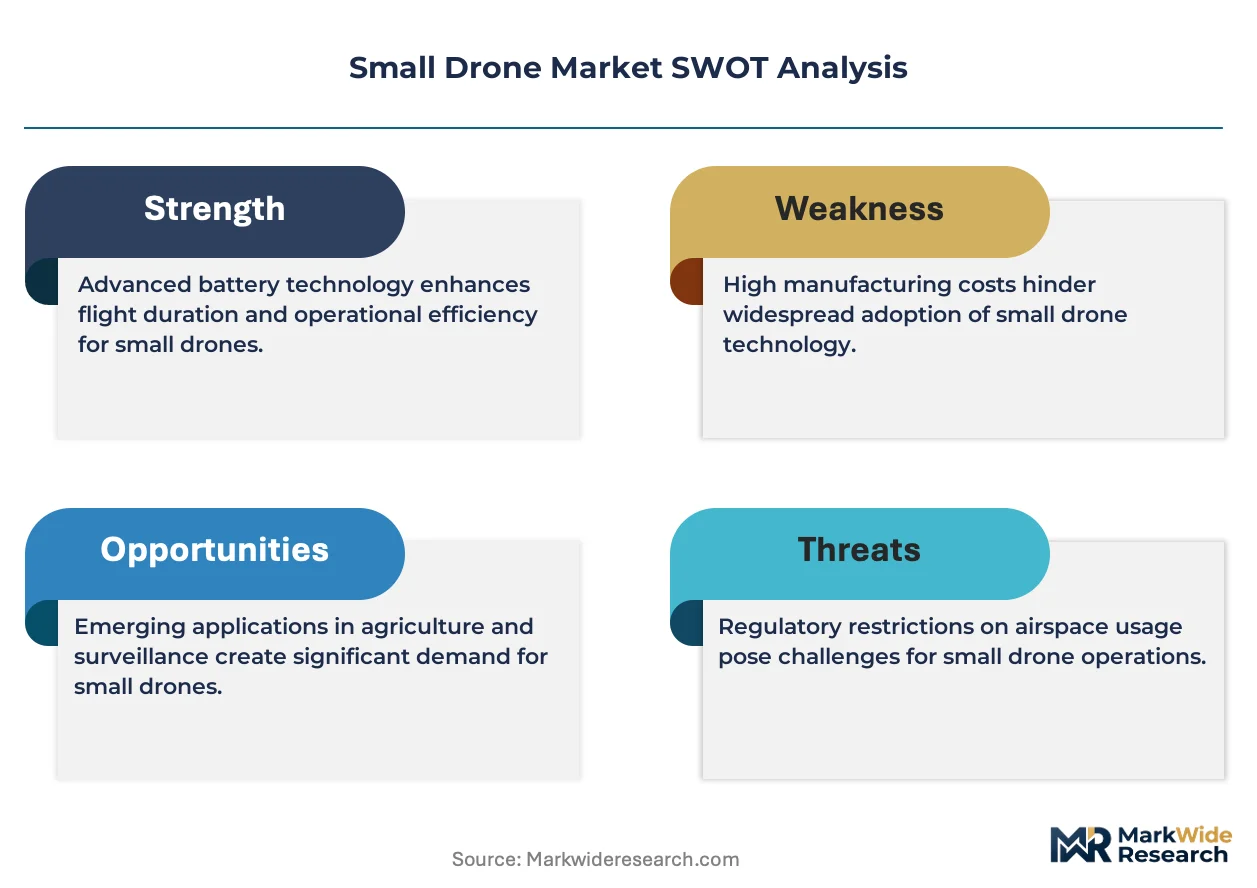
Autonomous navigation systems are compressing operator training requirements while expanding addressable task sets across infrastructure inspection and emergency response workflows. This technological inflection is redrawing competitive boundaries between hardware-centric and software-first vendors.
Growth Catalysts
- Beyond-visual-line-of-sight waivers:FAA Part 107 regulatory amendments in the United States are unlocking commercial scalability for last-mile delivery networks and linear infrastructure monitoring.
- Precision agriculture:Brazilian soybean and sugarcane operators are expanding fleet purchases as multispectral imaging and variable-rate application integration mature.
- Guangdong component ecosystem:Concentrated lithium-polymer battery and flight controller manufacturing in China's Pearl River Delta sustains cost-performance advantages for downstream assemblers.
Market Restraints
- Lithium supply concentration:Cathode material processing and cell manufacturing concentrate in Chinese and South Korean facilities, exposing fleet operators to input cost volatility and geopolitical sourcing risk.
- Airspace fragmentation:Divergent detect-and-avoid mandates across FAA, EASA, and CAAC jurisdictions multiply certification costs for manufacturers targeting transatlantic or multi-regional distribution.
- Manned aviation substitution:Helicopter-based inspection and crop-dusting services retain altitude, payload, and all-weather advantages that constrain drone addressable market in premium segments.
Strategic Opportunities
- Urban air mobility corridors:China's MIIT-designated low-altitude economy zones in Shenzhen and Chengdu are concentrating flight testing permissions and commercial deployment rights for autonomous logistics.
- LiDAR-surveying convergence:Integration of solid-state ranging sensors with photogrammetry software is opening high-precision mapping contracts in mining reclamation and coastal erosion monitoring.
- Subscription flight services:Equipment-as-a-service models are displacing capital purchase cycles among mid-sized agricultural cooperatives and municipal public safety departments.
Industry Challenges
- Remote pilot certification throughput:FAA Part 107 testing center capacity constraints and knowledge test backlogs are delaying commercial operator onboarding timelines.
- Detect-and-avoid system integration:Retrofitting ADS-B Out and radar altimeter compatibility into existing air traffic management infrastructure demands coordinated capital deployment across airport authorities and unmanned traffic management providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Drone Market |
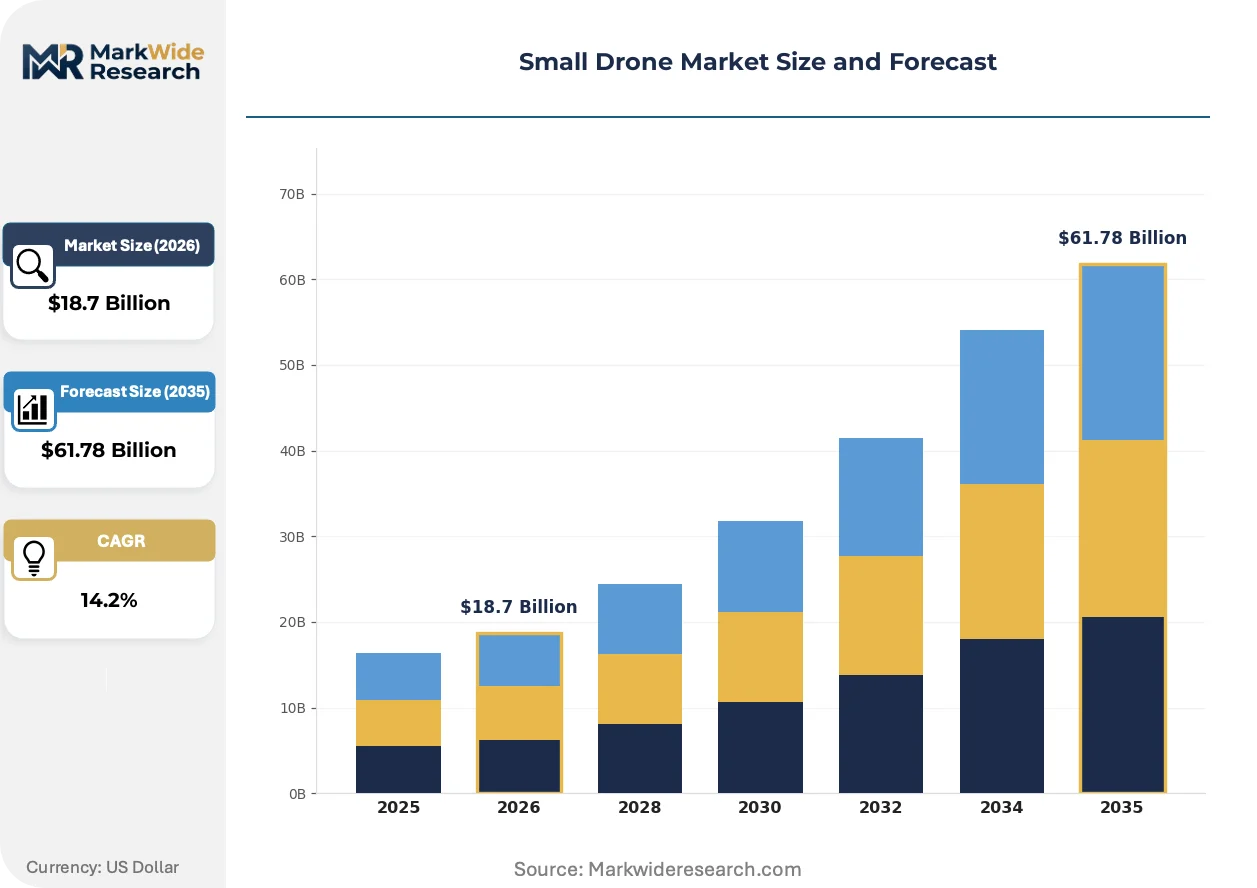
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Drones, Racing Drones, Commercial Drones, Delivery Drones Application: Aerial Photography, Agriculture Monitoring, Infrastructure Inspection, Surveying End User: Individuals, Enterprises, Government Agencies, Educational Institutions Technology: GPS Navigation, Optical Flow, LiDAR, FPV Systems |
| Companies Covered | DJI, Parrot Drone SAS, Lockheed Martin Corporation, AeroVironment, Inc., Israel Aerospace Industries, Northrop Grumman Corporation, BAE Systems, Skydio, Inc., Autel Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Drone Market Emerging Trajectories
Edge computing architectures and onboard AI inference are shifting processing loads from ground stations to airframes, enabling real-time decision-making in bandwidth-constrained environments. This compute migration is redefining hardware specifications and software licensing models across the value chain.
Computer vision-based obstacle avoidance is displacing GPS-dependent waypoint navigation in infrastructure inspection deployments. Electric utility and cell tower operators in the United States are adopting these systems for autonomous close-proximity flight. The technology is compressing inspection cycle times while reducing pilot skill requirements and insurance premiums.
EASA's Specific Category framework for drone operations is mandating operational risk assessments and conformity assessments that exceed basic CE marking requirements. Manufacturers targeting European distribution are redesigning fail-safe systems and redundant flight control architectures to satisfy these elevated safety cases. The regulation is favoring established aerospace suppliers with existing quality management certifications over consumer-electronics entrants.
Enterprise procurement teams are unbundling hardware acquisition from pilot training and data analytics subscriptions. Agricultural and construction buyers in Australia and Brazil are negotiating multi-year service agreements that transfer fleet management and maintenance liability to operators. This shift is compressing upfront capital requirements while locking in recurring revenue streams for vertically integrated service providers.
Small Drone Market Segmentation
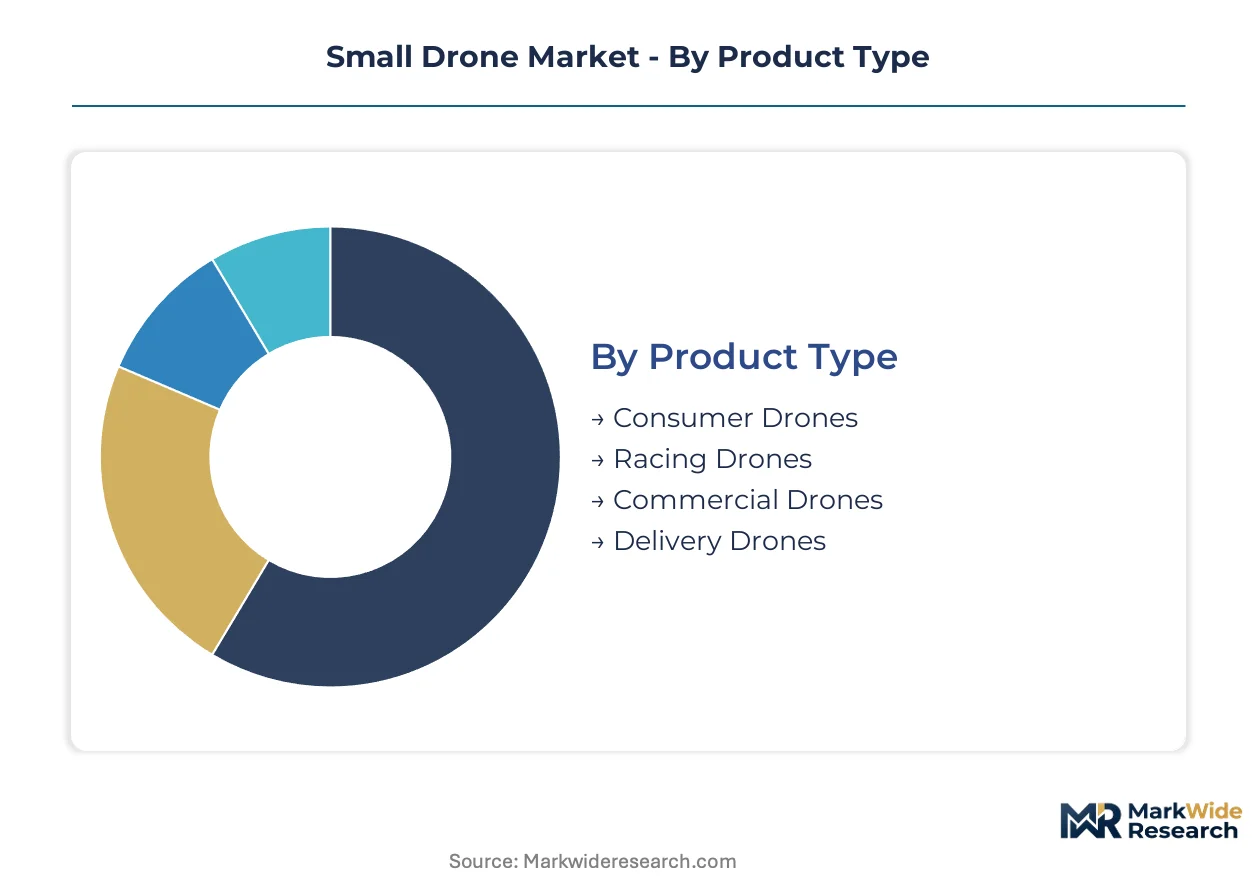
Segmentation reveals how hardware specifications, software integration depth, and regulatory compliance requirements partition revenue pools across the small drone value chain. Procurement patterns diverge sharply between consumer impulse purchases and enterprise capital cycles governed by FAA Part 107 waivers and insurance underwriting.
Product Type:
Margin pools concentrate in commercial and delivery tiers where software subscriptions and service contracts extend lifetime value beyond hardware margins.
- Commercial Drones:Enterprise-grade platforms integrate multispectral sensors, RTK-GPS positioning, and redundant flight controllers for precision agriculture and linear infrastructure monitoring. Brazilian soybean operators and U.S. electric utilities are expanding fleet deployments as BVLOS waivers mature, though lithium supply concentration creates input cost volatility.
- Delivery Drones:Autonomous logistics platforms with parachute recovery systems and ADS-B transponders operate within designated low-altitude corridors. China's MIIT-designated zones in Shenzhen and Chengdu are concentrating flight permissions, while FAA Type Certification timelines in the United States constrain near-term deployment scale.
- Consumer Drones:Recreational platforms with 4K camera gimbals and GPS-stabilized hovering dominate unit volumes through retail channels.
- Racing Drones:FPV-first quadcopters with manual flight modes and carbon-fiber frames serve competitive leagues and hobbyist communities.
The dominant share belongs to Commercial Drones, while Delivery Drones is closing the gap fastest.
Application:
Revenue per deployment varies by data deliverable complexity, with point-cloud surveying commanding premiums over photogrammetry-only outputs.
- Infrastructure Inspection:Close-proximity flight systems with computer vision obstacle avoidance enable autonomous cell tower and transmission line surveys. U.S. electric utilities are adopting these platforms to compress inspection cycle times while reducing pilot certification burdens and liability premiums.
- Agriculture Monitoring:Multispectral imaging with NDVI analysis supports variable-rate application decisions in Brazilian sugarcane and Australian broadacre operations. Fleet purchases are accelerating as prescription map integration matures, though seasonal utilization rates constrain ROI timelines.
- Surveying:LiDAR-equipped platforms generate high-density point clouds for mining reclamation and coastal erosion monitoring.
- Aerial Photography:Cinematography and real estate marketing applications favor gimbal-stabilized 4K outputs with automated flight paths.
Infrastructure Inspection captures the highest margins per flight hour, with Agriculture Monitoring expanding most quickly among mid-sized cooperatives.
End User:
Procurement authority and budget cycles segment distinctly between capital-constrained individual buyers and enterprise purchasing departments with multi-year planning horizons.
- Enterprises:Agricultural conglomerates, construction firms, and energy utilities negotiate equipment-as-a-service agreements that transfer fleet maintenance and regulatory compliance liability to operators. Australian mining companies and Brazilian cooperatives are displacing capital purchase cycles with subscription models.
- Government Agencies:Public safety departments and environmental regulators require ITAR-compliant platforms with encrypted data transmission and audit trails. FAA coordination on disaster response deployments shapes procurement specifications.
- Individuals:Recreational pilots and content creators drive consumer-tier volumes through direct-to-consumer retail channels.
- Educational Institutions:University research programs and vocational training centers purchase platforms for STEM curriculum and pilot certification instruction.
Enterprises command the largest aggregate spend, with Government Agencies gaining share fastest through civil defense and environmental monitoring programs.
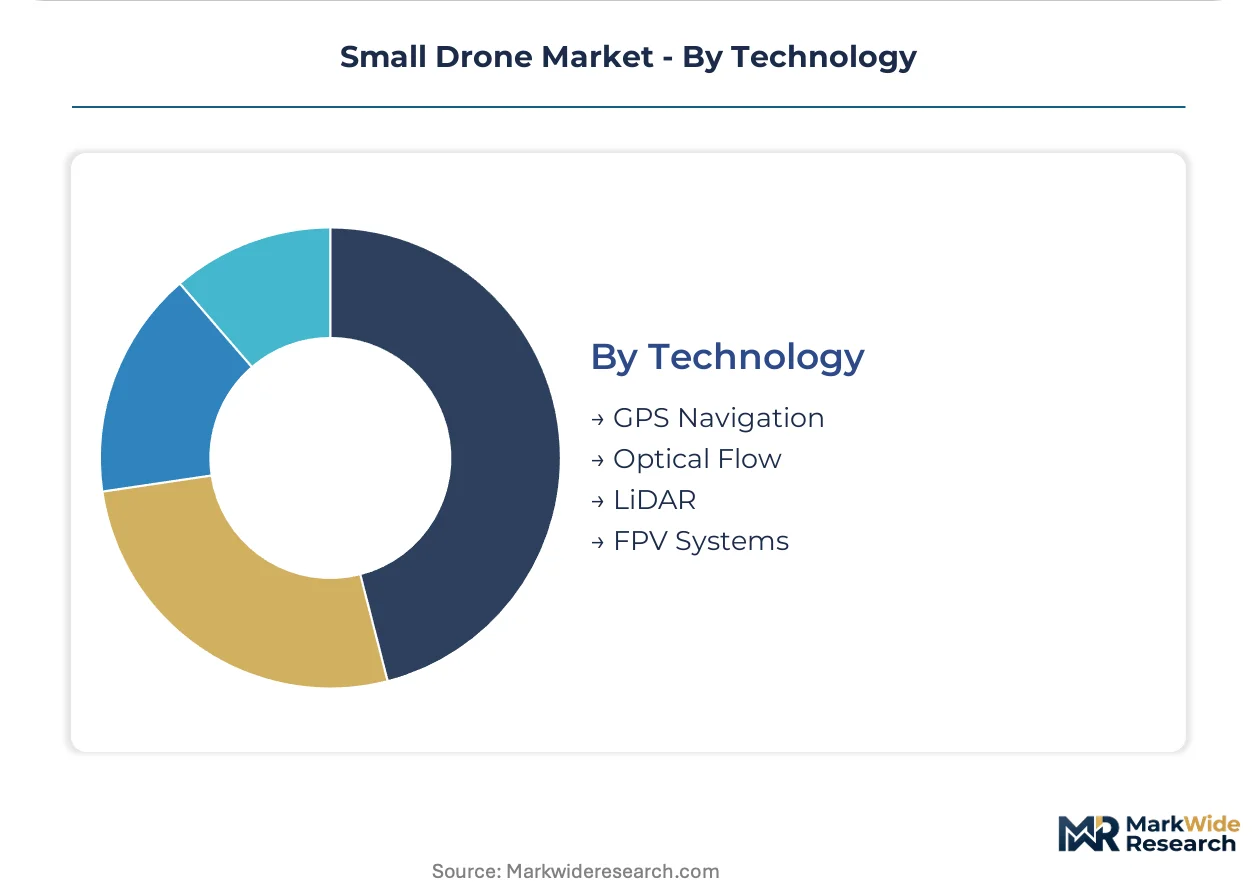
Technology:
Sensor fusion architectures and onboard compute capabilities determine platform pricing tiers and addressable mission profiles.
- LiDAR:Solid-state ranging sensors with photogrammetry software integration enable millimeter-accuracy elevation modeling for mining volumetrics and floodplain mapping. Mining reclamation contracts in Australia and coastal monitoring programs in Brazil are driving adoption despite premium hardware costs.
- GPS Navigation:RTK-corrected positioning with redundant IMU arrays provides centimeter-level accuracy for agricultural prescription mapping and construction progress monitoring.
- Optical Flow:Downward-facing camera arrays enable stable indoor hovering and precision landing without satellite coverage.
- FPV Systems:Low-latency video transmission supports manual racing maneuvers and close-proximity inspection in GPS-denied environments.
LiDAR dominates premium contract viability, while GPS Navigation maintains broadest deployment across commercial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in the United States, China, and Brazil drive the majority of commercial fleet deployments, with government agencies in Israel and Germany accelerating defense-adjacent acquisitions.
United States
Electric utilities and cell tower operators dominate commercial uptake as BVLOS waivers expand operational scope. FAA Part 107 certification backlogs constrain pilot onboarding timelines for service providers. The Dallas-Fort Worth corridor hosts concentrated flight testing infrastructure for autonomous logistics platforms.
China
Guangdong's manufacturing ecosystem supplies lithium-polymer batteries and flight controllers to downstream assemblers worldwide. CAAC coordination with MIIT on low-altitude economy zones accelerates commercial deployment permissions in designated urban corridors. Shenzhen anchors component production density that sustains cost-performance advantages across export markets.
Brazil
Soybean and sugarcane operators expand multispectral imaging fleets for variable-rate application integration. ANVISA environmental compliance requirements shape pesticide spraying drone specifications for agricultural service providers. São Paulo state concentrates equipment distribution networks serving the Cerrado and southern production belts.
Germany
Industrial inspection contractors adopt LiDAR-equipped platforms for mining volumetrics and infrastructure monitoring. EASA Specific Category framework mandates elevate fail-safe system requirements beyond basic CE marking. Bavaria hosts aerospace suppliers with existing quality management certifications serving defense and civil applications.
Israel
Defense procurement channels sustain demand for ITAR-compliant platforms with encrypted data transmission. The national civil aviation regulator coordinates airspace integration for dual-use technology development. Tel Aviv's technology corridor concentrates autonomous navigation software development for export markets.
Small Drone Market Vendor Landscape
Player mix skews toward vertically integrated hardware manufacturers with captive component supply and specialized autonomy software developers with defense contracting access. Tiering separates consumer-volume producers from enterprise-grade platform builders and ITAR-restricted defense suppliers. Dominant competitive moves include geographic expansion into MIIT-designated low-altitude zones and strategic partnerships with agricultural cooperatives for equipment-as-a-service deployment.
Within the Shenzhen-based manufacturing tier, DJI exemplifies scale-driven platform integration spanning consumer and enterprise segments. Among U.S.-based autonomy specialists, Skydio, Inc. occupies a position emphasizing computer vision navigation for infrastructure inspection workflows. Defense-adjacent suppliers include AeroVironment, Inc., which anchors ITAR-compliant contracting channels for government agency procurement.
| Leading Market Players |
|---|
| DJI |
| Parrot Drone SAS |
| Lockheed Martin Corporation |
| AeroVironment, Inc. |
| Israel Aerospace Industries |
| Northrop Grumman Corporation |
| BAE Systems |
| Skydio, Inc. |
| Autel Robotics |
| Others |
Supply Flow & Price Mechanics
Sixty-day lithium-polymer cell lead times from Guangdong suppliers concentrate pricing power among vertically integrated assemblers, while spot-market cathode material volatility feeds through to enterprise fleet procurement cycles. This inventory-to-pricing linkage rewards manufacturers with captive battery supply and penalizes pure-play distributors during input cost spikes.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate enterprise fleet procurement, insulating operators from cathode material swings while locking in assembler margins. Three-tier pricing structure across ITAR-compliant defense platforms, FAA-certified commercial systems, and recreational consumer tiers separates buyers by certification burden and software subscription bundling. Pricing pressure stems from South Korean cell manufacturers expanding European distribution, compressing margins for mid-tier assemblers lacking Guangdong ecosystem proximity. Agricultural cooperatives in Brazil exhibit highest price sensitivity, prioritizing hardware durability over autonomy software depth, while U.S. electric utilities accept premium positioning for BVLOS-ready platforms with ADS-B transponders.
Supply Chain Analysis
Inventory cycles for flight controller chipsets and carbon-fiber airframes run 45-60 days, with downstream distributors holding 30-day safety stocks against Guangdong production volatility. Component manufacturing concentrates in China, South Korea, and Japan, with solid-state LiDAR sensors drawing from Israeli and German optical engineering clusters. Single-source vulnerability concentrates in rare-earth magnet supply for brushless motors, tethering motor performance to Chinese processing capacity. Distribution runs through Shenzhen-based OEM direct channels for enterprise buyers, while consumer tiers reach retail through regional electronics distributors in São Paulo and Dallas-Fort Worth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from autonomous ground robotics in last-mile logistics and manned helicopter services in premium inspection segments. Defense of market position requires preemptive capability investment and regulatory capture before substitute technologies achieve operational certification parity.
For Market Incumbents: Secure FAA Type Certification pathways for autonomous delivery platforms before ground-robotics operators achieve sidewalk deployment scale at comparable cost points. Deepen backward integration into lithium-polymer cell production through joint ventures with South Korean cathode suppliers, reducing exposure to Chinese processing concentration. Lock in multi-year equipment-as-a-service contracts with Brazilian agricultural cooperatives to displace capital purchase cycles and entrench fleet management relationships.
For New Entrants and Emerging Players: Subscription pilot training and regulatory compliance services represent the most penetrable white space, as incumbent hardware manufacturers under-serve mid-sized operators lacking in-house FAA waiver expertise. Target municipal public safety departments in secondary U.S. metropolitan areas, where procurement authority is decentralized and incumbent sales coverage is thin. Lead with bundled flight-hour pricing that transfers liability and maintenance burden, displacing capital-intensive fleet ownership models.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense conglomerates seeking to divest non-core unmanned systems divisions with ITAR compliance infrastructure but limited commercial channel access. Long-term viability favors platforms with software-defined autonomy stacks capable of migrating across hardware generations. Watch FAA detect-and-avoid mandate finalization as the signal for which sensor fusion architectures achieve operational certification at scale, determining which technology bets achieve commercial escape velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| BVLOS Certification Investment | FAA waiver readiness separates scalable logistics operators from visual-line-of-sight constraints. |
| Autonomy Software Licensing | Computer vision navigation stacks unlock recurring revenue beyond hardware depreciation cycles. |
| Equipment-as-a-Service Deployment | Subscription flight-hour models displace capital purchases among Brazilian agricultural cooperatives. |
| ITAR Compliance Infrastructure | Encrypted data transmission capabilities gate government agency procurement in defense-adjacent segments. |
| Low-Altitude Corridor Partnerships | MIIT-designated zone access in Shenzhen and Chengdu concentrates commercial deployment permissions. |
Methodological Framework
A standing panel of FAA certification consultants, agricultural fleet operators, electric utility inspection managers, and unmanned traffic management software engineers provided ongoing calibration against operational realities. Primary fieldwork combined structured interviews with procurement directors at Brazilian cooperatives and U.S. infrastructure operators with secondary validation through FAA waiver databases, EASA conformity assessment registries, and CAAC low-altitude economy zone designations. Bottom-up triangulation of fleet deployment data with top-down manufacturer shipment estimates anchored volume and value outputs.
Consistency checks against customs records for lithium-polymer cell trade flows and hyperscaler logistics pilot disclosures validated projection trajectories across the analysis window. Segmentation modeling spanned product type, application workflow, end-user procurement authority, and technology architecture dimensions. CAGRs derived from logistic diffusion curves fitted to BVLOS waiver issuance rates and agricultural prescription map adoption patterns, with sensitivity testing against lithium supply disruption scenarios and regulatory timeline slippage.
Underlying assumptions cover steady-state FAA certification throughput, EASA Specific Category framework stability, and MIIT zone expansion continuity, with deviation risk concentrated in detect-and-avoid mandate finalization and rare-earth magnet export restriction episodes. Revision becomes warranted when BVLOS waiver approval timelines extend beyond 18-month thresholds or when autonomous ground robotics achieve comparable last-mile cost economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
North America Tactical UAV Market
UAV
Drones Market
UAV
Anti-Drone Market
UAV
Commercial Drone Market
UAV
Micro Drone Market
UAV
Global Drone Light Shows Market
UAV
Drone Tracking Antenna Market
UAV
Middle-East and Africa Drones Market
UAV
Unmanned Aerial Vehicle Fuel Cell Market
UAV
Drone Delivery Services Market
UAV
Military UAV Sensor Market
UAV
Global Smartphone Controlled Drone Market
UAV
North America Drone Software Market
UAV
Drone Motors Market
UAV
Combat Drone Market
UAV
Toy Drones Market