
 Anti-Drone Technology Market | 2026-2036
Anti-Drone Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Drone Technology Market Outlook
MIL-STD certification tiers for electronic countermeasures is reorganizing supplier hierarchies in the anti-drone sector. RTX leverages its Patriot radar heritage to anchor integrated air-and-missile defense portfolios spanning counter-UAS layers. Lockheed Martin Corporation sustains technology leadership through directed-energy investments and software-defined detection architectures. Rafael Advanced Defense Systems dominates the kinetic interceptor segment with combat-proven Iron Dome derivatives adapted for drone swarms.
Anti-drone technology encompasses detection, tracking, and neutralization systems designed to identify and defeat unmanned aerial vehicles through radio frequency jamming, directed energy, kinetic projectiles, or cyber takeover protocols, typically operating across X-band and Ku-band radar spectra with sub-degree angular resolution. These systems serve military base protection, civilian airport perimeter defense, and critical infrastructure security against reconnaissance and payload delivery threats. Radio Frequency detection and disruption commands the largest installed base due to lower unit economics and faster deployment cycles, while Laser-based directed energy represents the fastest-expanding technology tier as solid-state fiber lasers achieve militarily relevant power densities. The Military end-user segment absorbs the majority of current procurement volume, though Commercial applications around data center and energy facility protection are emerging as margin-accretive niches.
The FAA's Remote ID rule and evolving Part 107 frameworks shape civilian counter-drone product standards and operational permissions across United States airspace. EASA's drone regulation harmonization under the EU Green Deal's digital infrastructure priorities, alongside NATO's emerging counter-UAS doctrine, is creating procurement alignment among European defense ministries. Stakeholders must monitor how emerging software-defined radio threats and AI-enabled autonomous drone swarms force continuous hardware refresh cycles and interoperability mandates.
Market Dynamics
Layered air defense architectures are forcing defense ministries to integrate counter-UAS systems into existing radar and command networks rather than deploy standalone point solutions. This structural shift favors suppliers with proven military pedigree and software-defined upgrade paths.
Growth Catalysts
- Remote ID mandate:The FAA's Remote ID rule creates compliance-driven procurement of detection systems across US civilian airports and critical infrastructure operators.
- NATO doctrine alignment:Emerging counter-UAS protocols among European defense ministries are standardizing interoperability requirements and accelerating joint procurement.
- Swarm threat evolution:AI-enabled autonomous drone formations are compelling base commanders to upgrade from single-target to multi-target tracking radars.
Market Restraints
- GaN supply concentration:Gallium nitride substrate production for high-power RF jammers concentrates among Japanese and US specialty foundries, creating input bottlenecks.
- Spectrum allocation friction:Military countermeasures in C-band and L-band encounter interference disputes with commercial 5G deployments regulated by national telecom authorities.
- Kinetic cost asymmetry:Low-cost quadcopters impose disproportionate interceptor economics, limiting kinetic solutions to high-value asset protection.
Strategic Opportunities
- Data center perimeter security:Hyperscale cloud operators in Virginia and Texas are piloting RF detection grids for facility protection against corporate espionage drones.
- Laser-convergence systems:Solid-state fiber lasers paired with electro-optical tracking are opening stationary defense contracts for energy infrastructure.
- India defense modernization:The country's PLI scheme for domestic manufacturing is creating joint-venture pathways for foreign counter-UAS technology transfer.
Industry Challenges
- MIL-STD certification timelines:Electronic warfare systems face 18-24 month validation cycles against evolving electromagnetic environmental effects standards.
- Software-defined radio countermeasures:Rapidly reprogrammable drone control protocols force detection algorithm refresh rates that strain development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Drone Technology Market |
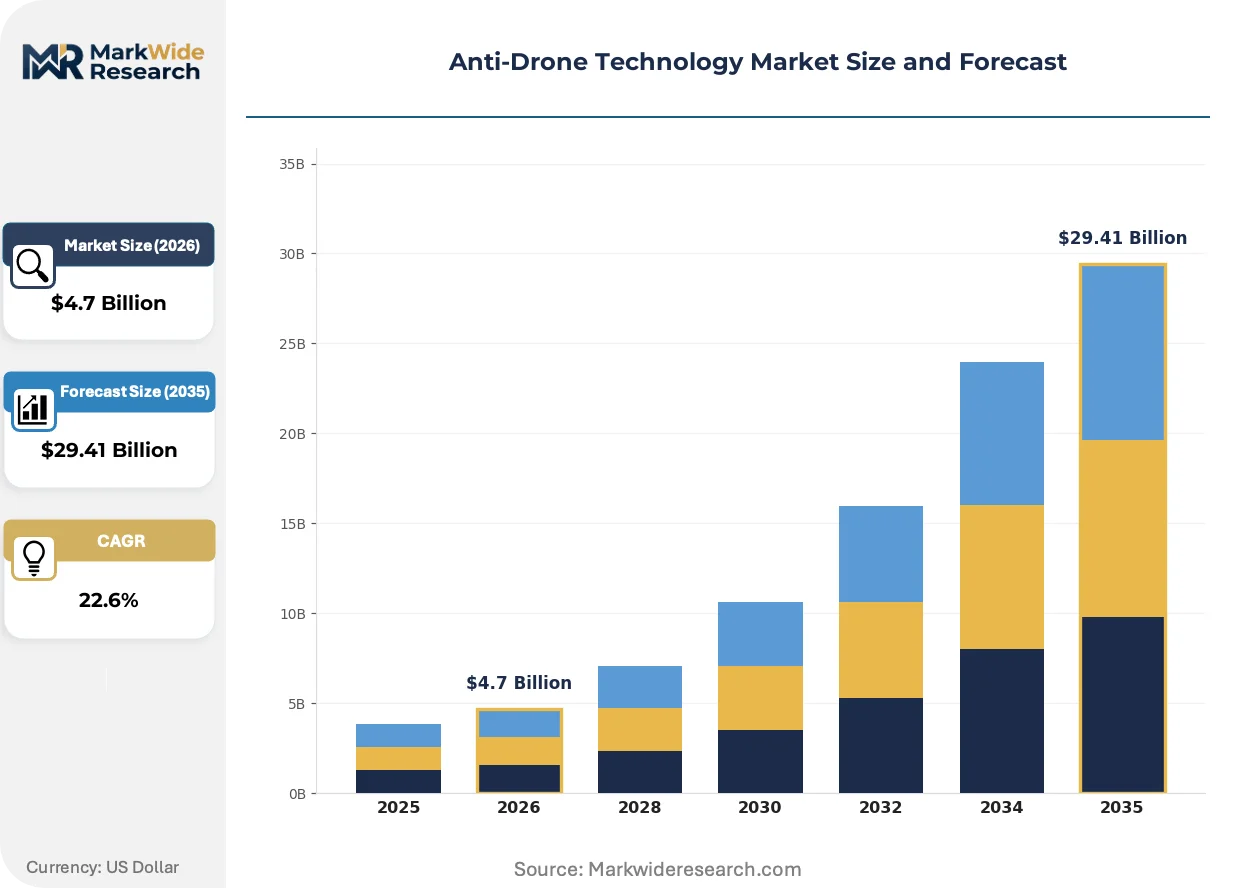
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Radio Frequency, Laser, Kinetic, Cybersecurity End User: Military, Aviation, Government, Commercial Deployment Model: On-Premise, Cloud-Based, Hybrid, Portable Application: Surveillance, Counter-Terrorism, Event Security, Asset Protection |
| Companies Covered | RTX, Lockheed Martin Corporation, Rafael Advanced Defense Systems, Israel Aerospace Industries, Thales, Leonardo S.p.A., Saab, DroneShield Ltd, Dedrone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Drone Technology Market Strategic Shifts
Software-defined architectures are compressing hardware refresh cycles across detection and neutralization tiers. Suppliers must now deliver firmware-upgradeable systems rather than fixed-capability platforms.
Solid-state directed energy weapons are displacing chemical laser systems in layered defense portfolios. Naval and ground-based operators in the United States and Israel are fielding 50-100 kW fiber laser demonstrators for drone swarm defeat. This displacement is collapsing the historical separation between point defense and area denial missions.
EASA's drone regulation harmonization under EU Green Deal digital infrastructure priorities is mandating standardized detect-and-avoid protocols across member state airspace. Commercial operators must now certify counter-UAS integration with unmanned traffic management systems. Civilian airport authorities in Germany and France are responding with phased procurement of cooperative and non-cooperative detection layers.
Defense ministries are unbundling detection hardware from neutralization service contracts. Buyers now procure sensor grids through capital appropriations while subscribing to software updates and threat libraries via annual licensing. This pattern is most pronounced in United Kingdom and Australian procurement frameworks for base perimeter security.
Anti-Drone Technology Market Segmentation
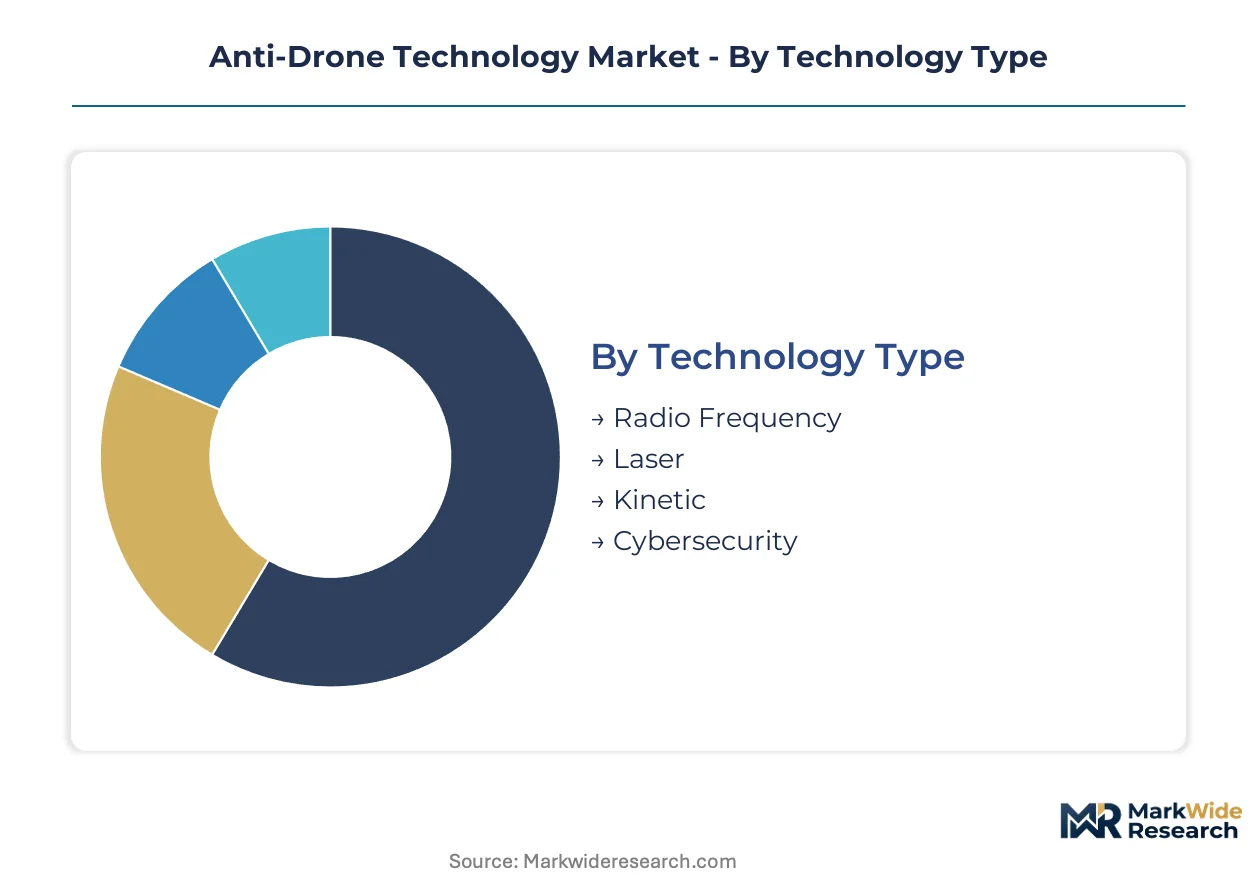
Anti-drone procurement decisions fragment across mission profiles, budget cycles, and regulatory jurisdictions. Buyers select technology tiers based on threat severity, collateral damage tolerance, and integration complexity with existing command networks.
Technology Type:
FAA airspace governance and NATO electromagnetic compatibility standards create divergent certification pathways for each technology tier.
- Radio Frequency:Systems exploit spectral signatures in C-band, L-band, and ISM frequencies to detect and jam drone command links. Military bases across the United States and United Kingdom prioritize RF grids for rapid deployment without permanent infrastructure. The FAA's Remote ID mandate accelerates civilian airport adoption of cooperative detection layers.
- Laser:Solid-state fiber lasers at 50-100 kW power densities deliver precise engagement against swarming threats with minimal collateral damage. Israeli and United States naval operators field demonstrators for layered defense portfolios. Solid-state architectures displace chemical laser systems through superior reliability and logistics footprints.
- Kinetic:Interceptor missiles and net-capture systems defeat hardened targets through physical destruction. Cost asymmetry limits deployment to highest-value asset protection.
- Cybersecurity:Protocol injection and GPS spoofing achieve non-destructive takeover of hostile drones. Regulatory ambiguity around electronic warfare in civilian airspace constrains commercial adoption.
Radio Frequency handles the majority of throughput; Laser is the fastest mover on share.
End User:
Budget authority and threat tolerance stratify procurement patterns across institutional buyers.
- Military:Base perimeter defense and expeditionary force protection drive layered system integration with Patriot radar and command networks. NATO doctrine alignment standardizes interoperability requirements across member state ministries.
- Aviation:Civilian airport authorities in Germany and France deploy phased detection layers under EASA harmonized standards. The FAA's Part 107 frameworks shape operational permissions for counter-UAS near runways.
- Government:Critical infrastructure protection and border security agencies balance detection depth against civil liberties constraints.
- Commercial:Hyperscale data center operators in Virginia and Texas pilot RF grids against corporate espionage threats. Energy facility operators evaluate laser-convergence systems for substation protection.
Military absorbs the dominant procurement volume; Commercial is climbing the fastest as regulatory clarity emerges.
Deployment Model:
Integration architecture determines refresh cycles and interoperability with legacy military networks.
- On-Premise:Dedicated hardware stacks deliver lowest latency for kinetic engagement decisions. Fixed installations dominate permanent base protection contracts.
- Cloud-Based:Centralized threat libraries and algorithm updates enable rapid response to software-defined radio mutations. United Kingdom and Australian frameworks favor this model for software subscription licensing.
- Hybrid:Edge processing with cloud analytics balances latency requirements against computational depth. This architecture gains traction in layered air defense integration.
- Portable:Man-portable and vehicle-mounted systems support expeditionary operations and temporary event security. Rapid deployment cycles favor RF-based units.
On-Premise retains the largest installed base; Hybrid is gaining share fastest through defense network modernization.
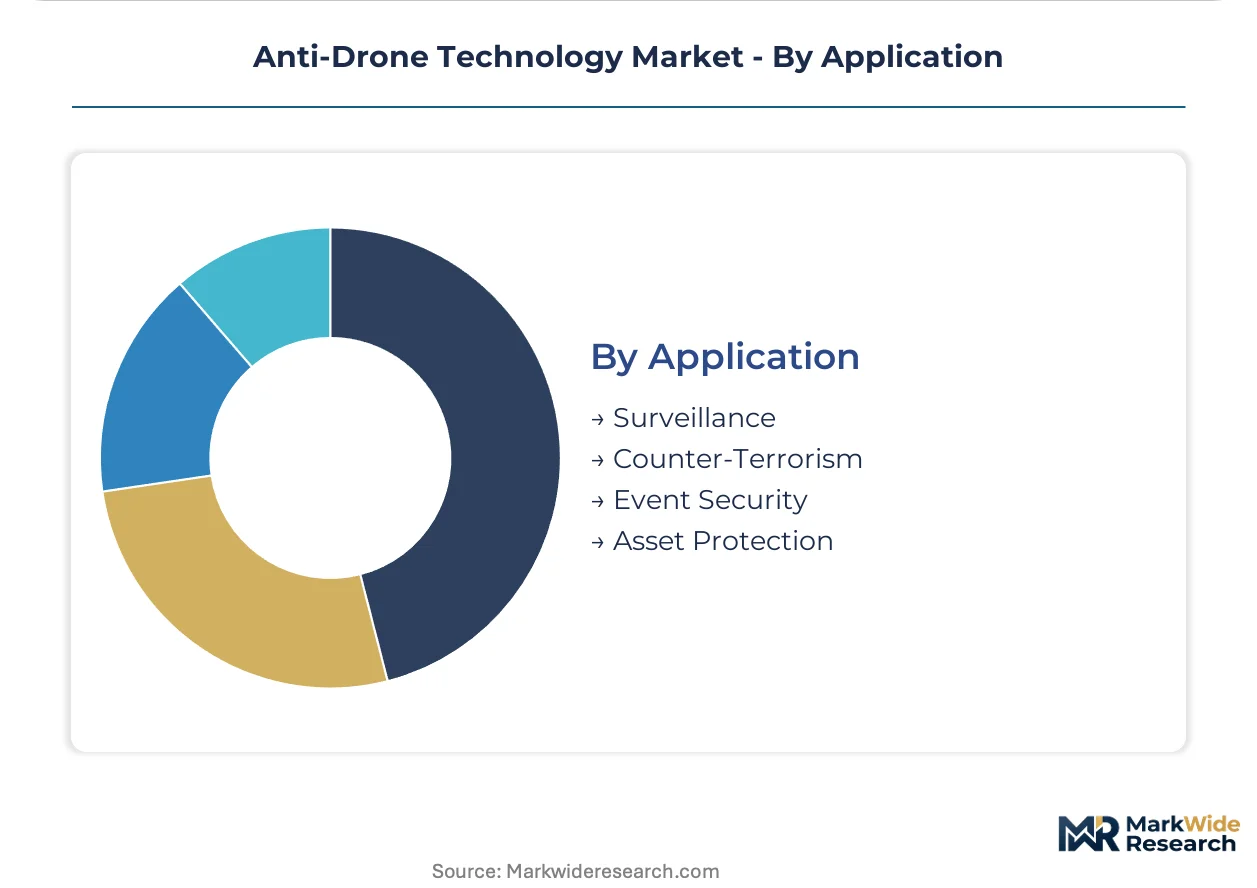
Application:
Mission specificity dictates sensor configuration and neutralization rules of engagement.
- Surveillance:Passive detection and tracking systems identify drone activity without immediate engagement. Civilian infrastructure operators favor this tier for regulatory compliance.
- Counter-Terrorism:High-certainty identification with immediate neutralization authority characterizes military and elite law enforcement deployments. Kinetic and directed energy systems concentrate here.
- Event Security:Temporary protection for political summits and sporting venues drives portable system rental markets. RF detection dominates due to rapid field deployment.
- Asset Protection:Permanent defense of energy infrastructure, data centers, and government facilities. Laser systems are penetrating this segment for stationary perimeter contracts.
Surveillance carries the broadest deployment footprint; Asset Protection shows the steepest expansion trajectory as critical infrastructure hardening accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor nations with established defense industrial bases and permissive technology transfer frameworks. The United States and Israel maintain net export positions in integrated counter-UAS systems. Import-dependent markets in Europe and Asia are accelerating domestic production through offset agreements and local partnership mandates.
United States
Layered air defense procurement by the Pentagon and FAA-mandated civilian airport upgrades drive detection system demand. The FAA's Remote ID rule and Part 107 frameworks shape operational permissions for counter-UAS deployments near critical infrastructure. Virginia and Texas host hyperscale data center pilots testing RF grids against corporate espionage threats.
Israel
Combat-proven kinetic interceptors and directed-energy demonstrators anchor defense export portfolios. The country's national security doctrine prioritizes multi-target tracking capabilities against autonomous swarm threats. Rafael Advanced Defense Systems and Israel Aerospace Industries concentrate R&D activity around Haifa and Tel Aviv metropolitan clusters.
United Kingdom
Base perimeter security contracts favor software-subscription models over capital-intensive hardware purchases. NATO counter-UAS doctrine alignment standardizes interoperability requirements across Ministry of Defence procurement. RAF installations and civilian airports in southeastern England deploy phased detection layers under harmonized electromagnetic compatibility standards.
Germany
Civilian airport authorities respond to EASA harmonized standards with cooperative and non-cooperative detection procurement. The EU Green Deal's digital infrastructure priorities mandate detect-and-avoid protocol integration with unmanned traffic management systems. Frankfurt and Munich airport operators lead continental adoption of layered civilian counter-drone architectures.
India
Defense modernization programs under the PLI scheme create joint-venture pathways for foreign technology transfer. The country's national defense procurement guidelines emphasize domestic manufacturing offsets for electronic warfare systems. Bangalore and Hyderabad defense clusters absorb technology partnerships for radar and directed-energy component localization.
Anti-Drone Technology Market Competitive Environment
Concentration sits with defense primes possessing MIL-STD certification heritage and integrated air-and-missile defense portfolios. Tier-one suppliers anchor layered system integration while specialized counter-UAS pure-plays capture portable and civilian niche contracts. Two strategic archetypes dominate: radar-heritage conglomerates leveraging Patriot-class sensor networks, and agile specialists delivering rapid-deployment RF units. Competitive moves center on strategic partnerships for GaN substrate supply security and software-defined architecture licensing to compress refresh cycles.
Within the radar-heritage tier, RTX and Lockheed Martin Corporation occupy positions shaped by decades of integrated air defense program execution. Rafael Advanced Defense Systems anchors the kinetic interceptor specialization segment. These three exemplify how certification depth and combat-proven system integration create defensive moats against commercial technology entrants.
| Leading Market Players |
|---|
| RTX |
| Lockheed Martin Corporation |
| Rafael Advanced Defense Systems |
| Israel Aerospace Industries |
| Thales |
| Leonardo S.p.A. |
| Saab |
| DroneShield Ltd |
| Dedrone |
| Others |
Value Chain & Pricing Dynamics
Long-term software-subscription contracts with embedded hardware refresh clauses lock in both GaN substrate supply access and price visibility for defense primes bidding on NATO-aligned base protection programs. The FAA's Remote ID mandate and EASA harmonization standards compress procurement cycles while binding buyers to recurring licensing fees for threat library updates.
Pricing Analysis
Defense ministry buyers anchor three-tier pricing structures across premium, standard, and economy levels based on MIL-STD certification depth and integration complexity with Patriot-class radar networks. Price differentiation stems from electromagnetic environmental effects validation tier and volume scale across multi-year base protection contracts. Cost compression in portable RF units is intensifying because commercial technology entrants are undercutting legacy defense pricing on rapid-deployment grids. Commercial data center operators exhibit highest price sensitivity due to unproven ROI models, while naval directed-energy programs show lowest sensitivity given mission-critical collateral damage constraints.
Supply Chain Analysis
Inbound logistics costs through transpacific container lanes from Japanese specialty foundries constrain GaN substrate delivery schedules for high-power RF jammer manufacturers. Gallium nitride wafer production concentrates in Japan and the United States, with solid-state fiber laser components sourcing from Israel and Germany. Raw material dependencies include rare-earth elements for magnet assemblies, high-purity sapphire substrates, and precision optical coatings. Single-source vulnerability around Japanese GaN foundry capacity creates supply chain risk. Distribution runs through defense prime integration facilities with direct military procurement channels dominating downstream fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-drone technology sector represents high-growth disruption as AI-enabled autonomous swarms and software-defined radio mutations force continuous hardware refresh cycles across layered air defense architectures.
For Market Incumbents: Fortify GaN substrate supply security through backward integration into Japanese specialty foundry partnerships or captive wafer supply agreements. Accelerate software-defined architecture licensing to compress 18-24 month MIL-STD certification timelines against emerging pure-play competitors. Prioritize NATO interoperability mandate compliance to lock out non-certified entrants from European defense procurement. For New Entrants and Emerging Players: Cloud-based threat library subscriptions represent a service-layer gap where radar-heritage primes under-serve mid-tier commercial buyers. Target hyperscale data center perimeter security in Virginia and Texas with rapid-deployment RF grids priced below defense-grade alternatives. Pursue joint-venture pathways under India's PLI scheme to establish localized manufacturing credibility for technology transfer contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-subscription counter-UAS providers serving United Kingdom and Australian base security frameworks. Long-term viability over the projection horizon favors targets with MIL-STD certification heritage and demonstrated Patriot radar integration. Monitor NATO counter-UAS doctrine ratification as the critical signal for procurement acceleration across member state ministries.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Substrate Supply Agreement | Secures high-power RF jammer production capacity against Japanese foundry bottlenecks. |
| Software-Defined Architecture Licensing | Enables firmware-upgradeable detection systems that compress hardware refresh cycles. |
| NATO Interoperability Certification | Unlocks joint procurement across European defense ministries under emerging doctrine. |
| Joint Venture under India PLI Scheme | Creates domestic manufacturing pathway for radar and directed-energy component localization. |
| Cloud-Based Threat Library Subscription | Captures recurring revenue from United Kingdom and Australian software-subscription frameworks. |
Study Parameters
Operator-level perspectives from base commanders, electromagnetic effects engineers, defense procurement officers, and critical infrastructure security directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FAA Remote ID rulemakings, EASA drone regulation harmonization documents, NATO counter-UAS doctrine drafts, and defense ministry budget appropriations. Bottom-up unit economics across technology tiers triangulated with top-down procurement volume estimates from United States, Israel, and United Kingdom defense budget disclosures.
Sensitivity analysis tested forecast robustness across GaN supply disruption scenarios, software-defined radio mutation rates, and NATO doctrine implementation timelines. Segmentation dimensions modeled include technology type, end-user budget authority, deployment architecture, and mission-specific application profiles. CAGRs derived from layered integration adoption curves and civilian regulatory mandate compliance schedules. Industry-specific inputs encompassed electromagnetic environmental effects certification timelines and directed-energy power density achievement curves.
Underlying assumptions cover sustained defense budget prioritization for layered air defense and EASA harmonization enforcement, with deviation risk concentrated in spectrum allocation disputes with commercial 5G deployments and GaN substrate supply concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Inspection Drones in Confined Space Market
UAV
Global Aerial Imaging Market
UAV
North America Small UAV Market
UAV
Latin America Small UAV Market
UAV
Drone Delivery Services Market
UAV
Europe Drone Light Shows Market
UAV
Commercial Drone-Enabled Services Market
UAV
Global Drone Light Shows Market
UAV
Europe Tactical UAV Market
UAV
Asia-Pacific Drone Motor Market
UAV
Racing Drone Market
UAV
Drone Identification System Market
UAV
Drone Data Management Market
UAV
Middle-East and Africa Small UAV Market
UAV
Global Smartphone Controlled Drone Market
UAV
Small Drone Market