
 Global Aerial Survey Services Market | 2026-2036
Global Aerial Survey Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerial Survey Services Market Foresight
Centimeter-grade accuracy standards are redrawing competitive boundaries in aerial survey procurement. Fugro N.V. leverages its offshore geotechnical heritage to dominate coastal and marine survey contracts. Nearmap sustains leadership in high-frequency urban imagery through proprietary camera systems and automated processing pipelines. EagleView Technologies competes in North American property analytics by combining aerial capture with insurance underwriting workflows.
Aerial survey services encompass the acquisition, processing, and geospatial analysis of terrain and infrastructure data from airborne platforms operating at altitudes from fifty meters to orbital heights, typically delivering outputs with ground sample distances below ten centimeters for engineering-grade applications. The primary commercial purpose centers on converting raw sensor data into actionable three-dimensional models that support capital planning, risk assessment, and regulatory compliance across asset-intensive industries. LiDAR mapping commands premium pricing in transmission corridor and transportation route surveys where vegetation penetration determines project viability. Drone imaging expands fastest in construction progress monitoring, where weekly flight frequencies displace traditional surveying labor pools. Photogrammetry retains scale advantages in agricultural monitoring, where spectral indices from multi-band cameras drive variable-rate input decisions.
FAA Part 107 waivers and EASA open-category frameworks shape operational altitude and beyond-visual-line-of-sight permissions that determine service economics in the United States and European Union. ISO 21384-3 unmanned aircraft system operational standards and ASTM F38 committee guidelines influence insurance underwriting and client procurement specifications across jurisdictions. Stakeholders must monitor evolving airspace integration timelines and sensor export control classifications to align fleet investments with addressable contract volumes.
Market Dynamics
Centimeter-grade accuracy requirements from utility transmission operators and precision agriculture cooperatives are compressing pricing power across the aerial survey services value chain while elevating technical barriers to contract participation.
Growth Catalysts
- FAA Part 107 expansion:Streamlined commercial drone flight permissions in the United States reduce operational friction for corridor monitoring contracts. Waivers for beyond-visual-line-of-sight operations unlock scale economics in rural transmission networks.
- LiDAR vegetation penetration:Forestry and infrastructure asset managers specify laser scanning for terrain modeling beneath dense canopy cover. This capability determines project viability in tropical and temperate forest zones.
- Australia mining deployment:Rio Tinto and BHP fleet-scale programs validate aerial data as operational infrastructure rather than periodic survey expenditure. Mine site digital twins now refresh weekly rather than annually.
Market Restraints
- Sensor import dependencies:High-resolution LiDAR units and thermal imaging cores concentrate in German and Israeli manufacturing. Tariff exposure and dual-use export controls create supply vulnerability.
- EASA operational altitude ceilings:European open-category frameworks restrict flight heights above 120 meters without specific operational authorization. This compresses corridor survey efficiency relative to jurisdictions with higher permitted altitudes.
- Photogrammetric substitution in flat terrain:Multi-band camera arrays deliver sufficient accuracy for agricultural monitoring at one-third the equipment cost of LiDAR systems. Spectral indices from RGB-NIR capture displace laser scanning in row-crop applications.
Strategic Opportunities
- India agricultural digitization:PM-KISAN satellite integration and state-level precision farming mandates create addressable demand for drone-based crop health monitoring. Cooperative procurement models aggregate smallholder demand into contract-scale volumes.
- ISO 21384-3 certification services:Third-party operational safety verification for unmanned aircraft systems opens recurring revenue streams beyond flight execution. Insurers and municipal procurement specifications increasingly mandate certified operators.
- Hyperspectral-multispectral convergence:Combined sensor payloads enable simultaneous vegetation stress detection and soil moisture mapping. Agronomy service providers bundle these outputs into variable-rate input prescriptions.
Industry Challenges
- Geomatics talent scarcity:Photogrammetrists with simultaneous expertise in point cloud processing and spectral analysis command premium compensation. University pipeline output lags fleet expansion timelines by three to five years.
- Airspace integration complexity:UTM (Unmanned Traffic Management) system deployment varies by national aviation authority. Operators must maintain jurisdiction-specific operational manuals and pilot certification stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerial Survey Services Market |
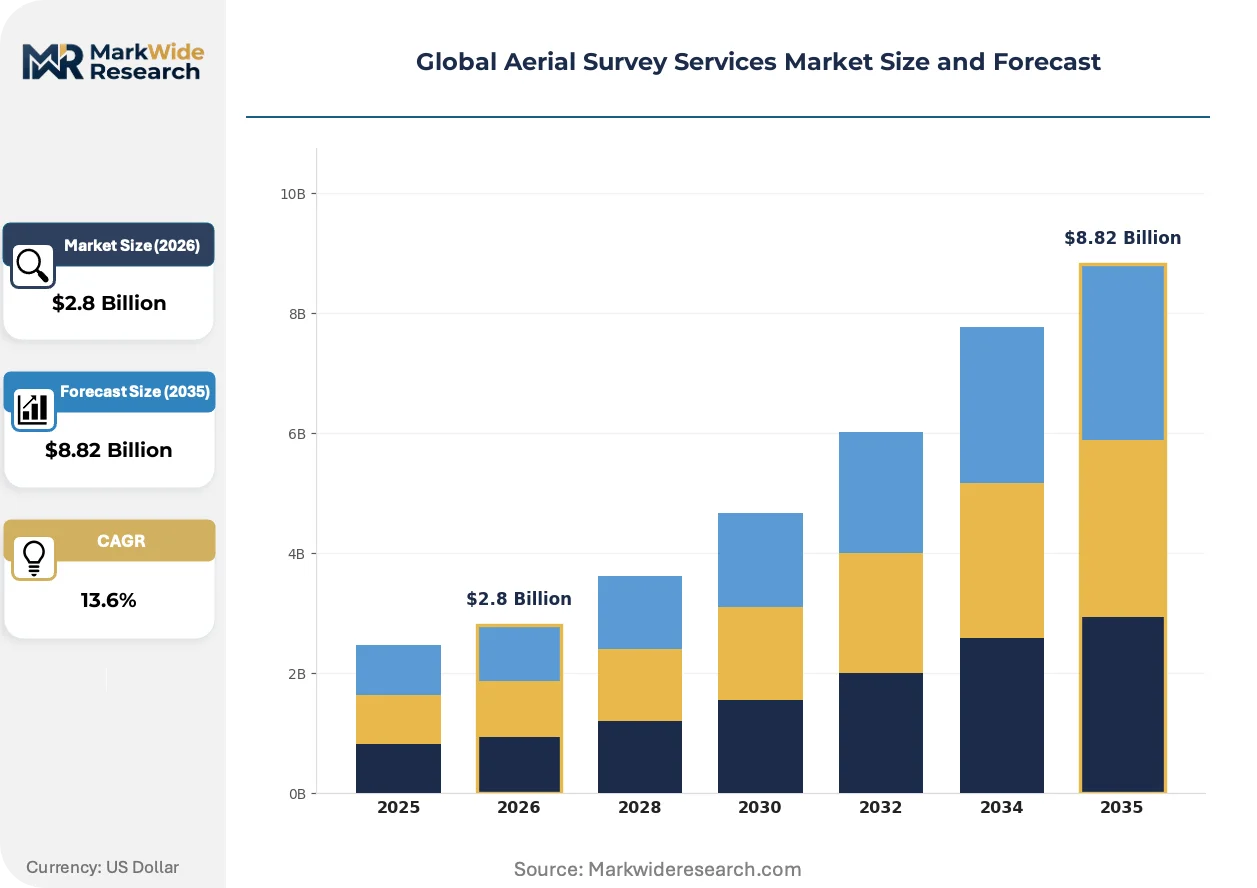
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: LiDAR Mapping, Photogrammetry, Drone Imaging, Thermal Surveying, Hyperspectral Imaging Platform: Fixed-Wing UAVs, Rotary-Wing UAVs, Manned Aircraft, Satellites, Balloons Industry Vertical: Construction, Mining, Agricultural Monitoring, Forestry Management, Environmental Assessments Application: Topographic Surveying, Infrastructure Inspection, Land Use Planning, Disaster Management, Wildlife Monitoring |
| Companies Covered | Fugro N.V., EagleView Technologies, Trimble Inc., Hexagon AB, Terra Drone Corporation, Topcon Corporation, Nearmap, Aerodyne Group, Wingtra AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerial Survey Services Market Shifts & Advancements
Real-time edge processing on aerial platforms is collapsing the traditional acquisition-to-delivery timeline from weeks to hours, reshaping competitive differentiation around speed rather than resolution specifications alone.
Photogrammetric mesh generation is fragmenting the market structure for engineering-grade deliverables. Automated dense-matching algorithms from Pix4D and Bentley ContextCapture now produce survey-grade point clouds from consumer-grade camera payloads. Small regional operators in Brazil and Indonesia compete for topographic mapping contracts previously reserved for LiDAR-equipped specialists. Quality assurance protocols struggle to distinguish algorithmically enhanced outputs from ground-truthed survey data.
EASA drone regulation harmonization across the European Union is standardizing operational certification thresholds. The Specific category framework replaces national variance with unified risk assessment methodologies. Infrastructure operators in Germany, France, and the Netherlands now procure cross-border survey services from single certified entities rather than jurisdiction-specific subcontractors. Insurance underwriters align premium calculations with EASA operational authorization tiers.
Subscription-based data licensing is displacing per-project aerial capture contracts. Nearmap and EagleView have conditioned property insurers and municipal assessors to expect continuous imagery refresh rather than bespoke flight scheduling. Procurement departments in Australian state governments now specify minimum capture frequency in standing offer arrangements. This compresses revenue volatility for fleet operators while elevating capital intensity for sensor refresh cycles.
Global Aerial Survey Services Market Segmentation
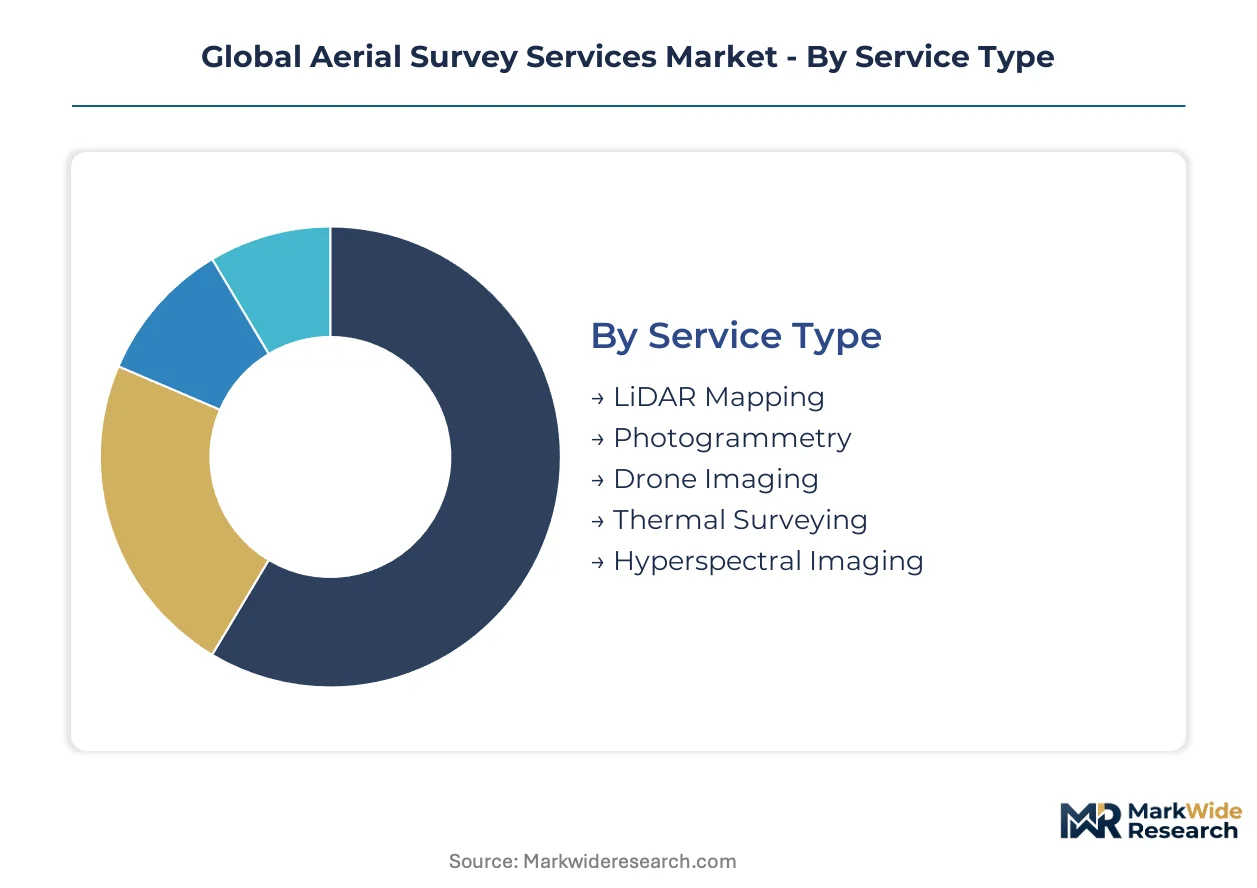
Service differentiation in aerial survey markets hinges on sensor payload economics and regulatory altitude permissions. Procurement patterns diverge sharply between asset-intensive industries requiring centimeter-grade precision and those tolerating meter-scale accuracy for large-area coverage.
Service Type:
Photogrammetry faces the most acute substitution pressure from algorithmic mesh generation tools that compress equipment cost barriers for regional operators.
- LiDAR Mapping:Laser scanning systems penetrate dense vegetation canopy to deliver bare-earth digital elevation models. Utility transmission operators in Australia and the United States specify this capability for corridor surveys beneath temperate forest cover, though German and Israeli sensor import dependencies create supply vulnerability.
- Photogrammetry:Dense-matching algorithms from specialized software vendors now generate survey-grade point clouds from consumer camera payloads. Small operators in Brazil and Indonesia compete for topographic contracts previously reserved for LiDAR-equipped specialists, fragmenting quality assurance protocols.
- Drone Imaging:Weekly flight frequencies displace traditional surveying labor pools in construction progress monitoring. FAA Part 107 waivers for beyond-visual-line-of-sight operations unlock scale economics in rural transmission networks.
- Thermal Surveying:Infrared capture detects heat signatures for photovoltaic plant inspection and building envelope analysis. Equipment costs concentrate procurement among mid-scale service providers.
- Hyperspectral Imaging:Combined multispectral payloads enable simultaneous vegetation stress detection and soil moisture mapping for agronomy service bundling.
Photogrammetry retains volume leadership across contract volumes; hyperspectral imaging climbs the fastest as precision agriculture digitization accelerates.
Platform:
Cost tier stratification separates capital-intensive manned aircraft operations from rapidly depreciating UAV fleets.
- Fixed-Wing UAVs:Extended endurance platforms cover linear infrastructure corridors with efficient power consumption. EASA operational altitude ceilings above 120 meters restrict efficiency relative to jurisdictions with higher permitted heights.
- Rotary-Wing UAVs:Vertical takeoff capability accesses confined construction sites and dense urban environments. Construction progress monitoring in Australian state capitals drives fleet deployment.
- Manned Aircraft:Large-area photogrammetry and LiDAR campaigns for regional mapping authorities. High fixed costs concentrate contracts among established operators with hangar infrastructure.
- Satellites:Orbital platforms deliver spectral indices for agricultural monitoring at ground sample distances insufficient for engineering-grade applications.
- Balloons:Low-altitude tethered systems for localized environmental assessments and academic research missions.
Rotary-wing systems dominate new fleet investment; fixed-wing configurations hold the steepest expansion curve in transmission corridor markets.
Industry Vertical:
Customer type concentration varies by asset replacement cycle intensity and regulatory compliance mandates.
- Construction:Weekly digital twin refresh requirements compress project timelines from months to days. Edge processing on aerial platforms collapses acquisition-to-delivery windows.
- Mining:Rio Tinto and BHP fleet-scale programs in Australia validate aerial data as operational infrastructure rather than periodic survey expenditure. Mine site models refresh weekly rather than annually.
- Agricultural Monitoring:PM-KISAN satellite integration in India and state-level precision farming mandates create addressable demand for drone-based crop health monitoring.
- Forestry Management:LiDAR vegetation penetration determines project viability in tropical and temperate forest zones for carbon inventory verification.
- Environmental Assessments:Regulatory compliance documentation for infrastructure permitting and post-construction monitoring.
Mining commands premium pricing per square kilometer; agricultural monitoring expands most quickly through cooperative procurement aggregation.
Application:
Application maturity correlates with standardization of deliverable formats and client procurement specifications.
- Topographic Surveying:Automated processing pipelines from specialized software vendors democratize access to engineering-grade elevation data. Regional operators in Southeast Asia compete on price.
- Infrastructure Inspection:Subscription-based data licensing displaces per-project capture contracts. Nearmap and EagleView condition property insurers to expect continuous imagery refresh.
- Land Use Planning:Municipal assessors specify minimum capture frequency in standing offer arrangements, elevating capital intensity for sensor refresh cycles.
- Disaster Management:Rapid deployment requirements favor rotary-wing UAVs with minimal launch infrastructure.
- Wildlife Monitoring:Thermal and hyperspectral payloads track population movements in protected area management.
Infrastructure inspection captures the largest revenue share; disaster management applications gain share fastest through emergency response procurement frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor manufacturing concentrates in Germany and Israel, while fleet-scale deployment dominates in Australia and the United States. Demand fragmentation across regulatory jurisdictions creates divergent operational economics for service providers.
United States
Utility transmission operators drive corridor monitoring contracts beneath temperate forest cover. FAA Part 107 waivers for beyond-visual-line-of-sight operations unlock scale economics in rural networks. Houston and Denver clusters host specialist operators serving Permian Basin energy infrastructure.
Australia
Rio Tinto and BHP validate aerial data as operational infrastructure with weekly mine site digital twin refresh. State-level precision agriculture mandates aggregate cooperative procurement volumes. Perth and Brisbane harbor the densest concentrations of fleet-scale service providers.
Germany
High-resolution LiDAR unit manufacturing anchors sensor supply chains for European markets. EASA Specific category frameworks standardize cross-border operational certification. Bavaria and North Rhine-Westphalia concentrate engineering consultancies bundling survey outputs into infrastructure planning workflows.
India
PM-KISAN satellite integration creates addressable demand for drone-based crop health monitoring among smallholder cooperatives. State-level precision farming mandates accelerate fleet deployment timelines. Maharashtra and Gujarat agricultural belts aggregate contract-scale procurement volumes.
China
Construction progress monitoring displaces traditional surveying labor pools in mega-project developments. National aviation authority UTM deployment varies by provincial jurisdiction. Yangtze River Delta and Pearl River Delta clusters integrate aerial capture into smart city infrastructure platforms.
Global Aerial Survey Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with offshore geotechnical heritage separating premium-positioned specialists from price-competitive regional operators. The vendor base spans three tiers: integrated geospatial conglomerates with sensor manufacturing arms, pure-play aerial capture specialists with proprietary processing pipelines, and asset-light regional operators leveraging algorithmic mesh generation tools. Consolidation pressures concentrate among mid-scale operators facing equipment cost barriers and talent scarcity. Dominant competitive moves include strategic partnerships with insurance underwriters and vertical integration into subscription-based data licensing.
Within the integrated geospatial tier, Fugro N.V. and Hexagon AB represent offshore geotechnical heritage and sensor manufacturing integration respectively. Among pure-play capture specialists, Nearmap and EagleView Technologies occupy positions conditioning property insurers and municipal assessors toward continuous imagery refresh expectations. Trimble Inc. anchors the positioning-and-automation technology vector serving construction and agricultural verticals.
| Leading Market Players |
|---|
| Fugro N.V. |
| EagleView Technologies |
| Trimble Inc. |
| Hexagon AB |
| Terra Drone Corporation |
| Topcon Corporation |
| Nearmap |
| Aerodyne Group |
| Wingtra AG |
| Others |
Supply & Pricing Matrix
ISO 21384-3 certification tiers simultaneously gate supplier qualification and stratify contract pricing, with certified operators commanding premium positioning in municipal procurement specifications while uncertified competitors absorb margin compression in commodity photogrammetry segments. Utility transmission operators in Australia and the United States anchor demand for precision-grade deliverables, creating bifurcated pricing dynamics between engineering-grade corridor surveys and agricultural monitoring contracts.
Pricing Analysis
FAA Part 107 operational waivers dictate the pricing tier structure across North American aerial survey markets. Three-tier pricing separates certified BVLOS operators from standard visual-line-of-sight providers and uncertified regional competitors. Price differentiation rests on certification grade and sensor payload specification, with LiDAR-equipped specialists capturing premium positioning against photogrammetry-only rivals. Cost compression in standard-tier construction monitoring intensifies as automated mesh generation tools democratize point cloud production. Agricultural cooperatives exhibit highest price sensitivity, while mining operators in Western Australia demonstrate lowest sensitivity due to operational-critical digital twin refresh requirements.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes intermittently disrupt sensor delivery schedules for LiDAR units manufactured in Germany and thermal imaging cores produced in Israel. Geographic supply concentration centers on German precision optics, Israeli infrared sensor technology, and Chinese UAV airframe assembly. Raw material dependencies span rare-earth magnet components for gimbal stabilization, high-purity germanium for thermal detectors, and specialized glass substrates for multispectral filters. Single-source vulnerability concentrates in high-resolution LiDAR transmitter modules. Distribution runs through direct OEM relationships for fleet-scale mining operators and regional distributor networks serving agricultural cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Centimeter-grade accuracy requirements fragment procurement specifications across utility, mining, and agricultural verticals, creating specialized service niches that resist commoditization despite algorithmic processing advances.
For Market Incumbents: Compound subscription-based data licensing momentum by conditioning municipal assessors and property insurers to expect continuous imagery refresh rather than bespoke flight scheduling. Deepen backward integration into proprietary sensor manufacturing to reduce exposure to German and Israeli supply concentration. Lock in long-term standing offer arrangements with Australian state governments before emerging operators achieve ISO 21384-3 certification parity. For New Entrants and Emerging Players: Hyperspectral agronomy bundling represents the most penetrable white-space target, as precision agriculture digitization outpaces incumbent service coverage in India's Maharashtra and Gujarat agricultural belts. Target cooperative procurement aggregation models that consolidate smallholder demand into contract-scale volumes. Pursue go-to-market partnerships with crop input distributors possessing established rural extension networks. For Investors and Strategic Acquirers: EASA Specific category framework harmonization reshapes the acquisition landscape by enabling cross-border operational scale previously fragmented across national jurisdictions. Long-term viability favors vertically integrated operators controlling sensor manufacturing, processing pipelines, and subscription distribution. Monitor BVLOS waiver approval velocity at FAA as the critical inflection signal for North American corridor survey market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 21384-3 Certification Investment | Unlocks municipal procurement eligibility and insurance premium reductions for certified operators. |
| Proprietary Sensor Manufacturing Integration | Reduces tariff exposure and dual-use export control vulnerability from German and Israeli suppliers. |
| Subscription Data Licensing Expansion | Conditions property insurers and assessors to expect continuous refresh rather than per-project capture. |
| Hyperspectral-Agronomy Service Bundling | Captures precision agriculture digitization demand through variable-rate input prescription integration. |
| BVLOS Operational Authorization Pursuit | Unlocks scale economics in rural transmission networks previously requiring multiple visual-line-of-sight crews. |
Research Methodology
A standing panel of fleet operations directors, utility transmission survey managers, agricultural cooperative procurement leads, and geomatics software product managers provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews combined with regulatory filing analysis from FAA, EASA, and Australia's Civil Aviation Safety Authority, trade customs data for sensor imports, and operator certification registries. Bottom-up contract volume aggregation triangulated against top-down market sizing from aerial platform manufacturer shipment disclosures.
Consistency checks validated volume and value outputs against external benchmarks including UAV fleet deployment databases and geospatial services revenue disclosures across the analysis window. Segmentation modeling incorporated service type, platform configuration, industry vertical, and application maturity dimensions. CAGRs derived from logistic diffusion curves fitted to technology adoption patterns in adjacent precision agriculture and infrastructure monitoring markets. Forecast inputs included airspace integration timelines and sensor cost depreciation trajectories.
Forecasts assume regulatory continuity in FAA Part 107 waiver frameworks and EASA Specific category implementation; material policy shifts would require re-modeling. Sensor export control tightening or tariff escalation constitute specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
North America Drones Market
UAV
Global Drone Autopilots Market
UAV
Drone-As-A-Service Market
UAV
Global Smartphone Controlled Drone Market
UAV
Global VTOL UAV Market
UAV
Racing Drone Market
UAV
Asia-Pacific Drones Market
UAV
Drone Delivery Services Market
UAV
UAV Navigation Systems Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
Tactical UAV Market
UAV
Drone Identification System Market
UAV
Aerial Smart Weapons Market
UAV
North America Fuel Cell UAV Market
UAV
Asia-Pacific Tactical UAV Market
UAV
GCC Drones Market