
 Asia-Pacific Drones Market | 2026-2036
Asia-Pacific Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Drones Market Outlook
The gap between commercial-grade and consumer-grade flight control architectures is narrowing as unified autopilot stacks penetrate both segments. SZ DJI Technology Co., Ltd. leverages its Shenzhen manufacturing base to dominate consumer and prosumer channels across the region. Chengdu Aircraft Industry (Group) Co., Ltd. anchors military and dual-use procurement through state-backed aerospace programs. XAG Co., Ltd. specializes in agricultural application systems with spray payloads optimized for rice paddy topography in southern China and Vietnam.
Asia-Pacific drones encompass unmanned aerial vehicles spanning fixed-wing, multi-rotor, hybrid, and single-rotor configurations with payload capacities from sub-1kg sensors to 200kg+ cargo platforms, powered by lithium-polymer or hydrogen fuel cell propulsion depending on endurance requirements. Their primary purpose spans aerial data acquisition, payload delivery, and autonomous inspection across terrain where manned aviation proves uneconomical or hazardous. Multi-rotor systems capture the dominant share in commercial inspection and surveillance due to vertical takeoff flexibility and sub-$50,000 unit economics at scale. Hybrid platforms represent the fastest-expanding category as delivery operators in Australia and Japan demand fixed-wing range combined with rotary-wing landing precision. AI Integration and Autonomous Flight technology segments concentrate margin pools where software licensing recurring revenue outpaces hardware commoditization cycles.
China's Civil Aviation Administration and Japan's METI enforce divergent airworthiness certification regimes that fragment cross-border product deployment timelines. India's DGCA mandates NPNT (No Permission No Takeoff) protocol integration for all commercial operations above 200 feet AGL, constraining software architecture choices for vendors entering that market. Australia's CASA remote operator certificates impose pilot training minimums that shape fleet management economics for mining and energy survey contractors. Stakeholders must monitor regulatory harmonization progress across ASEAN low-altitude corridors to anticipate where unified type certifications will unlock scaled cross-border deployment.
Market Dynamics
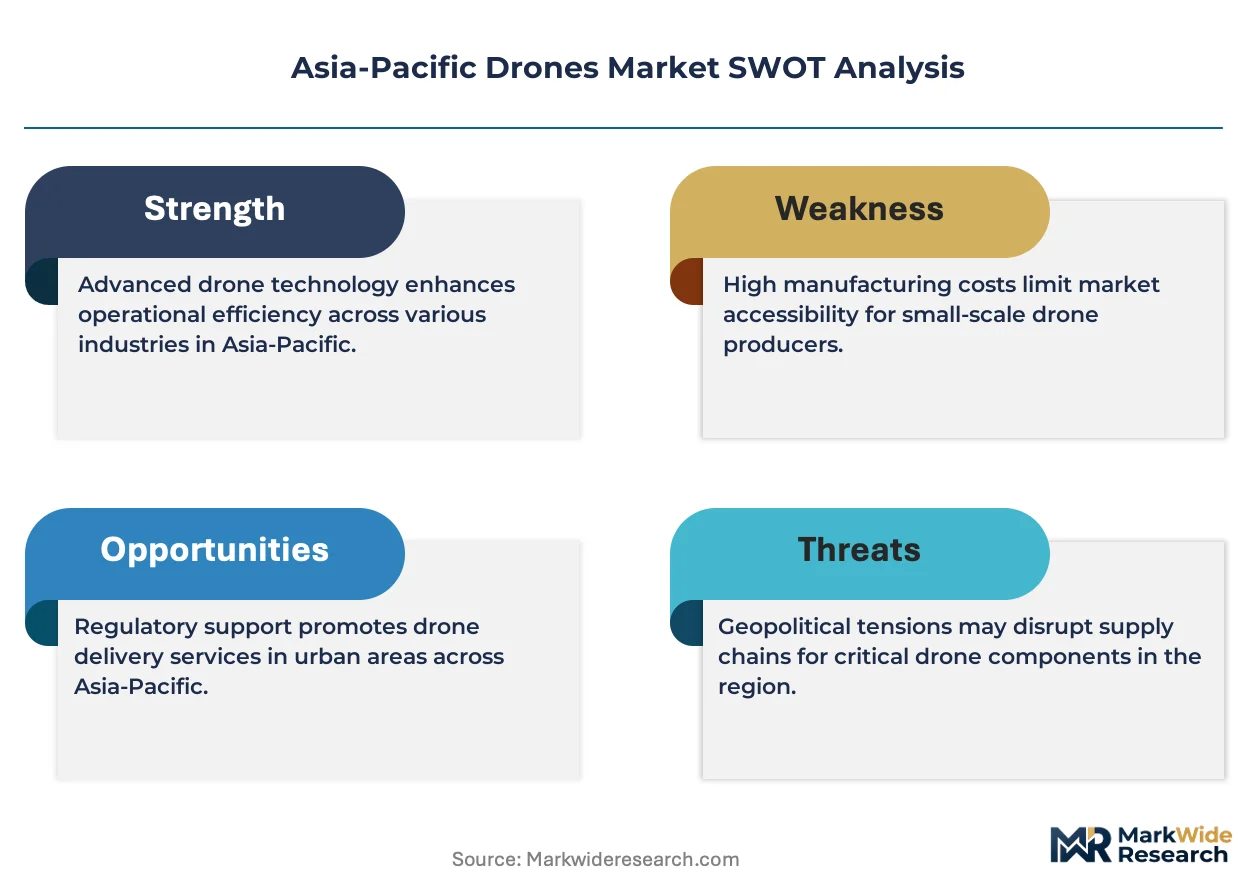
China's low-altitude economy regulatory framework is forcing rapid recertification of existing commercial fleets while fragmenting cross-border deployment pathways across Southeast Asian corridors.
Growth Catalysts
- Japan METI Remote Pilot Framework:Standardized certification tiers for beyond-visual-line-of-sight operations unlock commercial scale for infrastructure inspection and maritime surveillance contracts.
- Precision Agriculture:Rice paddy topography across southern China and Vietnam demands specialized spray payloads, accelerating procurement of hybrid VTOL systems with terrain-following radar.
- Lithium-Polymer Cost Curves:Battery pack economics at scale enable sub-$50,000 multi-rotor unit pricing for commercial inspection fleets in Australian mining and energy sectors.
Market Restraints
- India DGCA NPNT Protocol:Mandatory No Permission No Takeoff software architecture requirements constrain vendor entry timelines and fragment product development roadmaps for operations above 200 feet AGL.
- Hydrogen Fuel Cell Supply:Proton exchange membrane stack production concentrates in East Asian specialist suppliers, creating input cost volatility for long-endurance cargo platform manufacturers.
- Airworthiness Certification Divergence:China's CAAC and Japan's METI enforce incompatible testing regimes, doubling type approval costs for cross-border product deployment.
Strategic Opportunities
- Indonesian Archipelago Logistics:Island-to-island cargo routes remain underserved by manned aviation, creating white space for 200kg+ payload hydrogen fuel cell platforms with autonomous precision landing.
- AI-Enabled Autonomous Stacks:Convergence of computer vision inference hardware and unified autopilot software enables recurring licensing revenue models that outpace hardware commoditization cycles.
- Australian CASA Remote Operator Certificates:Streamlined pilot training minimums for mining survey contractors reduce fleet management overhead and accelerate contractor adoption of fixed-wing inspection systems.
Industry Challenges
- Cross-Border Regulatory Harmonization:ASEAN low-altitude corridor unification remains stalled at working-group level, delaying unified type certifications that would unlock scaled deployment across member states.
- Legacy System Integration:Mining and energy operators require seamless data pipeline compatibility with existing GIS and asset management platforms, extending sales cycles and demanding specialized middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Drones Market |
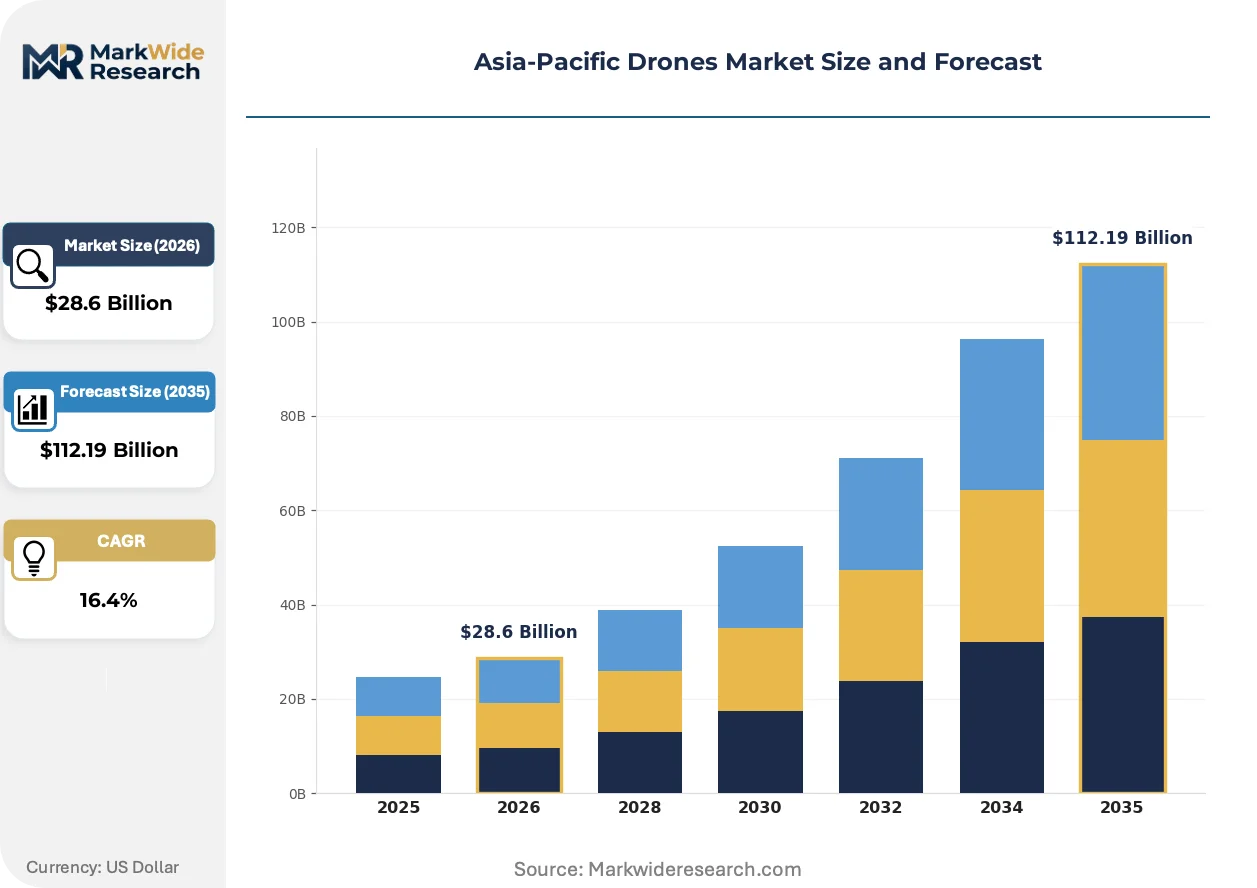
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Wing, Multi-Rotor, Hybrid, Single-Rotor Application: Agriculture, Surveillance, Delivery, Inspection End User: Aerospace, Construction, Law Enforcement, Energy Technology: AI Integration, GPS Navigation, IoT Connectivity, Autonomous Flight |
| Companies Covered | Autel Robotics Co., Ltd., Chengdu Aircraft Industry (Group) Co., Ltd., SZ DJI Technology Co., Ltd., Jouav, XAG Co., Ltd., Guangzhou EHang Intelligent Technology Co., Ltd., Garuda Aerospace, Yuneec International, Terra Drone Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Drones Market Strategic Shifts
Software-defined flight control architectures are compressing hardware differentiation cycles while regulatory fragmentation accelerates regional specialization in certification pathways.
Edge-based AI inference hardware is migrating from centralized ground-station processing to onboard NVIDIA Jetson and Qualcomm Flight platforms. Australian mining survey contractors now demand real-time anomaly detection without persistent datalinks. This migration from ground-dependent architectures is compressing acceptable latency thresholds below 50 milliseconds for critical safety decisions.
China's CAAC low-altitude economy regulations mandate airworthiness certification for commercial platforms above 25 kilograms. The framework requires flight data recorder integration and remote identification broadcasting. Agricultural operators in Guangdong and Hainan provinces are retrofitting existing spray fleets to comply, accelerating domestic aftermarket service revenue concentration.
Energy sector buyers now unbundle hardware procurement from pilot training and maintenance contracts. Australian mining contractors separately source CASA-certified remote operator certificates through third-party training providers rather than OEM bundled offerings. This unbundling is most visible in Western Australia iron ore operations, where fleet scale exceeds 50 units per site.
Asia-Pacific Drones Market Segmentation
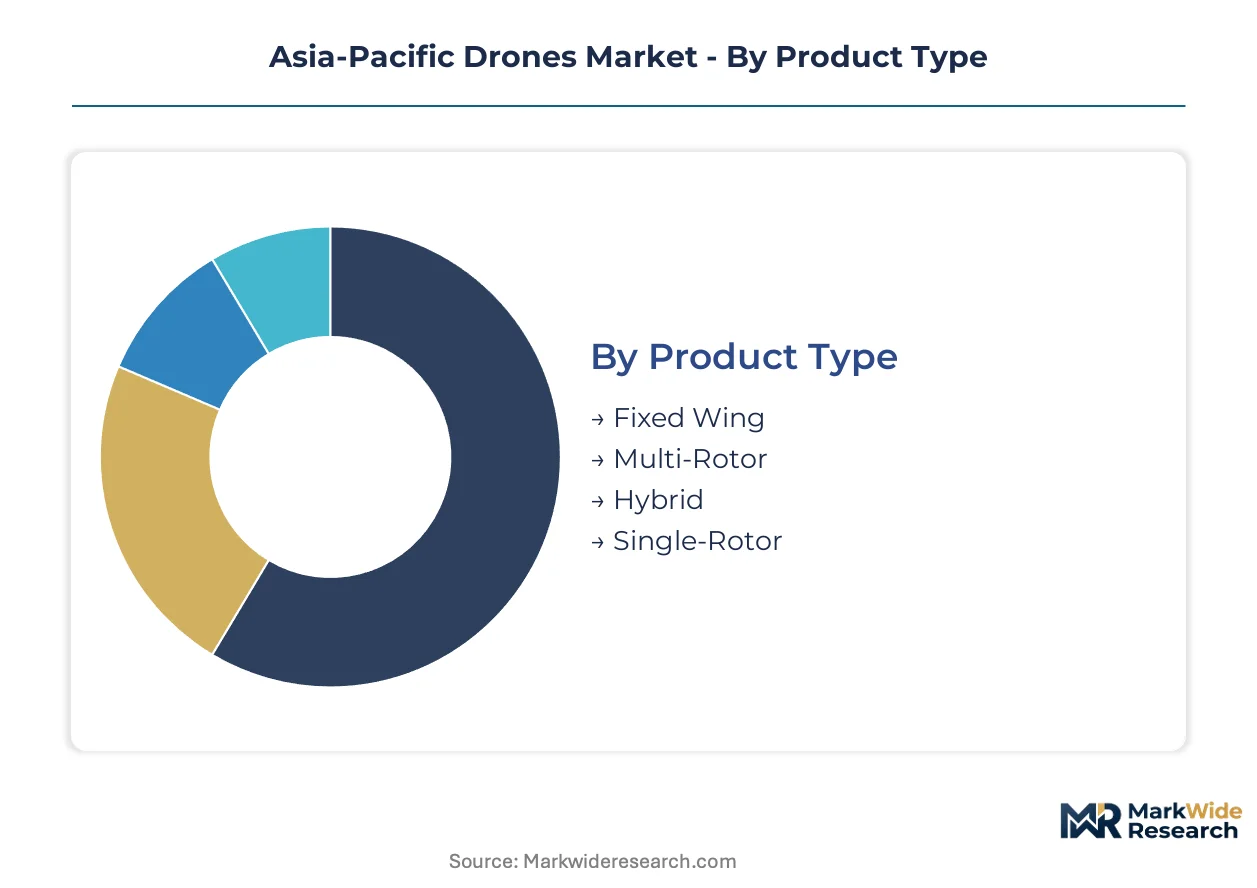
Segmentation in the Asia-Pacific Drones Market reveals how regulatory fragmentation and application-specific payload requirements reshape procurement patterns. Buyers select platforms based on endurance demands, certification pathways, and integration complexity with legacy infrastructure systems.
Product Type:
Platform architecture determines operational ceiling, payload flexibility, and unit economics across deployment scenarios.
- Multi-Rotor:Vertical takeoff capability with four to eight propeller configurations dominates commercial inspection and surveillance contracts. Australian mining operators in Western Australia deploy sub-50kg fleets for conveyor belt and pit wall monitoring where landing space constraints eliminate fixed-wing alternatives.
- Hybrid:Combined fixed-wing range with rotary precision landing addresses delivery corridors across the Indonesian archipelago and Japanese mountainous terrain. Hydrogen fuel cell variants in this category achieve 200km+ ranges for inter-island cargo routes underserved by manned aviation.
- Fixed Wing:Long-endurance platforms with 2-10 hour flight times serve agricultural mapping across Australian wheat belts and Chinese northern plains.
- Single-Rotor:Helicopter-style configurations with higher payload densities support heavy-lift construction logistics in urban Chinese development zones.
Multi-Rotor holds installed capacity. Hybrid is rotating up the share rankings.
Application:
Use-case specialization drives sensor integration requirements and pilot certification tier selection.
- Agriculture:Spray payloads with terrain-following radar target rice paddy topography across southern China and Vietnam's Mekong Delta. XAG Co., Ltd. optimizes droplet dispersion algorithms for humidity conditions in these subtropical growing regions.
- Inspection:Pipeline and transmission tower surveys in Australian energy corridors demand real-time anomaly detection with sub-50 millisecond latency thresholds. Edge-based NVIDIA Jetson inference hardware now migrates from ground stations to onboard platforms.
- Surveillance:Maritime perimeter monitoring along Japanese coastlines and Southeast Asian port facilities utilizes persistent loiter capabilities.
- Delivery:Last-mile medical supply and e-commerce fulfillment trials concentrate in Singapore and Tokyo metropolitan regulatory sandboxes.
Agriculture commands the dominant procurement volume. Inspection is climbing the fastest.
End User:
Customer category shapes fleet scale, maintenance contract structures, and data security requirements.
- Energy:Mining and oil & gas operators in Western Australia and Queensland unbundle hardware procurement from pilot training, sourcing CASA-certified remote operator certificates through third-party providers rather than OEM bundles.
- Construction:Urban development projects in Chinese tier-one cities utilize heavy-lift single-rotor systems for material transport to elevated work sites.
- Aerospace:Defense modernization programs across India and Australia drive dual-use procurement through state-backed aerospace frameworks.
- Law Enforcement:Border patrol and crowd monitoring operations in India require NPNT protocol compliance above 200 feet AGL.
Energy leads capital deployment. Construction is gaining share fastest.
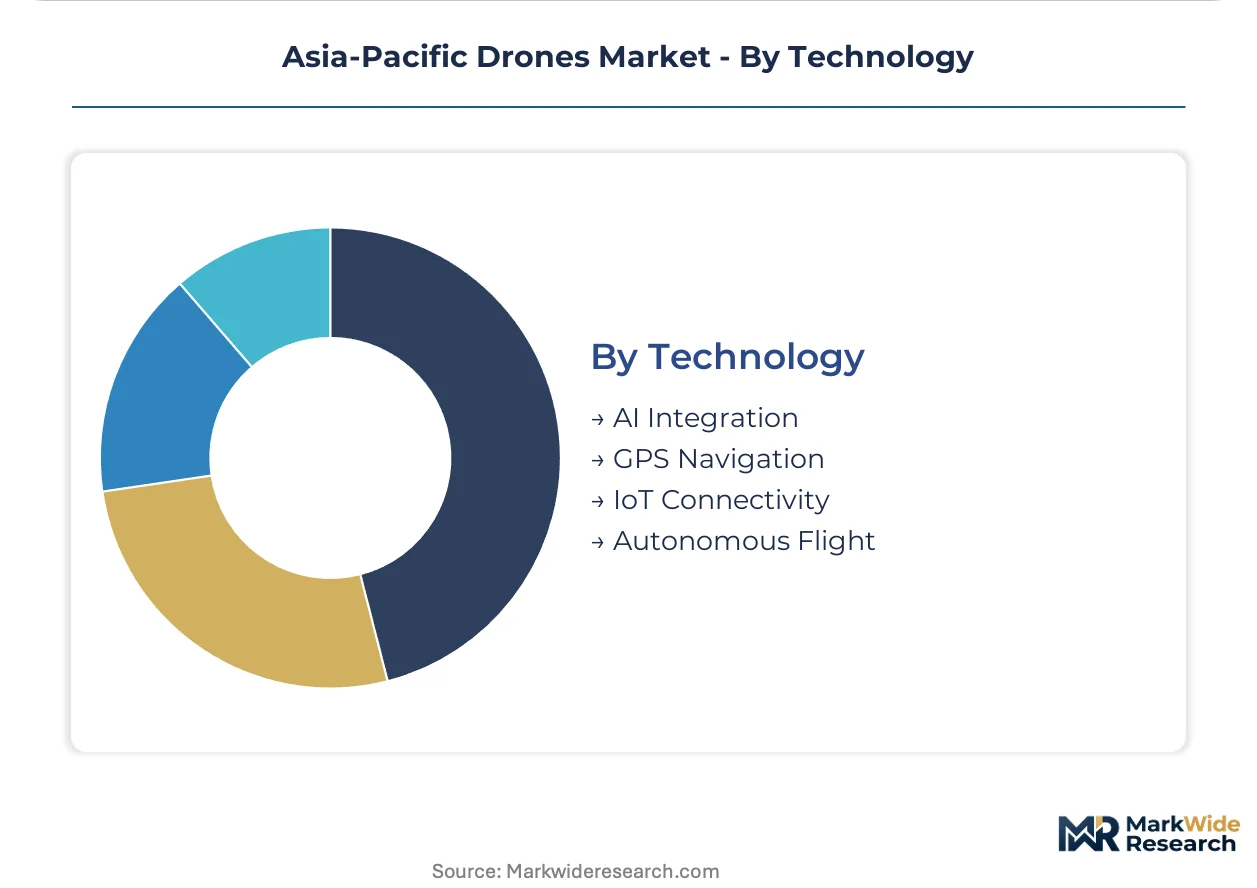
Technology:
Software and sensor architecture determines margin retention and recurring revenue potential.
- Autonomous Flight:Beyond-visual-line-of-sight capabilities unlock commercial scale for infrastructure inspection under Japan's METI-certified remote pilot frameworks. Unified autopilot stacks now penetrate both consumer and commercial segments.
- AI Integration:Computer vision inference hardware enables real-time decision-making without persistent datalinks. This segment concentrates margin pools where software licensing outpaces hardware commoditization cycles.
- GPS Navigation:Precision positioning systems support centimeter-level accuracy for agricultural spraying and construction staking.
- IoT Connectivity:Fleet management platforms integrate with existing GIS and asset management systems, extending sales cycles for vendors addressing mining and energy operators.
Autonomous Flight holds the deepest installed base. AI Integration is ascending the share curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China-based manufacturers export multi-rotor and hybrid platforms to Australian mining contractors and Vietnamese agricultural operators, establishing the dominant trade corridor in the regional drones ecosystem.
China
Defense modernization and precision agriculture budgets drive procurement of heavy-lift and spray-optimized systems. The Civil Aviation Administration mandates airworthiness certification for commercial platforms above 25 kilograms with flight data recorder integration. Guangdong and Hainan provinces concentrate agricultural retrofit activity as operators adapt existing fleets to low-altitude economy regulations.
Australia
Mining survey contractors in Western Australia and Queensland unbundle hardware procurement from pilot training, sourcing CASA-certified remote operator certificates through third-party providers. The Civil Aviation Safety Authority imposes training minimums that shape fleet management economics for energy sector buyers. Pilbara iron ore operations deploy sub-50kg multi-rotor fleets for conveyor belt and pit wall monitoring where landing constraints eliminate fixed-wing alternatives.
Japan
Infrastructure inspection and maritime surveillance contracts accelerate under METI-certified remote pilot frameworks for beyond-visual-line-of-sight operations. The Ministry of Economy, Trade and Industry enforces standardized certification tiers that unlock commercial scale. Mountainous terrain across Honshu drives demand for hybrid platforms combining fixed-wing range with rotary precision landing.
India
Defense modernization programs and border patrol operations propel dual-use procurement through state-backed aerospace frameworks. The Directorate General of Civil Aviation mandates NPNT protocol integration for all commercial operations above 200 feet AGL, constraining software architecture choices for vendors. Garuda Aerospace anchors domestic manufacturing capacity for agricultural and surveillance applications.
Vietnam
Rice paddy topography across the Mekong Delta demands specialized spray payloads with terrain-following radar, accelerating procurement of hybrid VTOL systems. Agricultural spraying operations import Chinese-manufactured platforms adapted for subtropical humidity conditions. Southern provinces concentrate fleet deployment as cooperatives modernize crop monitoring operations.
Asia-Pacific Drones Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented certification environments. The vendor base separates into three tiers: Shenzhen-based manufacturers with integrated supply chains, state-affiliated aerospace conglomerates serving defense procurement, and application-focused specialists optimizing payloads for terrain-specific agriculture. Consolidation pressure concentrates in software-defined flight control stacks where recurring licensing revenue outpaces hardware commoditization. Strategic moves emphasize regulatory pre-certification across multiple jurisdictions and backward integration into battery pack production.
Among Shenzhen-based manufacturers, SZ DJI Technology Co., Ltd. exemplifies channel control through manufacturing scale and consumer-to-prosumer penetration. Chengdu Aircraft Industry (Group) Co., Ltd. anchors the state-affiliated tier, representing dual-use procurement pathways through aerospace frameworks. XAG Co., Ltd. occupies the agricultural specialist position, with spray payload optimization signaling terrain-specific product architecture.
| Leading Market Players |
|---|
| Autel Robotics Co., Ltd. |
| Chengdu Aircraft Industry (Group) Co., Ltd. |
| SZ DJI Technology Co., Ltd. |
| Jouav |
| XAG Co., Ltd. |
| Guangzhou EHang Intelligent Technology Co., Ltd. |
| Garuda Aerospace |
| Yuneec International |
| Terra Drone Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Shenzhen-area lithium-polymer battery production compresses cell pricing and cascades downstream into sub-$50,000 multi-rotor unit economics, while simultaneously pressuring suppliers to consolidate around flight control stack integration to retain margin.
Pricing Analysis
The technology-generation pricing gap separates next-generation hydrogen fuel cell platforms from current-generation lithium-polymer systems and prior-generation lead-acid alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Pricing pressure stems from DJI's manufacturing scale in consumer-to-prosumer channels. Australian mining contractors show highest price sensitivity due to unbundled procurement practices, while Japanese infrastructure operators accept premium tiers for METI-certified BVLOS compliance.
Supply Chain Analysis
Contract manufacturing concentration rests with Shenzhen-based EMS providers and Chengdu aerospace integrators serving state-backed programs. Geographic supply concentrates in China, South Korea, and Japan for battery cells, flight controllers, and composite airframes. Raw material dependencies draw from rare-earth magnet supply for motors, lithium carbonate for cells, and carbon fiber for airframe structures. Single-source vulnerability concentrates in proton exchange membrane stack production for hydrogen variants. Distribution runs through direct OEM channels for defense procurement and tier-one distributor networks for commercial agriculture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against ground-based robotics and satellite imagery services that threaten aerial data acquisition contracts in mining and agricultural monitoring segments.
For Market Incumbents: Build regulatory certification moats across CAAC, METI, and CASA jurisdictions simultaneously. Pursue backward integration into battery pack production to capture cost compression rather than surrender margin to cell suppliers. Counter satellite imagery substitution by emphasizing sub-50 millisecond latency for real-time anomaly detection that orbital platforms cannot match. For New Entrants and Emerging Players: Pursue Indonesian archipelago cargo corridors where 200kg+ payload hydrogen platforms address island-to-island routes underserved by manned aviation. Target Vietnamese agricultural cooperatives in the Mekong Delta with terrain-following spray payloads adapted for subtropical humidity. Enter through software licensing partnerships rather than hardware manufacturing to bypass Shenzhen supply chain scale disadvantages. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among autonomous flight stack developers with AI inference licensing models that outpace hardware commoditization cycles. Long-term viability favors vendors with multi-jurisdiction certification portfolios rather than single-market specialists. Monitor ASEAN low-altitude corridor harmonization progress as the inflection signal for scaled cross-border deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Pre-Approval | CAAC, METI, and CASA simultaneous approval halves cross-border deployment timelines for hybrid platforms. |
| Backward Integration into Battery Production | Captive lithium-polymer cell supply insulates margin from East Asian specialist supplier volatility. |
| AI Stack Licensing Partnership | NVIDIA Jetson and Qualcomm Flight platform integration enables recurring software revenue beyond hardware sales. |
| Hydrogen Fuel Cell Platform Development | 200km+ range unlocks Indonesian inter-island cargo routes where manned aviation economics fail. |
| Third-Party Pilot Training Certification | Unbundled CASA remote operator certificates reduce fleet management overhead for Australian mining contractors. |
Study Parameters
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings. Conversations with CAAC certification officers, METI framework administrators, CASA remote operator assessors, Australian mining fleet managers, and Vietnamese agricultural cooperative directors combined with DGCA NPNT protocol documentation, CAAC low-altitude economy regulations, CASA advisory circulars, and ASEAN working-group position papers. Bottom-up platform shipment estimates and top-down defense procurement budget analysis triangulate market sizing.
Calibration against historical certification timelines and fleet deployment rates shapes the projection framework. Segmentation dimensions span platform architecture, application specialization, end-user category, and technology integration depth across the analysis window. CAGR derivation rests on procurement budget growth in defense modernization and precision agriculture, regulatory harmonization velocity, and battery cost curve trajectories. Hydrogen fuel cell supply constraints and AI inference hardware migration patterns serve as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Australian mining commodity prices, Chinese agricultural subsidy levels, or Japanese infrastructure investment cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and technology cost curves. Quarterly review of ASEAN low-altitude corridor working-group outputs and CAAC certification queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Global Drone Sensor Market
UAV
Electric Glider Market
UAV
Tethered Drones Market
UAV
UAV Simulator Market
UAV
Middle-East and Africa Drones Market
UAV
Military Unmanned Aerial Vehicles Market
UAV
Global Aerial Imaging Market
UAV
Multirotor Drones Market
UAV
United States Drone Services Market
UAV
Solar-Powered UAV Market
UAV
Europe Drone Services Market
UAV
Delivery Drones Market
UAV
Tactical UAV Market
UAV
Fixed Wing Military Drones Market
UAV
Rc Helicopter Market
UAV
FPV Drone Goggles Market