
 Global Smart Commercial Drones Market | 2026-2036
Global Smart Commercial Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Commercial Drones Market Outlook
China's Shenzhen manufacturing corridor is fragmenting as production capacity disperses across secondary hubs. SZ DJI Technology leverages vertical integration across flight controllers and camera gimbals to sustain cost leadership. Skydio, Inc. specializes in autonomous navigation stacks for enterprise security patrols. Parrot anchors European regulatory compliance through its senseFly subsidiary, which dominates fixed-wing surveying across French and German civil engineering contracts.
Smart commercial drones are unmanned aerial vehicles integrating sensor payloads, real-time data links, and onboard processing for commercial task execution, typically operating at 400 feet altitude ceiling under standard aviation waivers. Multirotor configurations lead unit shipments due to vertical takeoff flexibility in confined construction and surveillance environments, while fixed-wing platforms capture margin pools in large-area mapping services where endurance exceeds 90 minutes per sortie. AI integration represents the fastest-growing technology segment as edge-computing inference enables real-time defect detection without ground-station dependency.
The FAA's Part 107 framework and the EU's U-space drone regulations jointly shape airspace access protocols and remote identification mandates across North America and Europe. China's CAAC coordinates with MIIT to enforce GB standard certification for civilian UAV exports, directly conditioning market entry for manufacturers seeking domestic certification reciprocity. Stakeholders must monitor emerging detect-and-avoid mandates and battery fire-safety standards as these technical barriers will determine which platform architectures achieve cross-border operational approval.
Market Dynamics
Edge-computing inference is compressing ground-station dependency and forcing platform vendors to redesign payload architectures around onboard AI accelerators rather than telemetry-heavy designs.
Growth Catalysts
- Brazilian precision agriculture:Soybean and sugarcane operators deploy variable-rate spraying UAVs across Mato Grosso and São Paulo states, converting aerial application from manned helicopters to autonomous fleets.
- FAA Part 107 expansion:Beyond-visual-line-of-sight waivers for infrastructure inspection unlock linear asset monitoring for oil pipelines and electrical transmission corridors without human spotter requirements.
- GB standard certification reciprocity:China's CAAC-MIIT coordination streamlines export pathways for civilian UAV manufacturers seeking domestic certification acceptance in target markets.
Market Restraints
- Lithium-polymer battery thermal volatility:Energy density gains in flight packs trade off against fire-safety certification delays under evolving UN 38.3 transport regulations and airline cargo restrictions.
- Guangdong component concentration:SZ DJI Technology's dominance in flight controller and gimbal supply creates single-source vulnerability for tier-two assemblers seeking alternative vendors.
- Detect-and-avoid technical immaturity:Non-cooperative aircraft sensing remains unproven at scale, blocking routine operations in unsegregated airspace under FAA and EASA mandates.
Strategic Opportunities
- Underpenetrated Indian agricultural spraying:Punjab and Haryana rice-wheat systems lack aerial application infrastructure, creating first-mover space for service providers establishing rural ground crews.
- EU U-space regulatory tailwind:Remote identification mandates and automated traffic management integration favor early-certified platforms in German and French civil engineering contracts.
- 5G network slicing convergence:Ultra-reliable low-latency communication enables real-time video analytics without dedicated radio links, collapsing hardware cost structures for surveillance operators.
Industry Challenges
- Autonomy software certification timelines:EASA's artificial intelligence guidance for safety-critical systems lacks finalized compliance pathways, freezing product roadmaps for European market entry.
- Composite airframe repair skill scarcity:Carbon fiber damage assessment requires specialized non-destructive testing expertise that maintenance networks outside Shenzhen and Toulouse struggle to source.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Commercial Drones Market |
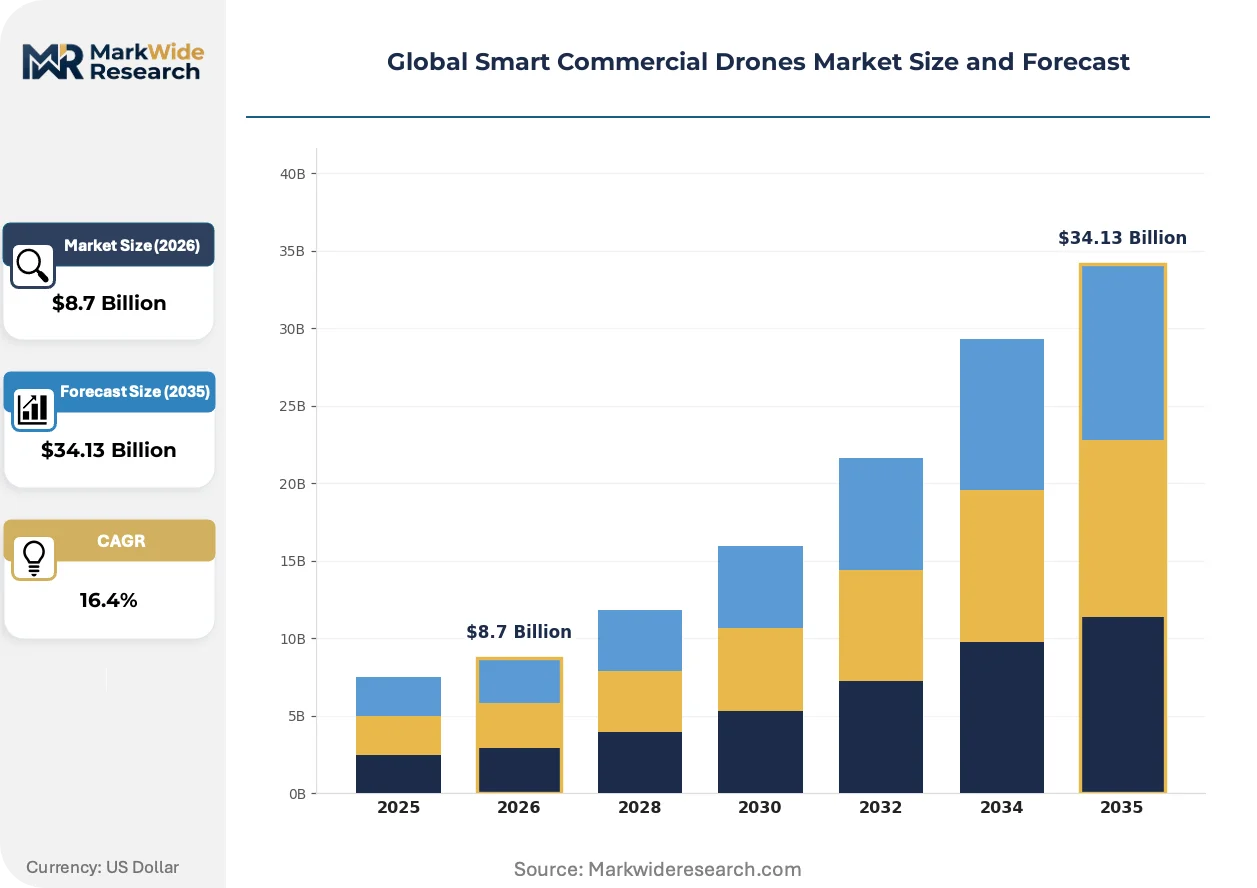
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multirotor, Hybrid, Delivery Drones End User: Agriculture, Logistics, Construction, Surveillance Technology: AI Integration, Autonomous Navigation, Payload Capacity, Battery Type Application: Aerial Photography, Mapping Services, Package Delivery, Search & Rescue |
| Companies Covered | SZ DJI Technology Co. Ltd, AeroVironment Inc., Skydio, Inc., Parrot, Yuneec Holding Ltd, Autel Robotics, 3D Robotics, Inc., PrecisionHawk, senseFly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Commercial Drones Market Strategic Shifts
Sensor fusion architectures are redefining payload value capture, with vendors racing to integrate thermal, multispectral, and LiDAR modules into unified hardware-software stacks that reduce integration friction for end-users.
Onboard inference hardware is migrating from ground-dependent processing to edge-native defect detection. Mining operators in Western Australia now deploy sorties with real-time crack identification in tailings dam walls, eliminating the 15-45 minute latency of cloud upload and human review. This compression of decision loops is reshaping contract structures toward per-flight outcome pricing rather than equipment lease models.
EASA's U-space regulatory package for unmanned traffic management is mandating networked remote identification and geofencing compliance across European operations. Civil engineering surveyors in France and Germany face retrofit requirements for legacy fleets, accelerating replacement cycles for fixed-wing platforms that lack firmware upgrade paths. The compliance burden falls heaviest on small fleet operators without dedicated regulatory affairs staff.
Service-based contracting is displacing equipment ownership in North American infrastructure inspection. Energy utilities in Texas and California now procure aerial data through subscription tiers tied to inspection frequency rather than capital expenditure on airframes. This shift concentrates vendor relationships with platform-agnostic data aggregators who subcontract flight operations to certified pilot networks, compressing margins for original equipment manufacturers.
Global Smart Commercial Drones Market Segmentation
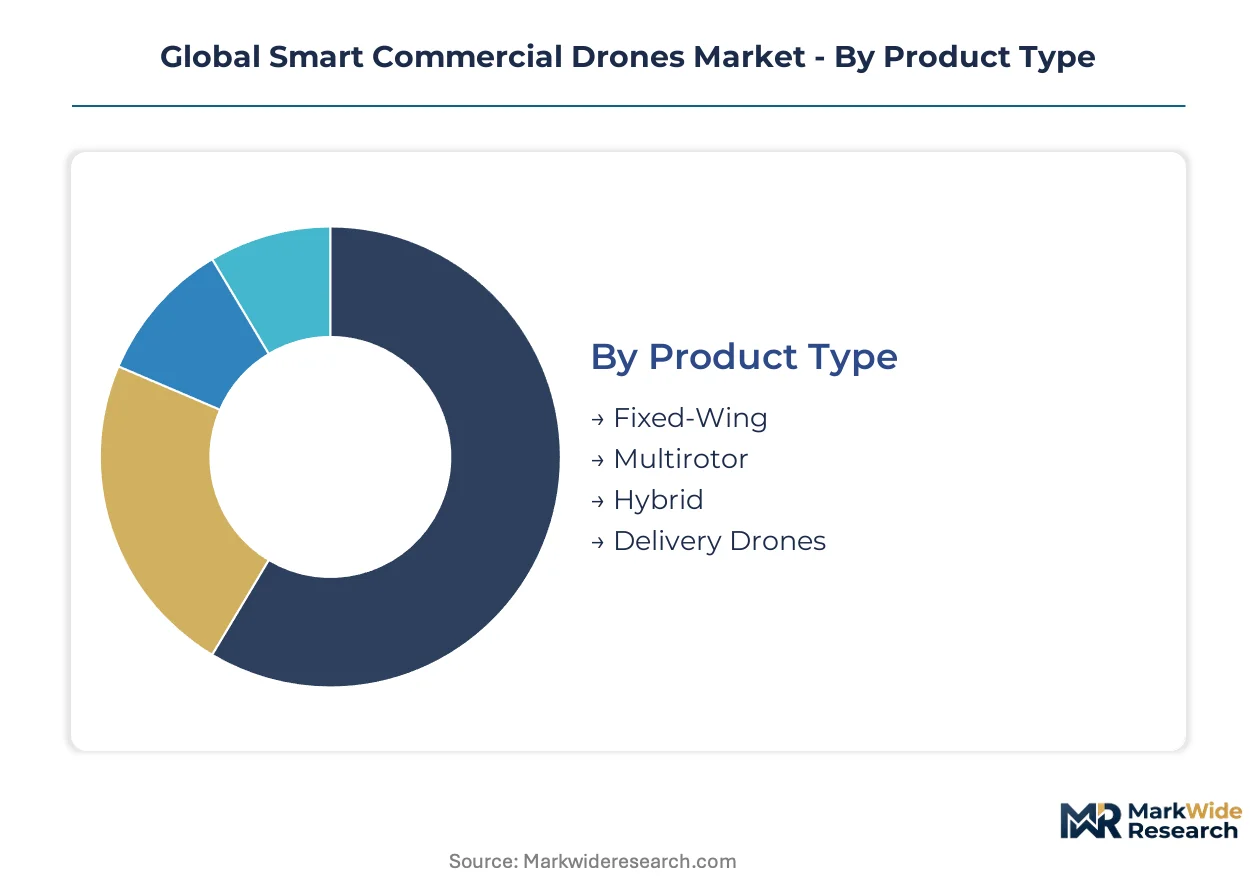
Smart commercial drones segment across flight physics, operational purpose, and intelligence layers. Each axis carries distinct margin profiles, certification burdens, and vendor specialization patterns that shape procurement decisions.
Product Type:
Use-case spectrum spans endurance-intensive corridor mapping to precision maneuvering in confined airspace.
- Multirotor:Vertical takeoff and landing capability eliminates runway dependency. Construction site surveys in São Paulo and security patrols across Texas oil facilities concentrate demand here, with operators prioritizing payload flexibility over flight duration.
- Fixed-Wing:Aerodynamic efficiency delivers 90+ minute sorties for large-area mapping. French civil engineering contracts and Australian mining tailings inspections drive fleet procurement, though launch infrastructure requirements limit deployment flexibility.
- Hybrid:Tilt-rotor architectures combine VTOL convenience with fixed-wing range. Emerging applications in offshore wind turbine inspection and mountainous terrain surveying favor this configuration where both hover stability and transit speed matter.
- Delivery Drones:Specialized payload bays and drop mechanisms optimize for last-mile logistics. Pilot programs in Rwanda medical supply chains and Dubai suburban retail delivery test regulatory tolerance for autonomous package release.
The dominant share belongs to Multirotor, while Hybrid is closing the gap fastest as endurance requirements harden across infrastructure inspection contracts.
End User:
Customer maturity varies sharply, with price tolerance and technical sophistication determining vendor access.
- Agriculture:Variable-rate spraying and multispectral crop monitoring dominate Brazilian Mato Grosso operations. Soybean cooperatives convert helicopter fleets to UAV swarms, with spray drift regulations conditioning nozzle and flight altitude specifications.
- Surveillance:Real-time video feeds with AI-enabled anomaly detection serve prison perimeters, border patrol, and critical infrastructure. Thermal sensor integration and encrypted data links distinguish premium deployments from basic monitoring contracts.
- Construction:Progress documentation and volumetric surveying replace manual measurement crews. German civil engineering firms mandate EASA U-space compliance for urban site work, accelerating fleet refresh cycles.
- Logistics:Hub-to-hub and last-mile delivery trials concentrate in Gulf Cooperation Council states and Chinese megacities. Payload weight restrictions and beyond-visual-line-of-sight waivers determine viable route economics.
Agriculture commands the largest installed base, though Surveillance is expanding most quickly as security budgets harden across Middle Eastern and North American critical infrastructure.
Technology:
Intelligence layers differentiate commodity hardware from defensible platform economics.
- AI Integration:Edge-computing inference enables real-time defect detection without ground-station dependency. Mining operators in Western Australia deploy crack identification algorithms directly on tailings dam inspection flights.
- Autonomous Navigation:Computer vision stacks replace GPS dependency for indoor and denied-environment operations. Skydio's obstacle avoidance systems penetrate enterprise security patrols where signal jamming risks exclude standard navigation.
- Payload Capacity:Lift specifications determine spray tank volumes, camera gimbal weights, and delivery package limits. Agricultural operators in India's Punjab prioritize 10+ liter tanks for rice-wheat system efficiency.
- Battery Type:Lithium-polymer packs dominate due to energy density, though thermal volatility triggers UN 38.3 transport restrictions and airline cargo bans that complicate spare parts logistics.
AI Integration attracts the steepest R&D allocation, while Battery Type innovations face the toughest certification headwinds from evolving fire-safety mandates.
Application:
Service delivery models diverge between data-as-output and physical intervention.
- Mapping Services:Orthomosaic generation and digital elevation models serve surveying, mining, and urban planning. Fixed-wing platforms with integrated LiDAR command premium pricing in German and French civil engineering tenders.
- Package Delivery:Automated release mechanisms and parachute recovery systems enable beyond-line-of-sight logistics. Regulatory sandboxes in Rwanda and the UAE test commercial viability before FAA and EASA rule finalization.
- Aerial Photography:Cinematic and commercial imaging remains the entry point for small operators. Content creator demand in Los Angeles and Mumbai sustains mid-tier gimbal and camera module sales.
- Search & Rescue:Thermal imaging and loudspeaker payloads support emergency response coordination. Alpine rescue services in Switzerland and wildfire agencies in California integrate UAVs into multi-asset response protocols.
Mapping Services generates the highest contract values, though Package Delivery is gaining share fastest as logistics operators pressure regulators for operational scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component sourcing clusters in China's Guangdong province while operational demand fragments across agricultural and infrastructure inspection markets. SZ DJI Technology anchors Shenzhen's manufacturing corridor through captive supply of flight controllers and camera gimbals. Regulatory divergence between FAA, EASA, and CAAC compliance pathways forces vendors to maintain parallel certification tracks.
United States
Energy utilities in Texas and California procure aerial inspection data through subscription contracts rather than capital expenditure on airframes. The FAA's Part 107 expansion for beyond-visual-line-of-sight operations unlocks linear asset monitoring for oil pipelines and electrical transmission corridors. Skydio, Inc. and AeroVironment Inc. concentrate autonomous navigation development in Silicon Valley and Washington DC metro defense corridors.
China
Domestic demand concentrates in precision agriculture across Heilongjiang and Xinjiang farming belts where variable-rate spraying displaces manned helicopter fleets. The CAAC coordinates with MIIT to enforce GB standard certification for civilian UAV exports, conditioning market entry reciprocity. SZ DJI Technology and Autel Robotics anchor Shenzhen's Pearl River Delta manufacturing ecosystem through vertical integration across flight control systems.
Brazil
Soybean cooperatives in Mato Grosso and sugarcane operators in São Paulo states convert aerial application infrastructure to autonomous UAV swarms. ANVISA and the national civil aviation agency regulate spray drift and flight altitude specifications for agricultural chemical deployment. Campinas and Ribeirão Preto host emerging service provider networks establishing rural ground crews for fleet operations.
Germany
Civil engineering firms mandate EASA U-space compliance for urban construction site surveys and volumetric measurement contracts. The EU's remote identification mandates and automated traffic management integration accelerate replacement cycles for legacy fixed-wing fleets. senseFly, a Parrot subsidiary, dominates fixed-wing surveying procurement across Baden-Württemberg and Bavaria infrastructure projects.
Australia
Mining operators in Western Australia deploy edge-computing inference for real-time crack identification in tailings dam walls without ground-station dependency. The Civil Aviation Safety Authority coordinates detect-and-avoid technical standards with mining sector safety protocols. Perth anchors maintenance networks for carbon fiber airframe repair and non-destructive testing expertise.
Global Smart Commercial Drones Market Competitive Environment
Vertically integrated conglomerates and specialized autonomy developers split the market into distinct capability tiers. SZ DJI Technology captures scale economies through backward integration into flight controller and gimbal production. Three archetypes dominate: Shenzhen-based hardware integrators with component captive supply, US-focused autonomy software specialists, and European regulatory compliance anchors. Competitive moves concentrate on strategic partnerships for certification reciprocity and geographic expansion through local service provider networks.
Within the hardware-integrator tier, SZ DJI Technology and Yuneec Holding Ltd occupy positions defined by manufacturing scale and component sourcing depth. Skydio, Inc. exemplifies the autonomy-specialist archetype through computer vision navigation stacks. Parrot represents the European compliance anchor model through its senseFly subsidiary's fixed-wing surveying presence. 3D Robotics, Inc. and PrecisionHawk sit within the North American data-aggregator ecosystem, contracting flight operations to certified pilot networks rather than manufacturing airframes directly.
| Leading Market Players |
|---|
| SZ DJI Technology Co. Ltd |
| AeroVironment Inc. |
| Skydio, Inc. |
| Parrot |
| Yuneec Holding Ltd |
| Autel Robotics |
| 3D Robotics, Inc. |
| PrecisionHawk |
| senseFly |
| Others |
Value Chain & Pricing Dynamics
The Shenzhen-Hong Kong logistics corridor channels component flows from Guangdong manufacturing clusters to global assembly points, with freight cost volatility amplifying price spreads between certified and uncertified platform tiers while battery transport restrictions under UN 38.3 compound downstream margin compression.
Pricing Analysis
FAA Part 107 and EASA U-space compliance tiers dictate the pricing tier structure across the analysis window. Three-tier pricing structure across premium, standard, and economy levels separates EASA-certified fixed-wing platforms from Part 107-compliant multirotor units and uncertified hobby-grade imports. Cost compression in the economy tier is intensifying because Indian and Brazilian agricultural cooperatives prioritize spray tank capacity over navigation sophistication. Agricultural operators in Mato Grosso exhibit the highest price sensitivity, while Australian mining contractors demonstrate the lowest due to outcome-based contracting for tailings dam inspections.
Supply Chain Analysis
US export controls on AI accelerators and Chinese gallium processing restrictions limit semiconductor flows into flight controller manufacturing. Component sourcing draws from China's Guangdong province for gimbal assemblies, South Korea for lithium-polymer cells, and Taiwan for edge-computing chips. Single-source vulnerability concentrates in SZ DJI Technology's flight controller captive supply, which tier-two assemblers cannot readily substitute. Distribution runs through Shenzhen-based OEMs to regional service provider networks in Campinas, Ribeirão Preto, and Perth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward energy utilities and mining operators as procurement consolidates around subscription-based data contracts, fragmenting equipment ownership across pilot-network intermediaries.
For Market Incumbents: Insulate certification moats by accelerating EASA AI guidance compliance before finalized pathways freeze competitor roadmaps. Deepen backward integration into thermal imaging sensor production to offset South Korean battery supplier concentration. Channel control through certified pilot network exclusivity in Texas and California utilities represents the critical defensive lever against data-aggregator margin compression.
For New Entrants and Emerging Players: Pursue regulatory sandbox positioning in Rwanda medical delivery and UAE suburban logistics where BVLOS waivers precede FAA and EASA rule finalization. Underpenetrated Indian agricultural spraying in Punjab and Haryana offers the most penetrable entry point for service providers establishing rural ground crews. A hardware-agnostic data platform bundling flight operations with analytics software provides the optimal go-to-market angle against capital-constrained cooperative buyers.
For Investors and Strategic Acquirers: EASA's U-space remote identification mandate reshapes the acquisition landscape toward firmware-upgradeable fixed-wing platforms with geofencing compliance. Long-term viability centers on autonomous navigation software assets with computer vision stacks applicable across security patrol and denied-environment operations. The signal to watch is FAA detect-and-avoid rule finalization, which would unlock unsegregated airspace operations and revalue autonomy-enabled platform architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Navigation Certification | EASA AI guidance compliance unlocks European civil engineering contracts in Germany and France. |
| Edge-Computing Hardware Integration | Onboard inference eliminates ground-station dependency for Western Australian mining operators. |
| Regional Service Provider Network | Campinas and Ribeirão Preto ground crews capture Brazilian agricultural spraying demand. |
| Battery Safety Certification Investment | UN 38.3 compliance enables airline cargo transport for spare parts logistics. |
| 5G Network Slicing Partnership | Ultra-reliable low-latency communication collapses hardware costs for surveillance operators. |
Study Parameters
Operator-level perspectives from agricultural cooperative managers, mining site engineers, utility inspection coordinators, and civil engineering surveyors anchored the qualitative base. Primary interviews combined with secondary validation from FAA waiver filings, EASA U-space regulatory texts, CAAC GB standard documentation, and customs trade data for Guangdong component exports. Bottom-up fleet deployment estimates and top-down addressable market sizing triangulated volume figures across the projection horizon.
Scenario-bracketing framed the analytical approach with regulatory acceleration and delay variants across the modeling period. Segmentation dimensions encompassed flight physics configuration, operational end-use, intelligence layer integration, and regional regulatory cluster. CAGRs derived from fitted adoption curves weighted by certification timeline probability. Industry-specific forecast inputs included BVLOS waiver approval rates and lithium-polymer energy density improvement trajectories.
Macroeconomic conditions sit as an overlay; deviation in commodity crop prices and mining capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions on regulatory harmonization pace and detect-and-avoid technical maturation. Material shifts in FAA Part 107 expansion scope or EASA AI guidance finalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Firefighting Drone Market
UAV
Global Target Drone Market
UAV
Anti-Drone Market
UAV
Global Drone Inspection and Monitoring Market
UAV
Global VTOL UAV Market
UAV
Multirotor Drones Market
UAV
UAV Payload and Subsystems Market
UAV
Autonomous Underwater Gliders (AUG) Market
UAV
UAV GNSS Antenna Market
UAV
Airborne Digital Battlefield Market
UAV
UAV Simulator Market
UAV
Electric Unmanned Aerial Vehicle Market
UAV
Commercial Drone-Enabled Services Market
UAV
Autonomous Aircraft Cameras Market
UAV
Asia-Pacific Drone Software Market
UAV
Global Drone Autopilots Market