
 Aerial Smart Weapons Market | 2026-2036
Aerial Smart Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Aerial Smart Weapons Market Outlook
The EU Green Deal's defense sustainability provisions is restructuring procurement criteria for aerial munitions across European militaries. Lockheed Martin Corporation leverages its vertical integration in guidance systems to sustain delivery timelines for precision strike packages. BAE Systems anchors European supply chains through its manufacturing presence in the United Kingdom. RTX Corporation competes on sensor fusion architectures that differentiate its portfolio in contested electromagnetic environments.
Aerial smart weapons encompass precision-guided munitions integrating seekers, inertial measurement units, and data links to engage moving or fixed targets with circular error probable measured in single-digit meters. These systems employ composite airframes, multi-mode seekers, and programmable mission computers to execute surveillance, combat operations, reconnaissance, and target acquisition from manned or unmanned platforms. Missiles and guided bombs dominate current procurement volumes as legacy inventories require replacement and stockpiling accelerates among Indo-Pacific buyers. GPS Navigation and Image Recognition technologies capture expanding share as jamming-resistant waveforms and machine-learning target classification mature from demonstration to deployment.
The US Department of Defense, Israel's Ministry of Defense, and the UK's Defence Science and Technology Laboratory shape demand through export control frameworks, interoperability mandates, and sovereign capability requirements that restrict market access for non-aligned suppliers. NATO standardization agreements and national security reviews determine which guidance architectures gain platform integration approvals. Stakeholders must monitor shifting allied procurement coalitions and domestic content thresholds as these dictate which technology suppliers qualify for multi-year program awards.
Market Dynamics
The US Department of Defense's acceleration of autonomous targeting systems is compressing technology refresh cycles and forcing suppliers to restructure development pipelines around software-defined seeker architectures.
Growth Catalysts
- NATO Standardization Agreements:Interoperability mandates across allied air forces are consolidating procurement volumes around certified guidance architectures, expanding addressable market for qualified suppliers.
- Israeli Combat Operations:Sustained aerial modernization programs in contested theaters are validating multi-mode seeker performance and generating export demand from Indo-Pacific militaries.
- Machine-Learning Target Classification:Deployment of jamming-resistant waveforms with embedded neural processing is extending engagement envelopes against mobile targets in GPS-denied environments.
Market Restraints
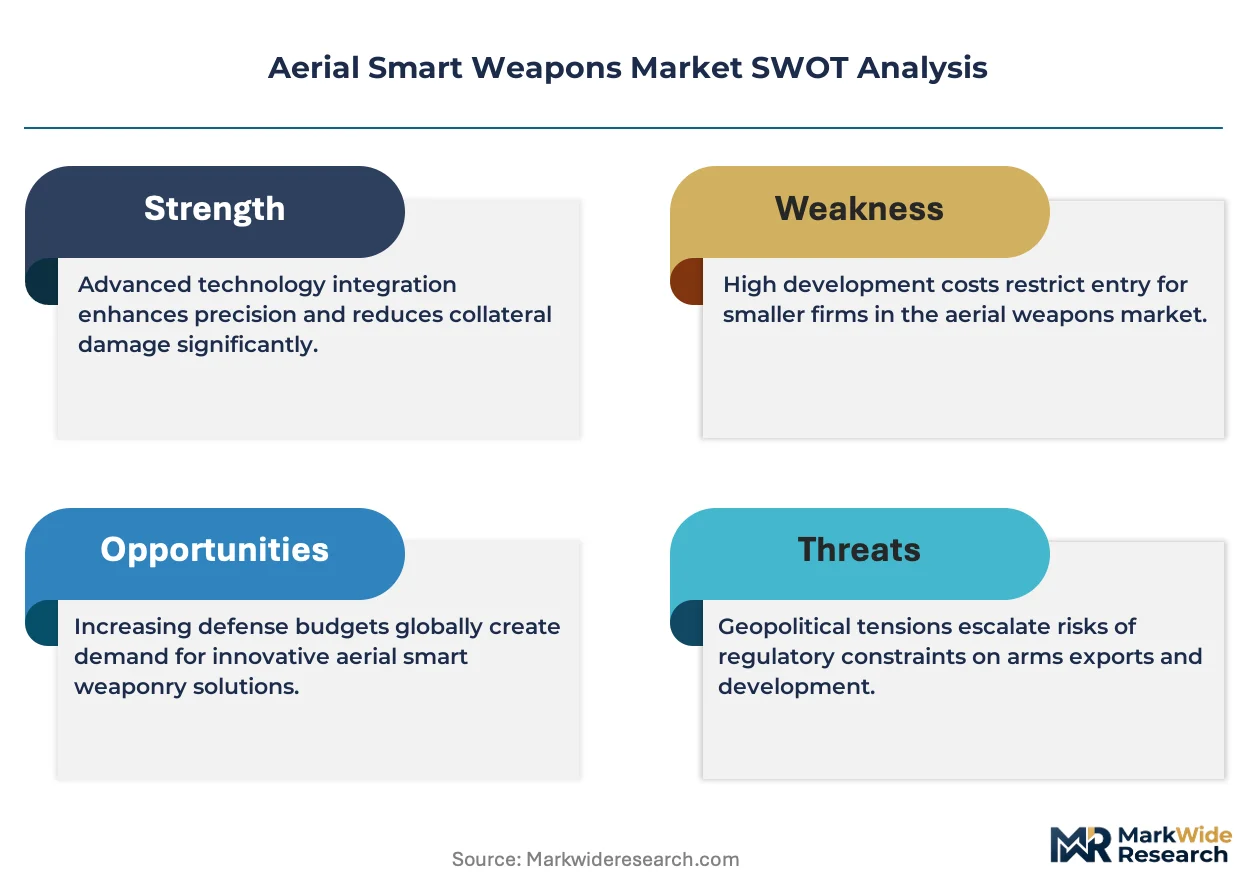
- Semiconductor Supply Concentration:Radiation-hardened mission computers depend on captive foundry capacity concentrated in the United States, creating single-source vulnerability for seeker processing units.
- Export Control Friction:ITAR restrictions and national security reviews extend sales timelines for non-NATO buyers, freezing market access for aligned suppliers seeking Middle Eastern contracts.
- Composite Airframe Input Volatility:Carbon fiber precursor costs fluctuate with aerospace industrial demand, compressing margin structures for guided bomb manufacturers.
Strategic Opportunities
- EU Green Deal Defense Provisions:Sustainability-weighted procurement criteria are creating qualification advantages for suppliers with low-emission manufacturing footprints in European tenders.
- Unmanned Platform Convergence:Integration of miniature precision munitions with Group 4-5 UAVs is opening new mission profiles for loitering munitions in suppression of enemy air defense roles.
- Indo-Pacific Stockpiling:Accelerated inventory builds by Japan, Australia, and South Korea are expanding multi-year program awards for interoperable precision strike packages.
Industry Challenges
- Seeker Algorithm Talent Scarcity:Competition with commercial autonomous vehicle sectors is constraining access to machine-learning engineers capable of real-time target tracking development.
- Platform Integration Timelines:Certification of new munitions on F-35 and Eurofighter fleets requires 18-36 month flight test programs, delaying revenue recognition for guidance system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerial Smart Weapons Market |
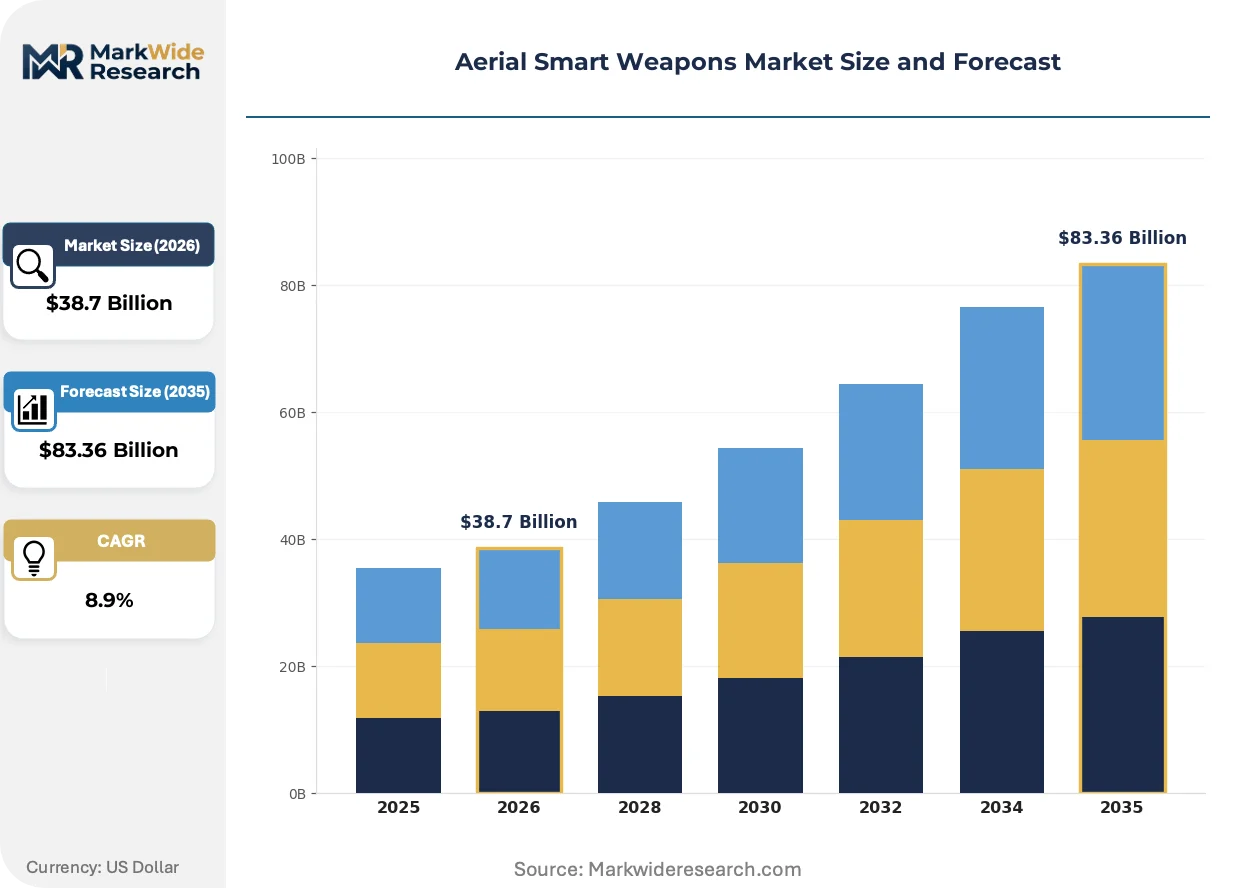
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $83.36 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Weapon Type: Missiles, Drones, Guided Bombs, Torpedoes Technology: GPS Navigation, Infrared Guidance, Laser Targeting, Image Recognition End User: Military, Defense Contractors, Government Agencies, Security Forces Application: Surveillance, Combat Operations, Reconnaissance, Target Acquisition |
| Companies Covered | Lockheed Martin Corporation, BAE Systems, Northrop Grumman Corporation, RTX Corporation, General Dynamics Corporation, The Boeing Company, MBDA, Rafael Advanced Defense Systems, Israel Aerospace Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerial Smart Weapons Market Strategic Shifts
Software-defined seeker architectures are displacing hardware-fixed guidance systems, enabling post-production mission reprogramming and accelerating threat-response cycles without physical retrofit.
Multi-mode sensor fusion is electrifying engagement flexibility in contested electromagnetic environments. Naval strike wings and unmanned combat air vehicles are adopting these architectures fastest, with operational test units fielding combined infrared-millimeter wave seekers within 24-month procurement windows. This convergence is compressing the tradable space between precision munitions and tactical reconnaissance systems.
EU Green Deal sustainability provisions are restructuring European defense procurement evaluation matrices. France's national armament regulator and the UK's Defence Science and Technology Laboratory now embed carbon footprint thresholds in multi-year precision munitions tenders, favoring domestic suppliers with vertical control over energetics manufacturing. Contractors are responding by relocating composite airframe production to low-emission energy grids.
Defense ministries are unbundling munitions procurement from platform acquisition, creating standalone precision strike program offices with independent budget authority. This separation is fragmenting traditional prime-subcontractor relationships and opening direct contracting channels for seeker specialists in Israel and the United Kingdom. The United States Air Force Armament Directorate exemplifies this structural shift, accelerating competition for alternative guidance system suppliers.
Aerial Smart Weapons Market Segmentation
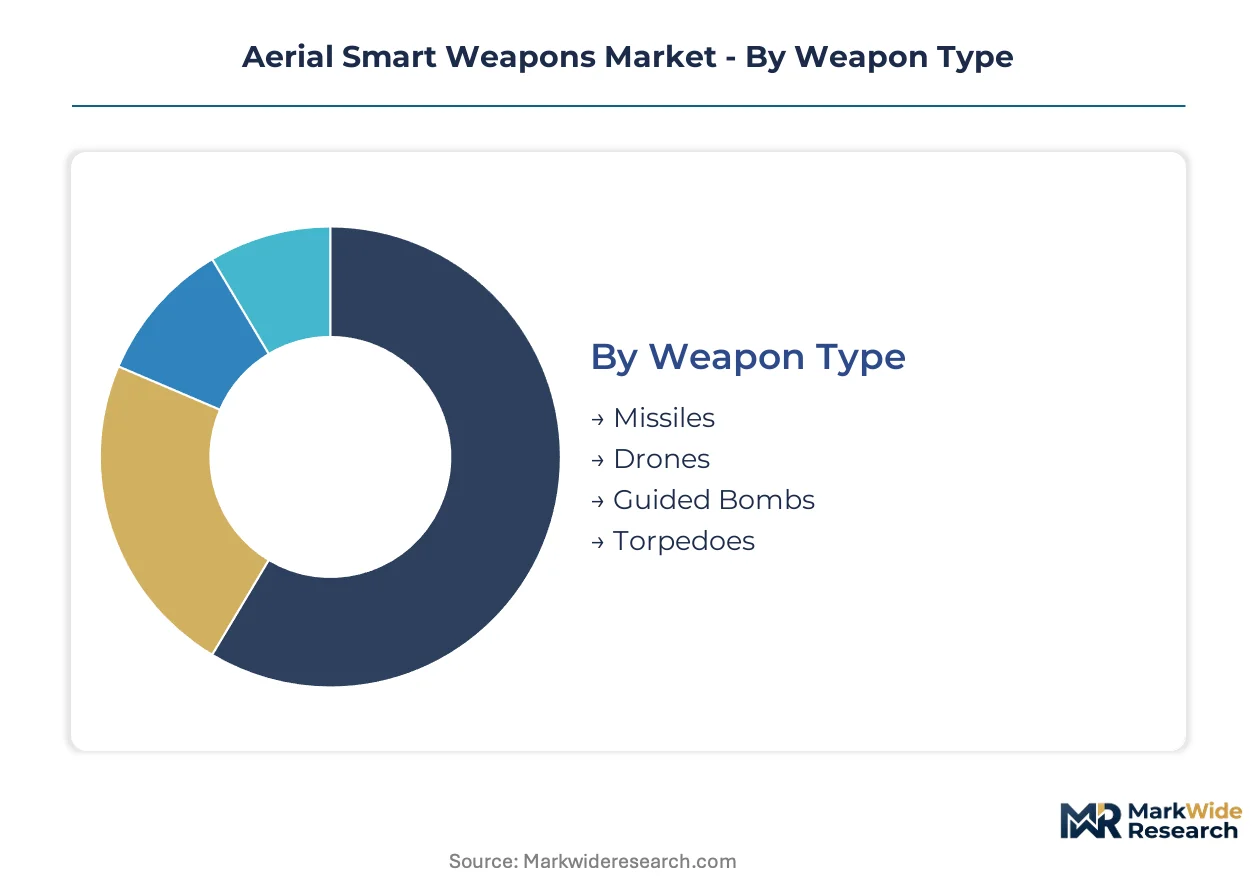
Segmentation in aerial smart weapons reveals how procurement priorities diverge across mission profiles and platform integration requirements. Weapon type and technology selections directly determine seeker architecture investments and manufacturing qualification pathways for suppliers.
Weapon Type:
Replacement cycles for legacy inventories are accelerating procurement volumes across all weapon categories, with platform integration timelines dictating which segments capture near-term awards.
- Missiles:Multi-mode seekers combining radar, infrared, and millimeter-wave guidance dominate air-to-air and air-to-ground engagements. Demand concentrates in the United States and Israel as F-35 integration mandates drive certification investments for extended-range variants.
- Guided Bombs:JDAM-class kits and precision glide weapons employ GPS-inertial navigation with optional laser terminal guidance. Indo-Pacific stockpiling by Japan and Australia is expanding multi-year program awards for interoperable strike packages against fixed and relocatable targets.
- Drones:Loitering munitions with electro-optical seekers execute suppression of enemy air defense missions. Israeli combat operations are validating swarm coordination architectures.
- Torpedoes:Acoustic-homing and wake-hunting guidance systems engage submarine and surface targets from maritime patrol aircraft. Naval strike wings in the United Kingdom prioritize anti-submarine refresh programs.
Volume placements concentrate in Missiles; the faster expansion belongs to Guided Bombs.
Technology:
Cost tiers separate legacy guidance architectures from software-defined seekers with post-production reprogramming capability.
- GPS Navigation:Satellite-aided inertial systems provide all-weather accuracy against fixed coordinates. Jamming-resistant waveforms with embedded anti-spoofing algorithms are climbing the fastest as Indo-Pacific buyers prioritize contested electromagnetic environment performance.
- Image Recognition:Machine-learning target classification enables engagement of moving targets without operator-in-the-loop confirmation. The US Department of Defense's autonomous targeting acceleration is compressing development cycles for neural processing units in seeker heads.
- Infrared Guidance:Cooled and uncooled focal plane arrays detect thermal signatures for passive targeting. Legacy platform integration dominates current procurement.
- Laser Targeting:Semi-active laser seekers require external designation for terminal homing. Special operations forces in the United Kingdom sustain demand for man-portable designator compatibility.
Procurement gravity sits with GPS Navigation; Image Recognition commands the steepest technology investment trajectory.
End User:
Customer type determines budget authority structures and sovereign capability requirements that gate market access.
- Military:National air forces and naval aviation wings operate the dominant procurement volume with platform-centric acquisition frameworks. The US Air Force Armament Directorate exemplifies unbundled munitions procurement with independent precision strike program offices.
- Defense Contractors:Prime integrators and subsystem suppliers compete for seeker and guidance component awards. BAE Systems and RTX Corporation anchor European and US supply chains respectively through manufacturing presence and sensor fusion architectures.
- Government Agencies:Research laboratories including the UK's Defence Science and Technology Laboratory shape interoperability mandates and certification standards.
- Security Forces:Paramilitary and coast guard units acquire limited precision munitions for counter-terrorism and border security roles.
Award concentration favors Military end users; Defense Contractors are gaining direct contracting channels fastest.
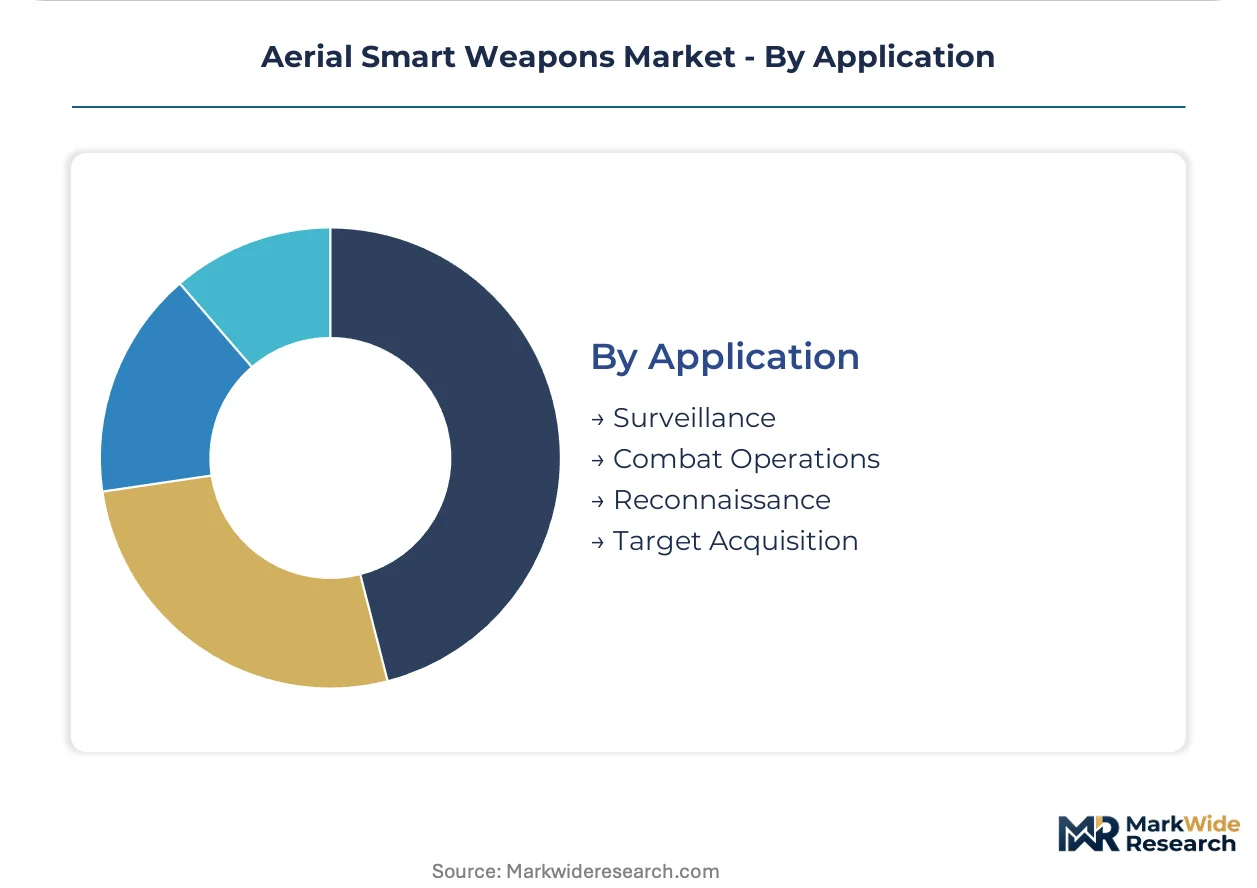
Application:
Mission profile differentiation is reshaping seeker specification requirements and platform integration priorities.
- Combat Operations:Kinetic strike missions demand sub-meter accuracy against hardened and mobile targets. NATO standardization agreements are consolidating procurement volumes around certified guidance architectures for interoperable allied operations.
- Target Acquisition:Sensor-to-shooter networks require real-time data links and multi-spectral cueing. Unmanned combat air vehicles in the United States are adopting these architectures fastest with combined infrared-millimeter wave seekers.
- Surveillance:Standoff reconnaissance employs similar seeker hardware with non-kinetic mission software. Intelligence collection requirements in Israel sustain dedicated platform allocations.
- Reconnaissance:Pre- and post-strike battle damage assessment missions prioritize persistence over precision. Group 4-5 UAV integration is opening new mission profiles.
Program scale centers on Combat Operations; Target Acquisition is expanding platform integration approvals most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates precision munitions manufacturing while Israel and the United Kingdom drive specialized seeker development. Consumption clusters in NATO air forces across the Indo-Pacific rim.
United States
The Department of Defense accelerates autonomous targeting procurement through the Air Force Armament Directorate's unbundled precision strike programs. ITAR frameworks restrict technology transfer while consolidating domestic supply chains. Arizona and Texas host radiation-hardened semiconductor foundries supplying mission computers for GPS-denied navigation systems.
Israel
Combat operations validate multi-mode seeker architectures for loitering munitions and precision glide weapons. The Ministry of Defense shapes export control precedents through technology release protocols for Middle Eastern allies. Haifa and central Israel anchor development clusters for electro-optical guidance and swarm coordination systems.
United Kingdom
The Defence Science and Technology Laboratory embeds carbon footprint thresholds in multi-year munitions tenders under EU Green Deal alignment. BAE Systems maintains manufacturing presence for European supply chain continuity. Scotland and Lancashire concentrate composite airframe production relocated to low-emission energy grids.
Japan
Accelerated stockpiling programs expand multi-year awards for interoperable JDAM-class kits and extended-range missiles. METI coordinates industrial base protection for seeker component suppliers. Nagoya and the Kanto region integrate precision munitions with F-35 platforms through 18-36 month certification timelines.
Australia
Indo-Pacific deterrence priorities drive inventory builds for suppression of enemy air defense roles using miniature precision munitions on Group 4-5 UAVs. The Department of Defence prioritizes interoperability with US and UK guidance architectures. South Australia hosts integration facilities for unmanned combat air vehicle convergence programs.
Aerial Smart Weapons Market Competitive Environment
The competitive structure tilts toward vertically integrated primes with captive guidance system capabilities. Three tiers separate full-spectrum munitions integrators from seeker specialists and component subsystem suppliers. Consolidation pressures favor primes with software-defined seeker architectures over hardware-fixed legacy platforms. Strategic moves center on sensor fusion acquisitions and low-emission manufacturing relocations for EU tender qualification.
Among US-based defense conglomerates, Lockheed Martin Corporation and RTX Corporation exemplify the integrated prime archetype with control over guidance system supply chains. BAE Systems represents the European anchor position through UK manufacturing presence and NATO interoperability certification. Rafael Advanced Defense Systems occupies the specialist tier, demonstrating how combat-proven seeker architectures generate export demand from Indo-Pacific militaries seeking validated multi-mode performance.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| BAE Systems |
| Northrop Grumman Corporation |
| RTX Corporation |
| General Dynamics Corporation |
| The Boeing Company |
| MBDA |
| Rafael Advanced Defense Systems |
| Israel Aerospace Industries |
| Others |
Value Chain & Pricing Dynamics
Carbon fiber precursor costs cascade from aerospace industrial demand through guided bomb manufacturer margin structures, with composite airframe input volatility compressing profitability at standard-tier suppliers while premium-tier seeker specialists capture value through software-defined architectures and post-production reprogramming services.
Pricing Analysis
Outcome-based pricing anchored to mission success rates and circular error probable performance differentiates software-defined seeker architectures from hardware-fixed legacy platforms. Three-tier pricing structure across precision, enhanced, and baseline guidance levels separates F-35 certified suppliers from Eurofighter retrofit specialists and legacy platform maintainers. Pricing pressure stems from semiconductor supply concentration in radiation-hardened mission computers, squeezing margin structures for seeker processing unit suppliers. Defense contractors exhibit lowest price sensitivity due to sovereign capability requirements and ITAR compliance costs, while security forces procurement shows highest elasticity to unit cost fluctuations.
Supply Chain Analysis
Refurbishment flows for seeker heads and inertial measurement units create secondary supply channels that moderate raw material pressure on prime integrators. Manufacturing gravity centers on the United States, Israel, and the United Kingdom for guidance system final assembly, with carbon fiber airframe production relocating to Scotland and Lancashire for EU Green Deal qualification. Radiation-hardened semiconductors draw from captive Arizona and Texas foundry capacity, creating single-source vulnerability for GPS-denied navigation systems. Tariff exposure on composite precursors and ITAR restriction friction constitute primary structural risks. Distribution runs through national armament directorates and unbundled precision strike program offices with independent budget authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as software-defined seeker architectures displace hardware-fixed legacy platforms, forcing subscale guidance system suppliers into acquisition targets or program office exit.
For Market Incumbents: Hedge against seeker algorithm talent scarcity by acquiring machine-learning engineering capabilities from autonomous vehicle sectors before real-time target tracking development pipelines stall. Lockheed Martin Corporation and RTX Corporation should deepen backward integration into radiation-hardened semiconductor foundry capacity to secure captive supply of mission computers against single-source vulnerability. Certification investment for F-35 and Eurofighter platform integration remains the critical defensive lever against Israeli seeker specialists penetrating NATO procurement volumes. For New Entrants and Emerging Players: The mid-tier price-point gap between precision-certified F-35 suppliers and baseline JDAM kit manufacturers creates white-space opportunity for enhanced-tier entrants with jamming-resistant waveform capabilities. Target Australia's Indo-Pacific deterrence programs and Japan's accelerated stockpiling initiatives as most penetrable geographies, where interoperability mandates with US guidance architectures lower certification barriers. A direct contracting channel to unbundled precision strike program offices offers the fastest go-to-market angle outside traditional prime-subcontractor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor electro-optical guidance specialists in Israel and sensor fusion architecture providers in the United Kingdom where combat-proven validation generates export demand premiums. Long-term viability over the projection horizon rests on software-defined seeker capabilities with post-production reprogramming revenue streams. Monitor NATO standardization agreement amendments and EU Green Deal defense sustainability threshold adjustments as early inflection indicators for qualification advantage shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Seeker Architecture Development | Enables post-production mission reprogramming for the US Air Force Armament Directorate's unbundled procurement model. |
| Low-Emission Manufacturing Relocation | Qualifies suppliers for UK Defence Science and Technology Laboratory tenders embedding EU Green Deal carbon thresholds. |
| Machine-Learning Engineering Acquisition | Addresses seeker algorithm talent scarcity constraining real-time target tracking development pipelines. |
| Radiation-Hardened Foundry Capacity Expansion | Reduces single-source vulnerability for GPS-denied navigation mission computers in contested electromagnetic environments. |
| Indo-Pacific Interoperability Certification | Captures multi-year program awards from Japan, Australia, and South Korea's accelerated precision strike stockpiling. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with primary interviews conducted across program managers at the US Air Force Armament Directorate, guidance system engineers at BAE Systems and Rafael Advanced Defense Systems, procurement officers at Japan's METI, and precision strike specialists at the UK's Defence Science and Technology Laboratory. Secondary validation drew from NATO standardization agreement documentation, ITAR export control registers, EU Green Deal defense sustainability provisions, and Department of Defense budget justification materials. Bottom-up segment sizing across weapon type, technology, end user, and application dimensions reconciled with top-down defense expenditure allocation analysis.
Data-stream reconciliation between procurement volume tracking and technology adoption curves informed the analytical framework across the projection horizon. Segmentation modeling incorporated weapon type differentiation, guidance technology maturity tiers, platform integration complexity levels, and regional sovereign capability requirements. CAGRs derived from weighted average growth assumptions calibrated to defense budget trajectory analysis and replacement cycle timing for legacy precision munitions inventories. Industry-specific forecast inputs included F-35 platform certification pipeline visibility and Indo-Pacific stockpiling program commitment timelines.
Inputs from defense ministry procurement databases and prime contractor guidance system revenue disclosures were available through the study window; gaps in classified program funding levels and seeker algorithm development timelines introduce uncertainty bands around autonomous targeting acceleration scenarios. Practitioners should monitor NATO interoperability mandate amendments, ITAR restriction relaxation proposals, and EU Green Deal threshold adjustments for early signals of qualification advantage redistribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
UAV Navigation Systems Market
UAV
Drones Market
UAV
Europe Tethered Drone Market
UAV
North America Drone Services Market
UAV
Drone Powered Business Solutions Market
UAV
Drone Leasing Market
UAV
Europe Drones Market
UAV
Airborne Digital Battlefield Market
UAV
UAV Simulator Market
UAV
Asia-Pacific Tethered Drone Market
UAV
Anti-Drone Technology Market
UAV
UAV Drones Market
UAV
Europe Drone Services Market
UAV
Global Drone Software Market
UAV
Rc Helicopter Market
UAV
Fixed-Wing VTOL UAV Market