
 Drones Market | 2026-2036
Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Drones Market Intelligence
Capital-intensity divergence between sensor-integrated platforms and basic camera drones is rotating competitive advantage toward vertically integrated manufacturers. DJI leverages in-house chip design and gimbal production to sustain margin control across consumer and enterprise tiers. Skydio specializes in autonomous navigation software, anchoring its position in defense and public safety contracts where obstacle avoidance accuracy commands premium positioning.
A drone is an unmanned aerial vehicle powered by electric motors or combustion engines, typically operating at altitudes below 400 feet with payload capacities ranging from grams to hundreds of kilograms depending on configuration. Its primary commercial purpose spans aerial data acquisition, physical delivery, and remote sensing across industries requiring spatial intelligence without manned aircraft economics. Multi-rotor systems dominate consumer and light-commercial segments due to vertical takeoff simplicity and maneuverability in confined spaces, while fixed-wing platforms capture infrastructure mapping and agricultural monitoring where endurance and range determine unit economics. Hybrid configurations are gaining structural traction in logistics trials, though battery energy density limits remain the binding constraint on payload-distance performance.
The FAA's Part 107 framework and evolving BVLOS waiver processes shape US commercial deployment timelines, while EASA's drone-specific regulations under EU 2019/947 standardize operational categories across European member states. China's CAAC coordinates with MIIT on low-altitude economy zones, creating designated airspace corridors that accelerate domestic delivery pilot programs. Stakeholders must monitor regulatory divergence between permissive test environments and restrictive operational certifications, as compliance architecture will determine which technology investments convert to scalable revenue streams.
Market Dynamics
Battery energy density constraints are compressing payload-distance economics while regulatory fragmentation between permissive test zones and restrictive operational certifications forces manufacturers into parallel compliance architectures. This tension determines which technology investments convert to scalable revenue streams.
Growth Catalysts
- BVLOS regulatory frameworks:Brazil's aviation regulator is scaling precision agriculture fleets under evolving beyond-visual-line-of-sight waivers, unlocking agricultural monitoring at commercial scale.
- Low-altitude economy zones:China's CAAC coordinates with MIIT on designated airspace corridors that accelerate domestic delivery pilot programs and component ecosystem integration.
- Autonomous navigation software:Defense and public safety agencies demand obstacle avoidance accuracy that commands premium positioning for specialized platform providers.
Market Restraints
- Lithium-polymer cell supply:Battery energy density limits remain the binding constraint on payload-distance performance for hybrid logistics configurations.
- Guangdong component concentration:Manufacturing ecosystems for consumer and enterprise tiers concentrate in a single Chinese province, creating geographic supply vulnerability.
- FAA Part 107 friction:Evolving waiver processes and restrictive operational certifications in the United States compress commercial deployment timelines relative to test environment progress.
Strategic Opportunities
- EU 2019/947 standardization:EASA's drone-specific regulations create operational category clarity across European member states, enabling cross-border service scaling.
- Sensor-integrated platform convergence:Multi-spectral imaging fused with real-time data analytics opens precision agriculture and infrastructure inspection white space.
- Direct-to-operator distribution:Enterprise buyers increasingly bypass traditional aerospace channels for manufacturer-direct procurement with embedded training and certification support.
Industry Challenges
- Certification timeline compression:FAA, EASA, and CAAC operate on divergent type certification schedules, forcing manufacturers into redundant testing regimes.
- Embedded systems talent scarcity:Flight control firmware and computer vision engineering functions face acute hiring competition from automotive autonomy programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drones Market |
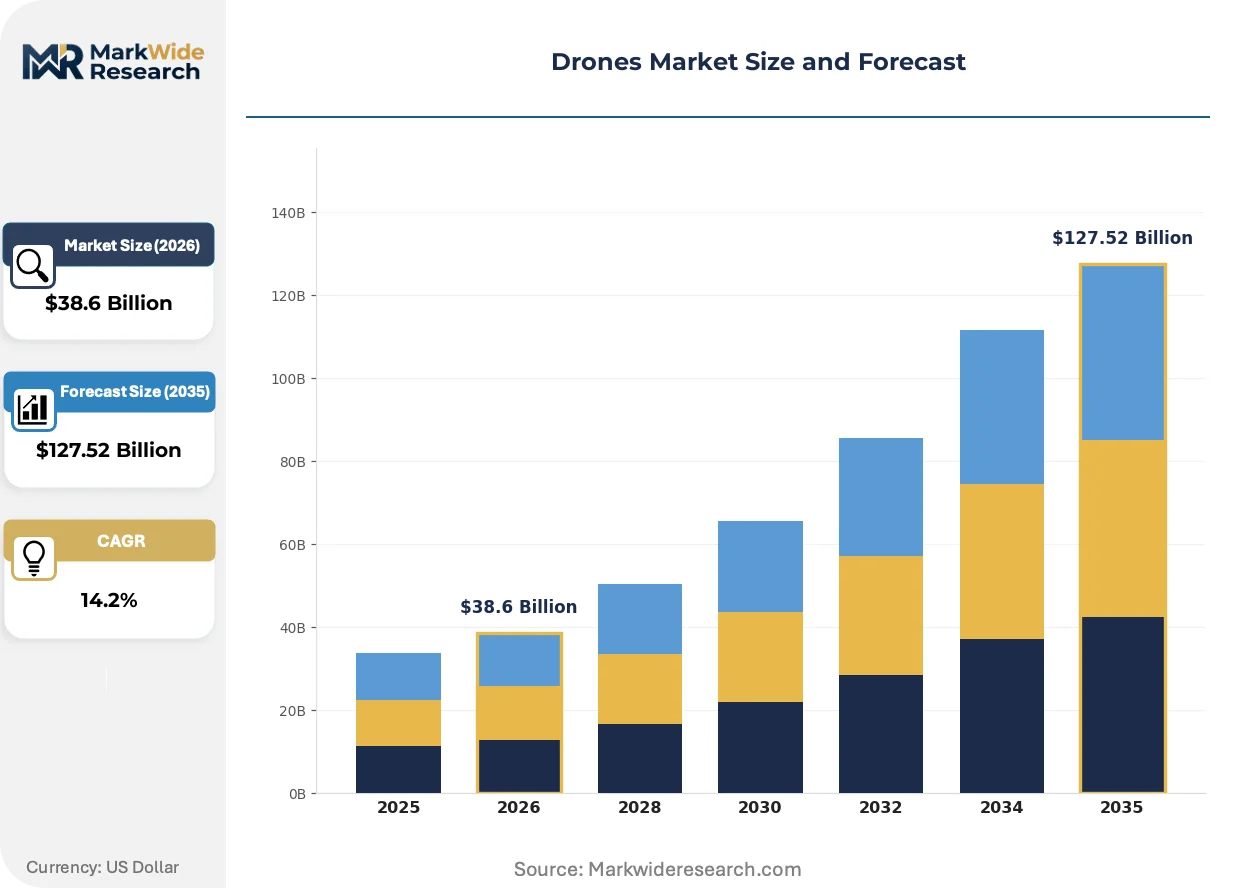
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multi-Rotor, Single-Rotor, Hybrid End User: Agriculture, Law Enforcement, Construction, Filmmaking Application: Surveillance, Delivery, Mapping, Search & Rescue Technology: FPV, BVLOS, GPS, AI |
| Companies Covered | DJI, Skydio, Autel Robotics, Parrot, AeroVironment, Yuneec, General Atomics Aeronautical Systems, Northrop Grumman Corporation, Freefly Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drones Market Strategic Shifts & Innovations
Autonomous flight systems are reshaping competitive boundaries between hardware-centric and software-centric vendors. Three distinct vectors are compressing traditional differentiation models.
Computer vision-based navigation is bifurcating the competitive landscape between camera-dependent and sensor-fusion platforms. Defense contractors and first-response agencies are adopting fully autonomous systems at accelerated procurement cycles. This technology is compressing the addressable market for pilot-dependent hardware while expanding premium tiers for zero-intervention reliability.
EASA's EU 2019/947 framework establishes standardized operational categories across member states, replacing fragmented national exemptions. Industrial consequence includes simplified cross-border service deployment for logistics and inspection operators. Agricultural monitoring fleets in France and Germany are responding by consolidating multi-country contracts under unified compliance architectures.
Enterprise procurement is consolidating around bundled hardware-software-service contracts with embedded regulatory compliance support. Traditional aerospace distributors are losing share to manufacturer-direct channels offering integrated training and certification. This pattern is most visible in German industrial inspection and Japanese infrastructure monitoring verticals.
Drones Market Segmentation
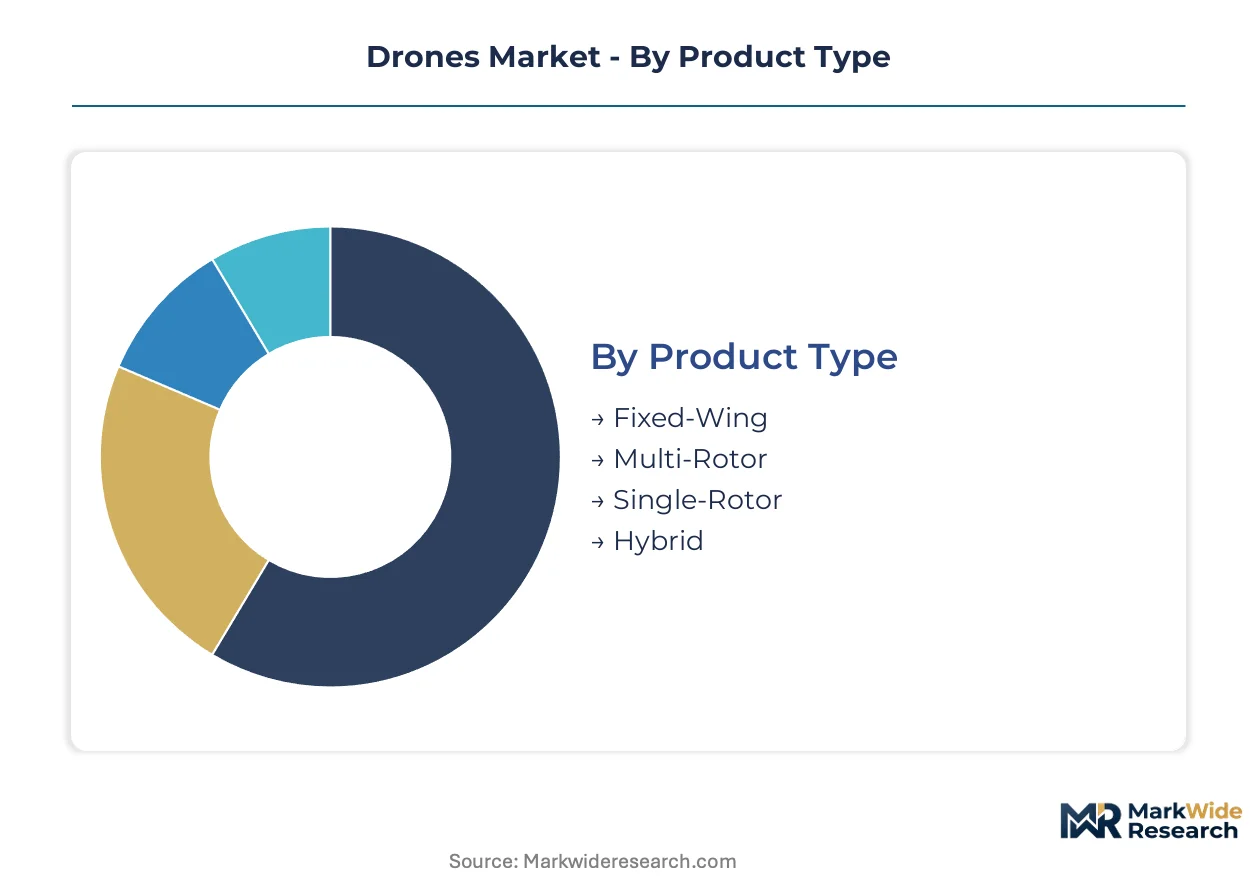
Drone market segmentation reveals how platform architecture, operational purpose, and regulatory maturity create divergent investment profiles across hardware tiers and service models. Understanding these fault lines enables stakeholders to match capability development against addressable demand pockets.
Product Type:
Fixed-wing platforms dominate export-led agricultural monitoring contracts in Brazil and Australia, while multi-rotor systems anchor domestic consumer and light-commercial volumes concentrated in China's Guangdong manufacturing corridor.
- Fixed-Wing:Extended endurance configurations with glider-derived aerodynamics achieve flight times exceeding 90 minutes. Agricultural monitoring contracts in Brazil and Australia concentrate demand where acreage coverage per sortie determines unit economics.
- Multi-Rotor:Quad- and hexacopter architectures with vertical takeoff capability dominate consumer and enterprise tiers. Guangdong assembly lines feed both domestic Chinese demand and export channels for cinematography and inspection applications.
- Single-Rotor:Helicopter-style platforms with main-tail rotor configurations serve specialized heavy-lift niches. Limited production runs concentrate in German and Japanese precision engineering clusters.
- Hybrid:VTOL-fixed-wing combinations attempt to merge maneuverability with range. Logistics trials in China's low-altitude economy zones test payload-distance performance against lithium-polymer constraints.
Multi-rotor commands the established base. The steepest expansion runs through hybrid configurations as energy density improvements unlock commercial logistics viability.
End User:
Cost-tier segmentation separates capital-intensive agricultural fleet operators from procurement-light creative professionals, with law enforcement occupying a mid-tier equipment refresh cycle.
- Agriculture:Fleet operators deploy multi-spectral imaging for crop health monitoring and precision spraying. Brazilian producers under ANVISA-coordinated BVLOS waivers scale beyond-visual-line-of-sight operations across soybean and sugarcane belts.
- Law Enforcement:Public safety agencies require obstacle avoidance accuracy for urban search and surveillance. Procurement concentrates at state and municipal budget cycles with embedded training requirements.
- Construction:Surveying and progress monitoring applications drive enterprise hardware adoption. Japanese infrastructure inspectors favor bundled hardware-software-service contracts with regulatory compliance support.
- Filmmaking:Creative professionals prioritize gimbal stability and camera payload flexibility. Demand clusters in Los Angeles, Mumbai, and London production hubs with direct-to-operator manufacturer relationships.
Agriculture commands the established base. The steepest expansion runs through construction as infrastructure inspection digitization accelerates.
Application:
Volume concentration varies sharply between mature aerial photography segments and emerging logistics trials where regulatory permission precedes technology readiness.
- Surveillance:Persistent monitoring applications span border security, facility protection, and event management. Defense contractors and first-response agencies drive premium-tier procurement for fully autonomous reliability.
- Delivery:Last-mile logistics trials operate within China's CAAC-designated low-altitude corridors and select FAA BVLOS waiver zones. Payload-distance economics remain constrained by battery energy density limits.
- Mapping:Photogrammetry and LiDAR-based survey applications serve construction, mining, and environmental monitoring. French and German agricultural fleets consolidate multi-country contracts under unified EASA compliance architectures.
- Search & Rescue:Thermal-equipped platforms extend operational reach for emergency responders. Alpine rescue coordination in Switzerland and Austria tests computer vision-based navigation in GPS-denied environments.
Mapping commands the established base. The steepest expansion runs through delivery as airspace corridor designations proliferate.
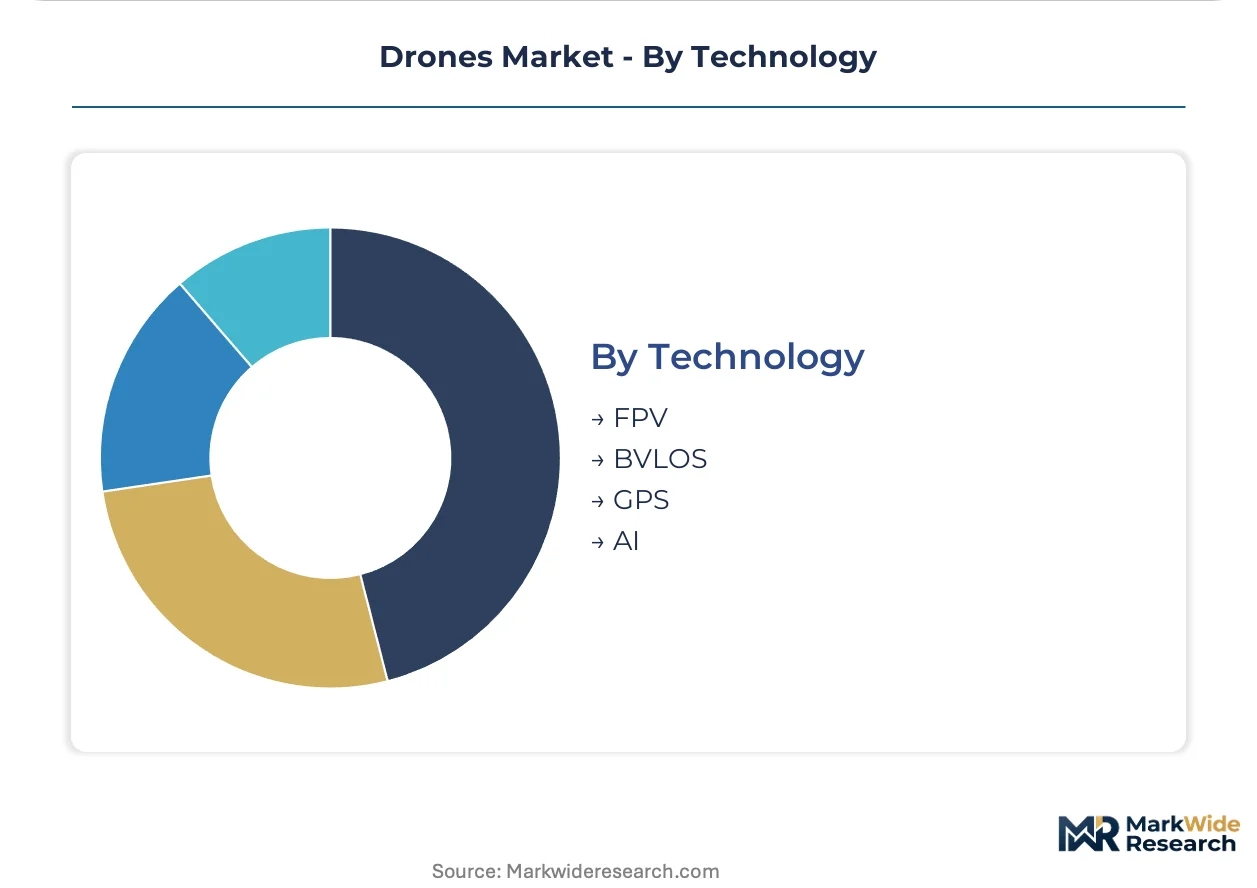
Technology:
Customer-type segmentation separates hobbyist FPV pilots from enterprise buyers requiring certified autonomous systems, with GPS serving as the universal positioning layer.
- FPV:First-person video piloting through immersive goggles dominates racing and recreational segments. Consumer-tier manufacturing concentrates in Shenzhen with component ecosystem integration.
- BVLOS:Beyond-visual-line-of-sight operation requires regulatory waiver or certified autopilot systems. ANVISA frameworks in Brazil and CAAC corridors in China create divergent compliance paths for agricultural and logistics operators.
- GPS:Satellite positioning underlies navigation for virtually all commercial and consumer platforms. Signal augmentation and redundancy features differentiate premium enterprise tiers.
- AI:Computer vision and autonomous decision-making compress pilot dependency for defense and public safety applications. Obstacle avoidance accuracy commands procurement premiums where zero-intervention reliability is mandatory.
GPS commands the established base. The steepest expansion runs through AI as autonomous navigation displaces pilot-dependent hardware in mission-critical deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Shenzhen's component corridors exceeds margin capture in São Paulo's agricultural deployment zones by substantial multiples. Brazil's fleet operators absorb higher unit costs due to import duties and ANVISA compliance overhead, while Guangdong manufacturers retain upstream value through captive chip and gimbal production.
United States
Defense and public safety agencies drive procurement for autonomous navigation platforms with zero-intervention reliability requirements. The FAA's Part 107 framework and evolving BVLOS waiver processes compress commercial deployment timelines relative to test environment progress. Los Angeles production hubs anchor demand for cinematography-grade gimbal stability and camera payload flexibility.
China
Domestic delivery pilot programs and enterprise hardware volumes concentrate demand across consumer and industrial tiers. The CAAC coordinates with MIIT on low-altitude economy zones, creating designated airspace corridors that accelerate logistics trials. Guangdong's manufacturing corridor feeds assembly lines with integrated component ecosystems for both domestic consumption and export channels.
Brazil
Soybean and sugarcane belt operators scale precision agriculture fleets under ANVISA-coordinated BVLOS waivers. ANVISA frameworks enable beyond-visual-line-of-sight operations that unlock commercial-scale agricultural monitoring. São Paulo-based fleet operators consolidate multi-state contracts under unified compliance architectures.
Germany
Industrial inspection and infrastructure monitoring verticals favor bundled hardware-software-service contracts with embedded regulatory compliance support. EASA's EU 2019/947 framework standardizes operational categories, enabling simplified cross-border service deployment. Bavarian precision engineering clusters anchor limited production runs for specialized heavy-lift helicopter-style platforms.
Switzerland
Alpine rescue coordination tests computer vision-based navigation in GPS-denied environments for emergency response applications. Swissmedic-aligned procurement standards shape equipment specifications for medical delivery trials. Zurich and Geneva anchor thermal-equipped platform development for search and rescue operational reach extension.
Drones Market Key Industry Players
Concentration sits with vertically integrated manufacturers controlling in-house chip design and gimbal production. The vendor base spans defense contractors, consumer electronics specialists, and precision engineering clusters with divergent capability investments. Three archetypes dominate: scale-driven platform assemblers, autonomous navigation software specialists, and precision hardware fabricators. M&A activity targets sensor fusion capabilities, while geographic expansion focuses on regulatory waiver zones.
Within the autonomous navigation tier, Skydio exemplifies obstacle avoidance accuracy commanding premium positioning in defense and public safety contracts. DJI anchors the scale-driven end through Shenzhen-based vertical integration across consumer and enterprise tiers. AeroVironment occupies a position among defense contractors accelerating procurement cycles for fully autonomous systems.
| Leading Market Players |
|---|
| DJI |
| Skydio |
| Autel Robotics |
| Parrot |
| AeroVironment |
| Yuneec |
| General Atomics Aeronautical Systems |
| Northrop Grumman Corporation |
| Freefly Systems |
| Others |
Cost & Logistics Intelligence
Lithium-polymer cell chemistry substitution for solid-state alternatives is compressing unit economics while simultaneously redrawing manufacturing geography toward South Korean and Japanese battery specialists, forcing Guangdong assemblers to absorb margin compression or cede pricing control to upstream cell suppliers.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise platforms with embedded BVLOS certification support from standard multi-rotor units sold through direct channels. Pricing stratifies across premium, standard, and economy tiers based on sensor integration density and FAA/EASA compliance grade. Cost compression in the standard tier is intensifying because Shenzhen-based manufacturers are flooding export channels with undifferentiated camera drones. Agricultural fleet operators in Brazil exhibit the lowest price sensitivity due to ANVISA compliance overhead and import duty absorption, while creative professionals in Los Angeles and Mumbai demand manufacturer-direct relationships but negotiate aggressively on volume.
Supply Chain Analysis
Container availability fluctuations on the Shenzhen-Los Angeles trade lane are elevating inbound logistics costs for North American distributors just as demand concentrates in Guangdong's component corridors. Manufacturing draws from China for lithium-polymer cells and gimbal motors, Taiwan for flight control chipsets, and Japan for precision optical sensors. Single-source vulnerability sits with MIIT-coordinated rare earth magnet supply for motor assemblies. Distribution runs through manufacturer-direct channels for enterprise tiers and aerospace distributors for defense contracts, with traditional retail collapsing for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins are flattening while recurring revenue from embedded training, certification renewal, and fleet management software expands faster than unit sales, repositioning the market as a service-attach opportunity where platform providers capture lifetime value through operator enablement layers.
For Market Incumbents: Fortify control over flight control firmware and computer vision engineering talent against automotive autonomy poaching by expanding captive R&D centers in German and Swiss precision engineering clusters. Deepen backward integration into in-house gimbal production and chip design to defend margin position against Shenzhen-based cost competitors. Lock in ANVISA and EASA certification pipelines as competitive moats that delay entrant timelines by 18-24 months. For New Entrants and Emerging Players: EASA's EU 2019/947 fast-track for specific category operations offers regulatory arbitrage against FAA Part 107 friction, enabling cross-border service deployment from German industrial inspection bases. Target Swiss alpine rescue and medical delivery trials where Swissmedic-aligned procurement standards favor specialized thermal-equipped platforms over commodity hardware. Pursue direct-to-operator distribution with embedded training and certification support to bypass entrenched aerospace channel relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors autonomous navigation software specialists over hardware assemblers, with computer vision capabilities commanding acquisition premiums. Long-term viability hinges on regulatory waiver zone positioning and defense contract visibility rather than consumer volume scale. Watch FAA BVLOS waiver approval velocity as the inflection signal separating scalable logistics operators from perpetual pilot-dependent service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Navigation Software Acquisition | Computer vision engineering teams in Boston and Zurich command premium valuations from defense contractors accelerating procurement cycles. |
| BVLOS Certification Fast-Track Investment | ANVISA-coordinated waiver pipelines in Brazil unlock agricultural fleet scaling before FAA timelines compress US commercial deployment. |
| Low-Altitude Economy Zone Partnership | CAAC-designated corridors in Guangdong accelerate logistics trials while creating captive demand for hybrid VTOL platforms. |
| Sensor Fusion Capability Buildout | Multi-spectral imaging integration opens precision agriculture white space where Brazilian soybean operators consolidate multi-state contracts. |
| Direct-to-Operator Channel Expansion | Manufacturer-direct relationships with embedded training displace traditional aerospace distributors in German infrastructure inspection verticals. |
Research Approach
Desk research of FAA waiver filings, EASA regulatory submissions, CAAC corridor designations, and component trade flow databases preceded structured interviews with fleet operations directors at Brazilian agricultural contractors, German industrial inspection service providers, and Chinese low-altitude economy zone administrators. Primary fieldwork with defense procurement officers and public safety agency equipment managers combined with secondary validation from customs records and aviation regulator disclosure documents. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across platform architecture tiers.
Variance decomposition across product type, end user segment, application purpose, and technology layer shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory milestone timing. Modeled inputs included battery energy density improvement curves, BVLOS waiver approval velocity assumptions, and low-altitude economy zone expansion schedules.
Underlying assumptions cover sustained lithium-polymer cost trajectories and permissive regulatory evolution in test zones, with deviation risk concentrated in FAA Part 107 waiver friction and Guangdong supply concentration vulnerability. Forecasts reflect these conditions without contingency for abrupt tariff regime shifts or solid-state battery breakthrough timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
North America Tactical UAV Market
UAV
Fuel Cell UAV Market
UAV
North America Fuel Cell UAV Market
UAV
Asia Pacific Small UAV Market
UAV
Inspection Drones in Confined Space Market
UAV
Miniature Drone Market
UAV
Firefighting Drone Market
UAV
Global Smart Commercial Drones Market
UAV
Tethered Drones Market
UAV
Solar Powered Drones Market
UAV
UAV Navigation Systems Market
UAV
UAV Simulator Market
UAV
Home Security Drone Market
UAV
Micro Drone Market
UAV
Multirotor Drones Market
UAV
Global Drone Data Services Market