
 Airborne Digital Battlefield Market | 2026-2036
Airborne Digital Battlefield Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne Digital Battlefield Market Insights
Platform bundling is consolidating as prime contractors integrate sensor fusion, edge computing, and cybersecurity modules into single-source aerial system contracts rather than discrete component sales. Lockheed Martin leverages its Skunk Works division to sustain classified development pipelines for next-generation manned-unmanned teaming architectures. BAE Systems anchors European supply chains through its UK-based electronic systems division, competing for NATO interoperability mandates. Elbit Systems differentiates via vertical integration into helmet-mounted displays and tactical datalinks, extending its reach across allied defense procurement networks.
The airborne digital battlefield comprises networked aerial platforms, ground stations, and software-defined mission systems that process multi-spectral sensor data at the tactical edge with sub-second latency for decision advantage. These systems employ open architecture standards, artificial intelligence-enabled target recognition algorithms, and encrypted waveform protocols to fuse intelligence across distributed nodes for precision engagement and electronic attack missions. Sensor fusion technology leads platform investment as militaries prioritize passive-active sensor pairing for contested electromagnetic environments, while unmanned aerial vehicles represent the fastest-expanding platform category as attritable systems replace manned assets in high-risk reconnaissance roles. Edge computing architectures concentrate margin pools at the subsystem level, where ruggedized processing units must survive jamming, thermal stress, and kinetic threat proximity.
The US Department of Defense's JADC2 framework and the Federal Aviation Administration's special airworthiness certifications shape platform development timelines and airspace integration pathways for military contractors. European alignment with NATO's Digital Transformation Strategy and the EU's Permanent Structured Cooperation (PESCO) defense initiatives create dual compliance obligations for transatlantic suppliers seeking cross-border operational certification. Stakeholders must monitor how export control revisions under the US International Traffic in Arms Regulations and emerging EU defense procurement autonomy measures reshape supplier eligibility and technology transfer boundaries for allied program participation.
Market Dynamics
The US Department of Defense's Joint All-Domain Command and Control architecture is forcing prime contractors to reengineer platform interoperability, compressing development cycles and privileging vendors with existing classified clearances and multi-domain integration experience.
Growth Catalysts
- JADC2 Mandates:Pentagon directives require seamless data fusion across air, space, and cyber domains, pulling investment toward software-defined mission systems with open architecture standards.
- Sensor Fusion Technology:Passive-active sensor pairing for contested electromagnetic environments is displacing standalone electro-optical systems in NATO procurement specifications.
- Indo-Pacific Theater Demand:US Pacific Command operational requirements for distributed maritime surveillance are accelerating attritable unmanned aerial vehicle procurement timelines.
Market Restraints
- Semiconductor Supply Concentration:Advanced gallium nitride and silicon carbide substrates for radar systems concentrate in East Asian foundries, exposing prime contractors to export control friction.
- ITAR Compliance Burden:US International Traffic in Arms Regulations create structural barriers for European and Israeli subsystem suppliers seeking direct NATO program participation.
- Thermal Management Limitations:Ruggedized edge computing units face fundamental physics constraints on processing density in jamming-proximate environments.
Strategic Opportunities
- Estonian and Polish Procurement:NATO's eastern flank members are expanding national drone programs with limited domestic industrial bases, creating white space for integrated system providers.
- Manned-Unmanned Teaming:Convergence of autonomous swarming algorithms with fifth-generation fighter architectures opens new contract categories for human-machine interface specialists.
- EU Defense Fund Alignment:Permanent Structured Cooperation initiatives are channeling pooled procurement toward cross-border electronic warfare standardization, rewarding vendors with multi-national certification.
Industry Challenges
- Cleared Workforce Scarcity:Polygraph-cleared software engineers with embedded systems expertise remain concentrated at legacy primes, constraining mid-tier vendor scaling.
- Airworthiness Certification Compression:FAA special military experimental certifications and DoD rapid fielding pathways create conflicting timeline pressures for platform developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne Digital Battlefield Market |
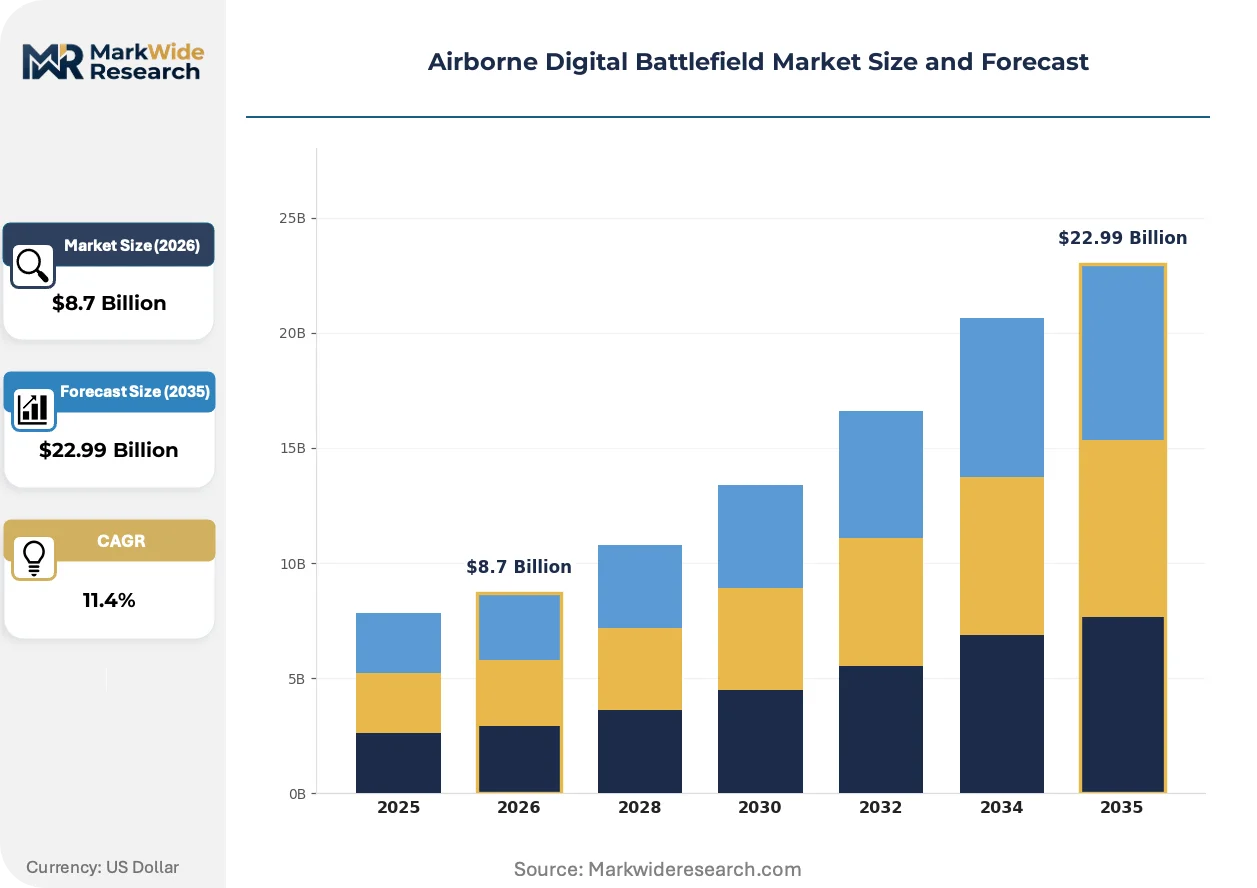
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Artificial Intelligence, Machine Learning, Edge Computing, Sensor Fusion, Augmented Reality, Cybersecurity Platform Type: Unmanned Aerial Vehicles, Manned Aircraft, Satellites, Aerostats, Balloons, High-Altitude Platforms Application: Real-Time Surveillance, Target Acquisition, Electronic Warfare, Command & Control, Communication Relay, Reconnaissance End User: Defense Forces, Intelligence Agencies, Special Operations, Security Contractors, Tactical Units, Strategic Commands |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, Raytheon Technologies Corporation, BAE Systems, Thales Group, L3Harris Technologies, General Dynamics Corporation, Elbit Systems Ltd., Israel Aerospace Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne Digital Battlefield Market Trends and Innovations
Artificial intelligence-enabled target recognition is compressing sensor-to-shooter timelines, while open systems architectures are dismantling proprietary vendor lock-in that dominated prior-generation programs.
Software-defined radio waveforms with cognitive jamming resistance are converging with solid-state active electronically scanned array hardware. US Navy and Air Force programs are fielding these combined systems on carrier-based and land-based unmanned platforms. This convergence is collapsing the traditional separation between communications, electronic attack, and radar functions into unified aperture management.
The EU AI Act's risk classification framework for autonomous targeting systems is reshaping development roadmaps for European suppliers. Military applications fall under high-risk categories requiring human oversight documentation and algorithmic transparency. French and German prime contractors are restructuring AI development pipelines to pre-empt compliance costs before NATO interoperability mandates harden.
Allied defense ministries are unbundling platform procurement from through-life support contracts, fragmenting historical sole-source arrangements. Danish and Norwegian armed forces now separate hardware acquisition from predictive maintenance software licenses. This pattern is most visible in Nordic procurement, where national sovereignty concerns over data residency accelerate domestic cloud infrastructure investment for mission system analytics.
Airborne Digital Battlefield Market Segmentation
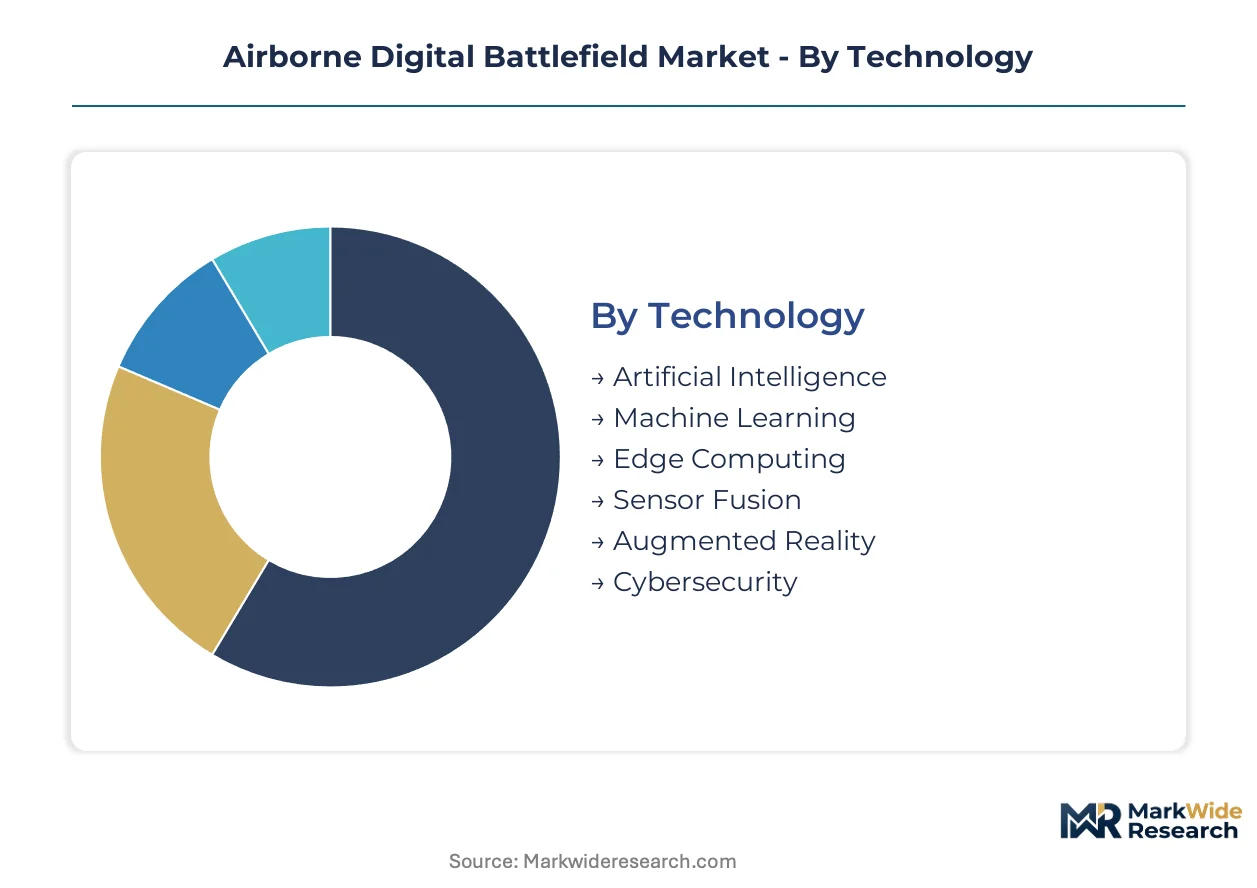
Segmentation in the airborne digital battlefield market reveals how technology investment, platform procurement, and mission requirements intersect across defense procurement hierarchies. Procurement officers weight platform survivability against software upgradeability when allocating modernization budgets across competing mission sets.
Technology:
Volume concentrates in processing hardware, while premium margins accrue to software-defined layers that enable post-deployment capability expansion.
- Artificial Intelligence:Algorithms for autonomous target recognition and threat prioritization process multi-spectral sensor feeds at tactical edge nodes. US Indo-Pacific Command operational requirements are accelerating procurement of AI-enabled decision-support tools for distributed maritime surveillance architectures.
- Machine Learning:Adaptive pattern recognition systems refine electronic warfare countermeasures through mission data feedback loops. NATO electronic warfare standardization mandates under Permanent Structured Cooperation are channeling investment toward interoperable ML training pipelines.
- Edge Computing:Ruggedized processing units with jamming-resistant thermal management.
- Sensor Fusion:Passive-active sensor pairing for contested electromagnetic environments.
- Augmented Reality:Helmet-mounted displays for pilot and operator situational awareness.
- Cybersecurity:Encrypted waveform protocols and zero-trust architecture for networked platforms.
Today's leader: Sensor Fusion. Tomorrow's challenger: Artificial Intelligence.
Platform Type:
Application drives the attritable-versus-survivable trade-off, with mission risk profiles determining procurement volume across platform categories.
- Unmanned Aerial Vehicles:Attritable systems with modular payload bays for reconnaissance and electronic attack missions in denied airspace. US Pacific Command urgent operational needs are compressing procurement timelines for attritable UAV swarms.
- Manned Aircraft:Fifth-generation fighter and command platform architectures with manned-unmanned teaming interfaces. Pentagon JADC2 interoperability mandates are forcing sensor and datalink standardization across legacy and next-generation manned fleets.
- Satellites:Low-earth orbit constellations for beyond-line-of-sight communications and missile warning.
- Aerostats:Persistent surveillance platforms for border and maritime domain awareness.
- Balloons:Stratospheric platforms for communications relay and wide-area sensing.
- High-Altitude Platforms:Long-endurance systems bridging satellite and tactical aircraft capabilities.
Volume dominance: Unmanned Aerial Vehicles. Capability premium: Manned Aircraft.
Application:
Customer mission profiles split between intelligence-driven analysis and kinetic engagement timelines, reshaping procurement priority across application categories.
- Real-Time Surveillance:Multi-spectral persistent stare capabilities with sub-second latency for threat detection. Estonian and Polish national drone programs are expanding procurement of integrated surveillance packages with limited domestic industrial bases.
- Electronic Warfare:Cognitive jamming resistance and electronic attack functions unified through software-defined aperture management. EU defense procurement autonomy measures are creating compliance obligations for cross-border electronic warfare standardization.
- Target Acquisition:AI-enabled sensor-to-shooter linkages for precision engagement.
- Command & Control:Distributed decision nodes for Joint All-Domain Command and Control architectures.
- Communication Relay:Beyond-line-of-sight datalink extension for contested environments.
- Reconnaissance:Strategic and tactical intelligence collection with multi-int fusion.
Procurement intensity: Real-Time Surveillance. Fastest capability evolution: Electronic Warfare.
End User:
Security clearance levels and operational tempo separate high-volume tactical procurement from premium strategic system development.
- Defense Forces:Conventional military services with platform-centric procurement hierarchies and through-life support requirements. Danish and Norwegian armed forces are unbundling hardware acquisition from predictive maintenance software licenses, fragmenting historical sole-source arrangements.
- Intelligence Agencies:National technical means with classified development pipelines and specialized human-machine interface requirements. Cleared workforce scarcity at legacy primes constrains mid-tier vendor scaling for intelligence community programs.
- Special Operations:Low-signature, rapidly deployable systems for direct action and special reconnaissance.
- Security Contractors:Private sector providers for site protection and convoy security missions.
- Tactical Units:Battalion-and-below formations with handheld and organic aerial systems.
- Strategic Commands:Theater-level coordination nodes for nuclear and conventional deterrence operations.
Contract volume leader: Defense Forces. Technology access premium: Intelligence Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The airborne digital battlefield industry traces its modern lineage to post-Cold War US defense modernization programs, with subsequent scaling through NATO interoperability mandates and Indo-Pacific theater operational requirements. European and Israeli industrial bases developed parallel capabilities through national security investments and technology transfer frameworks. Today's geographic distribution reflects concentrated defense procurement hierarchies, classified development pipelines, and regional alliance structures.
United States
Pentagon JADC2 architecture investments and Pacific Command urgent operational needs drive procurement of networked aerial platforms with edge computing capabilities. The FAA's special military experimental certifications and DoD rapid fielding pathways create dual compliance obligations for domestic contractors. The Greater Washington DC corridor hosts prime contractor headquarters and classified development facilities, while California's aerospace clusters concentrate unmanned systems engineering talent.
Israel
Regional security imperatives and conscription-sustained technical workforce depth sustain autonomous systems and electronic warfare specialization. The Israeli Ministry of Defense's Directorate of Defense Research and Development channels procurement toward dual-use technologies with export potential. Haifa and Tel Aviv metropolitan areas anchor defense electronics manufacturing and AI-enabled targeting algorithm development.
United Kingdom
NATO interoperability mandates and national carrier strike group modernization requirements prioritize sensor fusion and manned-unmanned teaming architectures. The UK Ministry of Defence's Defence and Security Industrial Strategy emphasizes sovereign capability in electronic systems and cyber-physical security. Lancashire and Bristol aerospace clusters concentrate BAE Systems production and supply chain integration activities.
Germany
EU Permanent Structured Cooperation initiatives and Franco-German defense industrial consolidation reshape procurement toward cross-border electronic warfare standardization. The Federal Office of Bundeswehr Equipment, Information Technology and In-Service Support manages platform acquisition with dual-use technology screening requirements. Bavaria's Munich-Stuttgart corridor hosts subsystem suppliers and AI development centers for mission system analytics.
France
Independent nuclear deterrence architecture and carrier aviation requirements sustain sovereign platform development alongside NATO alliance obligations. The EU AI Act's high-risk classification framework for autonomous targeting systems imposes human oversight documentation requirements on prime contractors. The Île-de-France region concentrates Thales Group headquarters and defense electronics research facilities.
Airborne Digital Battlefield Market Competitive Landscape
Premium-margin players sit above commodity-margin players across classified program access and multi-domain integration experience. The vendor base stratifies between legacy primes with polygraph-cleared workforces and mid-tier specialists seeking NATO interoperability certification. Three archetypes dominate: full-system integrators with classified development pipelines, subsystem specialists in sensor fusion and electronic warfare, and autonomous systems developers with attritable platform expertise. Competitive moves concentrate on strategic partnerships for JADC2 compliance and capacity expansion in eastern European NATO member states.
Within the full-system integrator tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify prime contractor positioning through classified development pipelines and multi-domain architecture experience. Raytheon Technologies Corporation occupies a comparable position among diversified defense conglomerates with sensor and effects integration capabilities. BAE Systems represents the European anchor with UK-based electronic systems division and NATO interoperability mandates. These entities sit within a structure where cleared workforce concentration and existing alliance relationships create structural barriers for mid-tier scaling.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Raytheon Technologies Corporation |
| BAE Systems |
| Thales Group |
| L3Harris Technologies |
| General Dynamics Corporation |
| Elbit Systems Ltd. |
| Israel Aerospace Industries |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride and silicon carbide substrate costs cascade from East Asian foundries through prime contractor margins into fixed-price platform contracts, compressing returns on sensor fusion subsystems while elevating premium pricing for ITAR-compliant domestic sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by security clearance requirements and integration complexity. Premium tiers command substantial markups for polygraph-cleared engineering teams and JADC2-certified architectures, while standard tiers serve NATO interoperability mandates with moderate customization. Price differentiation hinges on ITAR compliance certification and volume procurement scale. Cost compression in standard-tier edge computing units is intensifying because thermal management physics constraints limit processing density gains. Intelligence agencies exhibit the lowest price sensitivity due to classified program budgets, whereas eastern European NATO members face acute budgetary pressure.
Supply Chain Analysis
Freight costs for ruggedized processing units from California aerospace clusters to European integration facilities have risen substantially, amplifying landed cost differentials against domestic European sourcing. Semiconductor feedstock draws from Taiwan, South Korea, and Japan for advanced radar substrates, while final assembly concentrates in the United States and United Kingdom. Gallium nitride wafers, silicon carbide substrates, and encrypted waveform chipsets anchor component dependencies. Single-source vulnerability in East Asian foundry capacity exposes prime contractors to export control friction under ITAR and emerging EU defense procurement autonomy measures. Distribution runs through classified prime contractor channels for integrated systems, with subsystem specialists selling direct to platform integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in software-defined mission systems where post-deployment upgrade cycles generate recurring revenue, offsetting hardware commoditization pressure from attritable UAV proliferation.
For Market Incumbents: Extend classified development pipeline capacity to pre-empt mid-tier vendor scaling in manned-unmanned teaming architectures. Acquire or partner with Estonian and Polish subsystem suppliers to secure eastern European NATO procurement access before PESCO standardization hardens. ITAR compliance burden creates structural barriers that favor cleared workforce concentration at legacy primes. For New Entrants and Emerging Players: Capture white space in Nordic predictive maintenance software licensing where Danish and Norwegian armed forces unbundle hardware from analytics services. Target attritable UAV swarm integration for US Pacific Command urgent operational needs, where procurement timeline compression privileges agile developers. Pursue NATO interoperability certification as the primary go-to-market credential. For Investors and Strategic Acquirers: Consolidation pressure builds where cleared workforce scarcity constrains mid-tier scaling for intelligence community programs. Long-term viability favors subsystem specialists with sensor fusion expertise and multi-national certification rather than pure-play hardware manufacturers. Monitor EU AI Act high-risk classification enforcement as the signal to watch for algorithmic transparency compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| JADC2 Architecture Certification | Platform interoperability mandates under Pentagon directives create vendor lock-in for certified primes. |
| Eastern European Capacity Expansion | Estonian and Polish national drone programs offer first-mover positioning before PESCO standardization. |
| AI-Enabled Targeting Partnership | EU AI Act compliance requirements favor vendors with pre-positioned human oversight documentation. |
| Sensor Fusion Specialist Acquisition | Passive-active sensor pairing expertise concentrates margin pools at subsystem level. |
| Predictive Maintenance Software Licensing | Nordic procurement unbundling fragments historical sole-source arrangements into recurring revenue streams. |
Research Methodology
Bottom-up defense procurement modeling reconciled against top-down prime contractor revenue tracking forms the analytical core of this study. Primary interviews with platform program managers, electronic warfare subsystem engineers, NATO procurement officers, and cleared software developers were validated against secondary sources including Pentagon budget justification documents, FAA special airworthiness certification records, EU defense procurement autonomy regulatory filings, and NATO Digital Transformation Strategy implementation reports. Triangulation between demand-side operational requirements and supply-side production capacity ensures segmentation integrity.
Historical trendline analysis of defense modernization budget allocations and platform procurement cycles established baseline growth patterns across the projection horizon. Segmentation modeling incorporated technology layer, platform type, application mission set, and end-user security clearance tier as structural dimensions. CAGRs were derived from weighted scenario analysis of JADC2 implementation pace, Indo-Pacific theater operational tempo, and EU defense fund disbursement timelines. Forecast inputs included Pentagon rapid fielding pathway utilization rates and NATO eastern flank member state procurement acceleration indicators.
Export control revision triggers, semiconductor supply disruption events, and thermal management technology breakthroughs are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context and cleared workforce access constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Small Drone Market
UAV
Drone Data Management Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Multirotor Drones Market
UAV
Drone Camera Market
UAV
Firefighting Drone Market
UAV
Commercial UAV Market
UAV
UAV Sense-And-Avoid Systems Market
UAV
FPV Drone Goggles Market
UAV
Global Drone Data Services Market
UAV
North America Drones Market
UAV
Drone Lens Market
UAV
Drones Market
UAV
Global Drone Sensor Market
UAV
Drone Payload Market
UAV
Rotary Blade UAV Drones Market