
 Drone Leasing Market | 2026-2036
Drone Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Leasing Market Insights
Enterprise infrastructure teams and agricultural cooperatives are reorganizing procurement patterns away from direct ownership toward operational leasing models. DJI Innovations leverages its manufacturing scale to anchor supply agreements with lessors across North America and Asia. Parrot competes through specialized fixed-wing platforms optimized for long-duration mapping missions. Skydio differentiates via autonomous navigation stacks that reduce pilot dependency and insurance exposure for fleet operators.
Drone leasing denotes the contractual provision of unmanned aerial vehicle systems—typically encompassing airframes with payload capacities from 0.5 kg to 25 kg, flight controllers, telemetry links, and maintenance coverage—for defined operational periods rather than asset transfer. This arrangement enables operators to access rotating sensor packages, comply with evolving airworthiness directives, and avoid technology obsolescence cycles without capital deployment. Multi-rotor configurations dominate current leasing volumes due to versatility across inspection and cinematography applications, while fixed-wing platforms command premium terms for precision agriculture and corridor mapping where endurance exceeds 45 minutes. Fractional leasing structures are expanding fastest among mid-sized construction firms seeking intermittent access to thermal and LiDAR payloads without full fleet commitment.
FAA Part 107 mandates and EASA's specific category operational authorizations shape lessor liability frameworks and pilot qualification requirements across the United States and European Union. China's CAAC drone registration tiers and flight zone restrictions influence fleet deployment densities and cross-border leasing contract structures. India's DGCA UAS Rules and emerging PLI scheme incentives for domestic manufacturing are redirecting lessor partnership strategies toward local assembly requirements. Stakeholders must monitor how regulatory divergence in remote identification and beyond-visual-line-of-sight permissions reshapes cross-jurisdictional fleet utilization economics and insurance underwriting models.
Market Dynamics
Capital-light access models are compressing traditional equipment finance cycles as precision agriculture operators and infrastructure inspection teams prioritize operational flexibility over asset ownership in volatile technology refresh environments.
Growth Catalysts
- Beyond-Visual-Line-of-Sight waivers:FAA Part 107 exemptions for corridor mapping and linear infrastructure inspection are expanding addressable mission profiles for leased multi-rotor fleets without pilot co-location requirements.
- Precision agriculture yield optimization:Variable-rate input application and crop health monitoring via normalized difference vegetation index sensors are converting row-crop cooperatives from seasonal purchase to annual lease structures.
- EU drone operation frameworks:EASA's specific category operational authorizations are standardizing cross-border fleet deployment protocols, reducing insurance friction for lessors operating across Germany, France, and the Netherlands.
Market Restraints
- Lithium-polymer battery supply concentration:Cell manufacturing dominance in China creates input cost volatility and extended lead times for fleet refresh cycles in North American and European lessor portfolios.
- Remote ID mandate compliance:FAA broadcast requirements and EASA equivalent technical specifications impose retrofit costs on legacy airframes that compress lessor residual value assumptions.
- Pilot certification bottlenecks:FAA Part 107 practical examination availability constraints and EASA theoretical knowledge validation timelines extend crew qualification lead times beyond typical lease activation windows.
Strategic Opportunities
- India's PLI scheme for domestic manufacturing:Production-linked incentives for unmanned aerial vehicle assembly are attracting lessor joint ventures with local contract manufacturers to circumvent import duty structures.
- Thermal-LiDAR payload convergence:Integrated sensor packages combining radiometric thermal imaging with point cloud generation are opening municipal infrastructure digital twin contracts previously served by separate manned aviation and ground survey vendors.
- Fractional lease structures:Hourly-access models for cinematography and event coverage are penetrating mid-sized production houses in Germany and the United Kingdom that previously relied on freelance pilot networks.
Industry Challenges
- Autonomous navigation stack integration:Sensor fusion between visual-inertial odometry and GPS-denied positioning systems requires specialized firmware engineering talent that commands premium compensation in competitive labor markets.
- Cross-jurisdictional airworthiness certification:Divergent type approval requirements between FAA, EASA, and CAAC force lessors to maintain geographically segmented fleet configurations that complicate asset redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Leasing Market |
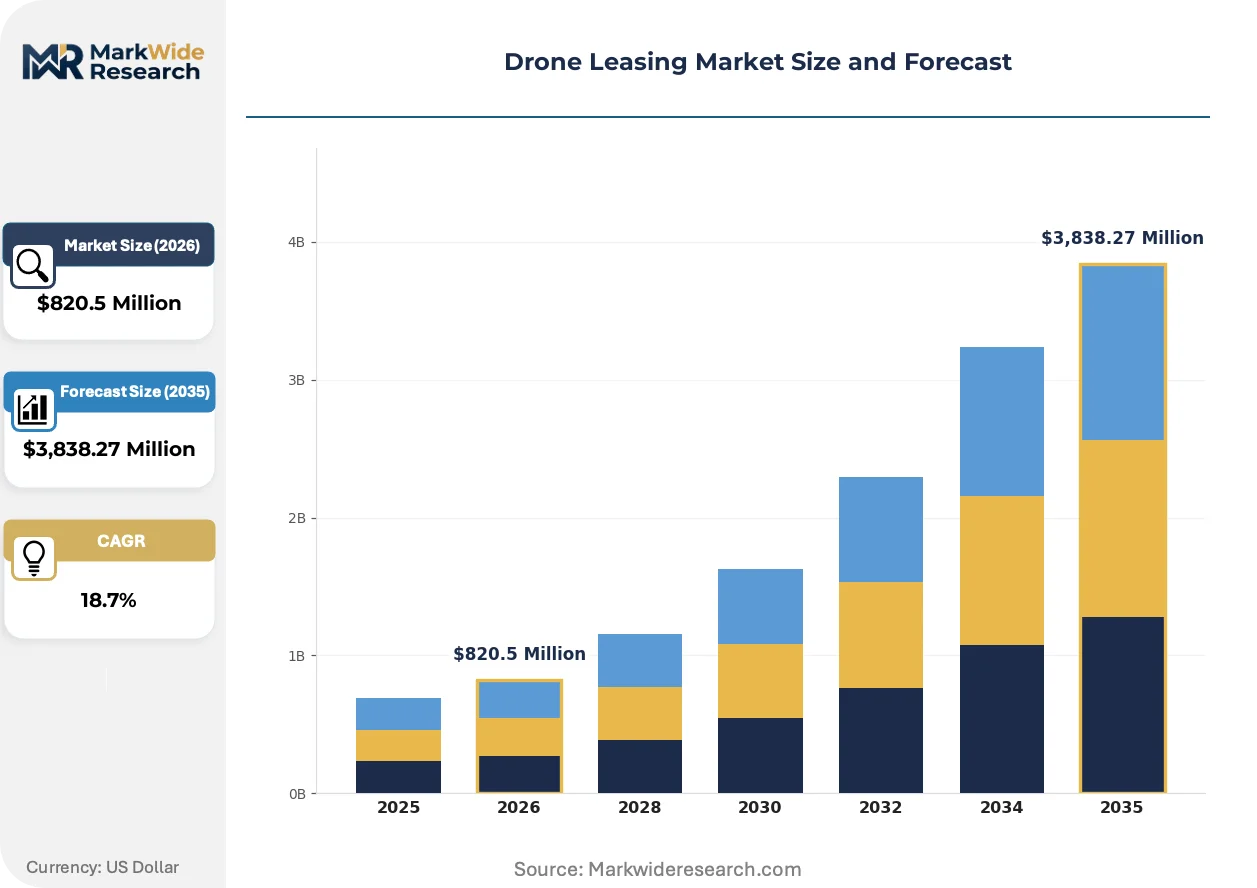
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $3,838.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing Drones, Multi-Rotor Drones, Hybrid Drones, Nano Drones End User: Agriculture, Construction, Entertainment, Surveillance Deployment Model: Private Leasing, Public Leasing, Fractional Leasing, On-Demand Leasing Application: Aerial Photography, Crop Monitoring, Delivery Services, Infrastructure Inspection |
| Companies Covered | Parrot, XAG, DJI Innovations, Yuneec, EHang, Skydio, JOUAV, Draganfly, Autel Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Leasing Market Trends and Innovations
Autonomous flight control architectures and modular payload interfaces are decoupling hardware from software value capture, enabling lessors to monetize sensor rotations and algorithm updates as recurring revenue streams distinct from airframe depreciation.
Edge-computing inference engines with onboard neural processing units are fragmenting traditional ground-station dependency for real-time object detection and collision avoidance. Agricultural cooperatives in the United States are deploying these systems for weed classification and livestock monitoring without continuous telemetry links. This capability compression is reducing insurance premiums for beyond-visual-line-of-sight operations and enabling lease structures with lower pilot-to-aircraft ratios.
EASA's drone regulation framework under Commission Delegated Regulation 2019/945 is harmonizing technical design standards across EU member states. The regulation mandates CE marking for unmanned aircraft systems above specific mass thresholds, creating compliance economies of scale for lessors with centralized maintenance operations. German and French infrastructure inspection contractors are consolidating vendor relationships toward CE-certified fleet providers to streamline cross-border project execution.
Usage-based contracting is displacing fixed-term lease arrangements in construction and energy verticals. Mid-sized engineering firms in Texas and California are negotiating flight-hour billing with embedded maintenance and payload swap entitlements rather than committing to 12-month minimums. This flexibility aligns cost structures with project-based revenue cycles and reduces idle fleet exposure during permitting delays or weather interruptions.
Drone Leasing Market Segmentation
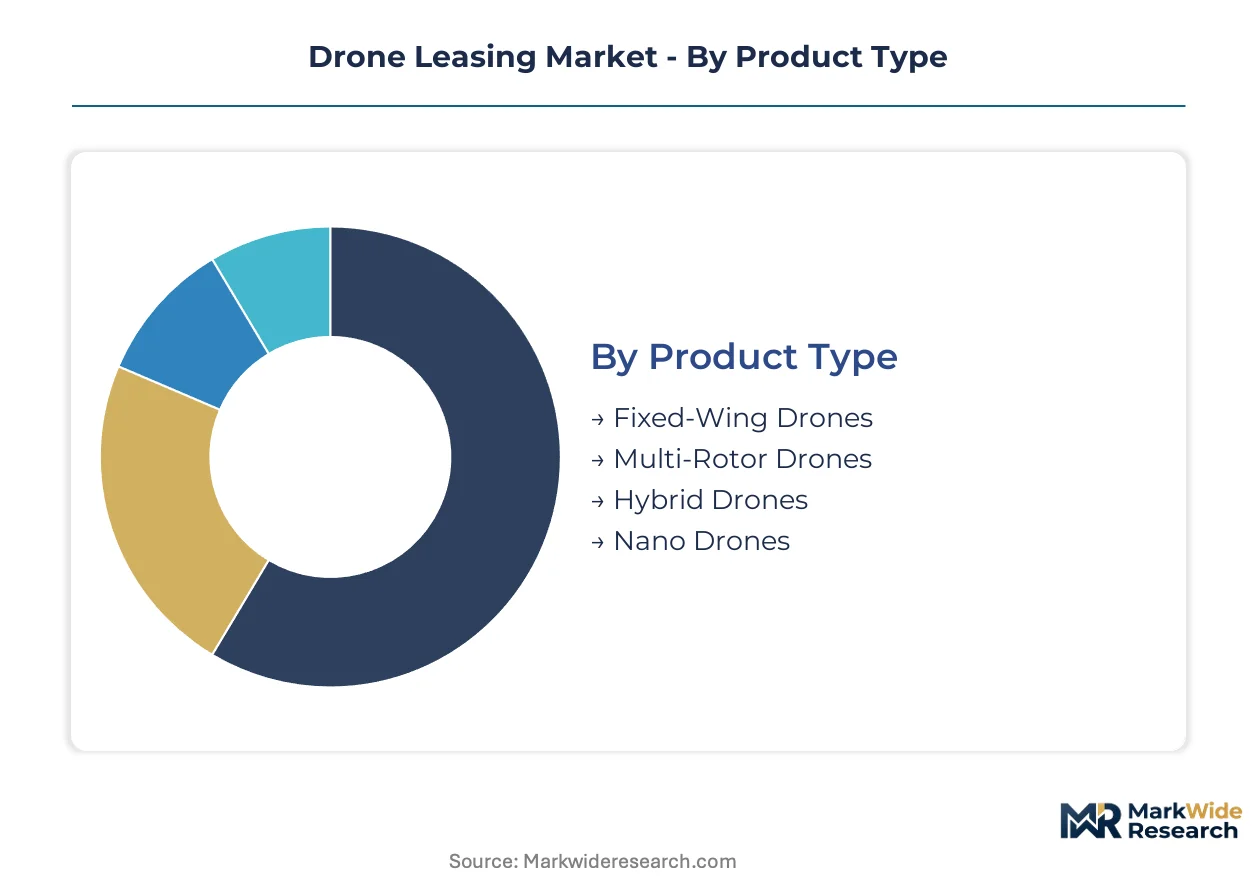
Leasing structures vary sharply by payload endurance, pilot certification requirements, and operational tempo. Regulatory frameworks from FAA, EASA, and CAAC impose divergent compliance burdens across product configurations and deployment models, fragmenting lessor portfolio strategies.
Product Type:
FAA Part 107 waivers and EASA specific-category operational authorizations apply differentially based on airframe mass, endurance thresholds, and kinetic energy classifications.
- Multi-Rotor Drones:Quad- and hexacopter configurations dominate current leasing volumes through versatility across vertical infrastructure inspection and cinematography missions. Demand concentrates among Texas and California construction contractors seeking intermittent access to thermal payloads without fleet ownership overhead. FAA Part 107 compliance costs remain lowest for sub-25 kg multi-rotor systems, accelerating lessor preference for this configuration in US portfolios.
- Fixed-Wing Drones:Aerodynamic efficiency enables endurance exceeding 45 minutes for corridor mapping and precision agriculture applications. German and French agricultural cooperatives are converting seasonal purchase commitments to annual lease structures for normalized difference vegetation index survey missions. EASA CE marking requirements for fixed-wing systems above specific mass thresholds create compliance economies that favor established European lessors with centralized maintenance operations.
- Hybrid Drones:Vertical takeoff and landing capability combined with fixed-wing cruise efficiency addresses payload-range tradeoffs for linear infrastructure inspection. China's CAAC registration tiers impose differentiated flight zone restrictions based on hybrid system mass categories.
- Nano Drones:Sub-250 gram systems operate under reduced regulatory burdens in most jurisdictions, attracting event coverage and indoor inspection lessors seeking minimal pilot certification overhead.
Established volume favors multi-rotor configurations; emerging adoption favors hybrid systems.
End User:
Customer procurement patterns reflect project-based revenue cycles and capital deployment constraints rather than continuous operational requirements.
- Agriculture:Row-crop cooperatives and specialty producers access variable-rate input application technologies through seasonal lease structures. United States Midwest operators prioritize NDVI sensor packages with embedded maintenance coverage to align costs with harvest cycles. India's DGCA UAS Rules and PLI scheme incentives are redirecting lessor partnerships toward domestic assembly for agricultural deployment.
- Infrastructure Inspection:Municipal engineering departments and energy utilities negotiate flight-hour billing with payload swap entitlements rather than fixed-term commitments. Texas and California mid-sized firms lead this shift toward usage-based contracting.
- Construction:Project developers seek intermittent thermal and LiDAR access for digital twin generation during permitting and pre-construction phases.
- Entertainment:German and United Kingdom production houses adopt fractional hourly-access models for cinematography, displacing freelance pilot networks.
Procurement concentration sits with agriculture; contract innovation runs through construction.
Deployment Model:
Capital intensity and asset utilization rates determine optimal lease structure selection across operator balance sheet profiles.
- Fractional Leasing:Hourly-access and seat-license structures enable mid-sized operators to rotate sensor packages without full fleet commitment. This model is gaining share fastest among European cinematography and event coverage providers seeking payload flexibility across project portfolios.
- Private Leasing:Dedicated fleet arrangements with embedded maintenance and pilot training serve enterprise infrastructure teams with predictable mission volumes. United States logistics operators favor this structure for beyond-visual-line-of-sight corridor mapping under FAA Part 107 waivers.
- On-Demand Leasing:Spot-market access platforms aggregate underutilized fleet capacity for emergency response and ad-hoc inspection missions.
- Public Leasing:Government fleet pools serve municipal and federal agencies with standardized procurement vehicles and consolidated insurance frameworks.
Margin compression threatens private leasing; flexibility premiums accrue to fractional structures.
Application:
Mission profile characteristics—flight duration, sensor payload, data processing requirements—determine airframe and lease term selection.
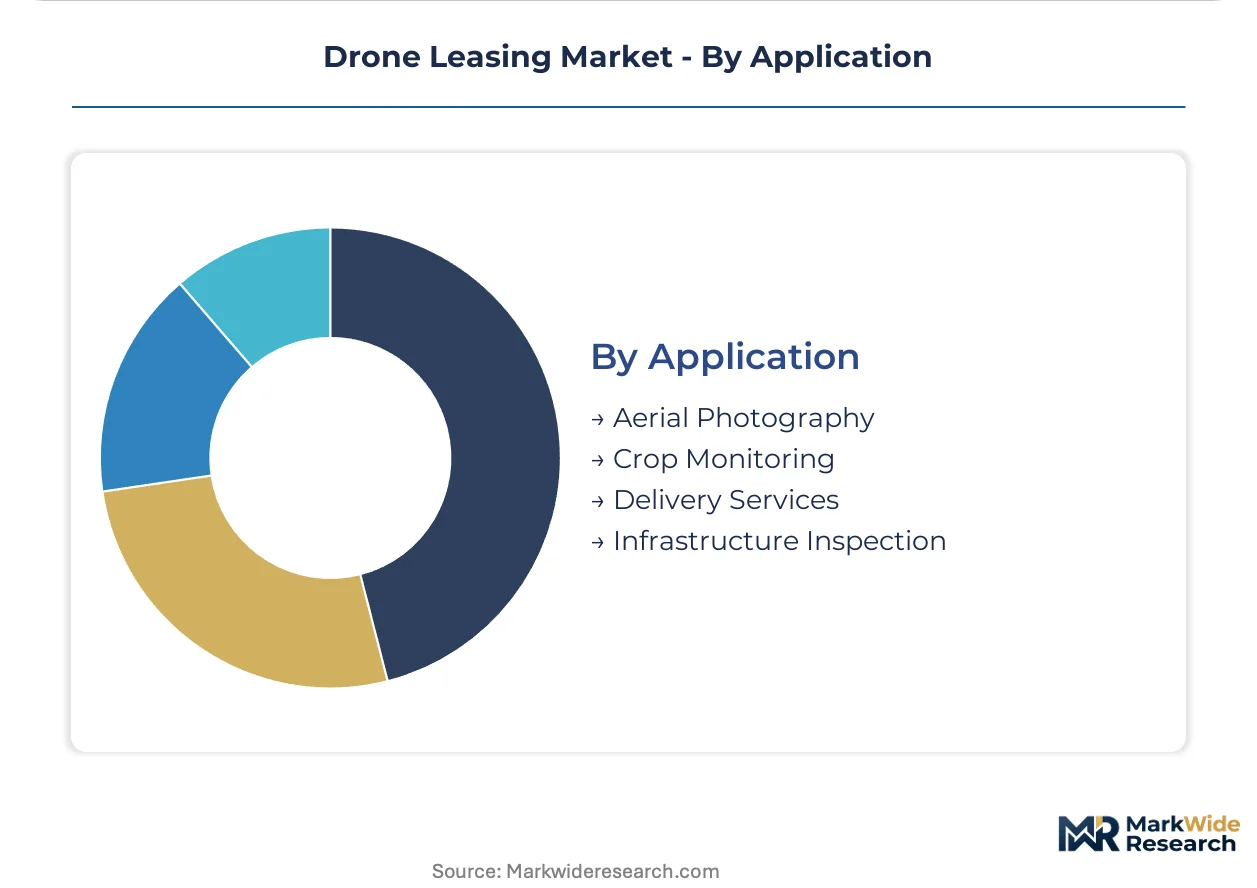
- Infrastructure Inspection:Bridge, pipeline, and transmission line assessment requires thermal-LiDAR payload convergence for digital twin generation. Municipal contracts previously served by manned aviation vendors are consolidating toward leased drone platforms with real-time anomaly detection.
- Crop Monitoring:Normalized difference vegetation index mapping and variable-rate prescription generation drive seasonal lease demand among United States and European agricultural cooperatives. Edge-computing inference engines with onboard neural processing units are reducing insurance premiums for these operations.
- Aerial Photography:Cinematography and real estate marketing applications favor multi-rotor agility with gimbal-stabilized imaging payloads.
- Delivery Services:Last-mile logistics pilots operate under restricted beyond-visual-line-of-sight waivers with specialized liability frameworks.
Revenue stability characterizes infrastructure inspection; technology refresh intensity defines crop monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports drone hardware to leasing operators across Germany and the United States, establishing the primary trade-flow corridor for airframe supply. Fleet lessors in North America and Europe source multi-rotor and fixed-wing platforms from Shenzhen-based manufacturers. Regulatory divergence between FAA, EASA, and CAAC frameworks shapes regional deployment economics.
United States
Texas and California construction contractors drive demand for thermal payload access through fractional lease structures. FAA Part 107 waivers for beyond-visual-line-of-sight corridor mapping expand addressable mission profiles for multi-rotor fleets. Dallas-Fort Worth infrastructure inspection firms negotiate flight-hour billing with embedded maintenance coverage.
Germany
Agricultural cooperatives in Bavaria and Lower Saxony convert seasonal purchase commitments to annual lease structures for normalized difference vegetation index surveys. EASA CE marking requirements for fixed-wing systems above mass thresholds favor established lessors with centralized maintenance operations. Berlin-Brandenburg hosts emerging fractional lease platforms for cinematography production houses.
China
Domestic logistics operators accelerate commercial deployment for last-mile delivery pilots under CAAC registration tiers. Shenzhen manufacturing clusters supply airframes to lessors across Asia-Pacific and European markets. Yangtze River Delta assembly facilities benefit from production-linked incentive schemes for unmanned aerial vehicle production.
India
Maharashtra and Gujarat agricultural operators access variable-rate input technologies through seasonal lease arrangements. DGCA UAS Rules and PLI scheme incentives redirect lessor partnerships toward domestic assembly requirements. Karnataka hosts emerging joint ventures between international lessors and local contract manufacturers.
United Kingdom
London and Southeast production houses adopt hourly-access models for event coverage and cinematography applications. EASA operational authorization frameworks streamline cross-border fleet deployment with German and French lessors. Midlands engineering firms negotiate usage-based contracts for infrastructure digital twin generation.
Drone Leasing Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and autonomous navigation capabilities. The vendor base stratifies between vertically integrated airframe producers and regional lessors with fleet management expertise. Three archetypes dominate: manufacturing-anchored lessors leveraging supply agreements, autonomous navigation specialists reducing pilot dependency, and regional operators with localized regulatory compliance capabilities. Consolidation pressures favor scale-driven players with multi-jurisdictional certification portfolios.
Within the manufacturing-anchored tier, DJI Innovations and Parrot occupy positions that exemplify divergent strategic approaches—Shenzhen-based scale advantages versus Parisian specialization in fixed-wing endurance platforms. Skydio represents the autonomous navigation archetype with US-based engineering concentration. These three companies illustrate how competitive positioning fragments across hardware manufacturing, software differentiation, and regional service density rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Parrot |
| XAG |
| DJI Innovations |
| Yuneec |
| EHang |
| Skydio |
| JOUAV |
| Draganfly |
| Autel Robotics |
| Others |
Pricing and Supply Chain Analysis
Flight-hour billing with embedded maintenance coverage locks in both fleet access and cost predictability for Texas and California construction contractors navigating volatile lithium-polymer battery input markets and FAA Part 107 compliance refresh cycles.
Pricing Analysis
Technology-generation pricing gaps separate current-generation multi-rotor systems with Remote ID compliance from prior-generation airframes facing retrofit obsolescence and next-generation autonomous navigation stacks commanding pilot-reduction premiums. Three-tier pricing structure across premium autonomous fleets, standard FAA Part 107-compliant systems, and economy-tier legacy rentals reflects certification grade and embedded insurance coverage. Cost compression in economy-tier rentals is intensifying because Remote ID mandate compliance burdens compress residual value assumptions. Mid-sized agricultural cooperatives exhibit highest price sensitivity, while municipal infrastructure departments with consolidated procurement vehicles show lowest sensitivity due to standardized budget allocations.
Supply Chain Analysis
China and South Korea anchor lithium-polymer cell manufacturing and flight controller semiconductor fabrication for global drone leasing fleets. Shenzhen assembly clusters draw from Korean battery chemistry inputs, Taiwanese sensor foundry output, and domestic rare-earth magnet processing. Single-source vulnerability concentrates in Chinese cell manufacturing dominance, exposing North American and European lessors to extended lead times during fleet refresh cycles. Distribution runs through manufacturer-direct supply agreements with lessors, bypassing traditional distributor tiers for airframe and payload procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone leasing markets build defensive moats through regulatory entrenchment: FAA Part 107 certification requirements and EASA operational authorization frameworks create switching costs that lock enterprise customers into established lessor relationships.
For Market Incumbents: Consolidate fleet portfolios through targeted acquisition of regional operators with localized CAAC and DGCA compliance capabilities. Prioritize backward integration into lithium-polymer battery refurbishment operations to offset cell supply concentration risks from Chinese manufacturers. Lock in municipal infrastructure contracts through multi-year flight-hour billing arrangements that embed maintenance and payload swap entitlements, raising rival switching costs. For New Entrants and Emerging Players: EASA fast-track certification pathways for specific-category operational authorizations open white-space entry points for German and French agricultural cooperatives seeking fixed-wing endurance platforms. Target fractional lease structures for European cinematography production houses in Berlin-Brandenburg and London Southeast, where hourly-access models displace freelance pilot networks. Pursue joint venture structures with Indian contract manufacturers under PLI scheme incentives to circumvent import duty barriers for agricultural deployment. For Investors and Strategic Acquirers: Autonomous navigation software specialists with GPS-denied positioning capabilities represent priority acquisition targets, as sensor fusion engineering talent commands premium compensation that constrains organic development timelines. Long-term viability hinges on regulatory divergence between FAA, EASA, and CAAC frameworks persisting, preserving demand for multi-jurisdictional certification expertise. Watch for Beyond-Visual-Line-of-Sight waiver standardization as an inflection signal that would commoditize pilot-reduction advantages and compress autonomous stack premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Operational Authorization Fast-Track | Accelerates cross-border fleet deployment for German and French lessors seeking CE marking economies. |
| Lithium-Polymer Battery Backward Integration | Captures refurbishment margins and reduces Chinese cell supply vulnerability for North American operators. |
| Thermal-LiDAR Payload Convergence | Opens municipal digital twin contracts previously served by separate manned aviation vendors. |
| Indian PLI Joint Venture Structure | Circumvents DGCA import duties and aligns with domestic assembly requirements for agricultural leasing. |
| Fractional Lease Platform Launch | Penetrates mid-sized European production houses displacing freelance pilot networks with hourly-access models. |
Research Methodology
The analysis maps multi-rotor, fixed-wing, hybrid, and nano drone configurations, each validated through fleet operations directors at regional lessors, FAA Part 107 certification instructors, agricultural cooperative procurement managers, and municipal infrastructure engineering leads. Primary interview findings triangulate against EASA regulatory filings, FAA waiver databases, CAAC registration tier documentation, and customs trade data for airframe import flows. Bottom-up lease volume estimates from individual operator disclosures reconcile with top-down market sizing derived from manufacturer production disclosures.
Consistency checks validated projection outputs against external benchmarks including manufacturer shipment disclosures, lessor fleet expansion announcements, and regulatory authorization issuance rates across the analysis window. Segmentation modeling incorporates product type, end user vertical, deployment model capital intensity, and application mission profile dimensions. CAGRs derive from fitted growth curves applied to validated baseline estimates, with sensitivity testing around lithium-polymer battery cost trajectories and Remote ID compliance adoption timelines.
The analysis sits within stated boundaries; outcomes outside sustained regulatory divergence between FAA, EASA, and CAAC frameworks or accelerated Beyond-Visual-Line-of-Sight standardization would require recalibration. Forecasts reflect assumptions regarding pilot certification bottleneck persistence and battery supply concentration stability. Recalibration cycles align with material shifts in waiver issuance rates, PLI scheme incentive revisions, and autonomous navigation stack commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Global Drone Software Market
UAV
Commercial UAV Market
UAV
Drone Identification System Market
UAV
Drones Market
UAV
Fixed Wing Military Drones Market
UAV
UAV Battery Market
UAV
Drone Wireless Charging Station Market
UAV
Tethered Drones Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
Short-Range Delivery Drone Market
UAV
Drone-As-A-Service Market
UAV
Ultra-Long Endurance Drone Market
UAV
Drone Payload Market
UAV
Global Drone Autopilots Market
UAV
Asia-Pacific Drone Software Market
UAV
UAV Payload Market