
 United States Set-Top Box Market | 2026-2036
United States Set-Top Box Market Size, Share, and Industry Trends Forecast 2026-2036
United States Set-Top Box Market Intelligence
Market Context with Strategic Players
Residential streaming adoption is broadening the end-use vertical mix for set-top hardware beyond traditional cable subscribers. Comcast Corporation anchors the cable box segment through its Xfinity platform and extensive subscriber infrastructure. Roku Inc competes aggressively in the streaming device category with a software-centric model that reduces hardware margin dependence. Amazon.com Inc leverages its Fire TV ecosystem to control content distribution and voice-interface standards across millions of installed units.
Technical Definition and Structural Segments
A set-top box is a dedicated computing appliance that decodes encrypted television signals, executes conditional access protocols, and outputs video through HDMI or coaxial interfaces to display devices. The unit typically incorporates system-on-chip architectures, DRAM buffers, and flash storage to enable electronic program guides, DVR functionality, and over-the-top application execution. Streaming Devices now lead volume growth as cord-cutting accelerates, while Cable Boxes retain higher per-unit margins through operator-subsidized deployment models. Hybrid Set-Top Boxes represent the fastest-expanding structural category, bridging linear broadcast reception with IP-delivered content aggregation. IPTV technology commands premium positioning in the Technology dimension, though 4K Ultra HD remains the practical standard for most residential deployments.
Regulatory Framework and Forward Outlook
FCC regulations governing set-top box interoperability and energy efficiency standards directly shape hardware design cycles and market access conditions for manufacturers. The National Telecommunications and Information Administration coordinates spectrum policy that affects wireless video delivery options, while state-level public utility commissions in California and New York influence franchise agreements for cable operators deploying customer premises equipment. Stakeholders must monitor evolving FCC rules around app-based alternatives to leased hardware, as regulatory permission for software substitution could compress physical unit demand across the residential segment.
Market Dynamics
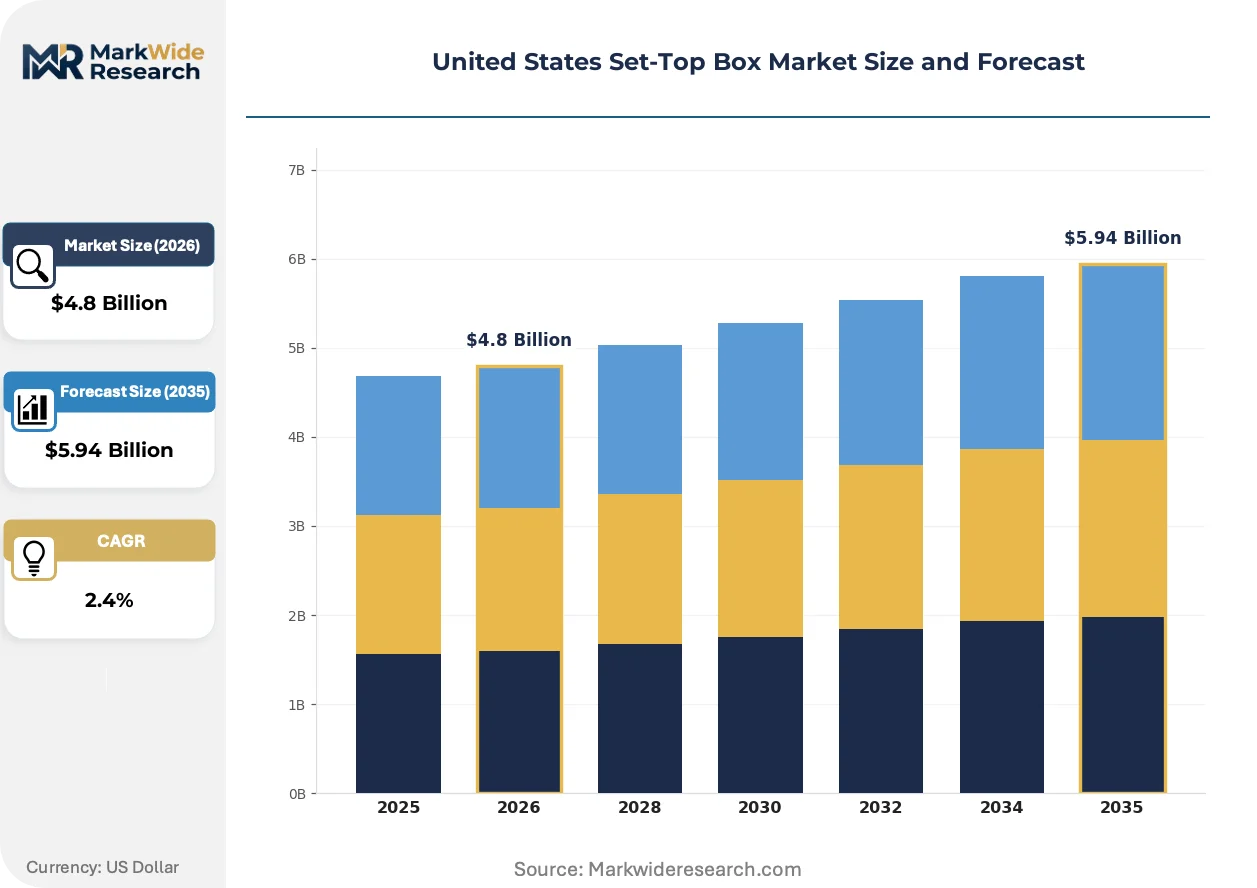
The United States set-top box market faces structural compression as FCC rules permitting app-based alternatives to leased hardware erode the traditional operator-subsidized deployment model. This regulatory pivot threatens the physical unit economics that have sustained cable and satellite equipment providers for decades.
Growth Catalysts
- Residential fiber buildouts:Verizon Fios and AT&T Fiber infrastructure expansions in Texas and California are expanding addressable households requiring 4K-capable IPTV gateways.
- Energy efficiency mandates:DOE appliance standards are forcing semiconductor upgrades that enable always-on streaming with reduced standby power draw.
- Smart home integration:Voice control protocols and Matter interoperability specifications are creating replacement demand among connected-home adopters.
Market Restraints
- Silicon supply concentration:Taiwan-based foundries dominate system-on-chip fabrication for set-top processors, exposing hardware vendors to geopolitical supply disruptions.
- DRAM price volatility:Memory buffer costs fluctuate with smartphone and server demand cycles, compressing margins on mid-tier streaming devices.
- Regulatory substitution risk:FCC app-based authorization rules allow cable operators to bypass leased equipment entirely, threatening physical unit volumes.
Strategic Opportunities
- Rural broadband subsidies:USDA ReConnect and FCC Rural Digital Opportunity Fund programs are extending addressable markets into underserved Appalachian and Great Plains counties.
- Healthcare vertical pivot:Remote patient monitoring integration through television interfaces is creating specialized set-top demand from Medicare Advantage plans.
- AI-driven personalization:On-device machine learning for content recommendation is differentiating premium hardware tiers from commodity streaming sticks.
Industry Challenges
- Conditional access certification delays:CableLabs security specifications require 12-18 month validation cycles that slow product launch timelines.
- Legacy QAM integration complexity:Hybrid devices must maintain backward compatibility with MPEG-2 broadcast infrastructure while supporting AV1 streaming codecs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Set-Top Box Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $5.94 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Streaming Devices, Cable Boxes, Satellite Receivers, Hybrid Set-Top Boxes Technology: 4K Ultra HD, HD, 8K, IPTV End User: Residential, Commercial, Educational Institutions, Hotels Distribution Channel: Online Retail, Electronics Stores, Telecom Operators, Others |
| Companies Covered | Apple Inc, ARRIS International Limited, Roku Inc, Alphabet Inc, EchoStar Corporation, Comcast Corporation, Amazon.com Inc, HUMAX Co. Ltd., Dish Network Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Set-Top Box Market Strategic Shifts & Innovations
Hardware architecture is fragmenting between operator-controlled gateways and consumer-purchased streaming appliances. This bifurcation is reshaping supply chain relationships and software monetization strategies across the residential video ecosystem.
Android TV and Roku operating systems are modularizing set-top functionality into discrete software layers that operators license rather than build. Charter Communications and Cox Communications have both migrated to third-party platforms. This shift compresses hardware differentiation while expanding addressable markets for silicon vendors selling reference designs.
FCC set-top box interoperability proceedings are mandating standardized APIs for navigation devices. Cable operators must expose linear channel lineups to competitive hardware. Comcast and Dish Network have accelerated software platform investments to retain subscriber control through superior user experience rather than equipment lock-in.
Subscription fatigue among United States households is shortening replacement cycles for streaming hardware. Consumers treat $30-50 devices as disposable rather than durable goods. Retail channels including Walmart and Best Buy have expanded private-label streaming stick placements to capture this churn-driven demand in suburban and exurban markets.
United States Set-Top Box Market Segmentation
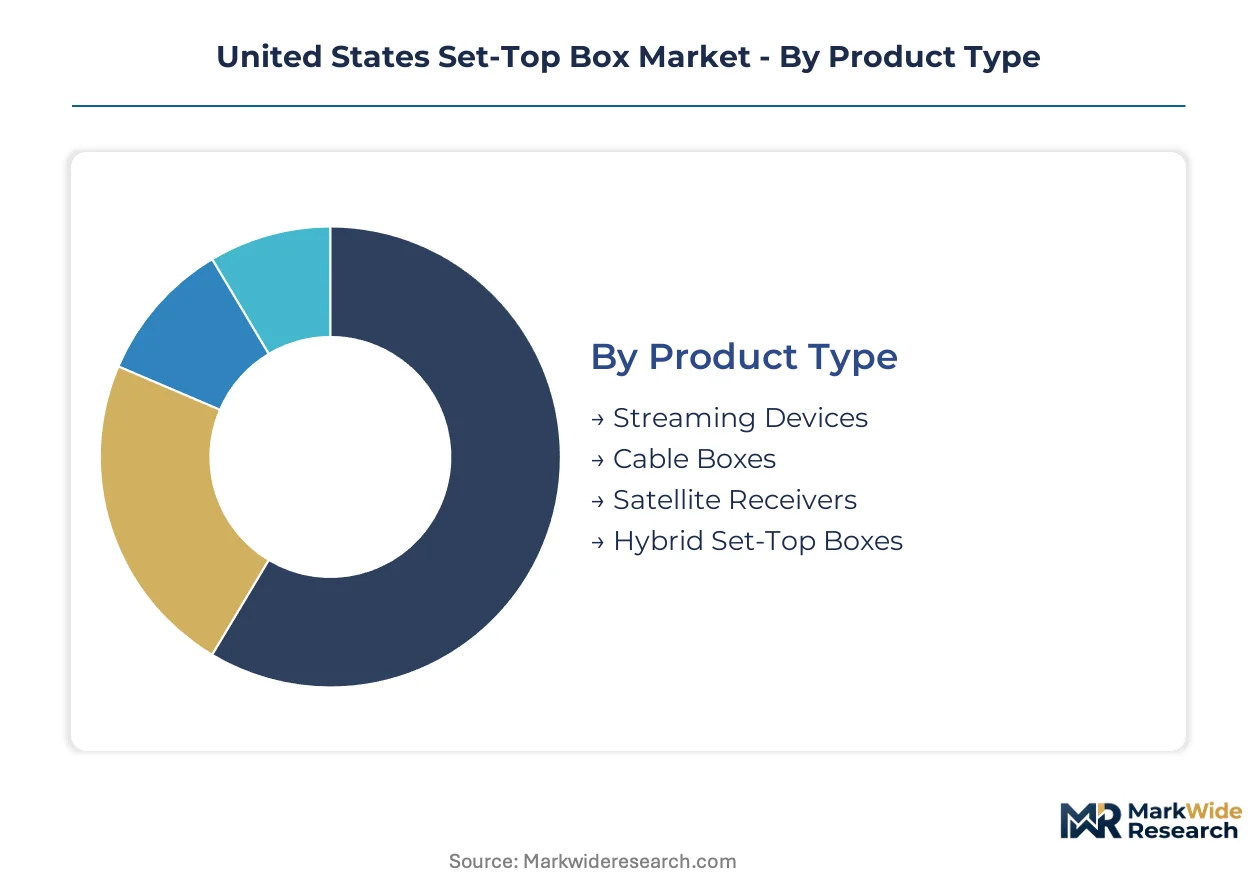
Segmentation in the United States set-top box market reveals divergent hardware requirements across delivery protocols and end-use environments. FCC certification burdens vary sharply between operator-controlled cable equipment and consumer-purchased streaming appliances, shaping vendor R&D allocation and go-to-market timelines.
Product Type:
Certification requirements fragment sharply across this dimension. Cable Boxes must complete CableLabs conditional access validation and FCC Part 15 emissions testing, a 12-18 month cycle that locks out smaller hardware vendors. Streaming Devices face lighter regulatory burdens through self-certification pathways, accelerating product refresh cycles.
- Streaming Devices:Compact HDMI-connected appliances running Android TV, Roku OS, or proprietary firmware on ARM-based system-on-chip architectures. Demand concentrates in suburban and exurban households cutting traditional cable subscriptions, driven by subscription fatigue and lower entry price points.
- Cable Boxes:Operator-leased decryption hardware with integrated QAM tuners, conditional access modules, and DOCSIS 3.1 connectivity for voice and data services. Deployment concentrates through Comcast Xfinity and Charter Spectrum infrastructure in California and Texas, constrained by FCC app-based substitution rules that threaten physical unit economics.
- Satellite Receivers:Dish Network and DirecTV proprietary hardware with Ka-band and Ku-band satellite demodulation capabilities.
- Hybrid Set-Top Boxes:Dual-mode devices bridging linear broadcast reception with IP-delivered streaming aggregation, requiring simultaneous CableLabs and streaming platform certification.
Cable Boxes sit at the top of the volume ranking, with Hybrid Set-Top Boxes climbing the fastest.
Technology:
Resolution tiers map directly to semiconductor cost structures and content availability, with 4K Ultra HD establishing the practical standard for most residential deployments while 8K remains a premium positioning play.
- 4K Ultra HD:3840x2160 resolution with HDR10 and Dolby Vision support, enabled by Amlogic and MediaTek chipsets with hardware AV1 decoding. Demand concentrates in fiber-connected households across California and Texas, driven by Netflix and Disney+ 4K tier availability.
- IPTV:IP-based video delivery using multicast and adaptive bitrate streaming protocols, requiring gateway devices with advanced QoS capabilities. Deployment concentrates through Verizon Fios and AT&T Fiber infrastructure, constrained by conditional access certification delays that extend product launch timelines.
- HD:1080p resolution hardware serving legacy cable subscribers and budget streaming segments.
- 8K:7680x4320 resolution with limited native content availability, positioned for early adopter and commercial display integration.
4K Ultra HD sits at the top of the volume ranking, with IPTV gaining share fastest through fiber infrastructure buildouts.
End User:
Customer type determines procurement pathways, with residential consumers purchasing through retail channels while commercial and institutional buyers negotiate direct operator contracts with extended service level agreements.
- Residential:Individual households acquiring hardware through retail purchase, operator lease, or bundled service agreements. Demand concentrates in multi-device homes seeking unified content aggregation, driven by smart home integration requirements and voice control protocol adoption.
- Commercial:Multi-dwelling unit deployments, corporate campuses, and hospitality properties requiring centralized management and bulk provisioning capabilities.
- Educational Institutions:K-12 and university deployments with CIPA compliance requirements and classroom integration specifications.
- Hotels:Property management system integration and guest room entertainment platforms with customized branding and billing interfaces.
Residential sits at the top of the volume ranking, with Commercial expanding most quickly through multi-dwelling unit fiber overbuilds.
Distribution Channel:
Channel selection determines margin capture and customer acquisition costs, with online retail compressing hardware margins while operator channels sustain subsidized deployment models.
- Telecom Operators:Verizon, AT&T, and cable MSOs deploying customer premises equipment through service bundling and lease arrangements. Volume concentrates in California and Texas infrastructure footprints, constrained by regulatory substitution risk from FCC app-based authorization rules.
- Online Retail:Amazon, Walmart.com, and direct-to-consumer channels for streaming devices and unlocked hardware. Growth concentrates in suburban markets with established e-commerce penetration, driven by subscription fatigue and shorter replacement cycles.
- Electronics Stores:Best Buy and regional retailers with in-store demonstration and installation service attachments.
- Others:Direct enterprise sales, system integrators, and specialized vertical distributors.
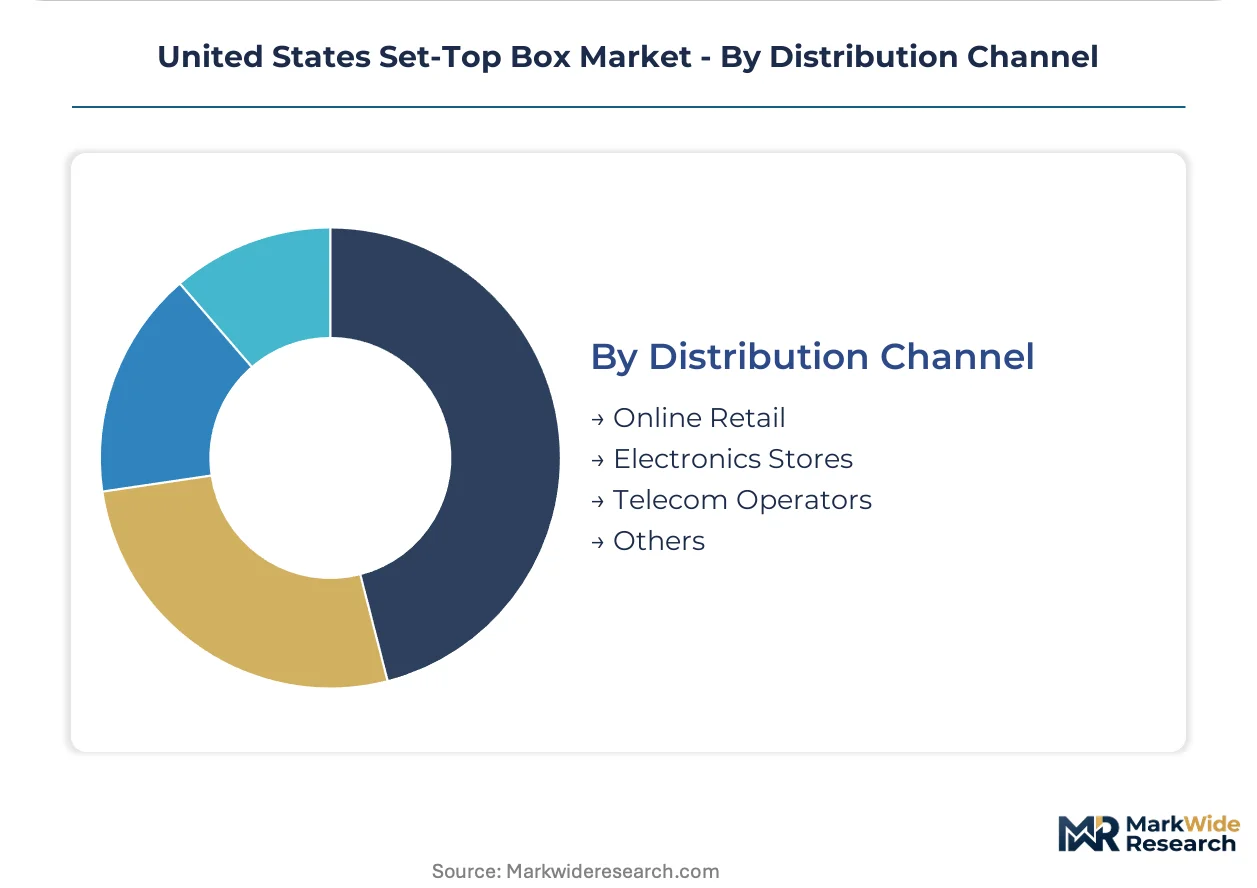
Telecom Operators sit at the top of the volume ranking, with Online Retail climbing the fastest through private-label streaming stick expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal in the United States set-top box market, as FCC certification requirements and CableLabs conditional access standards create uniform compliance costs nationwide. Production and deployment decisions instead track fiber infrastructure density, state-level franchise agreements, and regional household income distributions. Sub-regional concentration patterns reflect these underlying structural factors.
California
Verizon Fios and AT&T Fiber infrastructure expansions in Los Angeles and San Francisco metropolitan areas are driving 4K-capable IPTV gateway demand. California Public Utilities Commission franchise oversight shapes cable operator equipment deployment timelines. Silicon Valley semiconductor design clusters in Santa Clara County supply system-on-chip architectures to domestic hardware vendors.
Texas
AT&T Fiber buildouts in Dallas-Fort Worth and Houston are expanding addressable households for IP-based video delivery. Texas Public Utility Commission rate case proceedings influence operator capital allocation for customer premises equipment. Austin technology corridor hosts R&D facilities for streaming platform software development.
New York Metro
Multi-dwelling unit density in Manhattan and Brooklyn sustains demand for centralized video distribution systems. New York State Public Service Commission broadband infrastructure mandates accelerate fiber-to-the-building deployments. Long Island cable headend facilities serve as regional distribution hubs for leased set-top hardware.
Florida
Retirement community concentrations in Tampa and Orlando generate specialized demand for simplified user interfaces and healthcare-integrated television platforms. Florida Public Service Commission deregulation of video services reduces equipment deployment friction for competitive entrants. Miami serves as Latin American market testing ground for Spanish-language streaming hardware configurations.
Pacific Northwest
Amazon's Seattle headquarters proximity influences Fire TV ecosystem penetration rates in Portland and Seattle metropolitan areas. Washington Utilities and Transportation Commission consumer protection rules govern equipment lease disclosure requirements. Vancouver, Washington manufacturing facilities assemble streaming devices for West Coast retail distribution.
United States Set-Top Box Market Key Industry Players
Software platform licensing dominates the current landscape as cable operators abandon proprietary hardware development. The vendor base separates into three tiers: operator-controlled gateway suppliers, consumer-facing streaming device manufacturers, and hybrid solution providers bridging both models. Strategic archetypes include ecosystem orchestrators seeking content distribution control, semiconductor-integrated hardware specialists, and retail-channel-dependent volume players. Portfolio diversification and technology licensing represent the two dominant competitive moves, with vendors expanding from single-product lines into adjacent smart home categories while cross-licensing streaming platform software.
Among ecosystem orchestrators, Apple Inc exemplifies premium-tier positioning through integrated hardware-software-content stacks. Roku Inc occupies the streaming platform licensing vector, enabling operator migrations to third-party software without proprietary development. Comcast Corporation anchors the cable-integrated gateway segment through Xfinity infrastructure scale. These three entities represent distinct strategic archetypes rather than direct competitors, each capturing value from different segments of the bifurcating residential video hardware market.
| Leading Market Players |
|---|
| Apple Inc |
| ARRIS International Limited |
| Roku Inc |
| Alphabet Inc |
| EchoStar Corporation |
| Comcast Corporation |
| Amazon.com Inc |
| HUMAX Co. Ltd. |
| Dish Network Corporation |
| Others |
Cost & Logistics Intelligence
Silicon Valley firmware engineering clusters in Santa Clara County anchor the labor-cost differentials that separate premium-tier gateway pricing from economy streaming stick margins. The concentration of embedded systems talent near semiconductor design centers compresses R&D overhead for high-end IPTV hardware while offshore assembly in Mexican maquiladoras enables sub-$30 retail positioning for disposable streaming appliances.
Pricing Analysis
Retailer markup layers dominate final consumer pricing, with Best Buy and Walmart capturing 25-40 point spreads over factory-gate costs for streaming devices while operator lease arrangements bypass retail margin entirely. Three-tier pricing structure across premium, standard, and economy levels maps to CableLabs certification grade, with conditional access validation adding 18-month cost amortization to cable gateway hardware. Pricing pressure stems from FCC app-based substitution rules that eliminate equipment lease revenue streams for cable operators. Residential cord-cutters exhibit highest price sensitivity, treating sub-$50 streaming sticks as disposable consumables, while commercial multi-dwelling unit buyers prioritize centralized management capabilities over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundries fabricating Amlogic and MediaTek system-on-chip processors for streaming hardware. Hardware vendors draw from South Korean DRAM suppliers, Chinese PCB assembly contractors, and Vietnamese final assembly facilities for cost-sensitive retail SKUs. Geopolitical exposure to Taiwan Strait disruption represents the dominant structural risk, with alternative sourcing requiring 12-18 month qualification cycles. Distribution runs through operator-controlled provisioning systems for leased cable equipment and direct-to-retail container shipments for consumer-purchased streaming devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in hybrid gateway categories where fiber infrastructure buildouts justify premium hardware tiers, and in software licensing models that decouple revenue from physical unit economics.
For Market Incumbents: Hedge against FCC app-based substitution by accelerating Android TV and Roku platform licensing to cable operator clients, converting hardware revenue to recurring software fees. Deepen captive supply of conditional access modules through backward integration into CableLabs-certified security silicon, defending against margin compression from emerging fabless competitors in Shenzhen. For New Entrants and Emerging Players: Capture rural broadband subsidy flows through USDA ReConnect and FCC Rural Digital Opportunity Fund programs, targeting Appalachian and Great Plains counties with simplified 4K streaming hardware bundled with fixed-wireless access. Penetrate Medicare Advantage healthcare verticals through remote patient monitoring integration, leveraging television interfaces for senior demographics underserved by smartphone-centric health platforms. For Investors and Strategic Acquirers: Cable operators seeking software platform control are the most active acquirer in this space, prioritizing streaming OS licensing capabilities over hardware manufacturing assets. Long-term viability favors vendors with recurring revenue exposure and operator channel relationships rather than retail-dependent volume plays. Watch FCC interoperability rulemaking timelines as the critical inflection signal for physical unit demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Licensing Migration | Charter and Cox adopting Roku OS reduces proprietary development costs while locking in content distribution control. |
| Conditional Access Verticalization | CableLabs security certification investments create 18-month moats against unlicensed hardware competitors. |
| Rural Broadband Hardware Bundling | USDA ReConnect subsidies extend addressable markets into underserved counties with fiber-to-the-home overbuilds. |
| Healthcare Vertical Integration | Medicare Advantage plans integrating remote monitoring through television interfaces create specialized demand. |
| AI Personalization Tiering | On-device machine learning for content recommendation differentiates premium hardware from commodity streaming sticks. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cable operator procurement directors, streaming platform engineering leads, semiconductor vendor product managers, and retail category buyers with secondary validation against FCC equipment authorization databases, CableLabs certification filings, and SEC 10-K disclosures from publicly traded hardware vendors. Bottom-up volume modeling across product type, technology, and end-user segments was cross-checked against top-down infrastructure deployment data from Verizon Fios and AT&T Fiber.
Segment-weighting approaches applied differential growth assumptions across streaming devices, cable boxes, and hybrid gateways, with resolution tiers and distribution channels modeled as cross-cutting dimensions. CAGRs were derived from installed base turnover analysis and fiber household penetration curves, incorporating conditional access certification delays and regulatory substitution risk as dampening factors.
Geopolitical supply disruption, accelerated FCC app-based authorization, and DRAM price volatility are the dominant revision risks that could compress hardware unit forecasts or shift margin pools toward software licensing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
LTE IoT Devices Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
Communication Base Station Equipment Pcb Market
Telecom Hardware
SATCOM Transceivers Market
Telecom Hardware
Synchronous Optical Network (SONET) Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Industrial Transceivers Market
Telecom Hardware
Global Ultra Portable Internet Device Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
Base Station Market