
 LTE IoT Devices Market | 2026-2036
LTE IoT Devices Market Size, Share, and Industry Trends Forecast 2026-2036
LTE IoT Devices Market Insights
Modularization of connectivity stacks is shifting buyer choice from discrete components toward pre-certified module-plus-software bundles. Quectel Wireless Solutions leverages its manufacturing scale to dominate the embedded module tier across automotive and utility verticals. u-blox anchors its position through specialized GNSS-integrated cellular modules that reduce bill-of-material complexity for device makers.
LTE IoT devices are cellular-connected endpoints that transmit telemetry, status, and control data over licensed spectrum in the 700 MHz to 2.6 GHz range, with Cat M1 supporting mobility at 1 Mbps and NB-IoT optimizing stationary sensors at 200 kbps for decade-long battery life. Their primary purpose is to replace wired infrastructure and unlicensed radio networks in asset tracking, environmental monitoring, and remote equipment control. Module configurations lead volume shipments due to their integration into third-party hardware, while NB-IoT technology is capturing the fastest expansion in utility metering and agricultural soil monitoring where ultra-low power consumption outweighs bandwidth needs. Smart Cities as an end-user segment concentrates margin pools because municipal procurement cycles favor vendors with multi-year certification records and localized technical support.
The FCC governs device certification and spectrum allocation in the United States, while ETSI and the CE marking framework set radio equipment standards across Europe, and China's MIIT administers network access licenses and type approval for cellular devices. These regulators shape demand by dictating power limits, roaming protocols, and cybersecurity baselines that determine which hardware designs qualify for deployment. Stakeholders must monitor spectrum reallocation proceedings and emerging cybersecurity labeling requirements that could invalidate existing certification investments.
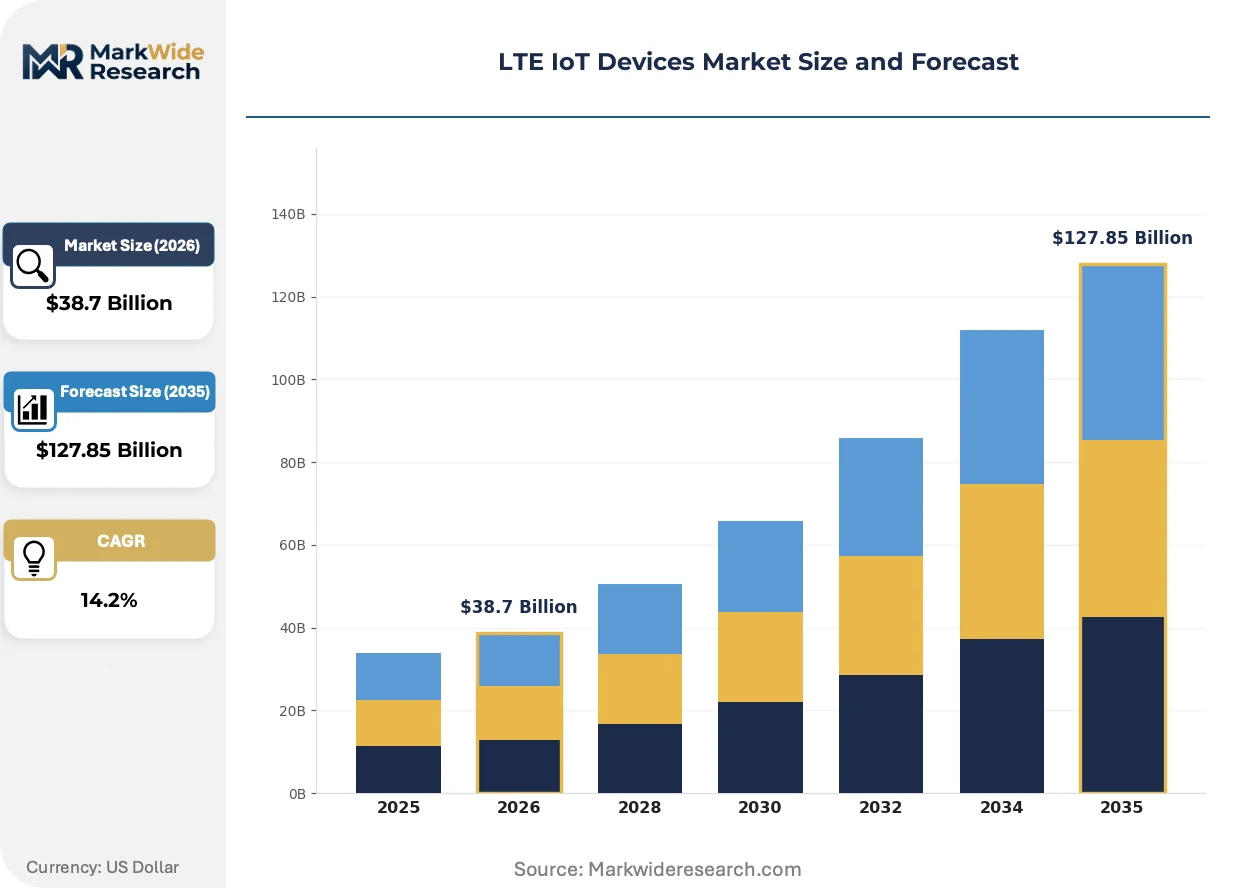
Market Dynamics
Modularization is compressing procurement cycles as buyers abandon discrete component sourcing for pre-certified module-plus-software bundles that slash certification timelines and engineering overhead.
Growth Catalysts
- FCC spectrum efficiency mandates:US utilities face regulatory pressure to replace legacy unlicensed radios with certified Cat M1 hardware, accelerating module replacement cycles across grid infrastructure.
- Smart city infrastructure:Municipal deployments in Barcelona and Singapore are standardizing on NB-IoT for streetlight control and waste management, creating recurring module procurement at scale.
- East Asian manufacturing corridors:Module integrators clustered in Shenzhen and Taipei serve automotive OEMs and industrial telemetry buyers, concentrating demand pull in vertically integrated supply zones.
Market Restraints
- Semiconductor input volatility:RF front-end components and power amplifiers face allocation constraints, squeezing module margins and extending lead times for high-volume orders.
- Supply concentration risk:Foundry capacity for cellular baseband silicon concentrates in Taiwan, exposing module vendors to geopolitical disruption and capacity rationing during demand spikes.
- NB-IoT mobility limitations:The 200 kbps stationary-optimized protocol cannot support vehicle tracking or handheld applications, restricting addressable use cases in logistics and workforce mobility.
Strategic Opportunities
- Indian utility metering:The country's central electricity regulator mandates smart prepaid meters nationwide, creating a greenfield NB-IoT deployment opportunity without legacy infrastructure displacement costs.
- GNSS-cellular convergence:Asset tracking buyers demand fused positioning stacks that combine LTE-M connectivity with multi-constellation navigation, enabling premium module pricing in fleet management.
- EU cybersecurity labeling:The forthcoming CE marking extension for connected devices creates first-mover advantage for vendors with pre-certified secure elements, locking out late entrants from public procurement.
Industry Challenges
- Multi-band certification complexity:Module vendors must validate hardware across 700 MHz to 2.6 GHz variants for each national regulator, fragmenting engineering resources and delaying regional launches.
- Firmware integration with legacy SCADA:Industrial buyers operate decades-old control systems with proprietary protocols, requiring costly protocol translation layers that erode module gross margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LTE IoT Devices Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modules, Sensors, Gateways, Routers Technology: Cat M1, NB-IoT, LTE, 5G End User: Manufacturing, Agriculture, Healthcare, Smart Cities Installation: Embedded, Standalone, Cloud-Based, On-Premises |
| Companies Covered | Quectel Wireless Solutions, u-blox, Qualcomm Technologies, Thales Group, Fibocom Wireless, Telit Communications, Sierra Wireless, Ericsson, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LTE IoT Devices Market Trends and Innovations
Connectivity stacks are collapsing into unified hardware-software bundles that compress buyer decision cycles and shift vendor competition from component specs to certification velocity and localized support depth.
iSIM technology is expanding into the embedded module tier by eliminating physical SIM trays and enabling remote carrier provisioning over-the-air. Automotive OEMs in Germany and Japan are adopting iSIM-equipped Cat M1 modules for telematics control units, cutting bill-of-material part counts while enabling subscription flexibility that legacy removable SIMs cannot match. This technology is expanding into fleet management and shared mobility platforms where device logistics and carrier switching costs previously blocked cellular adoption.
The EU Cybersecurity Act's radio equipment directive amendments now mandate vulnerability disclosure and secure update mechanisms for cellular IoT devices sold in member states. Module vendors must redesign firmware architectures to support encrypted boot chains and signed over-the-air updates, adding non-recurring engineering costs that favor established players with existing secure development lifecycles. Industrial sensor manufacturers targeting European energy and water utilities are prioritizing pre-certified modules from vendors with documented security development processes to avoid procurement disqualification.
Municipal buyers are consolidating vendor relationships around multi-year framework agreements that bundle hardware supply with localized technical support and spare inventory holding. Smart city procurement teams in Singapore and Barcelona now require module vendors to maintain regional engineering presence and commit to decade-long firmware maintenance, displacing transactional component sales. This pattern concentrates margin pools with vendors who have invested in direct municipal sales channels and certification track records, squeezing module distributors and trading houses out of high-value infrastructure contracts.
LTE IoT Devices Market Segmentation
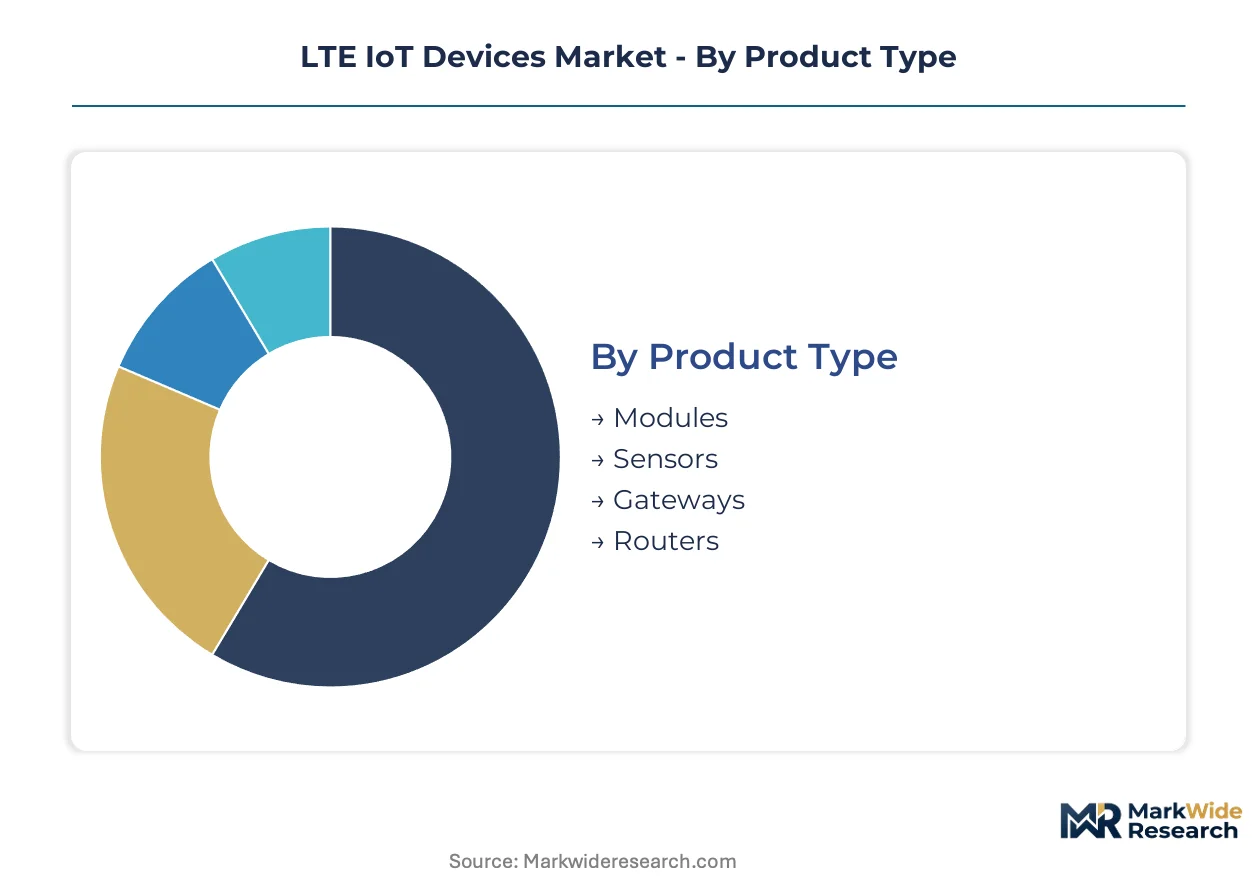
LTE IoT device procurement splits sharply between high-volume module shipments for embedded integration and premium-priced complete systems for municipal infrastructure. Understanding where margin pools concentrate versus where unit volumes flow determines vendor resource allocation and partnership strategy.
Product Type:
Modules dominate unit shipments while sensors and gateways capture disproportionate margin in complete solution sales.
- Modules:Pre-certified cellular radio units with integrated baseband processors and RF front-ends that device manufacturers solder onto motherboards. Demand concentrates in Shenzhen and Taipei manufacturing corridors where automotive OEMs and industrial telemetry buyers source embedded connectivity stacks, driven by FCC certification requirements that favor pre-validated hardware over discrete component builds.
- Sensors:Battery-powered environmental and equipment monitoring endpoints with integrated NB-IoT or Cat M1 radios. Agricultural soil monitoring deployments in Spain and utility metering programs in India are absorbing the fastest volume expansion, constrained by decade-long battery life requirements that limit processing headroom.
- Gateways:Edge aggregation devices that bridge multiple local sensors to cellular backhaul.
- Routers:High-throughput cellular routing equipment for mobile and temporary installations.
Today's leader: Modules. Tomorrow's challenger: Sensors.
Technology:
Stationary-optimized protocols trade bandwidth for power efficiency while mobility-capable standards command certification premiums.
- NB-IoT:Narrowband protocol operating at 200 kbps with 20 dB extended coverage and 10-plus year battery life for stationary assets. Smart city infrastructure in Barcelona and Singapore standardizes on NB-IoT for streetlight control and waste management, creating recurring procurement at scale.
- Cat M1:LTE-M standard supporting 1 Mbps throughput and full mobility handovers for vehicle and handheld applications. US utilities face FERC-aligned state mandates to replace legacy unlicensed radios with certified Cat M1 hardware, accelerating module replacement cycles across grid infrastructure.
- LTE:Legacy broadband cellular for high-bandwidth IoT applications.
- 5G:Next-generation cellular for ultra-low latency and massive device density.
NB-IoT commands volume leadership. Cat M1 holds pricing power in mobility applications.
End User:
Municipal procurement cycles favor established certification records while industrial buyers prioritize protocol compatibility with legacy control systems.
- Smart Cities:Municipal deployments spanning streetlight automation, environmental monitoring, and public safety networks. Singapore and Barcelona procurement teams require decade-long firmware maintenance commitments and regional engineering presence, concentrating margin pools with vendors who have invested in direct municipal sales channels.
- Manufacturing:Industrial telemetry for predictive maintenance and asset tracking. German and Japanese automotive OEMs are adopting iSIM-equipped modules for telematics control units, cutting bill-of-material complexity while enabling subscription flexibility.
- Agriculture:Soil moisture, weather, and livestock monitoring in remote locations.
- Healthcare:Remote patient monitoring and medical equipment tracking systems.
Smart Cities capture margin concentration. Manufacturing drives volume scale.
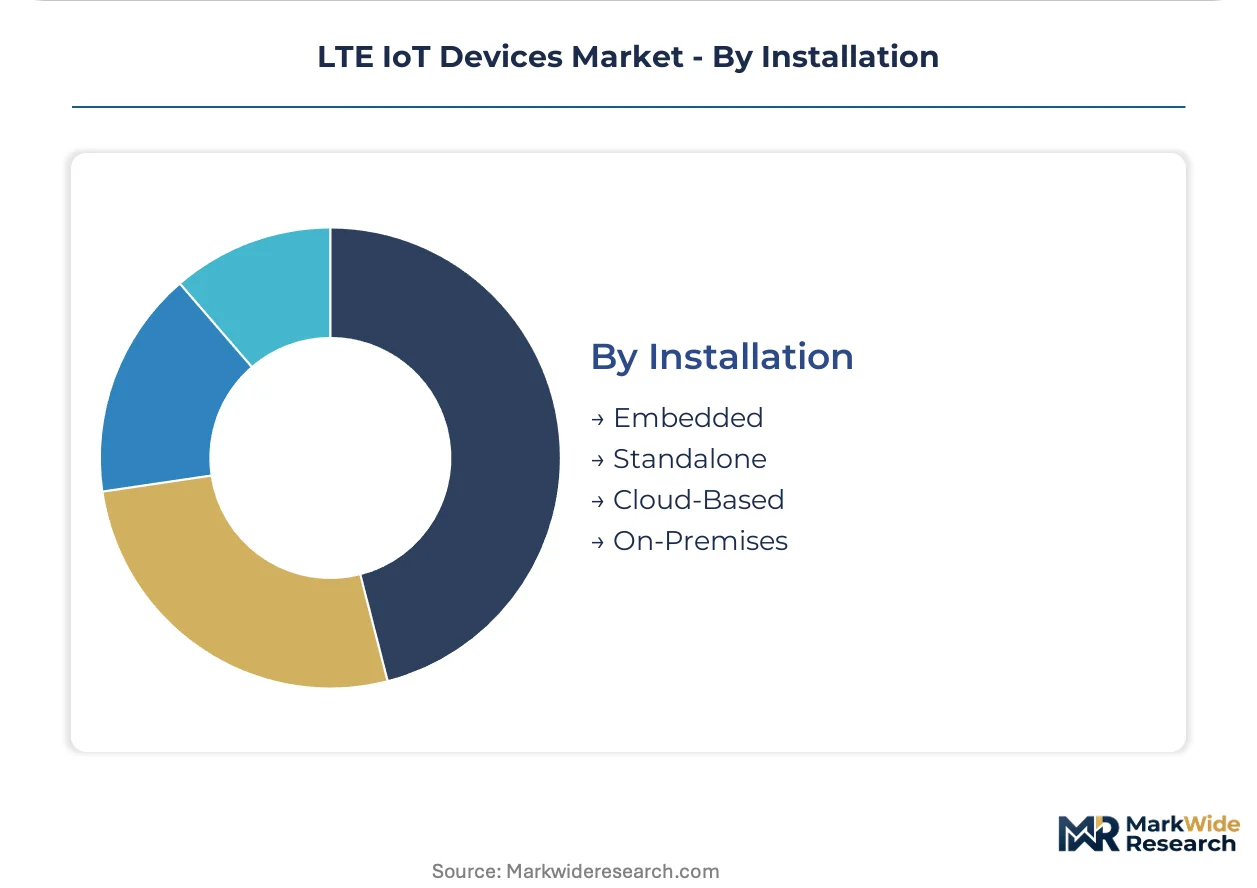
Installation:
Deployment architecture determines who controls the security boundary and bears ongoing maintenance liability.
- Embedded:Cellular modules integrated directly into third-party equipment during manufacturing. Module integrators in East Asian manufacturing corridors serve automotive and industrial telemetry buyers, concentrating demand pull in vertically integrated supply zones.
- Standalone:Self-contained devices with independent power and enclosure for field retrofit. Fleet management platforms and shared mobility operators favor standalone units where device logistics and carrier switching costs previously blocked cellular adoption.
- Cloud-Based:Devices connecting to vendor-managed cloud platforms for data processing.
- On-Premises:Local server deployment for data sovereignty and latency requirements.
Embedded leads OEM integration. Standalone gains in retrofit applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The LTE IoT device industry traces its commercial scaling to early cellular module manufacturing clusters in Shenzhen and Taipei, where contract electronics assemblers first integrated licensed-band radios into automotive telematics units during the mid-2010s.
United States
FERC-aligned state mandates and FCC spectrum efficiency rules are accelerating Cat M1 module procurement across electric utilities replacing legacy unlicensed grid radios. The FCC's device certification framework dictates power limits and roaming protocols that determine hardware qualification timelines. Module integrators in Silicon Valley and Austin serve industrial telemetry buyers with pre-certified embedded stacks.
Germany
Automotive OEMs in Stuttgart and Munich are adopting iSIM-equipped modules for telematics control units, cutting bill-of-material complexity while enabling subscription flexibility. The EU Cybersecurity Act's radio equipment directive amendments mandate secure update mechanisms for cellular IoT devices sold in member states. Bavarian engineering clusters anchor secure element integration into module firmware architectures.
China
MIIT network access licenses and type approval requirements govern cellular device deployment across smart city infrastructure and industrial monitoring applications. Module integrators concentrated in Shenzhen and Shanghai manufacturing corridors serve domestic automotive OEMs and agricultural sensor buyers. The Yangtze River Delta hosts vertically integrated supply zones where baseband silicon fabrication concentrates.
Singapore
Municipal procurement teams require decade-long firmware maintenance commitments and regional engineering presence for NB-IoT streetlight control and waste management deployments. The country's national telecommunications regulator shapes spectrum allocation for licensed IoT bands in dense urban environments. Smart city infrastructure procurement in the city-state favors vendors with multi-year certification records and localized technical support.
India
The Central Electricity Authority mandates smart prepaid meters nationwide, creating greenfield NB-IoT deployment opportunity without legacy infrastructure displacement costs. TRAI spectrum policies influence licensed-band IoT adoption timelines across utility and agricultural monitoring segments. Module distributors in Delhi-NCR and Bengaluru serve state electricity boards rolling out cellular-connected metering infrastructure.
LTE IoT Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification velocity and secure element integration depth. The vendor base organizes into three tiers: established module houses with decade-long municipal track records, automotive-focused specialists with GNSS-cellular convergence capabilities, and contract manufacturers competing on unit economics for high-volume embedded orders. Dominant competitive moves include strategic partnerships with foundry operators for baseband silicon allocation security and portfolio diversification into iSIM-equipped firmware architectures.
Within the established module tier, Quectel Wireless Solutions and u-blox exemplify divergent positioning strategies. Quectel leverages manufacturing scale to anchor the embedded module tier across automotive and utility verticals. u-blox occupies a position through specialized GNSS-integrated cellular modules that reduce bill-of-material complexity for device makers. Both represent archetypes of how vendors capture margin concentration in municipal procurement cycles versus volume scale in OEM integration channels.
| Leading Market Players |
|---|
| Quectel Wireless Solutions |
| u-blox |
| Qualcomm Technologies |
| Thales Group |
| Fibocom Wireless |
| Telit Communications |
| Sierra Wireless |
| Ericsson |
| Huawei Technologies |
| Others |
Pricing and Supply Chain Analysis
FCC spectrum efficiency mandates gate qualified supply and premium-tier pricing access for LTE IoT module vendors, as utilities demand pre-certified Cat M1 hardware that commands margin premiums over uncertified alternatives while excluding commodity producers lacking regulatory track records.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates module procurement, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in the economy tier is intensifying because foundry capacity constraints squeeze margins for high-volume orders. Municipal buyers in Singapore and Barcelona show lowest price sensitivity due to decade-long maintenance requirements, while agricultural sensor deployers in India prioritize unit economics above certification depth.
Supply Chain Analysis
RF front-end component supply rests on Taiwanese specialty semiconductor foundries, Japanese power amplifier manufacturers, and Chinese module assembly operations. Baseband silicon, ceramic filters, and precision oscillators constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan's cellular baseband fabrication, exposing vendors to geopolitical disruption. Distribution runs through Shenzhen and Taipei manufacturing corridors serving automotive OEMs and industrial telemetry buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LTE IoT device market functions as a regulatory compounder, with the EU Cybersecurity Act's radio equipment directive amendments creating certification barriers that accelerate demand consolidation toward pre-qualified vendors.
For Market Incumbents: Anchor module portfolio strategy around iSIM-equipped firmware architectures and secure element integration to defend against automotive OEMs switching to GNSS-cellular convergence stacks. Pursue backward integration into baseband silicon allocation through foundry partnership commitments, prioritizing Taiwan capacity locks. Deepen municipal sales channels in Singapore and Barcelona with decade-long maintenance contracts that disqualify transactional competitors. For New Entrants and Emerging Players: iSIM technology-first wedges open fleet management and shared mobility platforms where carrier switching flexibility previously blocked cellular adoption. Target Indian utility metering as the most penetrable geography, exploiting greenfield NB-IoT deployment without legacy displacement costs. Lead with over-the-air provisioning capabilities as the go-to-market angle against entrenched module houses. For Investors and Strategic Acquirers: Roll-up economics work for secure element specialists because EU cybersecurity labeling mandates create acquisition scarcity for pre-certified firmware architectures. Five-to-ten year viability hinges on certification velocity rather than manufacturing scale. Watch FCC spectrum reallocation proceedings as the inflection indicator for module replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| iSIM Architecture Migration | Eliminates physical SIM trays for German automotive OEMs while enabling subscription flexibility. |
| Secure Element Integration | Locks in EU public procurement eligibility ahead of cybersecurity labeling enforcement. |
| Foundry Capacity Partnership | Secures baseband silicon allocation from Taiwanese fabrication facilities amid rationing risk. |
| Municipal Framework Agreement | Bundles hardware supply with localized Singapore engineering presence for streetlight deployments. |
| GNSS-Cellular Convergence | Captures premium module pricing in fleet management through fused positioning stacks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with module vendor product managers, utility procurement officers, automotive telematics engineers, and municipal smart city directors with secondary validation from FCC equipment authorization databases, MIIT network access license filings, ETSI harmonized standards, and customs trade records for cellular radio modules. Bottom-up shipment aggregation and top-down market sizing triangulated across technology tiers and end-use verticals.
Comparable historical periods anchored the projection horizon to module replacement cycles observed during prior cellular generation transitions, with segmentation modeling across product type, technology protocol, end-user vertical, and installation architecture. CAGRs derived from regression analysis of procurement volume trends against regulatory mandate timelines, incorporating foundry capacity utilization and spectrum allocation proceedings as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor allocation constraints and geopolitical disruption to Taiwanese baseband supply. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and municipal procurement pacing. A small set of triggers—FCC spectrum reallocation decisions, EU cybersecurity labeling implementation dates, and foundry capacity expansion announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Africa Small Cell Market
Telecom Hardware
Digital TV Soc Market
Telecom Hardware
Synchronous Optical Network (SONET) Market
Telecom Hardware
Point-To-Point Antenna Market
Telecom Hardware
SATCOM Transceivers Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Very Small Aperture Terminal (VSAT) Market
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
OTN Hardware Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
Global Volte Market
Telecom Hardware
Base Station Market
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market