
 Europe Zero-Touch Provisioning Market | 2026-2036
Europe Zero-Touch Provisioning Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Zero-Touch Provisioning Market Insights
Software-defined networking (SDN) integration with cloud-native orchestration layers is reshaping how European carriers deploy and manage infrastructure at scale. Cisco Systems leverages extensive R&D investments across SDN controllers and intent-based networking to sustain technology leadership in automated service delivery. Nokia Corporation anchors its competitive position through deep specialization in telco-grade cloud infrastructure, while Juniper Networks competes aggressively in the service provider segment with contrail-based orchestration platforms.
Zero-touch provisioning denotes an automated methodology wherein network devices, servers, or endpoints self-configure without manual intervention upon initial power-on or network attachment, typically utilizing bootstrap protocols, certificate-based authentication, and pre-staged policy templates to establish secure operational states. The architecture eliminates truck rolls and reduces mean-time-to-service from days to minutes across distributed environments. Cloud-based deployment models now lead European adoption as telecom operators prioritize OpEx flexibility and elastic scaling across multi-vendor environments. AI-driven solutions within the technology dimension represent the fastest-expanding segment, with machine learning algorithms increasingly handling anomaly detection and self-healing during automated provisioning workflows.
The European Telecommunications Standards Institute (ETSI) and the EU Cybersecurity Act establish mandatory certification frameworks that shape product development timelines and market access conditions for automated provisioning vendors. CE marking requirements under the Radio Equipment Directive further constrain hardware-software integration pathways, particularly for IoT endpoints entering European networks. Stakeholders must monitor evolving ENISA guidance on automated security configuration as regulatory stringency intensifies for critical infrastructure operators across the continent.
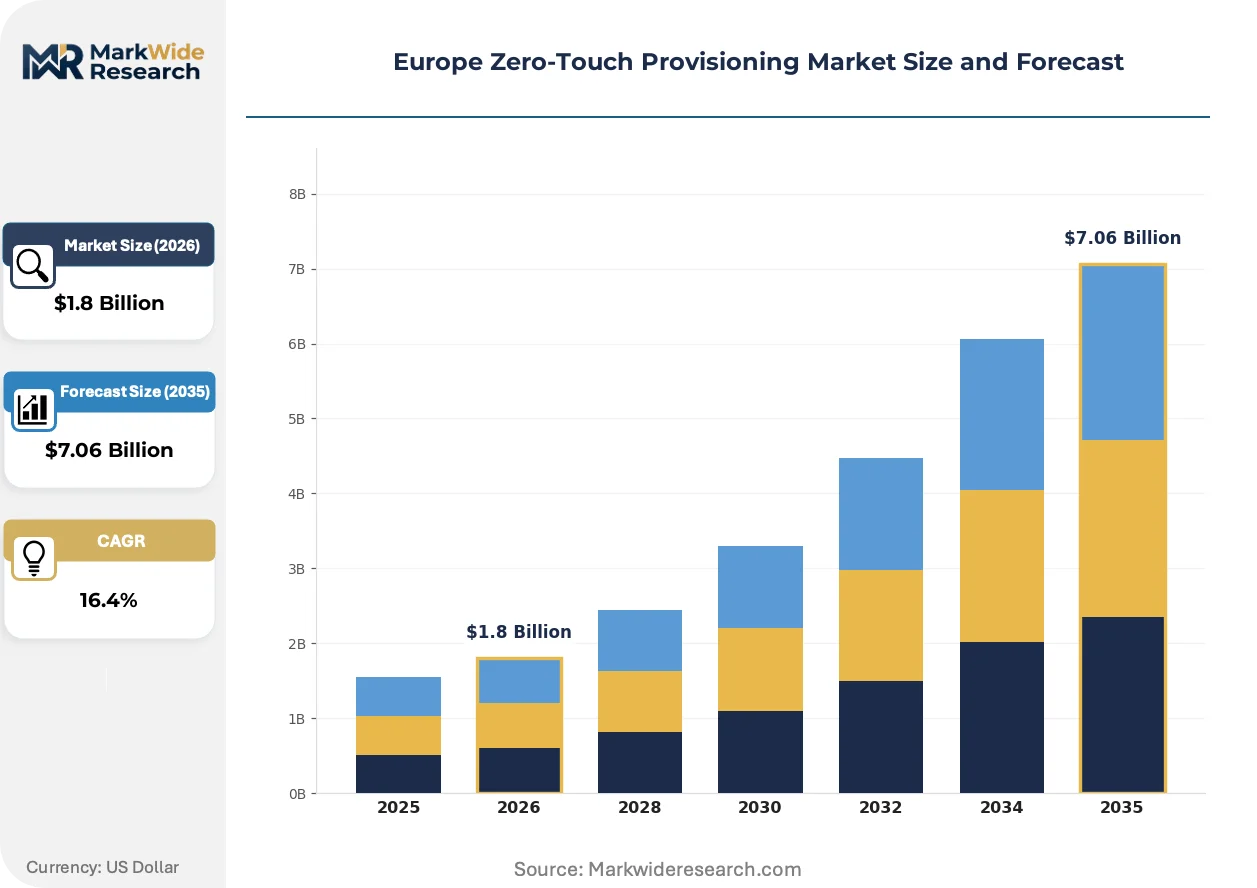
Market Dynamics
The EU AI Act and Cybersecurity Act are compressing vendor certification timelines while mandating automated security configuration for critical infrastructure, forcing European telecom operators to accelerate zero-touch deployment roadmaps across 5G and private networks.
Growth Catalysts
- EU AI Act compliance mandates:Automated provisioning systems satisfy Article 15 continuous monitoring requirements for high-risk AI applications in network infrastructure.
- Industrial private 5G deployments:German automotive manufacturers and chemical processors require zero-touch pipelines to scale thousands of connected sensors across distributed production sites.
- Cloud-native orchestration maturation:Kubernetes-based network function virtualization enables telcos to provision multi-vendor equipment through unified API layers.
Market Restraints
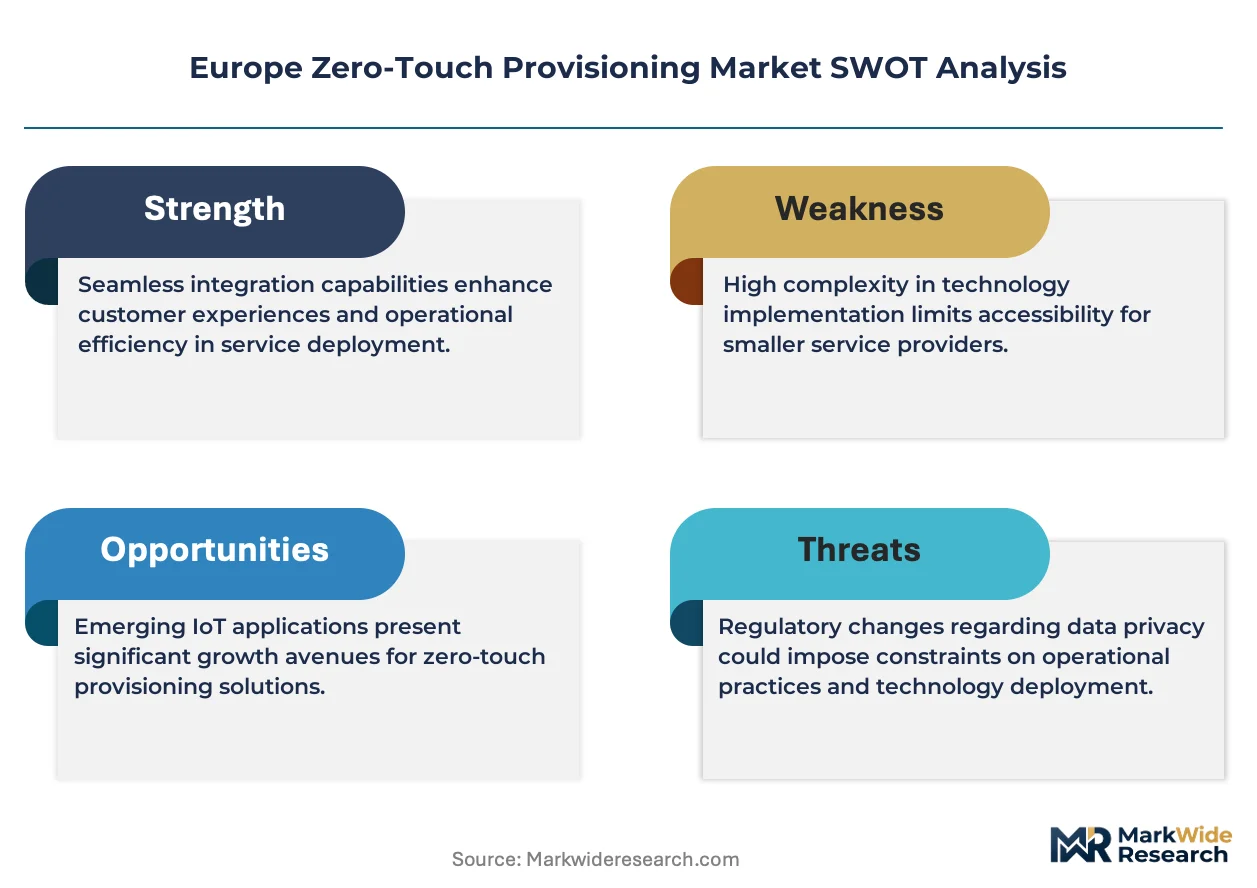
- CE marking complexity under RED:The Radio Equipment Directive imposes hardware-software integration testing that extends product launch cycles for IoT endpoints.
- Semiconductor supply concentration:Dependence on specialized ASICs from East Asian foundries creates vulnerability in network equipment manufacturing.
- Certificate management fragmentation:Incompatible PKI standards across EU member states complicate cross-border automated authentication workflows.
Strategic Opportunities
- Polish industrial corridor expansion:Central European manufacturing hubs are deploying private LTE networks with minimal existing automation infrastructure.
- ENISA certification pre-positioning:Early alignment with evolving automated security configuration guidance creates first-mover advantage for vendors.
- Edge-AI convergence:Integration of machine learning inference at network edge points enables real-time anomaly detection during device onboarding sequences.
Industry Challenges
- DevNetOps skill scarcity:European telecom operators struggle to recruit engineers fluent in both legacy telco protocols and cloud-native tooling.
- Brownfield integration friction:Retrofitting zero-touch capabilities into existing SNMP-managed infrastructure demands complex mediation layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Zero-Touch Provisioning Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-based, On-premises, Hybrid, Virtualized Application Type: Network Management, Device Configuration, Remote Monitoring, Security Setup End User: Telecom Providers, Enterprises, Managed Service Providers, Data Centers Technology: IPv6, SDN, AI-driven Solutions, Automation Tools |
| Companies Covered | Cisco Systems, Juniper Networks, Hewlett Packard Enterprise, Nokia Corporation, Telefonaktiebolaget LM Ericsson, Arista Networks, Extreme Networks, Dell Technologies, IBM, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Zero-Touch Provisioning Market Trends and Innovations
Intent-based networking architectures are rewriting how European carriers translate business policies into automated infrastructure configurations, compressing operational decision chains from days to seconds.
Certificate lifecycle automation is collapsing the traditional boundary between device onboarding and ongoing trust management. Deutsche Telekom and Vodafone are deploying automated PKI refresh mechanisms across their 5G radio access networks. This convergence eliminates manual re-provisioning events and reduces certificate-related outages by integrating renewal workflows directly into orchestration platforms.
The EU Cybersecurity Act's Common Criteria certification framework is mandating formal security evaluations for network equipment handling critical infrastructure traffic. ENISA is expanding its list of certified evaluation facilities to reduce backlog. Vendors targeting energy and transport verticals are prioritizing EAL4+ certification paths to satisfy national regulator procurement requirements.
Outcome-based network service contracts are displacing traditional equipment purchase models among mid-sized European enterprises. Managed service providers in France and the Netherlands now bundle zero-touch provisioning into per-site monthly fees. This shift transfers configuration risk to vendors while accelerating adoption among buyers lacking internal automation expertise.
Europe Zero-Touch Provisioning Market Segmentation
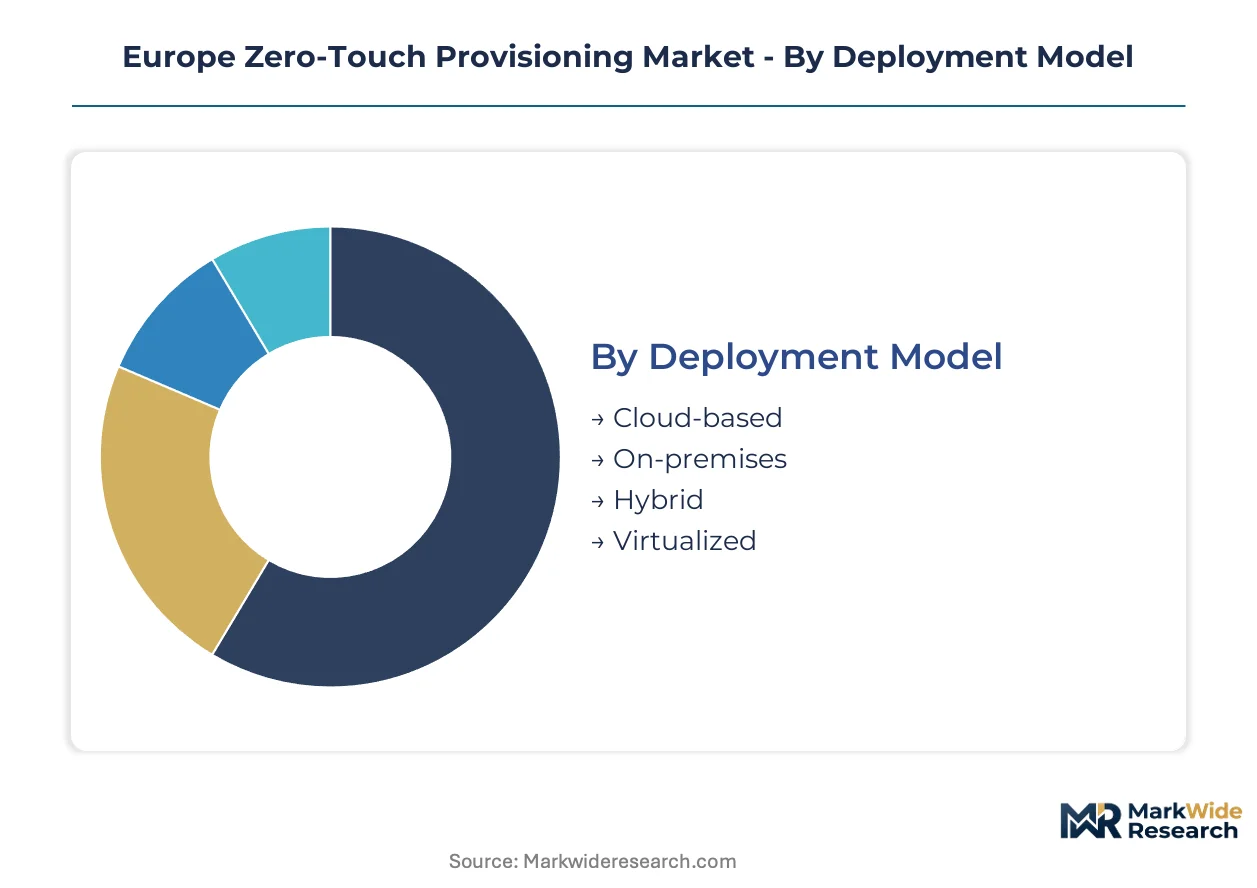
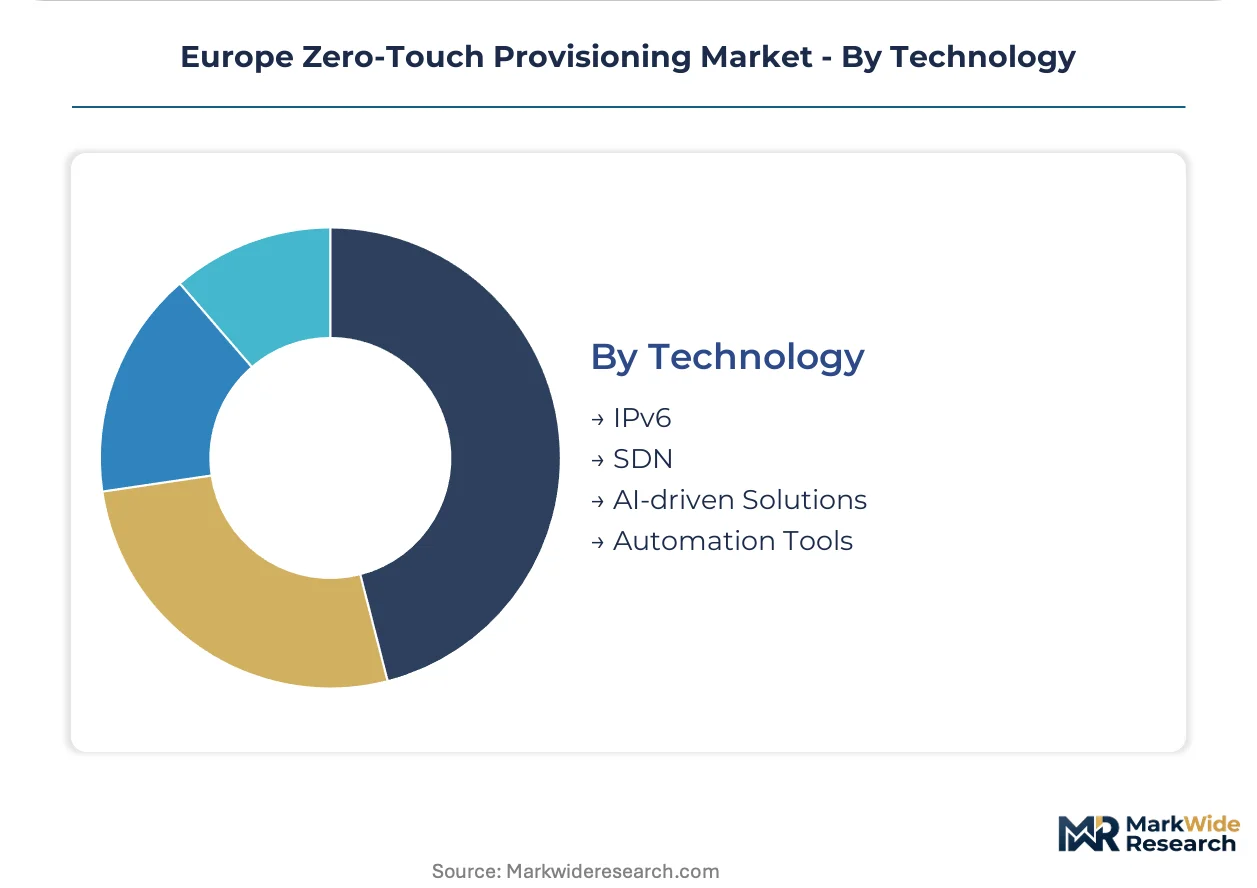
Zero-touch provisioning architectures vary sharply in refresh cadence and margin structure across deployment models and technology layers. Understanding segment turnover rates helps vendors calibrate R&D pipelines and service attach strategies for European telecom infrastructure.
Deployment Model:
Cloud-based deployments turn over fastest as operators swap orchestration layers quarterly, while on-premises installations persist for 5-7 year hardware cycles.
- Cloud-based:Multi-tenant SaaS orchestration platforms enable European carriers to provision network functions across distributed edge sites without capital-intensive infrastructure builds. Deutsche Telekom and Vodafone are consolidating vendor relationships around cloud-native stacks that auto-scale with traffic loads across German and British metro markets.
- On-premises:Dedicated controller hardware deployed inside carrier facilities satisfies data residency requirements under GDPR and national security frameworks. French and Italian operators favor this model for core network functions where latency constraints and sovereign data rules block public cloud extension.
- Hybrid:Split-plane architectures combining on-premises control with cloud analytics.
- Virtualized:Containerized network functions running on commodity compute.
On-premises anchors the volume base while cloud-based gains share at the steepest rate.
Application Type:
Cost tiers separate routine configuration automation from premium security orchestration with compliance certification overhead.
- Network Management:Intent-based controllers translate business policies into device-level configurations across multi-vendor radio access networks. Scandinavian operators are deploying these systems to automate 5G site commissioning across Norway and Sweden's challenging terrain.
- Security Setup:Automated certificate provisioning and trust anchor management satisfy EU Cybersecurity Act mandates for critical infrastructure. Energy and transport operators in the Netherlands and Belgium prioritize this application to achieve ENISA certification without manual PKI workflows.
- Device Configuration:Bootstrap protocols for IoT and enterprise endpoints.
- Remote Monitoring:Telemetry collection and anomaly detection during provisioning.
Network Management generates the largest revenue pool while Security Setup climbs the fastest as regulatory deadlines tighten.
End User:
Customer type determines contract structure, with telecom providers demanding outcome-based pricing and enterprises accepting perpetual licenses.
- Telecom Providers:Tier-1 and Tier-2 carriers across Germany, France, and the UK account for the majority of zero-touch procurement volume. These buyers require multi-vendor interoperability and API standardization to avoid single-supplier lock-in across their 5G and fiber access networks.
- Enterprises:Automotive manufacturers and chemical processors in Germany's industrial corridor are deploying private 5G networks with zero-touch provisioning for thousands of connected sensors. BMW and BASF have established automated deployment pipelines that reduce site activation from weeks to hours.
- Managed Service Providers:French and Dutch MSPs bundle provisioning into monthly per-site fees.
- Data Centers:Hyperscale facilities and colocation operators automating server rack deployment.
Telecom Providers anchor the volume base while Enterprises gain share at the steepest rate.
Technology:
Supply concentration varies by protocol maturity, with SDN controllers consolidating around three vendors while AI tooling fragments across dozens of specialists.
- AI-driven Solutions:Machine learning models embedded in orchestration platforms detect configuration anomalies and trigger self-healing workflows during device onboarding. These systems are expanding most quickly as operators seek to reduce mean-time-to-resolution for provisioning failures across distributed 5G infrastructure.
- SDN:Software-defined controllers separate control and data planes to enable centralized policy management across heterogeneous equipment. ETSI-standardized interfaces are helping European carriers avoid vendor-specific lock-in while maintaining telco-grade reliability requirements.
- IPv6:Next-generation addressing protocols enabling massive IoT scale.
- Automation Tools:Script-based and low-code workflow engines for legacy integration.
SDN anchors the volume base while AI-driven Solutions expands most quickly as inference moves to network edge points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment manufacturers export zero-touch provisioning systems to telecom operators across France, the UK, and the Netherlands, establishing a westward trade corridor that concentrates R&D investment in Central European industrial clusters.
Germany
Automotive manufacturers and chemical processors demand private 5G networks with automated sensor deployment across production sites. The EU Cybersecurity Act mandates automated security configuration for critical infrastructure operators. BMW and BASF operate automated deployment pipelines in Bavaria and Baden-Württemberg that compress site activation from weeks to hours.
United Kingdom
Vodafone and BT Group consolidate vendor relationships around cloud-native orchestration stacks for distributed edge sites. CE marking requirements under the Radio Equipment Directive constrain hardware-software integration pathways for IoT endpoints. London and Southeast England host managed service providers bundling zero-touch provisioning into per-site monthly fees.
France
Orange and Iliad favor on-premises deployment models for core network functions where data residency requirements under GDPR block public cloud extension. ENISA certification frameworks shape product development timelines for vendors targeting energy and transport verticals. The Paris-Saclay cluster concentrates R&D activity in intent-based networking controllers.
Netherlands
Energy and transport operators prioritize automated certificate provisioning to achieve ENISA certification without manual PKI workflows. The EU AI Act compresses vendor certification timelines for high-risk AI applications in network infrastructure. Rotterdam and Eindhoven host industrial corridors deploying private LTE networks with minimal existing automation infrastructure.
Poland
Central European manufacturing hubs seek zero-touch provisioning for brownfield industrial automation retrofits. The country's national cybersecurity regulator aligns with evolving ENISA guidance on automated security configuration. The Warsaw-Łódź corridor attracts private network deployments from automotive component suppliers expanding eastward from German supply chains.
Europe Zero-Touch Provisioning Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Tier-1 vendors supply multi-vendor orchestration platforms to Deutsche Telekom and Vodafone through direct enterprise sales forces. Tier-2 specialists target mid-sized carriers with Kubernetes-native controllers. Tier-3 regional integrators handle brownfield SNMP-to-automation mediation for industrial private networks. Consolidation pressures intensify as certificate lifecycle automation collapses boundaries between device onboarding and trust management.
Within the network infrastructure tier, Cisco Systems and Juniper Networks occupy positions as archetypal channel-controlling players with extensive R&D footprints across SDN controllers and intent-based networking. Nokia Corporation exemplifies the telco-grade cloud specialist archetype, anchoring competitive positioning through deep specialization in carrier-grade reliability requirements. These three vendors collectively represent the dominant competitive anchors as European operators accelerate zero-touch deployment roadmaps across 5G and private networks.
| Leading Market Players |
|---|
| Cisco Systems |
| Juniper Networks |
| Hewlett Packard Enterprise |
| Nokia Corporation |
| Telefonaktiebolaget LM Ericsson |
| Arista Networks |
| Extreme Networks |
| Dell Technologies |
| IBM |
| Others |
Pricing and Supply Chain Analysis
Munich's industrial automation cluster anchors European controller manufacturing capacity, concentrating R&D investment and specialized engineering talent. This geographic concentration grants incumbent vendors pricing leverage over mid-sized carriers seeking multi-vendor orchestration platforms, while cloud-native challengers erode that power through SaaS subscription models.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate hardware procurement for on-premises controllers, while cloud-based orchestration platforms operate on tiered SaaS subscriptions indexed to provisioned endpoint counts. Price differentiation hinges on EAL4+ Common Criteria certification grade and geographic delivery complexity across distributed edge sites. Pricing pressure stems from hyperscale cloud providers bundling basic provisioning tools into infrastructure-as-a-service offerings. Tier-2 carriers exhibit highest price sensitivity, whereas critical infrastructure operators in energy and transport prioritize certified security stacks over cost optimization.
Supply Chain Analysis
Supplier-financing facilities extended by Taiwanese and South Korean foundries help network equipment vendors manage working capital through extended 90-120 day payment terms. Manufacturing concentrates in Germany, Taiwan, and the United States for SDN controllers and specialized ASICs. Supply chains draw from advanced silicon wafers, precision optical components, and telco-grade power supplies. Single-source vulnerability in 7nm and 5nm fabrication creates exposure to geopolitical disruption. Distribution runs through direct enterprise sales forces for Tier-1 carriers and regional system integrators for industrial private networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification creates a regulatory inflection that favors vendors with pre-certified automated provisioning stacks. This compliance-driven disruption accelerates market consolidation as uncertified players face procurement exclusion from critical infrastructure verticals.
For Market Incumbents: Build certification moats through accelerated EAL4+ Common Criteria investment for core orchestration platforms. Acquire Kubernetes-native specialists to defend against cloud-native challengers eroding the mid-market. Prioritize backward integration into certificate lifecycle management to capture recurring revenue from automated PKI refresh workflows.
For New Entrants and Emerging Players: Poland's industrial corridor offers underpenetrated white-space for brownfield automation retrofits with minimal incumbent presence. Target managed service providers in France and the Netherlands with outcome-based pricing models that transfer configuration risk from end-users. Pursue ENISA certification pre-positioning to establish first-mover credibility before regulatory deadlines tighten.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-driven orchestration specialists with edge inference capabilities and established carrier relationships. Long-term viability rests on cloud-native architecture and regulatory certification depth rather than legacy protocol support. Watch for hyperscaler bundling strategies as the inflection signal indicating commoditization pressure on basic provisioning functions.
| Strategic Initiative | Industry Significance |
|---|---|
| ENISA Certification Pre-Positioning | Early alignment with evolving automated security guidance creates procurement advantage for critical infrastructure vendors. |
| Edge-AI Orchestration Integration | Machine learning inference at network edge points enables real-time anomaly detection during device onboarding sequences. |
| Certificate Lifecycle Automation | Automated PKI refresh mechanisms eliminate manual re-provisioning and reduce certificate-related outages across 5G infrastructure. |
| Hybrid Cloud-Native Expansion | Split-plane architectures combining on-premises control with cloud analytics satisfy GDPR data residency requirements. |
| Industrial Private Network Partnership | Collaboration with German automotive manufacturers accelerates zero-touch deployment across sensor-dense production sites. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with network architects at Tier-1 carriers, DevNetOps engineers at industrial enterprises, ENISA certification officers, and procurement leads at managed service providers; and secondary validation through ETSI technical specifications, EU Cybersecurity Act implementation guidance, SEC filings from publicly traded vendors, and carrier capex disclosure documents. Bottom-up endpoint deployment estimates triangulated against top-down infrastructure spending forecasts.
Forecast inputs considered deployment model adoption curves, technology maturation timelines, and regulatory compliance deadlines across the projection horizon. Segmentation dimensions modeled include deployment architecture, application type, end-user category, and technology layer. CAGRs derived from logistic diffusion curves fitted to historical provisioning automation penetration patterns. Industry-specific inputs encompassed 5G site commissioning velocity and ENISA certification queue processing rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers or rapid ENISA guidance expansion would shift outcomes. Macroeconomic contraction in European industrial investment, semiconductor supply disruption, or EU AI Act enforcement variance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Satellite Communication Terminal Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
Infiniband Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market
Telecom Hardware
5G Radio Unit Market
Telecom Hardware
Repeaters Market
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Industrial Transceivers Market
Telecom Hardware
DWDM Transceiver Market
Telecom Hardware
Land Mobile Radio System Market
Telecom Hardware
OTN Hardware Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
Room Cell Module Market
Telecom Hardware
Global Volte Market
Telecom Hardware
Point-To-Point Microwave Antenna Market
Telecom Hardware
Communication Base Station Equipment Pcb Market