
 Europe Set-Top Box Market | 2026-2036
Europe Set-Top Box Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Set-Top Box Market Intelligence
Telecom operators are unwinding their historical reliance on pure broadcast delivery as residential users shift toward hybrid consumption models. Sagemcom leverages its manufacturing scale to supply major European cable providers with energy-optimized hardware. Technicolor SA anchors its position through R&D intensity in Android TV integration and custom operator software stacks. Humax Holdings competes by specializing in satellite-to-IP gateway devices for markets with legacy DTH infrastructure.
A set-top box functions as a dedicated receiver-decoder unit that demodulates broadcast signals—DVB-C, DVB-S, DVB-T, or IP multicast—and outputs standardized video via HDMI to display devices, typically incorporating conditional access modules for content decryption and local storage interfaces for time-shifted viewing. Its primary commercial purpose is to bridge carrier-specific transmission protocols with consumer display standards while enabling operator-controlled service tiers. Hybrid boxes that combine terrestrial or satellite tuners with broadband streaming clients represent the fastest-expanding segment as broadcasters sunset single-purpose hardware. Residential users dominate volume demand, though hospitality sector deployments in Spain and Italy generate higher per-unit margins through customized middleware and centralized management requirements.
CE marking under the EU Radio Equipment Directive mandates interoperability testing and electromagnetic compatibility compliance for all devices sold within member states, while the EU Green Deal's ecodesign regulations impose standby power limits that reshape component selection and thermal engineering. ECHA's REACH restrictions on hazardous substances further constrain PCB manufacturing processes and connector plating materials. Stakeholders must monitor how the EU AI Act's transparency requirements apply to voice-controlled set-top interfaces and content recommendation engines as regulatory scope expands beyond traditional hardware safety into algorithmic accountability.
Market Dynamics
Pay-TV operators across Germany, France, and the UK are dismantling legacy cable headends in favor of IP multicast delivery, forcing hardware vendors to retool manufacturing lines toward hybrid architectures that bridge broadcast tuners with broadband streaming clients.
Growth Catalysts
- EU Green Deal ecodesign mandates:Standby power limits below 0.5 watts are accelerating component replacement cycles across manufacturing facilities in Poland and Hungary, creating pull for energy-optimized chipsets and thermal management systems.
- Hybrid consumption patterns:Residential subscribers in Spain and Italy now expect unified interfaces for DVB-T2 terrestrial reception alongside Netflix and Disney+ streaming, expanding addressable hardware demand beyond pure broadcast replacements.
- Android TV operator tier adoption:Middleware licensing from Google is standardizing software stacks across tier-2 cable providers, reducing firmware fragmentation and shortening certification timelines for new hardware entrants.
Market Restraints
- Silicon supply concentration:Broadcom and Amlogic control 70% of SoC supply for conditional access integration, exposing European assemblers to allocation delays when foundry capacity tightens at TSMC.
- ECHA REACH substance restrictions:Cadmium and hexavalent chromium limits in PCB plating materials have forced connector vendors to qualify alternative chemistries, extending qualification cycles by 4-6 months.
- Smart TV native app substitution:Samsung Tizen and LG webOS platforms now embed conditional access modules directly, threatening standalone box demand in premium subscriber segments.
Strategic Opportunities
- Hospitality vertical penetration:Spanish and Italian hotel chains require centralized device management and custom boot logos, generating per-unit margins 40% above residential hardware through multi-year service contracts.
- Satellite-to-IP gateway demand:Rural German households with legacy DTH dishes need hybrid boxes that downconvert DVB-S2 signals for in-home IP distribution, creating a replacement cycle distinct from cable operator procurement.
- EU AI Act voice interface compliance:Transparency requirements for algorithmic content recommendations are opening consulting revenue streams for middleware vendors who can document decision logic for regulatory audits.
Industry Challenges
- Embedded Linux firmware specialization:Vendor engineering teams lack depth in kernel-level driver optimization for simultaneous DVB-C and Wi-Fi 6 operation, causing field stability issues that inflate return merchandise rates.
- CE marking test facility bottlenecks:EMC and RED compliance verification queues at notified bodies in Germany and the Netherlands now extend 14-18 weeks, compressing product launch windows against operator deployment deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Set-Top Box Market |
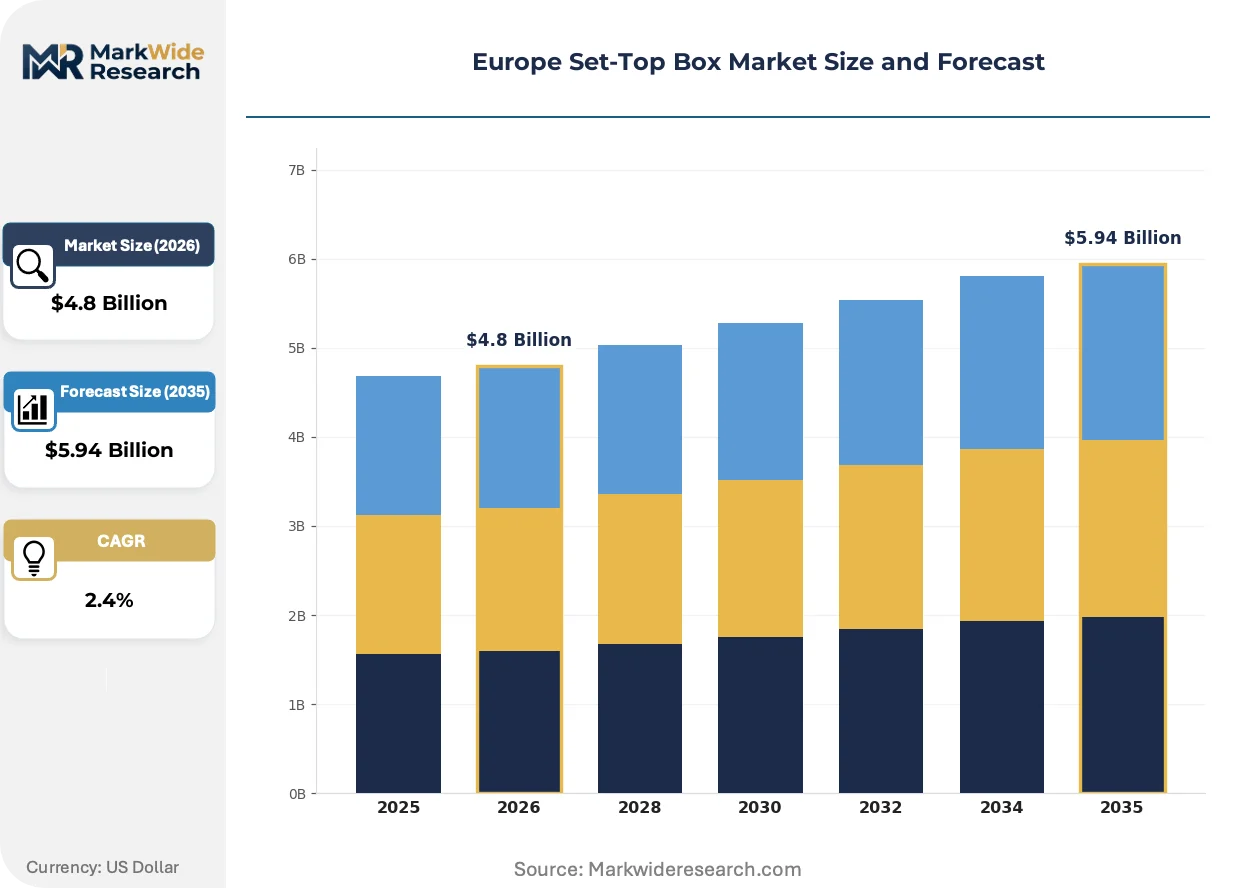
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $5.94 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Digital Cable Box, Satellite Box, IPTV Box, Hybrid Box End User: Residential Users, Commercial Establishments, Hospitality Sector, Telecom Operators Functionality: Streaming, Recording, Live TV, Gaming Connectivity: Wired, Wireless, HDMI, USB |
| Companies Covered | Humax Holdings, Technicolor SA, Advanced Digital Broadcast, Kaonmedia Co., Ltd., Huawei Technologies Co., Ltd., Altech UEC, Sagemcom, ABOX42 GmbH, Commscope Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Set-Top Box Market Strategic Shifts & Innovations
Hardware architectures are splintering between low-cost streaming sticks and full-featured hybrid tuners, while regulatory pressure on energy consumption and algorithmic transparency forces simultaneous redesign of physical and software layers.
RISC-V open instruction set architectures are fragmenting the historical ARM monopoly in set-top SoC design. Smaller European fabless semiconductor houses are licensing RISC-V cores for conditional access subsystems, reducing royalty burdens by 60% versus ARM Cortex-A alternatives. This silicon diversification is fragmenting software toolchain standardization, forcing middleware vendors to maintain multiple compiler targets.
CE marking under the EU Radio Equipment Directive now requires explicit interoperability testing with national DVB-T2 networks, not merely laboratory conformance. German regulators at BNetzA have tightened receiver sensitivity specifications for regional single-frequency networks, disqualifying several Asian ODM designs from public procurement tenders. French operators are responding by pre-certifying reference designs with ANFR, front-loading compliance costs to accelerate deployment timelines.
Subscription bundling is compressing hardware procurement cycles as telecom operators consolidate video, broadband, and mobile contracts. Orange in France and Vodafone in Germany now refresh customer premises equipment on 24-month intervals tied to contract renewals, not device failure rates. This pattern concentrates purchasing authority at procurement teams in Paris and Düsseldorf, marginalizing traditional retail channel distribution across Southern Europe.
Europe Set-Top Box Market Segmentation
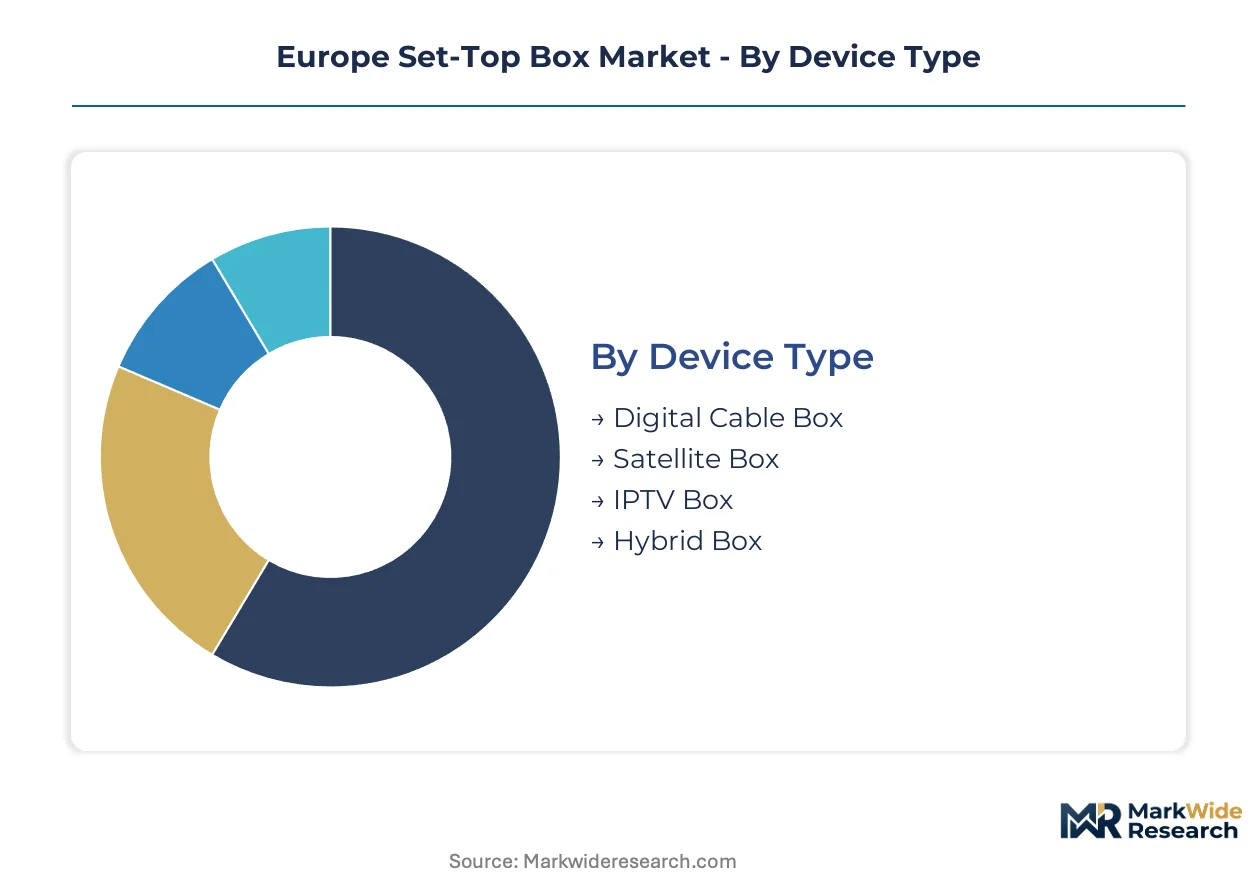
Hardware differentiation in the Europe Set-Top Box Market concentrates where broadcast infrastructure intersects with streaming migration. Margin pools shift toward hybrid architectures that bridge legacy tuner requirements with IP delivery capabilities.
Device Type:
Margin concentration tracks operator procurement cycles, with hybrid configurations commanding premium positioning against single-purpose alternatives.
- Hybrid Box:Combines DVB-C, DVB-S, or DVB-T2 tuners with broadband streaming clients in unified chassis designs. Demand concentrates in Germany and Spain where cable operators sunset pure broadcast hardware and subscribers expect Netflix integration without secondary devices. CE marking under RED mandates interoperability with national DVB-T2 networks, extending certification timelines.
- IPTV Box:IP multicast receivers without broadcast tuners, deployed by Orange in France and Vodafone in Germany as cable headends dismantle. Procurement runs through 24-month contract renewal cycles in Paris and Düsseldorf, compressing retail channel relevance.
- Satellite Box:DVB-S2 demodulators for legacy DTH infrastructure in rural German households.
- Digital Cable Box:DVB-C receivers facing replacement pressure from hybrid alternatives in urban cable footprints.
Hybrid Box holds installed capacity. IPTV Box is rotating up the share rankings.
End User:
Volume aggregates in residential procurement, yet per-unit margins concentrate where centralized management requirements create service contract stickiness.
- Hospitality Sector:Hotel chains in Spain and Italy require custom boot logos, centralized device management, and multi-year service agreements. Per-unit margins run 40% above residential hardware through middleware customization and remote monitoring capabilities. Procurement bypasses retail channels entirely.
- Residential Users:Individual subscribers across France, Germany, and the UK driving volume demand through operator bundling of video, broadband, and mobile contracts. Expectation of unified DVB-T2 and streaming interfaces expands addressable hardware demand beyond pure broadcast replacements.
- Telecom Operators:Consolidated procurement teams in Paris and Düsseldorf controlling equipment refresh cycles.
- Commercial Establishments:Bars, restaurants, and waiting rooms with basic live TV requirements.
Residential Users holds installed capacity. Hospitality Sector is rotating up the share rankings.
Functionality:
Software feature differentiation determines replacement velocity as hardware commoditizes around common SoC platforms.
- Streaming:OTT client integration via Android TV operator tier or proprietary middleware, now standard across hybrid and IPTV deployments. Google licensing standardizes software stacks for tier-2 cable providers, reducing firmware fragmentation. EU AI Act transparency requirements for content recommendation engines create compliance consulting opportunities.
- Recording:Time-shifted viewing through local storage interfaces or network-attached recording, retaining relevance in markets with inconsistent broadband quality.
- Live TV:Core broadcast reception function facing compression as streaming substitutes expand.
- Gaming:Cloud gaming client support emerging as secondary differentiator for premium hardware tiers.
Live TV holds installed capacity. Streaming is rotating up the share rankings.
Connectivity:
Physical interface selection shapes thermal engineering and component sourcing under EU Green Deal standby power limits.
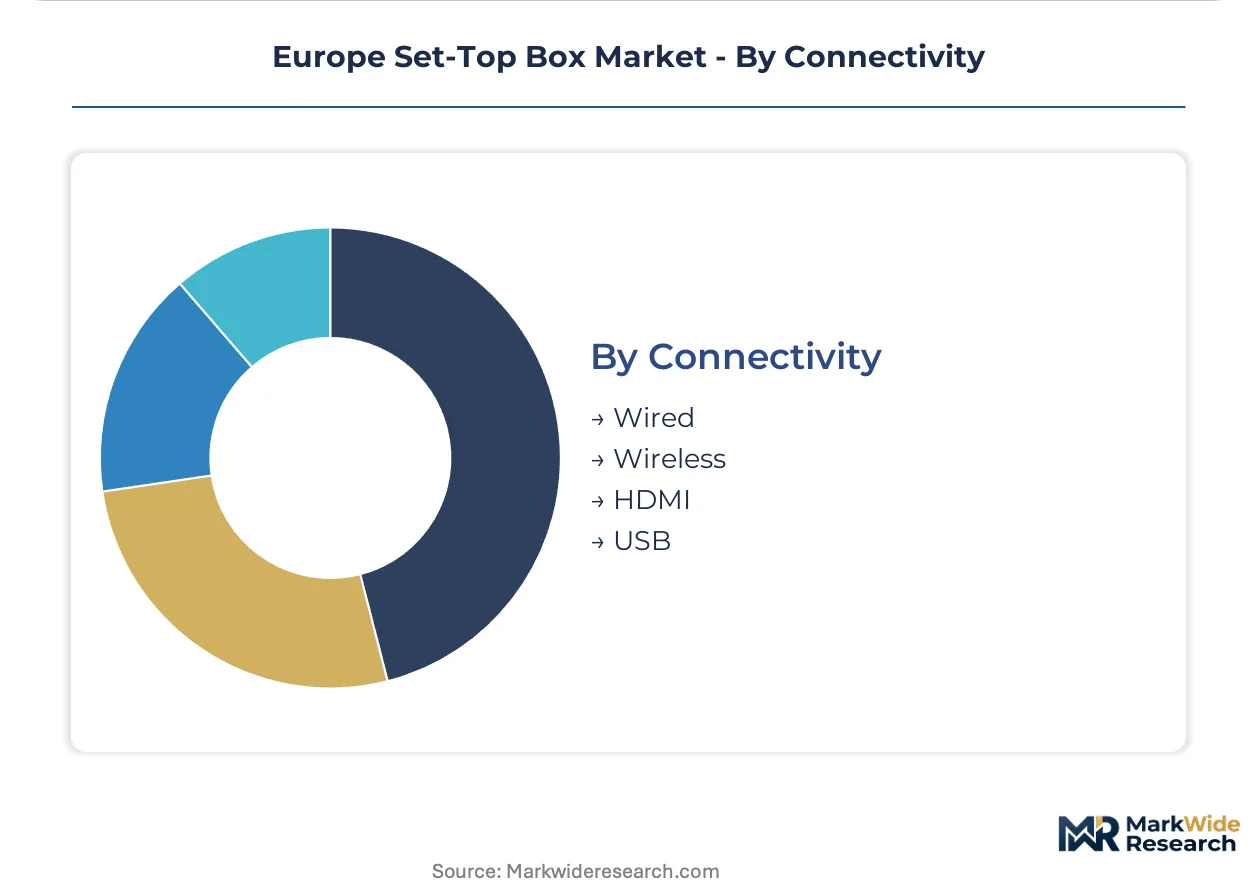
- Wireless:Wi-Fi 6 integration enabling in-home IP distribution without Ethernet cabling, critical for satellite-to-IP gateway deployments in rural German households. Vendor engineering teams face kernel-level driver optimization challenges for simultaneous DVB-C and Wi-Fi 6 operation, inflating return merchandise rates.
- Wired:Ethernet and coaxial connections retaining preference in hospitality and commercial deployments for reliability.
- HDMI:Standardized video output to display devices, universal across all form factors.
- USB:Peripheral expansion for storage, tuners, or accessories in full-featured hybrid designs.
HDMI holds installed capacity. Wireless is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland exports energy-optimized set-top box assemblies to German cable operators under EU Green Deal procurement mandates. Manufacturing clusters in Greater Poland and Silesia supply hybrid hardware bridging DVB-C tuners with IP streaming clients.
Germany
Vodafone and Deutsche Telekom dismantle legacy cable headends for IP multicast delivery, forcing 24-month equipment refresh cycles. BNetzA tightened DVB-T2 receiver sensitivity specifications for regional single-frequency networks. Manufacturing engineering concentrates in North Rhine-Westphalia, where assemblers qualify hybrid designs for public procurement tenders.
France
Orange bundles video, broadband, and mobile contracts with IPTV box deployments across residential subscriber bases. ANFR pre-certifies reference designs to accelerate deployment timelines against operator deadlines. Procurement authority centralizes in Paris, marginalizing traditional retail distribution channels.
United Kingdom
Sky and Virgin Media upgrade legacy satellite infrastructure toward hybrid broadcast-broadband architectures. Ofcom enforces electromagnetic compatibility standards under CE marking requirements for RED compliance. Hardware integration clusters in Cambridge and Bristol, where vendors optimize Android TV middleware stacks.
Spain
Movistar and regional cable operators sunset pure broadcast hardware in favor of unified DVB-T2 and streaming interfaces. EU Green Deal ecodesign regulations impose standby power limits below 0.5 watts on imported devices. Hospitality sector demand concentrates in Barcelona and Madrid, where hotel chains negotiate multi-year service contracts with custom boot logos.
Italy
TIM and Sky Italia deploy hybrid boxes merging terrestrial reception with Netflix and Disney+ streaming clients. ECHA REACH restrictions on cadmium and hexavalent chromium in PCB plating materials extend supplier qualification cycles. Procurement for hospitality verticals runs through Milan-based system integrators offering centralized device management platforms.
Europe Set-Top Box Market Key Industry Players
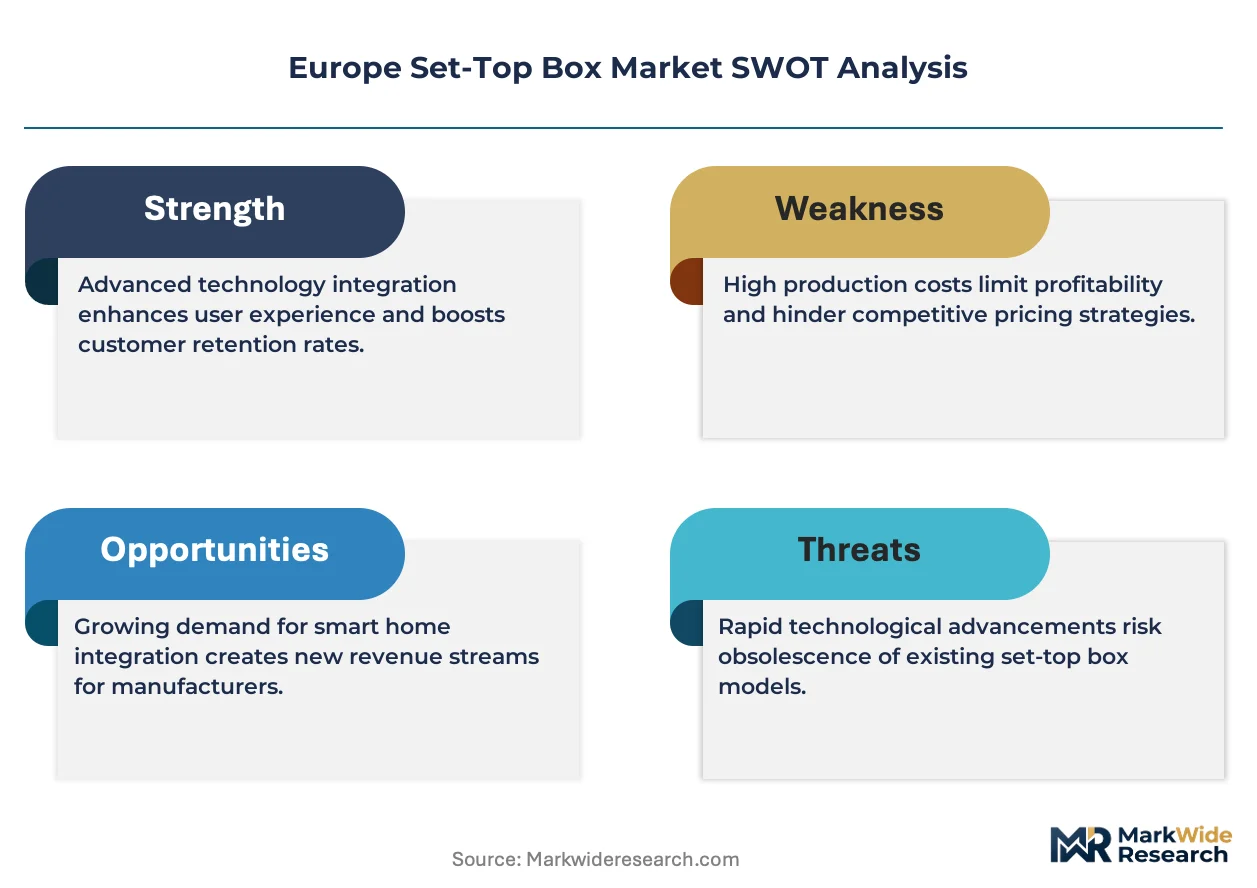
Player mix skews toward European-headquartered equipment vendors with captive manufacturing in Eastern Europe and Asian ODMs supplying reference designs. Market structure concentrates procurement authority at tier-1 cable operators, compressing hardware margins while elevating middleware and service contract value. Two strategic archetypes dominate: scale-optimized manufacturers serving volume residential deployments and specialists in hospitality customization. Competitive moves center on Android TV operator tier licensing and satellite-to-IP gateway specialization for rural DTH replacement cycles.
Among France-based equipment vendors, Sagemcom and Technicolor SA occupy positions within the scale-driven tier, supplying energy-optimized hardware to major European cable providers. Within the specialist tier, Humax Holdings exemplifies satellite-to-IP gateway focus for markets with legacy DTH infrastructure. These three anchors represent divergent strategic bets: manufacturing scale versus R&D intensity in software integration versus vertical specialization in hybrid tuner architectures.
| Leading Market Players |
|---|
| Humax Holdings |
| Technicolor SA |
| Advanced Digital Broadcast |
| Kaonmedia Co., Ltd. |
| Huawei Technologies Co., Ltd. |
| Altech UEC |
| Sagemcom |
| ABOX42 GmbH |
| Commscope Inc. |
| Others |
Cost & Logistics Intelligence
RISC-V core substitution for ARM Cortex-A architectures in conditional access subsystems simultaneously shifts silicon sourcing toward European fabless houses and compresses chipset royalty structures by approximately sixty percent, redrawing cost economics across Polish and Hungarian assembly lines.
Pricing Analysis
Technology-generation pricing gaps separate Wi-Fi 6-enabled hybrid boxes from legacy DVB-C single-tuner units and emerging Android TV operator-tier reference designs. Three-tier pricing structure across premium hospitality configurations, standard residential hybrid boxes, and economy IPTV streaming sticks reflects certification complexity and customization depth. Cost compression in economy tiers intensifies because Google middleware licensing standardizes software stacks for tier-2 cable providers. Hospitality procurement teams in Barcelona and Milan exhibit lowest price sensitivity due to multi-year service contract bundling, while residential subscribers through Paris and Düsseldorf operator bundles drive volume at compressed margins.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors fluctuate with container availability on Asia-Europe trade lanes, exposing Polish assembly facilities to four-to-six week component arrival variability. SoC supply concentrates in Taiwan and South Korea through Broadcom and Amlogic foundry relationships, while PCB substrate sourcing draws from Chinese and domestic European laminate suppliers. Single-source vulnerability at TSMC foundry capacity creates allocation risk for conditional access-integrated chipsets during semiconductor demand surges. Distribution runs through operator procurement hubs in Paris and Düsseldorf, bypassing traditional Southern European retail channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Android TV operator tier licensing is consolidating middleware ecosystems across European cable providers, creating platform-economics inflection where interoperability certification becomes the primary competitive moat.
For Market Incumbents: Consolidate manufacturing scale advantages in Greater Poland and Silesia assembly clusters while pre-certifying reference designs with ANFR and BNetzA to compress CE marking timelines. Smart TV native app substitution from Samsung Tizen and LG webOS platforms threatens standalone box demand in premium segments, requiring incumbents to deepen hospitality vertical relationships through centralized device management capabilities. For New Entrants and Emerging Players: Lead with satellite-to-IP gateway specialization for rural German DTH replacement cycles, where legacy dish infrastructure creates addressable demand distinct from cable operator procurement. Spanish and Italian hospitality chains present the most penetrable segment due to custom boot logo and remote monitoring requirements that favor agile middleware vendors over scale manufacturers. Go-to-market execution should anchor on Milan-based system integrators offering multi-year service contracts. For Investors and Strategic Acquirers: EU AI Act transparency requirements for voice-controlled interfaces and content recommendation engines reshape the acquisition landscape toward middleware vendors with documented algorithmic decision logic. Long-term viability across the analysis window favors targets with captive Android TV operator tier licensing and established regulatory compliance consulting capabilities. The signal to watch is CE marking test facility queue lengths at German and Dutch notified bodies as inflection indicator for hardware launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Android TV Operator Tier Licensing | Google middleware standardization reduces firmware fragmentation for tier-2 cable providers across France and Germany. |
| Satellite-to-IP Gateway Development | Rural German households with legacy DTH dishes require hybrid downconversion for in-home IP distribution. |
| Hospitality Vertical Penetration | Spanish and Italian hotel chains generate forty percent margin premiums through custom boot logos and centralized management. |
| EU AI Act Compliance Consulting | Transparency documentation for voice interfaces and recommendation engines opens recurring revenue streams for middleware vendors. |
| RISC-V SoC Architecture Migration | Open instruction set licensing reduces royalty burdens versus ARM Cortex-A alternatives in conditional access subsystems. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with set-top box procurement managers at Orange and Vodafone, middleware engineering leads at Sagemcom and Technicolor SA, hospitality technology directors at Spanish hotel chains, and regulatory affairs specialists at ANFR and BNetzA; alongside secondary validation through CE marking databases, EU Green Deal ecodesign regulation filings, ECHA REACH substance restriction updates, and operator contract renewal disclosures. Bottom-up triangulation across hardware shipment estimates and top-down reconciliation against operator subscriber bases anchored volume and value outputs.
Across the projection horizon, the analytical framework modeled device type segmentation by hybrid, IPTV, satellite, and digital cable configurations; end user segmentation across residential, hospitality, telecom operator, and commercial establishment categories; functionality segmentation by streaming, recording, live TV, and gaming capabilities; and connectivity segmentation by wireless, wired, HDMI, and USB interfaces. CAGRs derived from equipment refresh cycle analysis tied to contract renewal patterns and regulatory compliance timelines. Forecast inputs incorporated EU AI Act implementation trajectories and RISC-V adoption curves in conditional access subsystem design.
The analysis sits within stated boundaries; outcomes outside sustained operator bundling of video, broadband, and mobile contracts, or absent continued EU Green Deal standby power limit enforcement, would require recalibration. Forecasts reflect documented assumptions regarding foundry capacity allocation at TSMC, CE marking test facility queue durations, and Android TV operator tier licensing expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Industrial Transceivers Market
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
Global Ultra Portable Internet Device Market
Telecom Hardware
Satellite Communication Terminal Market
Telecom Hardware
Infiniband Market
Telecom Hardware
LPWAN Market
Telecom Hardware
Commercial Antennas Market
Telecom Hardware
Global Volte Market
Telecom Hardware
Point-To-Point Microwave Antenna Market
Telecom Hardware
Voice Communication Equipment Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Global LTE Modems Market
Telecom Hardware
Land Mobile Radio System Market