
 Base Station Market | 2026-2036
Base Station Market Size, Share, and Industry Trends Forecast 2026-2036
Base Station Market Outlook
Aftermarket service revenue is fragmenting across hardware vendors and third-party maintenance providers as 5G rollouts strain legacy support models. Huawei Technologies leverages its integrated chipset-to-antenna stack to capture lifecycle service contracts in emerging markets. Ericsson anchors European operator relationships through its intelligent automation platforms for network optimization. Samsung Electronics competes aggressively in North American Open RAN deployments with its vRAN software portfolio.
A base station constitutes a fixed radio transceiver that interfaces wireless user equipment with core network infrastructure, typically operating across sub-6 GHz and millimeter-wave spectrum bands with output powers ranging from milliwatts in femtocells to hundreds of watts in macro installations. Macro base stations command the largest installed base but face margin compression as operators prioritize dense urban capacity layers. Micro base stations and 5G NR deployments represent the fastest-expanding product-technology intersection, driven by indoor enterprise coverage requirements and smart city backhaul needs. Cloud-based deployment models are gaining traction among network providers seeking elastic capacity scaling without dedicated on-premise hardware.
The FCC governs spectrum allocation and equipment authorization in the United States, directly shaping vendor product roadmaps through auction timing and technical rules. ETSI and 3GPP standards frameworks in Europe mandate interoperability benchmarks that determine market access for non-integrated suppliers. China's MIIT enforces domestic 5G acceleration timelines through spectrum licensing and infrastructure investment targets. Stakeholders must monitor evolving Open RAN certification requirements and national security review regimes that could reshape supplier eligibility across major deployment markets.
Market Dynamics
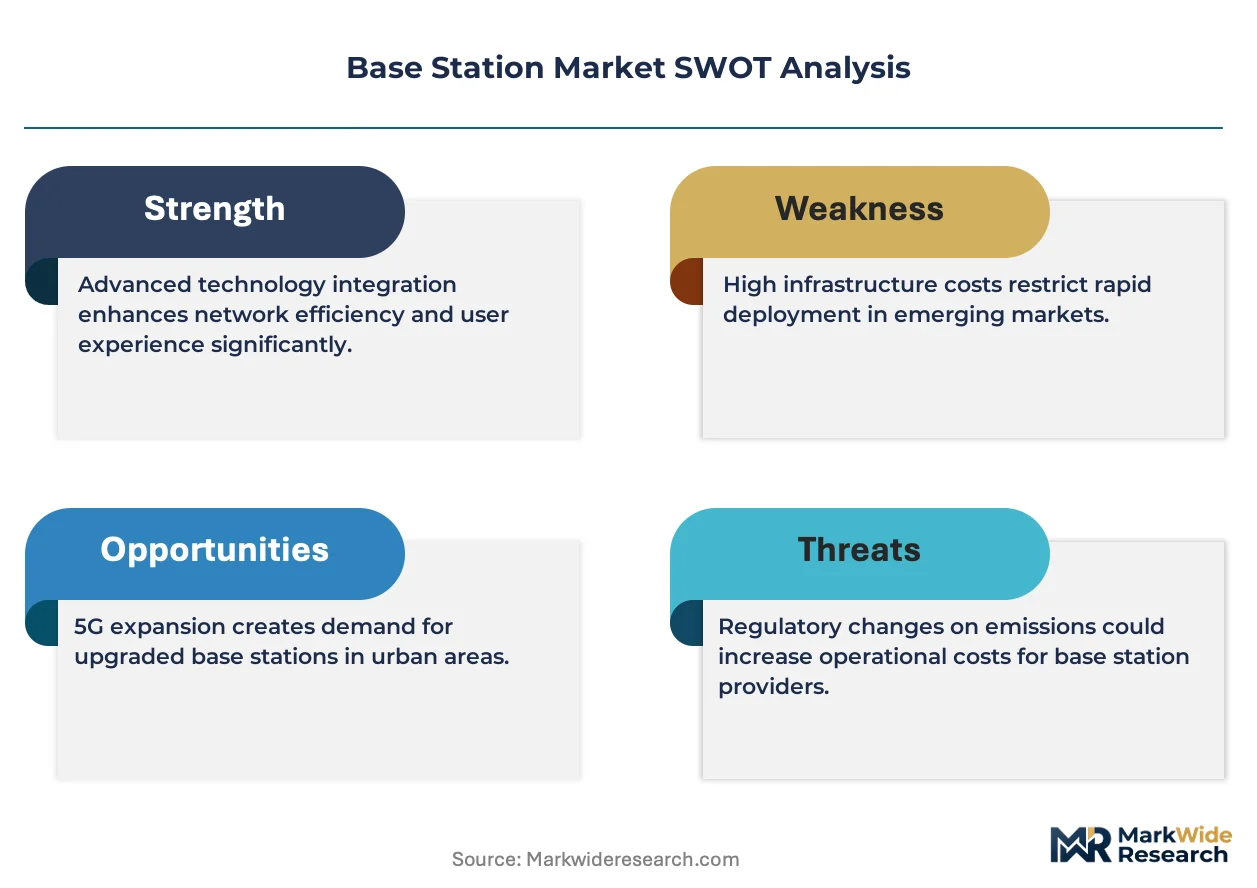
Massive MIMO deployment density in China's urban corridors is compressing unit economics while forcing vendors to reconfigure supply chains for sub-6 GHz and millimeter-wave hardware simultaneously.
Growth Catalysts
- Open RAN architecture mandates:The FCC's spectrum auction frameworks in the United States are accelerating disaggregated radio access network deployments that favor multi-vendor interoperability.
- Smart city backhaul requirements:Municipal governments across South Korea are procuring micro base stations to support connected traffic management and public safety networks.
- Millimeter-wave spectrum liberalization:Japan's METI has allocated high-band frequencies for private 5G networks, enabling industrial automation deployments in manufacturing zones.
Market Restraints
- GaN-on-SiC substrate concentration:Advanced power amplifier substrates depend on a concentrated supply base in East Asian foundries, exposing lead times to geopolitical friction.
- Site acquisition costs:Urban zoning restrictions in European metropolitan areas inflate deployment expenses for macro cell towers beyond rural benchmarks.
- Legacy 4G infrastructure lock-in:Operators carrying substantial LTE equipment depreciation resist accelerated replacement cycles despite 5G capacity advantages.
Strategic Opportunities
- Enterprise private networks:Germany's Industrie 4.0 policy framework incentivizes factory-floor 5G deployments that bypass public operator infrastructure.
- Cloud-native RAN orchestration:Containerized baseband function virtualization enables edge computing convergence with enterprise IT workloads.
- Rural coverage obligations:India's TRAI universal service mandates create subsidized demand pockets for low-power rural base station configurations.
Industry Challenges
- RF engineer scarcity:Millimeter-wave beamforming expertise concentrates among semiconductor designers in Taiwan and South Korea, constraining deployment velocity elsewhere.
- Multi-band integration complexity:Concurrent sub-6 GHz and mmWave operation demands thermal management solutions that extend certification timelines.
- Interoperability testing overhead:Open RAN fronthaul conformance verification against O-RAN Alliance specifications adds engineering resource requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Base Station Market |
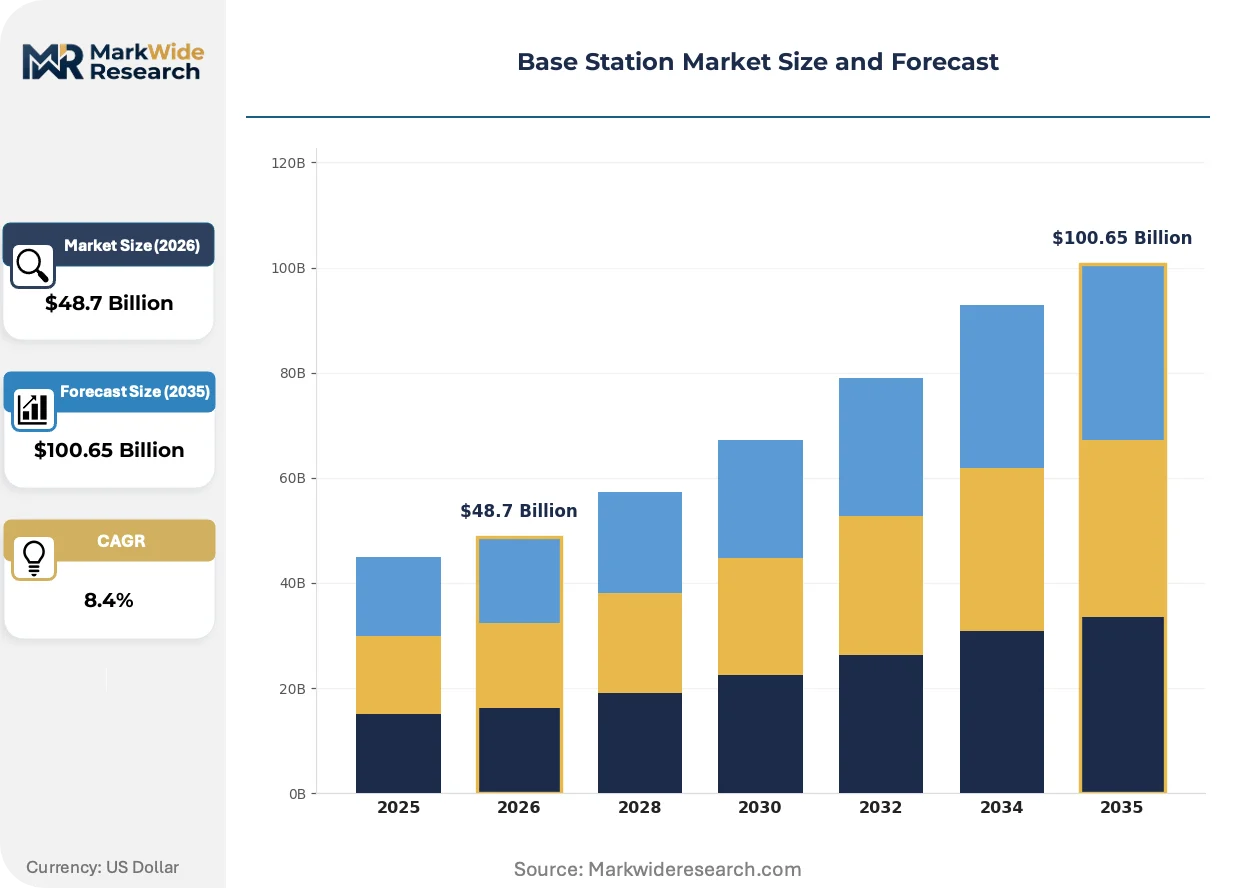
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Macro Base Stations, Micro Base Stations, Pico Base Stations, Femtocells Technology: 4G LTE, 5G NR, Wi-Fi, Satellite Communication End User: Telecom Operators, Enterprises, Government, Network Providers Deployment Model: On-Premise, Cloud-Based, Hybrid, Distributed |
| Companies Covered | Huawei Technologies, Ericsson, Nokia Corporation, ZTE Corporation, Samsung Electronics, CommScope Holding Company, Qualcomm Technologies, NEC Corporation, Airspan Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Base Station Market Strategic Shifts
Active antenna system architecture is redefining vendor competitive boundaries as digital beamforming displaces analog radio frequency chains and compresses hardware footprints.
Massive MIMO radio units are migrating from 64T64R configurations toward 128T128R and 256T256R arrays in dense urban corridors. Chinese mobile network operators are deploying these ultra-dense arrays in Shanghai and Beijing metro zones to manage stadium and transit hub capacity spikes. This density escalation is compressing per-gigabyte delivery costs while elevating power consumption and thermal design requirements for outdoor enclosures.
The FCC's equipment authorization rules for 6 GHz unlicensed operation are creating secondary spectrum access opportunities for neutral host deployments. Campus and venue operators in the United States are exploiting this framework to deploy private 5G without exclusive spectrum licenses. Indoor enterprise coverage segments are responding with small cell configurations that bypass traditional macro network dependency.
Network-as-a-service procurement models are displacing capital-intensive ownership structures among mid-tier mobile operators. European and Southeast Asian carriers are contracting managed infrastructure services that transfer base station lifecycle responsibility to vendor-managed entities. This arrangement concentrates most visibly in the United Kingdom and Indonesia where operators prioritize balance sheet flexibility over asset control.
Base Station Market Segmentation

Base station procurement patterns diverge sharply across deployment scales, spectrum technologies, and operational ownership models. Each segmentation axis captures distinct margin structures, certification requirements, and vendor competitive dynamics that shape supplier strategy.
Product Type:
Macro installations anchor carrier-grade coverage while compact form factors penetrate indoor enterprise and residential zones.
- Macro Base Stations:High-power outdoor installations spanning hundreds of watts with integrated antenna arrays for wide-area coverage. Mobile network operators in China and the United States concentrate procurement here for suburban and rural footprint expansion, though margin compression intensifies as capacity layers shift toward densification.
- Micro Base Stations:Mid-range output devices designed for urban infill and stadium deployments where macro signals degrade. South Korean smart city initiatives and German industrial zones are driving concentrated demand for these units as backhaul for connected traffic and automation systems.
- Pico Base Stations:Low-power indoor solutions for enterprise campuses and retail venues requiring localized capacity injection.
- Femtocells:Residential-grade consumer devices operating at milliwatt outputs for home coverage extension.
The dominant share belongs to Macro Base Stations, while Micro Base Stations are closing the gap fastest.
Technology:
Radio access generations stratify investment cycles, with newer standards commanding premium pricing and legacy equipment facing accelerated depreciation.
- 5G NR:New Radio specifications spanning sub-6 GHz and millimeter-wave bands with massive MIMO beamforming capabilities. FCC auction frameworks in the United States and MIIT licensing timelines in China are compressing deployment windows for this technology across dense urban corridors.
- 4G LTE:Mature FDD and TDD standards carrying substantial installed base depreciation. Operators in India and Southeast Asia extend LTE refresh cycles where 5G spectrum remains unallocated or device penetration lags.
- Wi-Fi:Unlicensed spectrum offload for indoor enterprise and residential convergence with cellular networks.
- Satellite Communication:Non-terrestrial backhaul for remote coverage and disaster recovery scenarios.
5G NR captures the steepest expansion trajectory as spectrum liberalization accelerates across major deployment markets.
End User:
Procurement authority splits between public network operators and private infrastructure owners with diverging technical specifications.
- Telecom Operators:Licensed spectrum holders deploying macro and micro infrastructure for consumer and enterprise service resale. These entities dominate volume procurement in China, the United States, and Japan where subscriber density justifies capital-intensive network builds.
- Enterprises:Manufacturing, logistics, and campus operators acquiring private 5G networks under localized spectrum frameworks. Germany's Industrie 4.0 policy and Japan's METI private 5G allocations are concentrating demand here for factory-floor automation.
- Government:Public safety and defense agencies procuring hardened infrastructure for secure communications.
- Network Providers:Neutral host operators deploying shared infrastructure for multiple tenant access.
Telecom Operators retain volume leadership, though Enterprise procurement is expanding most quickly as private network frameworks mature.
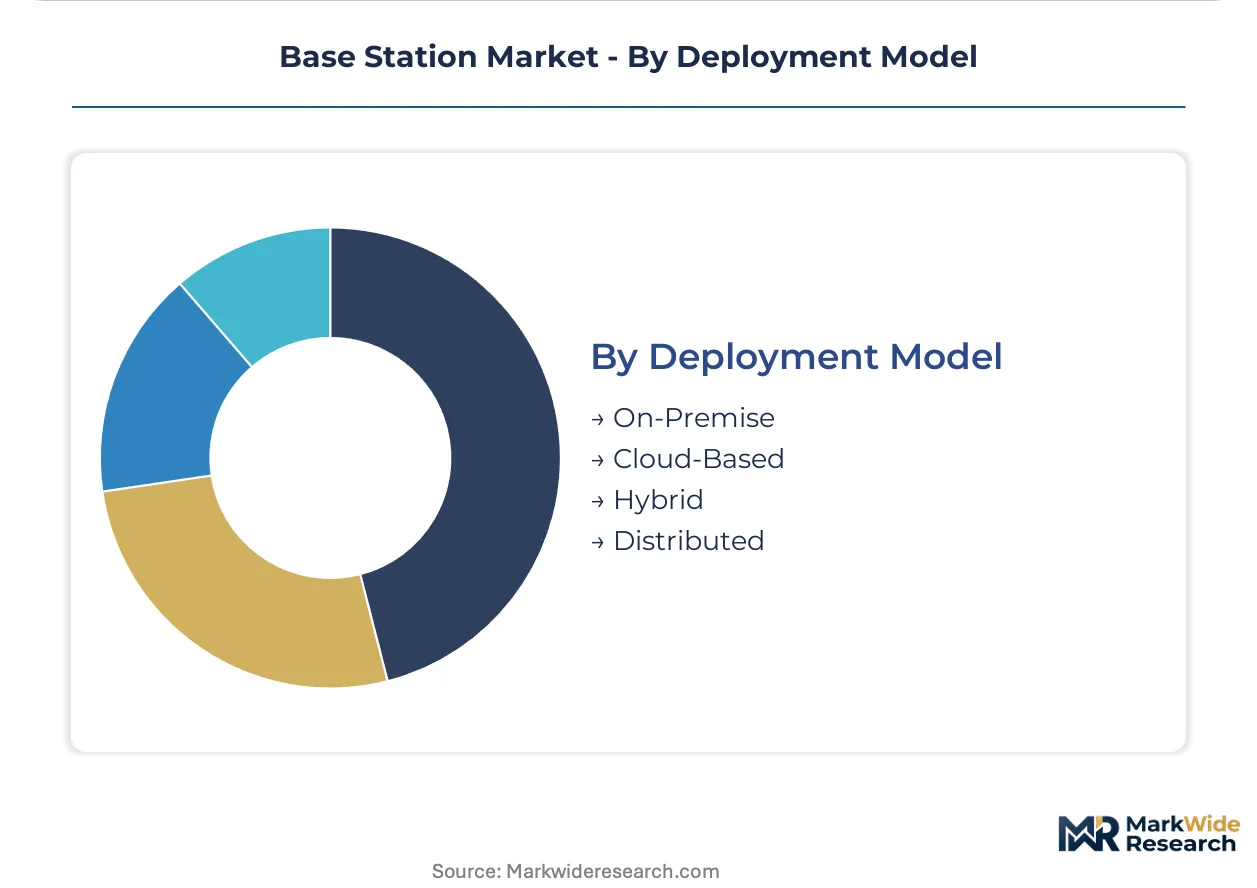
Deployment Model:
Infrastructure ownership economics are shifting from capital-heavy balance sheet models toward elastic service contracts.
- Cloud-Based:Containerized baseband function virtualization with centralized orchestration and edge computing convergence. European and Southeast Asian carriers in the United Kingdom and Indonesia are contracting managed infrastructure services that transfer lifecycle responsibility to vendors.
- On-Premise:Traditional dedicated hardware ownership with full operator control over physical infrastructure and maintenance scheduling.
- Hybrid:Split architectures combining centralized cloud processing with localized radio unit deployment for latency-sensitive applications.
- Distributed:Disaggregated Open RAN configurations with multi-vendor interoperability across radio, transport, and core layers.
On-Premise deployments still dominate installed base, yet Cloud-Based models are gaining share fastest among mid-tier operators prioritizing balance sheet flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across deployment markets. Operators in South Korea and Japan absorb premium pricing for millimeter-wave infrastructure, while Indian carriers prioritize low-power rural configurations under subsidy frameworks.
United States
FCC spectrum auctions are compressing 5G NR deployment windows across dense urban corridors. The regulator's equipment authorization rules for 6 GHz unlicensed operation enable private network deployments without exclusive licenses. Campus operators in Texas and California are exploiting this framework for neutral host infrastructure.
China
MIIT licensing timelines are accelerating massive MIMO installations in Shanghai and Beijing metro zones. The ministry enforces domestic 5G acceleration through spectrum allocation and infrastructure investment targets. Ultra-dense 128T128R and 256T256R arrays dominate new deployments in these urban corridors.
South Korea
Smart city backhaul requirements are driving concentrated micro base station procurement for connected traffic management. Municipal governments in Seoul and Busan are procuring these units under public safety network mandates. Mobile network operators simultaneously expand 5G NR infrastructure across the Seoul Capital Area.
Germany
Industrie 4.0 policy frameworks incentivize factory-floor 5G deployments that bypass public operator infrastructure. The country's national telecommunications regulator allocates localized spectrum for private industrial automation. Manufacturing clusters in Bavaria and North Rhine-Westphalia anchor enterprise network procurement.
India
TRAI universal service mandates create subsidized demand pockets for low-power rural base station configurations. Operators extend LTE refresh cycles where 5G spectrum remains unallocated. Deployment concentrates in Maharashtra and Gujarat where subscriber density justifies incremental infrastructure investment.
Base Station Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around integrated chipset-to-antenna stacks versus disaggregated Open RAN specialists. Three archetypes dominate: full-stack integrated suppliers, intelligent automation platform providers, and virtualized RAN software vendors. Competitive moves center on strategic partnerships for multi-vendor interoperability and portfolio diversification into cloud-native orchestration.
Within the full-stack integrated tier, Huawei Technologies exemplifies vertical control from semiconductor design through antenna deployment. Ericsson anchors European positioning through network optimization automation. Samsung Electronics occupies a position in North American Open RAN deployments with software-centric architectures.
| Leading Market Players |
|---|
| Huawei Technologies |
| Ericsson |
| Nokia Corporation |
| ZTE Corporation |
| Samsung Electronics |
| CommScope Holding Company |
| Qualcomm Technologies |
| NEC Corporation |
| Airspan Networks |
| Others |
Value Chain & Pricing Dynamics
Taipei-Hsinchu semiconductor corridor capacity allocation directly shapes downstream pricing power for GaN-on-SiC power amplifiers, compressing vendor margins when foundry utilization spikes. Operators in North America and Europe absorb these cost oscillations through long-term supply agreements, while Chinese vendors leverage captive substrate production to maintain pricing flexibility.
Pricing Analysis
Lifecycle service contracts now drive the majority of vendor profitability, displacing upfront hardware margins as the primary value capture mechanism. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration depth, with full-stack suppliers commanding service premiums over disaggregated hardware vendors. Pricing pressure stems from Open RAN interoperability mandates that commoditize radio unit hardware. Enterprise private network buyers exhibit lowest price sensitivity due to productivity-linked ROI calculations, while rural coverage operators in subsidy-dependent markets negotiate most aggressively on unit economics.
Supply Chain Analysis
Gallium nitride substrates and silicon carbide wafers feed from concentrated East Asian foundry capacity in Taiwan, South Korea, and Japan, creating single-source vulnerability for advanced power amplifier production. Thermal management components and massive MIMO antenna arrays complete the bill of materials, with certification timelines extending procurement cycles. Tariff exposure on Chinese-manufactured radio units disrupts cost planning for North American deployments. Distribution runs through direct vendor-operator relationships for macro infrastructure, with systems integrators mediating enterprise and neutral host transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Base station vendors face substitution pressure from cloud-native network-as-a-service models that transfer infrastructure ownership to hyperscale orchestrators, threatening traditional hardware-centric business models.
For Market Incumbents: Pre-empt disaggregation-driven margin erosion by deepening captive production of beamforming chipsets and antenna calibration systems. Secure O-RAN Alliance certification ahead of interoperability mandates to lock in multi-vendor deployment roles. Anchor operator relationships through managed service contracts that bundle hardware refresh cycles with optimization software subscriptions. For New Entrants and Emerging Players: Build out software-centric vRAN stacks targeting North American Open RAN deployment windows where incumbent hardware lock-in remains weakest. Campus and venue neutral host configurations offer the most penetrable entry segment, with 6 GHz unlicensed frameworks reducing spectrum licensing barriers. Lead with containerized orchestration platforms that demonstrate multi-vendor radio integration during pilot evaluations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors intelligent automation platform providers over pure-play hardware manufacturers as network optimization software captures expanding share of operator opex. Long-term viability hinges on cloud-native RAN orchestration capabilities and enterprise private network deployment track records. Monitor Open RAN certification completion rates as the inflection signal for vendor eligibility in major procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Certification Completion | O-RAN Alliance conformance verification unlocks multi-vendor procurement eligibility with major operators. |
| GaN-on-SiC Substrate Integration | Captive power amplifier production insulates margins from East Asian foundry utilization spikes. |
| Enterprise Private Network Deployment | Factory-floor 5G installations under Germany's Industrie 4.0 framework bypass traditional operator channels. |
| Cloud-Native RAN Orchestration | Containerized baseband virtualization enables edge computing convergence with enterprise IT workloads. |
| Managed Infrastructure Service Contracts | Network-as-a-service models transfer lifecycle responsibility to vendors while securing recurring revenue streams. |
Study Parameters
A standing panel of network planning executives at tier-1 mobile operators, RF engineering directors at infrastructure vendors, and procurement leads at enterprise private network deployers provided ongoing calibration across the study period. Primary interview findings were cross-validated against secondary sources including FCC equipment authorization databases, 3GPP technical specifications, MIIT spectrum allocation notices, and operator capex disclosure filings. Bottom-up deployment volume estimates were triangulated with top-down market sizing derived from vendor shipment disclosures and regulatory infrastructure targets.
Scenario-bracketing around spectrum auction timing, Open RAN mandate implementation pace, and enterprise private network subsidy levels bounded the projection range across the analysis window. Segmentation modeling captured product type, technology generation, end-user category, and deployment model dimensions, with regional regulatory clusters treated as distinct adoption environments. CAGRs were derived from fitted growth curves anchored to disclosed infrastructure investment commitments and spectrum license expiration schedules.
Stress conditions across GaN substrate supply disruption, Open RAN interoperability timeline delays, and enterprise adoption rate deceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology standardization velocity. Cross-checking against disclosed operator infrastructure spending plans and vendor order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Repeaters Market
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
SATCOM Transceivers Market
Telecom Hardware
LPWAN Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
Digital TV Soc Market
Telecom Hardware
Global LTE Modems Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
Commercial Antennas Market
Telecom Hardware
Synchronous Optical Network (SONET) Market
Telecom Hardware
5G BTS Antenna Market
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
LTE IoT Devices Market
Telecom Hardware
Global Ultra Portable Internet Device Market