
 Synchronous Optical Network (SONET) Market | 2026-2036
Synchronous Optical Network (SONET) Market Size, Share, and Industry Trends Forecast 2026-2036
Synchronous Optical Network (SONET) Market Analytics
GR-253-CORE certification from Telcordia is unwinding competitive access for equipment vendors lacking synchronous optical interoperability validation. Cisco Systems, Inc. leverages extensive router-to-SONET integration expertise to sustain enterprise and service provider relationships. Fujitsu Ltd. anchors North American supply through manufacturing scale and long-standing carrier partnerships. Huawei Technologies Co., Ltd. competes aggressively on cost but navigates procurement restrictions in multiple Western jurisdictions.
Synchronous Optical Network constitutes a standardized digital hierarchy for optical fiber transmission using time-division multiplexing to carry multiple data streams at hierarchical rates from OC-1 through OC-192 and beyond, with built-in operations, administration, maintenance, and provisioning capabilities for carrier-grade reliability. Core Network deployments retain the largest installed value base as tier-one operators preserve capital-intensive backbone investments, while Metropolitan Area Network segments attract selective upgrade spending where traffic aggregation demands exceed legacy capacity. Wavelength Division Multiplexing technology commands attention for spectral efficiency gains even within SONET-framed architectures, and Voice Over IP application layers continue displacing circuit-switched trunking to reshape interface card requirements.
FCC Part 68 registration requirements govern network equipment interconnection in the United States, while ITU-T G.707 and G.783 standards define international synchronous digital hierarchy compatibility that constrains product design across export markets. The EU Radio Equipment Directive and CE marking impose electromagnetic compatibility and safety obligations on optical transmission gear sold into European member states. Stakeholders must monitor hybrid packet-optical convergence timelines and assess at what threshold Internet Protocol over dense wavelength division multiplexing architectures render discrete SONET node investments economically indefensible.
Market Dynamics
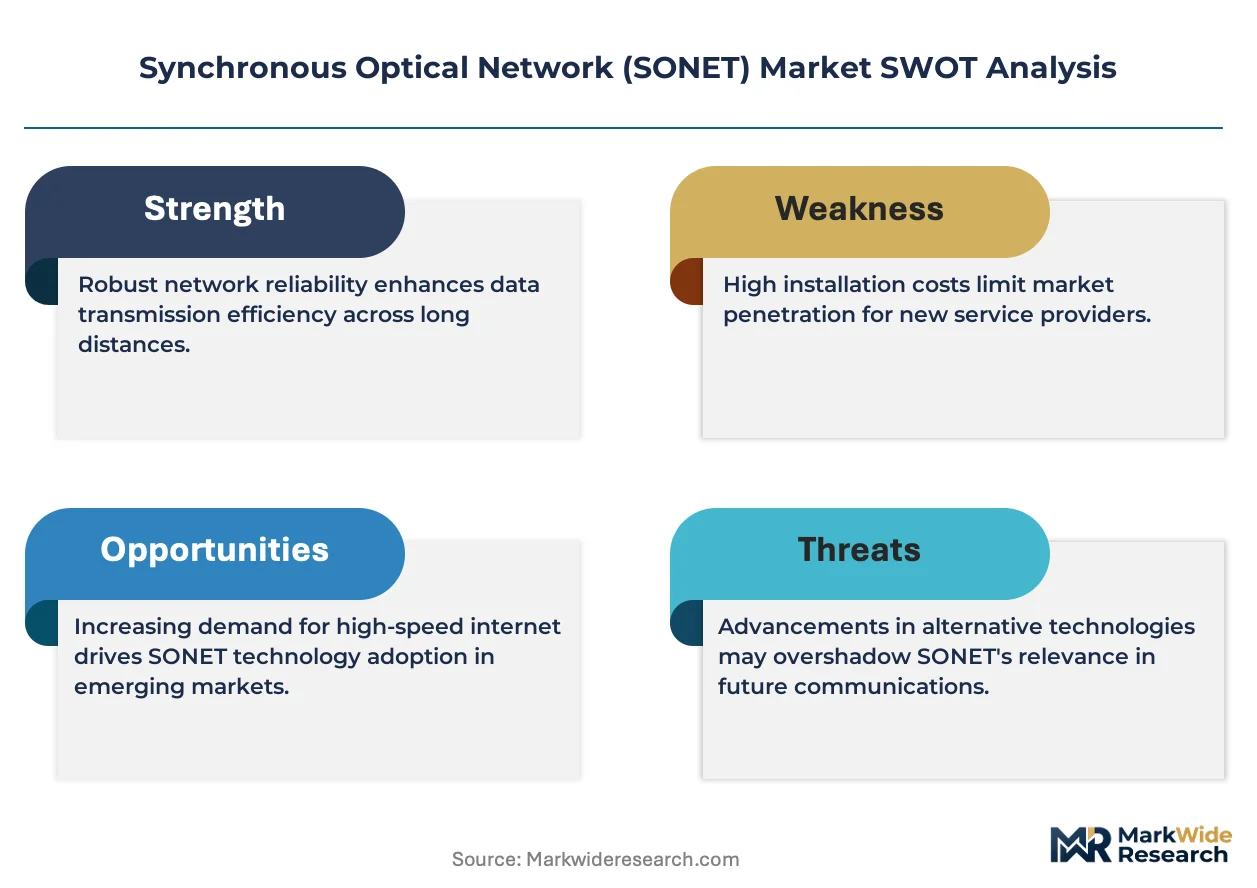
Carrier migration toward packet-optical convergence is compressing refresh cycles for discrete SONET node investments, forcing incumbent vendors to defend installed bases through software-defined overlays rather than hardware replacements.
Growth Catalysts
- GR-253-CORE certification:Telcordia's interoperability mandate sustains demand for validated equipment among US incumbent operators maintaining legacy infrastructure.
- Fiber densification:Metropolitan traffic aggregation requirements in the United States drive selective upgrades where legacy OC-48 rings exhaust capacity.
- Voice Over IP trunking:Circuit-switched displacement reshapes interface card portfolios toward Ethernet-optimized configurations.
Market Restraints
- Capital intensity:Dense wavelength division multiplexing platforms require substantial upfront investment, squeezing SONET-specific capital allocations.
- Supply concentration:North American manufacturing gravity limits vendor diversity and extends lead times for specialized optical components.
- Technical obsolescence:Internet Protocol over DWDM architectures threaten discrete time-division multiplexing node economics.
Strategic Opportunities
- Hybrid convergence:Software-defined networking overlays on existing SONET frames create service differentiation without full infrastructure replacement.
- Maintenance services:Extended support contracts for OC-192 and OC-768 installations capture recurring revenue from aging US backbone deployments.
- CE marking pathways:EU Radio Equipment Directive compliance opens European carrier markets previously constrained by interoperability fragmentation.
Industry Challenges
- Skill scarcity:Synchronous digital hierarchy engineering expertise is retiring faster than packet-optical training programs replenish talent pools.
- Certification timelines:FCC Part 68 registration delays product launches by six to eighteen months, compressing competitive windows.
- Legacy integration:Backward compatibility requirements with twenty-year-old OC-3 and OC-12 deployments constrain architectural flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synchronous Optical Network (SONET) Market |
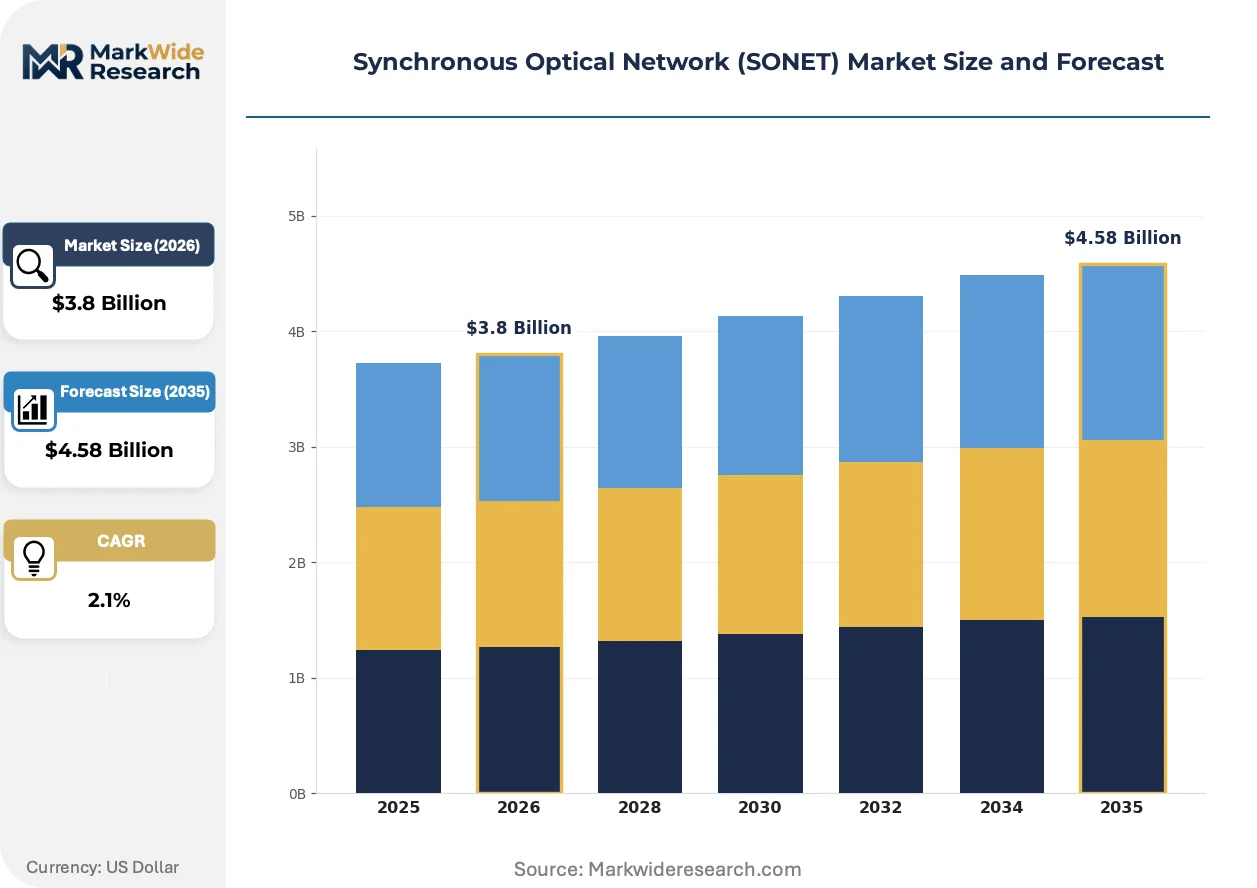
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.58 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Network, Core Network, Metropolitan Area Network, Long-Haul Network End User: Telecommunication Providers, Data Centers, Enterprises, Government Agencies Technology: Wavelength Division Multiplexing, Time Division Multiplexing, Optical Cross-Connect, Multiprotocol Label Switching Application: Internet Backbone, Voice Over IP, Video Transmission, Network Interconnection |
| Companies Covered | Alcatel-Lucent, Inc., Nokia Corporation, Cisco Systems, Inc., Fujitsu Ltd., Verizon Communications Inc., Ciena Corporation, Huawei Technologies Co., Ltd., Ericsson Inc., ADVA Optical Networking SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synchronous Optical Network (SONET) Market Evolving Landscape
Optical transport architecture is bifurcating between software-programmable layers and fixed hardware hierarchies, with SONET equipment vendors repositioning toward management plane value rather than pure transmission hardware.
Reconfigurable optical add-drop multiplexer technology is miniaturizing node footprints from chassis-based systems to pluggable transceiver modules. Tier-one US carriers are piloting these compact ROADM configurations in metropolitan rings to defer full node replacement. The form factor compression is miniaturizing capital deployment per route-mile and shifting supplier value toward silicon photonics vendors.
EU Radio Equipment Directive electromagnetic compatibility testing is tightening certification burdens for optical transmission gear sold into European member states. Equipment manufacturers must now demonstrate compliance with stricter emission and safety protocols before CE marking authorization. This regulatory tightening favors established vendors with dedicated compliance laboratories over smaller competitors.
Service contract unbundling is separating hardware procurement from long-term maintenance agreements. US incumbent operators now negotiate support terms independently of initial equipment purchases, compressing vendor margins on the service component. This purchasing pattern shift is most pronounced among regional Bell operating companies seeking operational expenditure flexibility.
Synchronous Optical Network (SONET) Market Segmentation
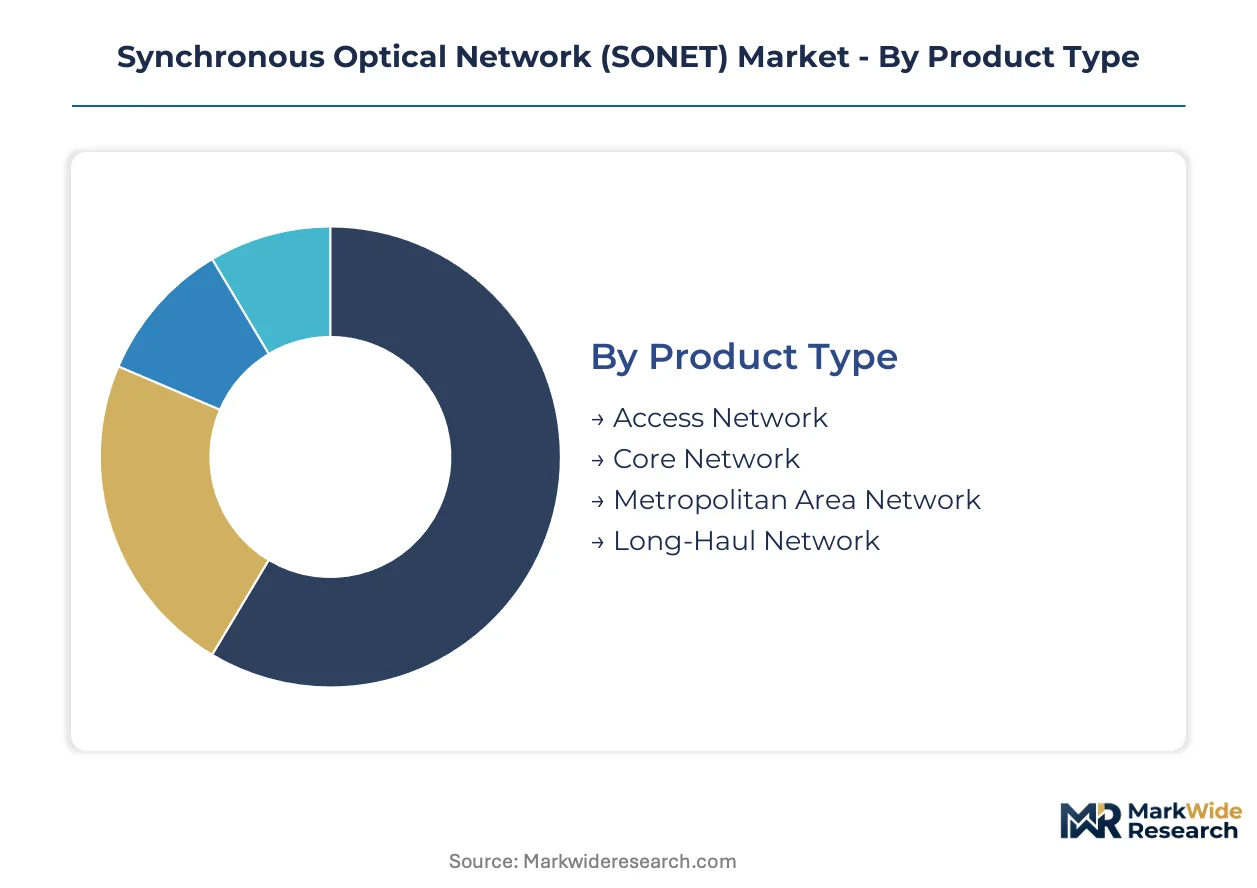
SONET market segmentation reveals how capital allocation splits between preservation of legacy time-division infrastructure and selective migration toward packet-optical hybrids. Procurement patterns diverge sharply across product tiers, with incumbent carriers prioritizing compatibility over performance gains.
Product Type:
Channel flows concentrate through direct carrier procurement for backbone tiers, while metropolitan segments route via systems integrators and regional distributors.
- Core Network:Backbone infrastructure carrying OC-192 and OC-768 signals across intercity fiber routes with redundant protection switching. US tier-one operators concentrate maintenance spending here, driven by FCC Part 68 interconnection mandates and the capital cost of full replacement.
- Metropolitan Area Network:Urban aggregation rings handling traffic handoffs between access and backbone layers, typically OC-48 and OC-192 configurations. Selective upgrade demand concentrates where fiber densification exhausts legacy OC-48 capacity in dense US metro corridors.
- Access Network:Last-mile termination equipment bridging customer premises to carrier infrastructure.
- Long-Haul Network:Extended-reach transmission systems spanning multi-thousand-kilometer routes with optical amplification.
Core Network dominates installed base. Metropolitan Area Network is where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive carrier deployments from operational expenditure-driven enterprise adoption.
- Telecommunication Providers:Incumbent local exchange carriers and competitive access providers maintaining GR-253-CORE certified infrastructure. US regional Bell operating companies anchor demand through legacy refresh cycles and selective OC-192 ring augmentation where traffic growth warrants.
- Data Centers:Hyperscale facilities requiring synchronous timing distribution for financial trading and distributed computing workloads. Interconnection-rich Ashburn and Dallas corridors concentrate procurement, driven by latency-sensitive application requirements.
- Enterprises:Large corporate networks with private fiber assets requiring carrier-grade reliability.
- Government Agencies:Federal and state entities with dedicated secure communication requirements.
Telecommunication Providers command the deepest installed base. Data Centers are climbing the fastest as timing-critical workloads proliferate.
Technology:
Application context determines whether spectral efficiency or protocol flexibility takes procurement priority.
- Wavelength Division Multiplexing:Multi-channel optical transmission combining multiple SONET streams onto single fiber pairs through wavelength separation. Tier-one US carriers pilot miniaturized ROADM configurations in metropolitan rings to defer full node replacement, driven by form factor compression and silicon photonics advancement.
- Time Division Multiplexing:Legacy synchronous hierarchy multiplexing lower-rate signals into higher-rate streams through fixed time slots. Preservation demand concentrates among US incumbents maintaining twenty-year-old OC-3 and OC-12 deployments where backward compatibility constrains architectural flexibility.
- Optical Cross-Connect:Circuit-switching fabrics enabling automated wavelength routing and restoration.
- Multiprotocol Label Switching:Packet-forwarding layer enabling traffic engineering across hybrid optical-packet infrastructure.
Time Division Multiplexing retains the largest deployed footprint. Wavelength Division Multiplexing is gaining share fastest as spectral efficiency pressures intensify.
Application:
Volume concentration aligns with traffic growth trajectories and interface card refresh requirements.
- Voice Over IP:Packetized voice trunking displacing circuit-switched TDM interconnection, reshaping SONET interface card portfolios toward Ethernet-optimized configurations. US incumbent operators drive replacement demand as they retire legacy Class 5 switches and consolidate trunking onto converged packet infrastructure.
- Internet Backbone:High-capacity interconnection points between autonomous systems and tier-one provider networks. Peering-rich facilities in Los Angeles, Miami, and New York concentrate deployment, driven by traffic aggregation demands exceeding legacy OC-48 ring capacity.
- Video Transmission:Broadcast and streaming content distribution requiring synchronous timing.
- Network Interconnection:Cross-carrier handoff points and neutral colocation facilities.
Internet Backbone anchors capital deployment scale. Voice Over IP is expanding most quickly as circuit displacement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber cable landings at Manasquan, New Jersey, and Shirley, New York, anchor United States dominance in legacy optical infrastructure maintenance and selective modernization.
United States
FCC Part 68 registration mandates and GR-253-CORE certification requirements sustain incumbent carrier procurement for OC-192 backbone rings. Regional Bell operating companies concentrate maintenance spending in Ashburn, Virginia, and Dallas, Texas, where data center interconnection demands exhaust legacy OC-48 capacity.
Germany
Deutsche Telekom's T-Systems division preserves substantial synchronous digital hierarchy installations requiring backward-compatible upgrades. CE marking under the EU Radio Equipment Directive governs electromagnetic compliance for optical transmission gear entering European member states. The Rhine-Ruhr corridor hosts concentrated carrier procurement for metropolitan ring augmentation.
Japan
Nippon Telegraph and Telephone maintains extensive OC-768 backbone infrastructure with rigorous JIS standards compliance for optical component interoperability. METI industrial policy supports domestic equipment sourcing preferences. The Tokyo-Osaka corridor concentrates demand for miniaturized ROADM configurations in metropolitan aggregation layers.
United Kingdom
Openreach's fiber densification program drives selective SONET interface card refresh for legacy business services. Ofcom regulatory frameworks govern network equipment interconnection standards. The London Docklands and Manchester media clusters concentrate procurement for synchronous timing distribution in financial trading infrastructure.
China
China Telecom and China Unicom maintain substantial installed bases of SDH-compatible equipment requiring ongoing component supply. MIIT standards certification and GB optical interface specifications constrain import procurement for critical infrastructure. The Yangtze River Delta corridor around Shanghai concentrates manufacturing scale for optical transmission components.
Synchronous Optical Network (SONET) Market Competitive Landscape
Listed leaders compete with private specialists across certification-validated equipment tiers, producing a consolidated structure where incumbent vendors defend installed bases through software overlays rather than hardware displacement. Three archetypes dominate: integrated telecom equipment conglomerates with end-to-end optical portfolios, specialized optical networking vendors with focused ROADM and transceiver expertise, and carrier-affiliated equipment divisions with captive demand pipelines. Competitive moves concentrate on strategic partnerships for packet-optical convergence and geographic licensing arrangements to bypass procurement restrictions.
Within the integrated conglomerate tier, Cisco Systems, Inc. and Fujitsu Ltd. exemplify archetypes combining router-to-SONET integration expertise with long-standing carrier certification relationships. Huawei Technologies Co., Ltd. occupies a contested position where cost competitiveness encounters Western procurement constraints. Among specialized optical vendors, Ciena Corporation and ADVA Optical Networking SE represent focused players repositioning toward software-defined management plane value.
| Leading Market Players |
|---|
| Alcatel-Lucent, Inc. |
| Nokia Corporation |
| Cisco Systems, Inc. |
| Fujitsu Ltd. |
| Verizon Communications Inc. |
| Ciena Corporation |
| Huawei Technologies Co., Ltd. |
| Ericsson Inc. |
| ADVA Optical Networking SE |
| Others |
Value Network & Pricing Analysis
Silicon photonics miniaturization is displacing discrete optical component assemblies across SONET equipment manufacturing, simultaneously shifting supply gravity toward East Asian semiconductor foundries and compressing pricing premiums for chassis-based systems. This substitution dynamic reconfigures procurement economics as pluggable transceiver modules erode traditional node-level pricing structures.
Pricing Analysis
Certification level creates the primary spread between GR-253-CORE validated equipment and uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels segments procurement: premium tiers command carrier-grade reliability premiums, standard tiers serve selective upgrade cycles, and economy tiers address maintenance parts. Cost compression in economy tiers is intensifying because service contract unbundling separates hardware from long-term support agreements. Regional Bell operating companies exhibit highest price sensitivity due to operational expenditure constraints, while data center operators prioritize timing precision over cost.
Supply Chain Analysis
Inbound logistics costs from East Asian semiconductor hubs through Los Angeles and Long Beach port complexes constrain component availability for North American assembly operations. Manufacturing concentration centers on Japan, South Korea, and Taiwan for optical transceivers and silicon photonics chips. Raw material dependencies include indium phosphide substrates, lithium niobate modulators, and specialized hermetic packaging. Single-source vulnerability persists for qualified GR-253-CORE testing laboratories. Distribution runs through direct carrier procurement for backbone tiers and systems integrators for metropolitan segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a defensive-moat opportunity anchored in regulatory entrenchment. FCC Part 68 registration and Telcordia certification requirements create structural barriers that protect incumbent positions while constraining new entrant pathways.
For Market Incumbents: Consolidate installed base relationships through software-defined networking overlays that extend hardware lifecycles without full infrastructure replacement. Deepen vertical integration into silicon photonics design to capture form factor compression value. Packet-optical convergence from Ciena Corporation and ADVA Optical Networking SE threatens discrete node margins; counter through extended maintenance contracts for OC-192 and OC-768 backbone installations.
For New Entrants and Emerging Players: Anchor in European carrier markets where CE marking under the EU Radio Equipment Directive opens procurement channels previously constrained by interoperability fragmentation. Target data center timing distribution segments in Ashburn and Dallas corridors where latency-sensitive workloads drive synchronous infrastructure demand. Pursue certification-first go-to-market strategies that front-load GR-253-CORE validation before hardware development.
For Investors and Strategic Acquirers: The market sits at a late-stage maintenance phase that specialized service providers and software-overlay vendors. Long-term viability hinges on hybrid convergence timelines and the threshold at which Internet Protocol over DWDM architectures render discrete SONET investments economically indefensible. Acquisition target archetype: optical networking vendors with established carrier certification relationships and software-defined management plane capabilities. Monitor FCC Part 68 registration backlogs as inflection indicator for competitive window compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Networking Overlay Deployment | Extends legacy SONET frame lifecycles without full hardware replacement, preserving carrier relationships. |
| Silicon Photonics Vertical Integration | Captures form factor compression value as pluggable transceivers displace chassis-based systems. |
| GR-253-CORE Certification Acceleration | Unlocks US incumbent carrier procurement channels constrained by Telcordia interoperability mandates. |
| CE Marking Pathway Investment | Opens European carrier markets under EU Radio Equipment Directive compliance requirements. |
| Extended Maintenance Service Unbundling | Captures recurring revenue from aging OC-192 and OC-768 backbone installations at regional Bell operating companies. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with network planning executives at tier-one carriers, optical transport engineers at regional Bell operating companies, and procurement leads at data center operators; alongside secondary validation through FCC Part 68 registration databases, Telcordia certification records, SEC equipment vendor filings, and ITU-T standards documentation. Bottom-up segmentation modeling triangulated against top-down market sizing from carrier capital expenditure disclosures and optical component trade data.
Across the projection horizon, the analytical framework modeled volume and value outputs through multi-dimensional segmentation spanning network tier, end-user archetype, technology type, and application context. CAGRs were derived from regression analysis of historical equipment shipments against carrier infrastructure refresh cycles and fiber densification trajectories. Forecast inputs incorporated packet-optical convergence adoption curves and synchronous timing distribution demand from financial trading infrastructure.
Material uncertainties — accelerated Internet Protocol over DWDM displacement, regulatory certification timeline extensions, and silicon photonics supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding carrier capital allocation priorities and standards migration pathways. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Laser Communications Terminals (Lcts) Market
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
LPWAN Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
OTN Hardware Market
Telecom Hardware
Land Mobile Radio System Market
Telecom Hardware
Global FPGA in Telecom Sector Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Industrial Transceivers Market
Telecom Hardware
Telecom Electronic Manufacturing Services (EMS) Market
Telecom Hardware
DWDM Transceiver Market
Telecom Hardware
Set-Top Box Market
Telecom Hardware
SATCOM Transceivers Market