
 Asia Pacific Enterprise Routers Market | 2026-2036
Asia Pacific Enterprise Routers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Enterprise Routers Market Insights
India's PLI scheme for telecom equipment manufacturing is decoupling hardware procurement from traditional import channels. Cisco Systems leverages its channel density to sustain dominance across Australian enterprise campuses. Huawei Technologies anchors supply relationships with state-affiliated carriers throughout mainland China. Juniper Networks competes through specialization in cloud-native routing stacks for hyperscale facilities.
Asia Pacific enterprise routers are Layer 3 network devices that forward data packets between computer networks using IP addressing tables, with throughput specifications commonly ranging from 1 Gbps to multi-terabit chassis systems designed for carrier-grade reliability. These systems enable secure traffic segmentation, quality-of-service enforcement, and software-defined WAN integration across distributed corporate infrastructures. Edge routers capture expanding margin pools as 5G backhaul requirements proliferate across Indonesian and Vietnamese telecom networks. Wireless routers represent the fastest-growing product category, driven by Wi-Fi 7 refresh cycles in South Korean and Japanese enterprise environments. On-premises deployment retains structural importance in China's banking sector due to data sovereignty mandates.
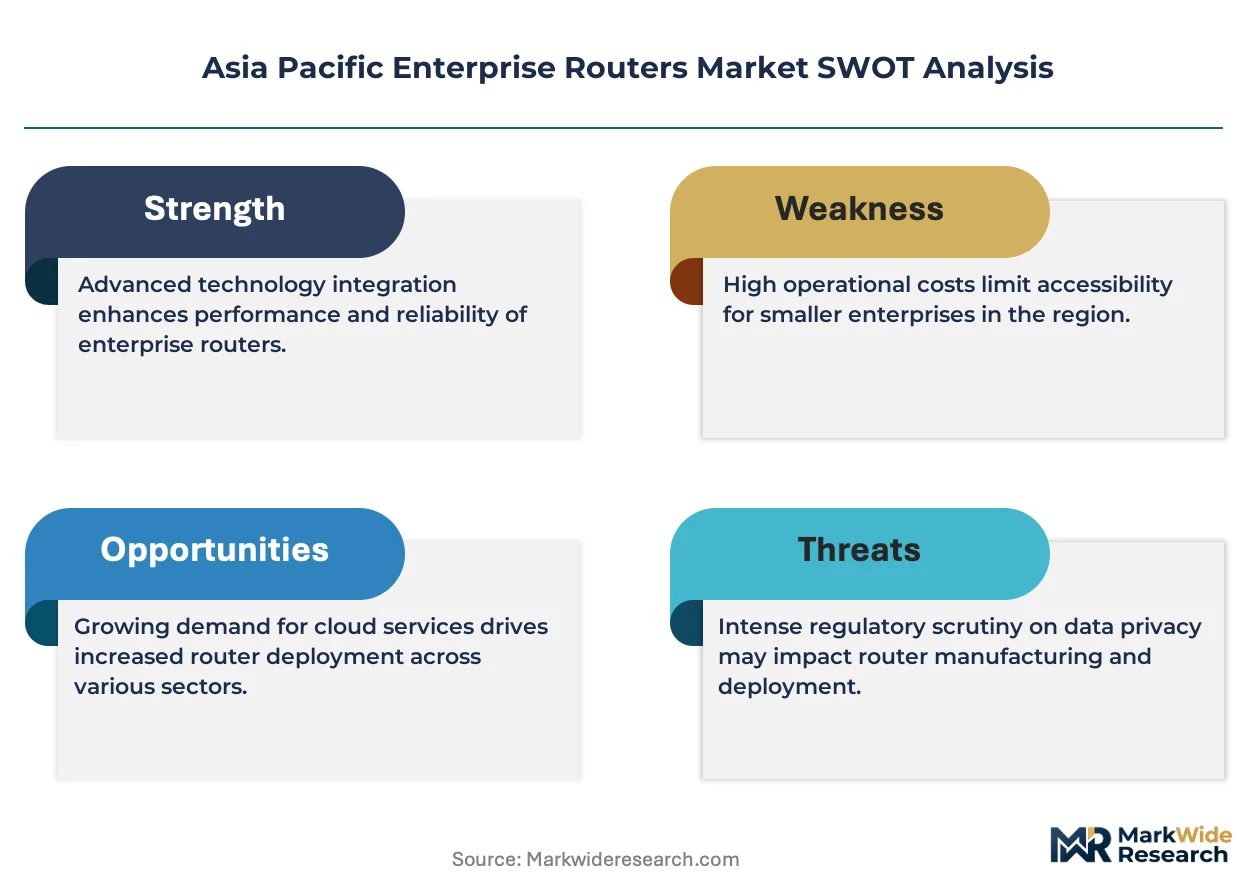
Japan's METI enforces cybersecurity certification frameworks that elevate compliance costs for foreign vendors seeking public-sector router contracts. China's MIIT mandates GB standards for encryption modules embedded in network infrastructure, creating localized product variant requirements. Australia's TGA-equivalent information security regulator imposes breach-notification rules that accelerate enterprise segmentation investments. Stakeholders must weigh the trade-off between centralized cloud management and sovereignty-driven edge deployment as regulatory fragmentation deepens across the region.
Market Dynamics
Cloud service providers across Southeast Asia are accelerating procurement of high-throughput routing infrastructure, compressing refresh cycles from five years to eighteen months in hyperscale facilities. This demand surge is restructuring vendor priorities toward software-defined architectures and subscription-based licensing models.
Growth Catalysts
- India's PLI scheme:The production-linked incentive program for telecom equipment manufacturing is decoupling hardware procurement from traditional import channels, incentivizing domestic assembly of enterprise-grade routing systems.
- Wi-Fi 7 refresh cycles:South Korean and Japanese enterprise environments are driving wireless router category expansion through mandatory upgrades to support 6 GHz spectrum utilization and deterministic latency for industrial IoT.
- 5G backhaul proliferation:Indonesian and Vietnamese telecom networks are deploying edge routers to handle fronthaul aggregation requirements, creating carrier-grade reliability demand in previously underserved markets.
Market Restraints
- Encryption module localization:China's MIIT mandates GB standards for embedded cryptographic components, forcing foreign vendors to maintain separate product variants and fragmenting supply chain economies of scale.
- Silicon supply concentration:Advanced routing ASIC fabrication depends on a concentrated foundry base in Taiwan, exposing lead times to geopolitical friction and capacity allocation decisions.
- Cybersecurity certification costs:Japan's METI frameworks elevate compliance expenditures for public-sector contracts, creating a structural barrier to market entry for mid-tier international suppliers.
Strategic Opportunities
- Vietnamese manufacturing corridors:Northern industrial zones near Hanoi are attracting router assembly investments as multinationals diversify production away from single-source dependencies.
- Data sovereignty mandates:China's banking sector retains structural preference for on-premises deployment, sustaining demand for chassis-based systems despite cloud migration trends elsewhere.
- SD-WAN convergence with SASE:Australian enterprise campuses are integrating routing infrastructure with zero-trust security stacks, creating bundled solution opportunities for vendors with cross-domain expertise.
Industry Challenges
- Legacy protocol integration:Financial institutions in Tokyo and Singapore require seamless MPLS-to-SRv6 migration paths, complicating deployment timelines for cloud-native routing stacks.
- Specialized field engineering scarcity:Multi-terabit chassis deployment demands expertise in optical interconnect and thermal management that outpaces regional training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Enterprise Routers Market |
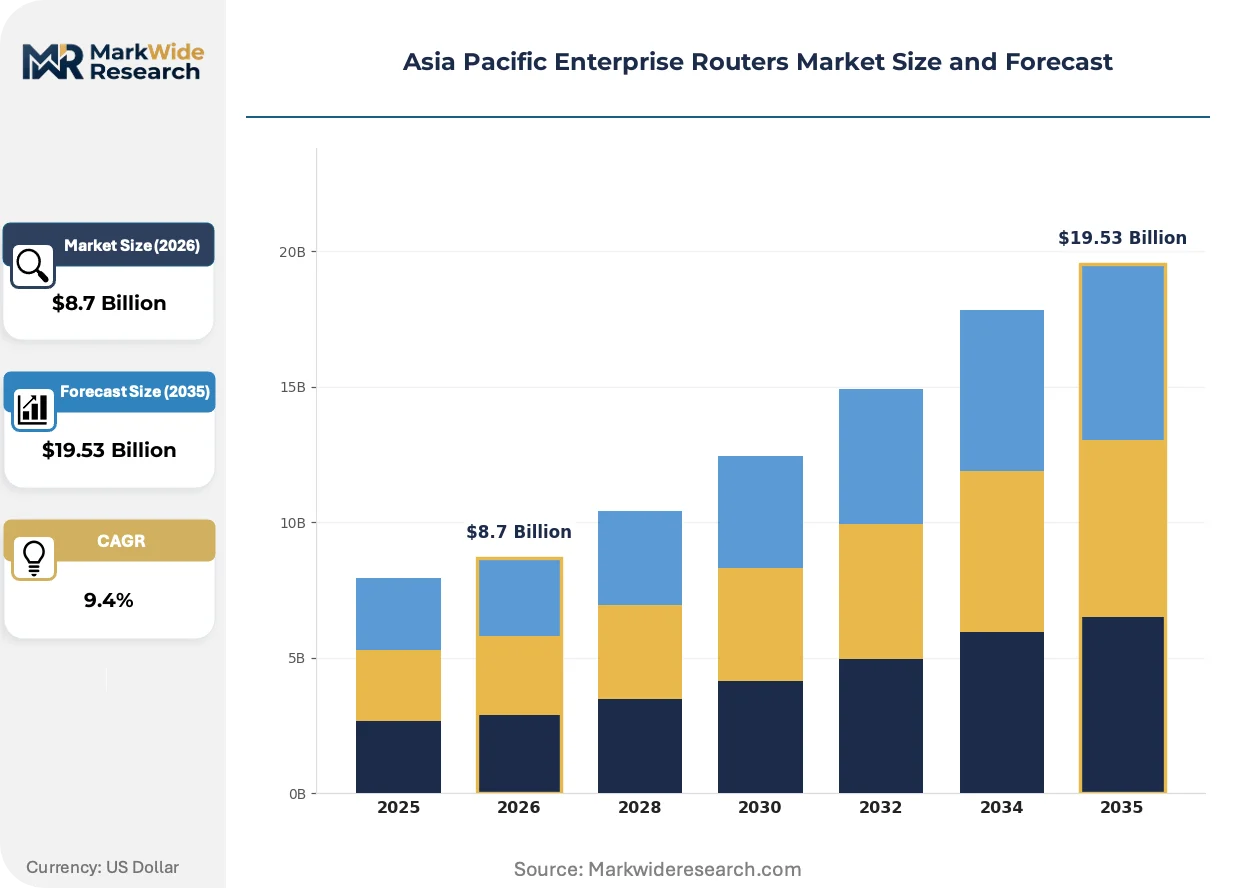
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Routers, Wireless Routers, Core Routers, Edge Routers Deployment Model: On-Premises, Cloud-Based, Hybrid, Virtualized End User: Small Businesses, Enterprises, Data Centers, Managed Service Providers Connectivity: Ethernet, Fiber Optic, DSL, 4G LTE |
| Companies Covered | Cisco Systems, Huawei Technologies, Hewlett Packard Enterprise, Juniper Networks, Extreme Networks, Arista Networks, Fortinet, Nokia Corporation, ZTE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Enterprise Routers Market Trends and Innovations
Disaggregated routing architectures are compressing hardware margins while elevating software and services revenue streams across Asia Pacific enterprise networks. Vendors are repositioning around programmable silicon and intent-based automation to capture value in this transition.
Merchant silicon-based whitebox routers are consolidating control plane functions onto standardized compute platforms, displacing proprietary ASIC dominance in data center interconnect applications. Australian cloud service providers are adopting these systems at scale for spine-leaf architectures. The shift is consolidating vendor ecosystems around three dominant switching silicon suppliers and compressing differentiation timelines.
Japan's METI cybersecurity certification frameworks now mandate firmware provenance documentation and supply chain attestation for public-sector router procurements. Foreign vendors face extended qualification timelines as they establish in-country security assessment partnerships. Financial services networks in Osaka and Tokyo are responding by pre-qualifying domestic system integrators as compliance intermediaries.
Enterprise buyers across South Korea are unbundling hardware acquisition from multi-year managed service contracts, compressing vendor lock-in durations and intensifying price transparency. Systems integrators in Seoul are responding with usage-based pricing models tied to actual throughput rather than port capacity. This behavioral shift is most visible in the manufacturing vertical, where smart factory deployments favor operational expenditure treatment for network infrastructure.
Asia Pacific Enterprise Routers Market Segmentation
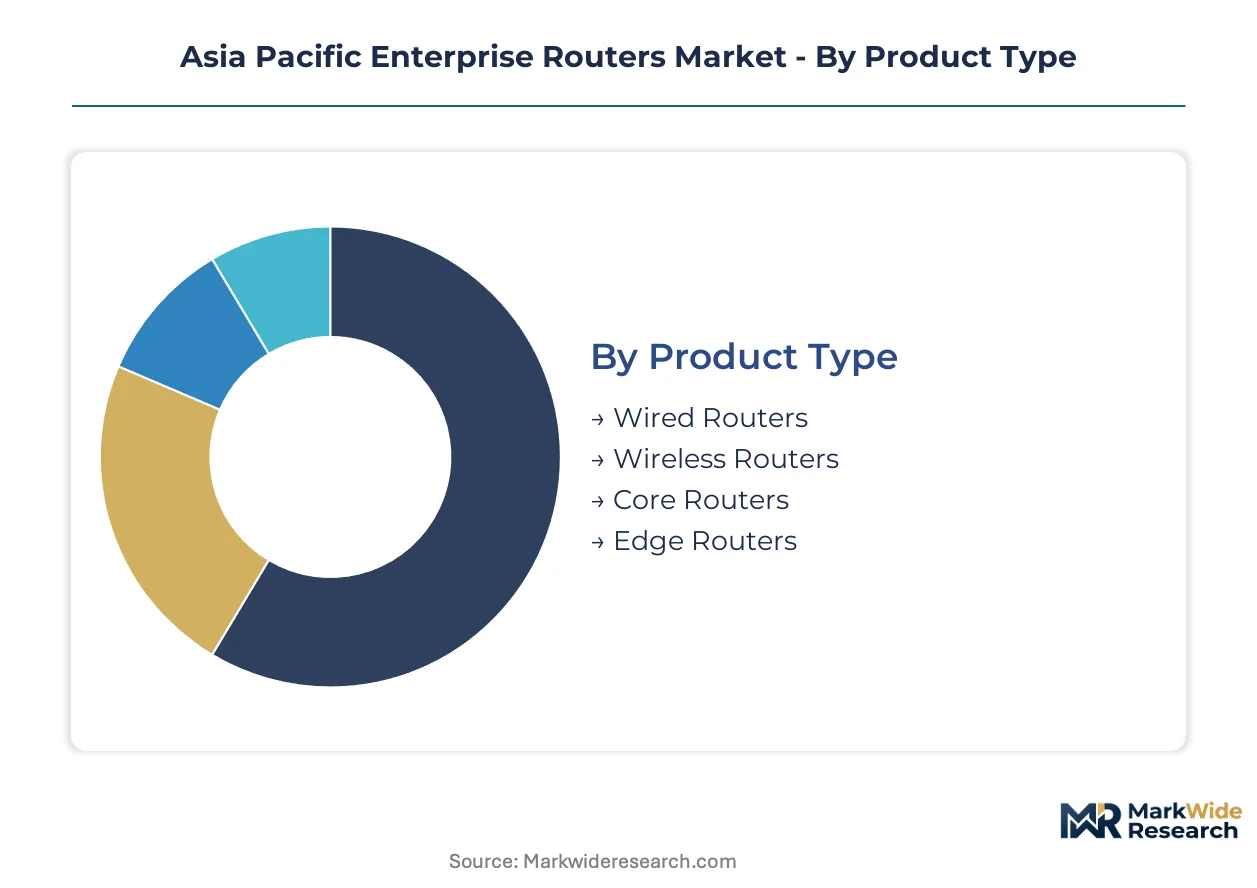
Enterprise router procurement patterns across Asia Pacific diverge sharply by infrastructure maturity and regulatory environment. Refresh cycles and compliance mandates reshape how vendors prioritize product development and channel investment across each segment category.
Product Type:
Upgrade timelines vary from eighteen months in hyperscale facilities to seven years in legacy banking infrastructure, creating tiered replacement demand across hardware categories.
- Wireless Routers:These systems integrate Wi-Fi 7 chipsets supporting 6 GHz spectrum and deterministic latency for industrial IoT workloads. South Korean manufacturing campuses and Japanese enterprise offices are driving category expansion through mandatory spectrum upgrades and smart factory deployments.
- Edge Routers:Compact form-factor devices aggregate fronthaul traffic for 5G backhaul networks with carrier-grade reliability specifications. Indonesian and Vietnamese telecom operators are deploying these systems at scale to handle baseband unit concentration requirements in previously underserved markets.
- Wired Routers:Traditional copper and fiber-based enterprise systems dominate legacy campus installations across Australian financial institutions.
- Core Routers:Multi-terabit chassis systems anchor backbone networks for state-affiliated carriers throughout mainland China.
Edge routers sit at the top of the volume ranking, with wireless routers climbing the fastest.
Deployment Model:
Cost tier differentiation separates sovereign-data mandates from cloud-economy preferences across the region's heterogeneous regulatory landscape.
- On-Premises:Physical hardware installations in customer-controlled facilities meet stringent data residency requirements. China's banking sector retains structural preference for chassis-based systems despite cloud migration trends elsewhere, sustaining premium pricing for localized support contracts.
- Hybrid:Split architectures route sensitive traffic through local appliances while offloading bulk workloads to regional cloud zones. Australian enterprise campuses favor this model to balance TGA-equivalent breach-notification compliance with operational flexibility.
- Cloud-Based:Fully managed routing-as-a-service offerings appeal to Southeast Asian cloud service providers compressing refresh cycles.
- Virtualized:Software-defined network functions running on standardized compute platforms gain traction in Indian data centers leveraging PLI scheme incentives.
On-premises deployments command the highest average contract values, though hybrid configurations are expanding most quickly across mid-market accounts.
End User:
Customer type determines procurement sophistication, with volume concentration in hyperscale operators and margin concentration in regulated verticals.
- Data Centers:Hyperscale facilities require spine-leaf architectures with merchant silicon-based whitebox systems and programmable forwarding planes. Australian cloud service providers are adopting disaggregated routing at scale, consolidating vendor ecosystems around dominant switching silicon suppliers.
- Enterprises:Distributed corporations demand integrated SD-WAN and SASE stacks for zero-trust security enforcement. Financial services networks in Tokyo and Singapore require seamless MPLS-to-SRv6 migration paths, complicating deployment timelines for cloud-native routing stacks.
- Managed Service Providers:Systems integrators in Seoul are unbundling hardware from multi-year contracts and introducing usage-based pricing tied to actual throughput.
- Small Businesses:Cost-sensitive deployments favor all-in-one wireless gateway appliances with simplified management interfaces.
Data centers dominate absolute unit volumes, while enterprise accounts deliver the steepest expansion trajectory as SD-WAN refresh accelerates.
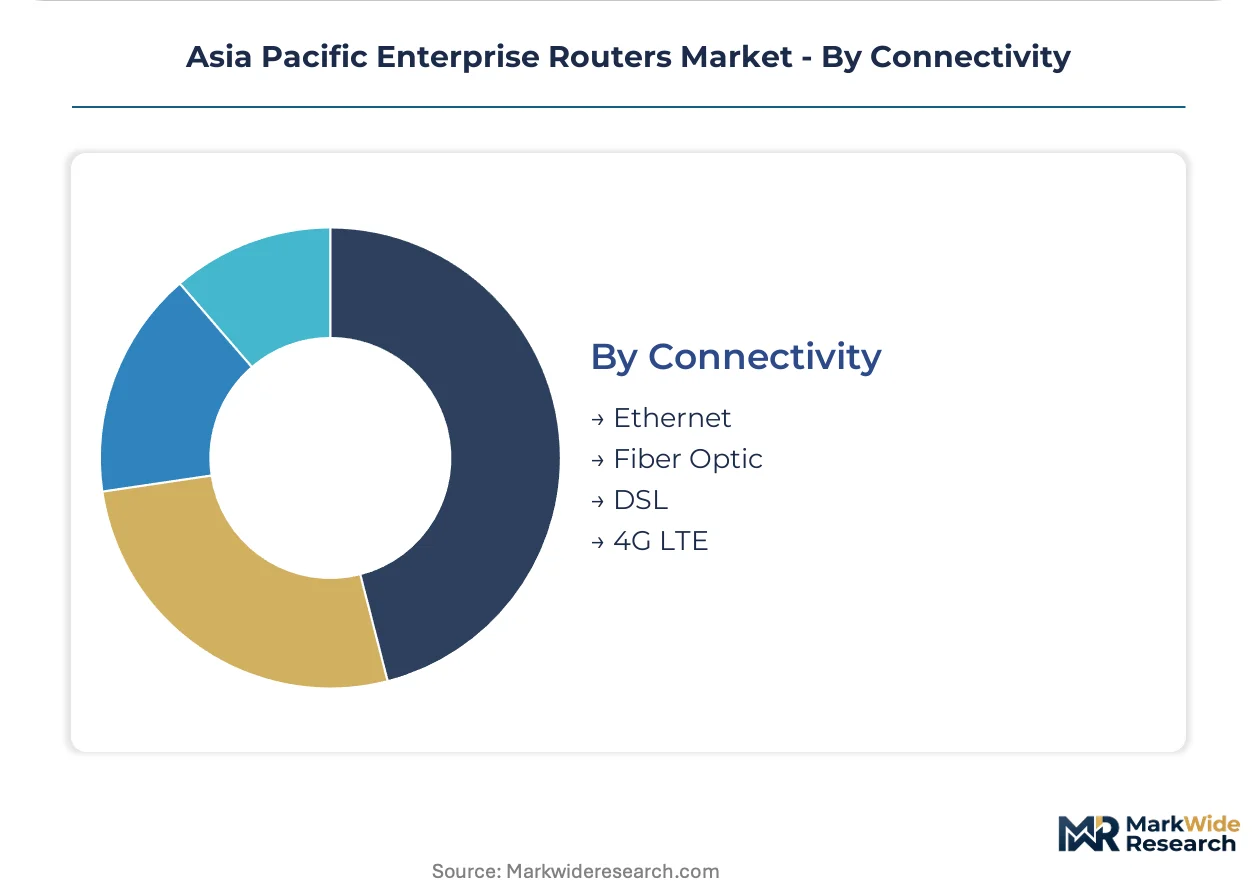
Connectivity:
Physical layer specifications correlate directly with geography and infrastructure vintage across the region's fragmented last-mile ecosystem.
- Fiber Optic:Single-mode and multi-mode optical interfaces support 100G and 400G aggregation for metro and long-haul networks. Japanese financial services sector upgrades prioritize low-latency fiber interconnect for high-frequency trading infrastructure.
- Ethernet:Copper-based Gigabit and 10GBase-T connections retain dominance in campus and branch deployments across mature Australian enterprise networks.
- 4G LTE:Cellular backhaul provides continuity for remote industrial sites and temporary deployments across Indonesian archipelago logistics networks.
- DSL:Legacy copper-line connectivity persists in rural Australian and Indian markets with limited fiber penetration.
Fiber optic interfaces generate the highest revenue per port, with 4G LTE gaining share fastest in mobile-first Southeast Asian deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized field engineers for multi-terabit chassis deployment cluster in Tokyo, Singapore, and Sydney, creating regional capability hubs that anchor enterprise router procurement sophistication across the Asia Pacific.
China
State-affiliated carriers drive demand for core router chassis systems with carrier-grade reliability specifications. MIIT mandates GB standards for encryption modules embedded in network infrastructure, forcing product localization. Beijing and Shanghai host concentrated procurement decisions for banking sector on-premises deployments.
Japan
Financial services networks prioritize low-latency fiber interconnect for high-frequency trading infrastructure. METI enforces cybersecurity certification frameworks that elevate compliance costs for foreign vendors seeking public-sector contracts. Osaka and Tokyo financial districts pre-qualify domestic system integrators as compliance intermediaries.
India
Data centers leverage PLI scheme incentives for domestic assembly of enterprise-grade routing systems. TRAI regulations shape telecom infrastructure procurement patterns. Northern industrial zones near Chennai and Bengaluru attract router assembly investments as multinationals diversify production.
Australia
Cloud service providers adopt disaggregated routing at scale for spine-leaf architectures. TGA-equivalent information security regulators impose breach-notification rules that accelerate enterprise segmentation investments. Sydney and Melbourne campuses integrate routing infrastructure with zero-trust security stacks.
Vietnam
Telecom operators deploy edge routers to handle 5G fronthaul aggregation requirements in previously underserved markets. The country's national telecom regulator shapes infrastructure deployment timelines. Northern industrial zones near Hanoi attract router assembly investments from multinationals diversifying away from single-source dependencies.
Asia Pacific Enterprise Routers Market Competitive Landscape
The competitive structure tilts toward diversified technology conglomerates with cross-domain networking portfolios. Vendor ecosystems consolidate around three dominant switching silicon suppliers, compressing differentiation timelines for hardware-centric players. Strategic archetypes include cloud-native routing specialists, carrier-grade chassis incumbents, and security-integrated platform vendors. Competitive moves center on strategic partnerships for SASE convergence and geographic expansion into Vietnamese manufacturing corridors.
Within the carrier-grade chassis tier, Huawei Technologies and ZTE exemplify state-affiliated supply relationships throughout mainland China. Among security-integrated platform vendors, Fortinet occupies a position representing bundled routing and zero-trust architectures. Juniper Networks sits within the cloud-native specialization vector, anchoring software-defined routing stacks for hyperscale facilities.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Hewlett Packard Enterprise |
| Juniper Networks |
| Extreme Networks |
| Arista Networks |
| Fortinet |
| Nokia Corporation |
| ZTE |
| Others |
Pricing and Supply Chain Analysis
Specialized field engineers for multi-terabit chassis deployment cluster in Tokyo, Singapore, and Sydney, creating labor-cost differentials that widen pricing-tier spreads between carrier-grade systems and commodity wireless access points. This workforce concentration forces vendors to absorb premium compensation structures into high-end product pricing while compressing margins on standardized hardware.
Pricing Analysis
The bundled-vs-unbundled service split is restructuring vendor revenue capture across Asia Pacific enterprise networks. Three-tier pricing structure across premium, standard, and economy levels separates chassis-based core routers with multi-year managed service contracts from whitebox spine-leaf systems sold on transactional terms. Price differentiation rests on certification grade and after-sales support intensity. Cost compression in the wireless router tier is intensifying because South Korean and Japanese buyers are unbundling hardware from multi-year contracts. Small businesses exhibit highest price sensitivity, while China's banking sector shows lowest sensitivity due to data sovereignty mandates.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan's concentrated foundry base for advanced routing ASIC fabrication. Merchant silicon suppliers in Taiwan, South Korea, and the United States anchor component sourcing for disaggregated architectures. Raw material dependencies include silicon wafers, optical transceivers, and specialized thermal management substrates. Tariff exposure from regulatory fragmentation across China's MIIT encryption mandates and Japan's METI certification frameworks fragments supply chain economies of scale. Distribution runs through systems integrators in Tokyo, Singapore, and Sydney that pre-qualify as compliance intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific enterprise routers function as a regulatory compounder, with Japan's METI cybersecurity certification frameworks and China's MIIT encryption mandates continuously elevating compliance-driven replacement demand.
For Market Incumbents: Extend software-defined architecture roadmaps to capture recurring subscription revenue as hardware margins compress. Defend against merchant silicon-based whitebox displacement by deepening proprietary ASIC differentiation in carrier-grade chassis. Invest in in-country security assessment partnerships to accelerate METI qualification timelines for public-sector contracts. For New Entrants and Emerging Players: Capture Vietnamese manufacturing corridors as multinationals diversify assembly away from single-source dependencies. Target edge router deployments for Indonesian and Vietnamese 5G fronthaul aggregation, the most penetrable growth vector. Lead with usage-based pricing models tied to actual throughput rather than port capacity to unbundle incumbent service contracts. For Investors and Strategic Acquirers: Cloud service providers are the most active acquirer in this space, seeking SASE-converged routing stacks for zero-trust integration. Long-term viability favors vendors with cross-domain networking-security portfolios over hardware-centric specialists. Watch SD-WAN-to-SASE migration velocity as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Silicon Adoption | Australian hyperscale facilities displace proprietary ASICs for spine-leaf cost efficiency. |
| SASE Platform Integration | Sydney and Melbourne campuses bundle routing with zero-trust security enforcement. |
| Vietnamese Manufacturing Expansion | Northern industrial zones near Hanoi attract assembly investments from multinationals. |
| Wi-Fi 7 Chipset Refresh | South Korean manufacturing campuses mandate 6 GHz spectrum upgrades. |
| Domestic System Integrator Partnership | Osaka and Tokyo financial districts pre-qualify compliance intermediaries for METI frameworks. |
Research Methodology
Direct dialogue with network architects at hyperscale cloud providers, procurement leads at Australian financial institutions, channel managers at systems integrators, and regulatory affairs specialists at telecom equipment vendors grounded the qualitative foundation. Secondary validation drew from MIIT GB standard filings, METI cybersecurity certification documentation, TRAI infrastructure procurement circulars, and hyperscaler capital expenditure disclosures. Bottom-up demand modeling across deployment models and product categories triangulated against top-down macroeconomic indicators.
Segmentation outputs across product type, deployment model, end user, and connectivity specification fed into analytical framework development over the projection horizon. CAGRs were derived from regression analysis of historical procurement cycles and regulatory-driven replacement patterns. Forecast inputs incorporated PLI scheme incentive trajectories in India and Wi-Fi 7 refresh timelines in South Korea and Japan.
Geopolitical friction in Taiwan Strait logistics, regulatory fragmentation across encryption standards, and silicon foundry capacity allocation decisions are the dominant revision risks. Forecasts reflect documented assumptions on technology adoption curves and vendor ecosystem consolidation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
4G Equipment Market
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
5G Radio Unit Market
Telecom Hardware
Base Station Market
Telecom Hardware
Global LTE Modems Market
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
Communication Base Station Equipment Pcb Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
DWDM Transceiver Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
Global Volte Market
Telecom Hardware
Point-To-Point Antenna Market
Telecom Hardware
Global FPGA in Telecom Sector Market
Telecom Hardware
Synchronous Optical Network (SONET) Market
Telecom Hardware
OTN Hardware Market