
 Digital Smart Set-Top Box (STB) Market | 2026-2036
Digital Smart Set-Top Box (STB) Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Smart Set-Top Box (STB) Market Insights
Chinese OEM production is consolidating around Shenzhen and Dongguan electronics corridors, where vertically integrated assembly lines now account for the majority of global STB motherboard fabrication. Samsung Electronics leverages in-house semiconductor foundries to sustain captive chip supply for its premium decoder lines. HUMAX anchors European operator partnerships through Linux-based middleware specialization, while Roku competes aggressively in North American retail channels with its proprietary streaming OS ecosystem.
A digital smart set-top box is a dedicated computing appliance that demodulates broadcast or broadband signals, decodes MPEG-4 AVC or HEVC video streams up to 4K resolution, and renders interactive content through HDMI 2.1 output to television displays. Its commercial purpose centers on bridging legacy broadcast infrastructure with internet protocol delivery, enabling unified access to linear channels and over-the-top services. Hybrid STB configurations now dominate operator procurement cycles as cable and satellite providers seek backward-compatible migration paths. Android-based technology stacks capture the fastest growth trajectory in retail and hospitality segments, though RDK middleware retains strong positioning among North American cable operators prioritizing open-source customization.
The FCC enforces set-top box energy consumption benchmarks and navigation device interoperability rules under 47 CFR Part 76, while the EU Ecodesign Directive mandates maximum active-mode power thresholds through delegated regulations. India's BIS certification scheme requires electromagnetic compatibility testing and safety compliance for all imported STB units. Stakeholders must monitor whether streaming platform exclusivity arrangements trigger renewed antitrust scrutiny from competition authorities in major deployment markets.
Market Dynamics
The hybridization of broadcast and broadband delivery architectures is compressing procurement cycles for pay-TV operators, forcing middleware vendors to support simultaneous DVB-C/DVB-S decoding alongside IP streaming stacks within single-chip SoC designs.
Growth Catalysts
- HEVC codec penetration:Broadcasters in India and Southeast Asia are mandating H.265 compression for 4K channel carriage, forcing legacy MPEG-4 STB replacements.
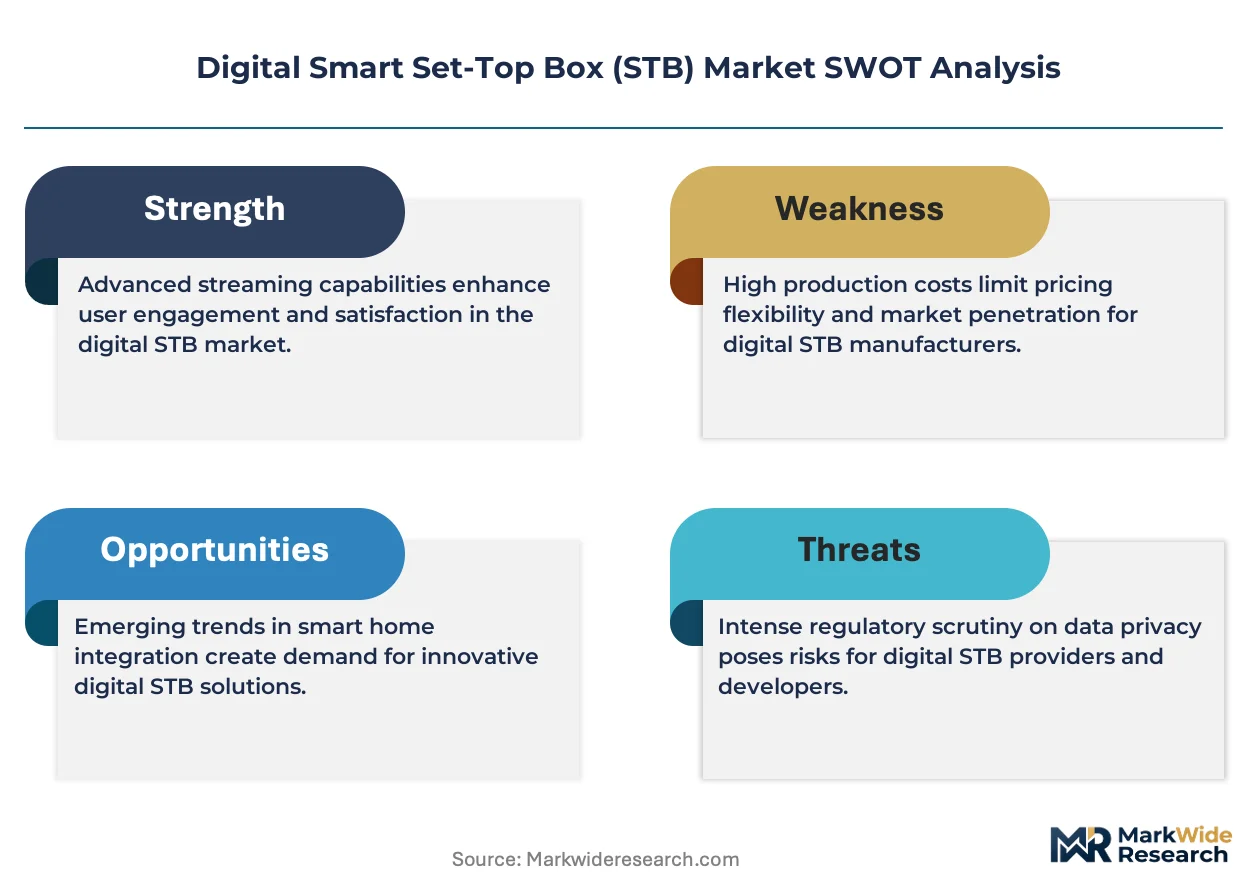
- EU Ecodesign standby limits:The delegated regulation capping standby consumption below 0.5 watts is accelerating power-management semiconductor upgrades across European operator fleets.
- Fiber-to-the-home buildouts:India's BharatNet rural broadband initiative is creating concentrated demand pockets for IP-only STB configurations in tier-2 and tier-3 municipalities.
Market Restraints
- Memory cost volatility:DDR4 and NAND flash pricing fluctuations directly compress margins for Android-based STB manufacturers serving retail channels.
- Shenzhen supply concentration:Over 70 percent of global motherboard fabrication sits within a 50-kilometer corridor, exposing procurement to single-region disruption risks.
- Smart TV native streaming:Television manufacturers embedding Roku, Tizen, and Android TV directly into display panels are eliminating the external decoder use case in North American and European households.
Strategic Opportunities
- Hospitality IPTV underpenetration:Mid-tier hotel chains in Vietnam, Indonesia, and the Philippines still rely on analog RF distribution, creating upgrade whitespace for hybrid STB deployments.
- Android TV Operator Tier licensing:Google's reduced certification friction for operator-customized Android stacks is enabling faster time-to-market for regional pay-TV brands.
- RDK-B middleware convergence:North American cable operators are extending RDK specifications from video to broadband gateway functions, opening single-device CPE consolidation opportunities.
Industry Challenges
- HDCP 2.3 certification bottlenecks:Content protection compliance testing for premium 4K HDR streams is extending product launch timelines by 8-14 weeks at authorized test facilities.
- Legacy SI table interoperability:European cable networks retain proprietary service information formats that fragment middleware development and fragment software maintenance burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Smart Set-Top Box (STB) Market |
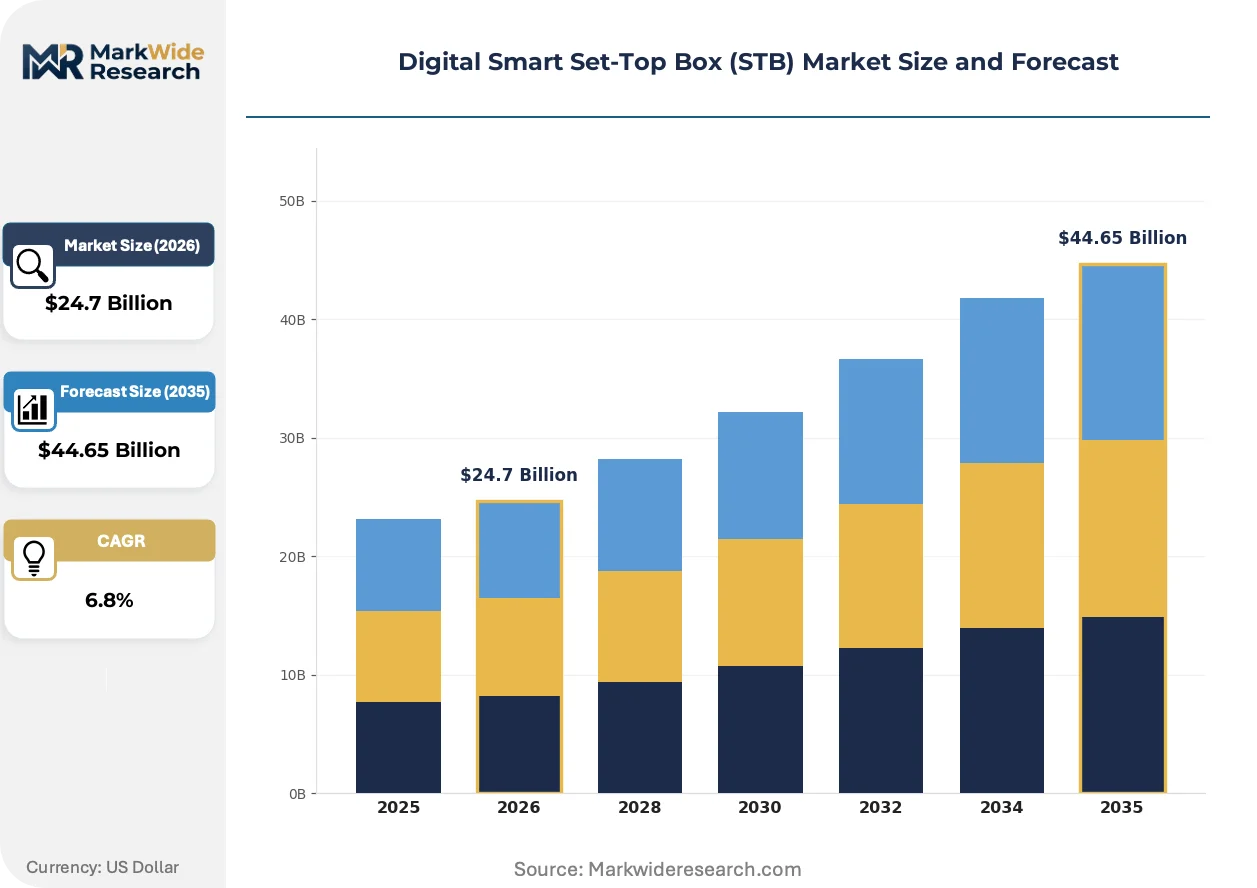
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IPTV STB, OTT STB, Cable STB, Hybrid STB Technology: Android, Linux, RDK, Proprietary End User: Residential, Commercial, Educational, Hospitality Distribution Channel: Retail, Online, Direct Sales, Telecom Operator |
| Companies Covered | Huawei Technologies, Samsung Electronics, CommScope, Roku, HUMAX, Advanced Digital Broadcast, Sagemcom, EchoStar, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Smart Set-Top Box (STB) Market Trends and Innovations
Artificial intelligence inference at the network edge is reshaping how STB processors handle content recommendation, ad insertion, and quality-of-service optimization without round-tripping to cloud data centers.
Edge AI acceleration in ARM Cortex-A55 and A76-based SoCs is automating real-time upscaling of sub-4K streams to display-native resolution, reducing bandwidth consumption for operators. Pay-TV providers in South Korea and Japan are deploying these chipsets for live sports broadcasts where latency constraints prohibit cloud transcoding. The compression of compute requirements onto local silicon is displacing previous-generation external scaler boxes and consolidating functionality within the primary decoder unit.
REACH substance restrictions on cadmium and lead in printed circuit board assemblies are forcing solder composition changes and component requalification across European-bound production lines. The delegated regulation's 2024 enforcement deadline has triggered supply chain audits at Dongguan and Shenzhen assembly facilities serving EU operator contracts. Manufacturers are responding with tin-silver-copper alloy transitions and X-ray inspection protocol upgrades to maintain CE marking eligibility.
Direct-to-consumer streaming aggregation is fragmenting the traditional operator-curated channel bundle as primary content access mode. North American and Western European households are prioritizing app-based discovery over electronic program guide navigation, forcing STB interface redesigns around content search rather than linear scheduling. This behavioral pivot is most visible in retail Android TV device sales through Amazon and Best Buy channels, where voice-controlled cross-app search has become the dominant purchase criterion over tuner specifications.
Digital Smart Set-Top Box (STB) Market Segmentation
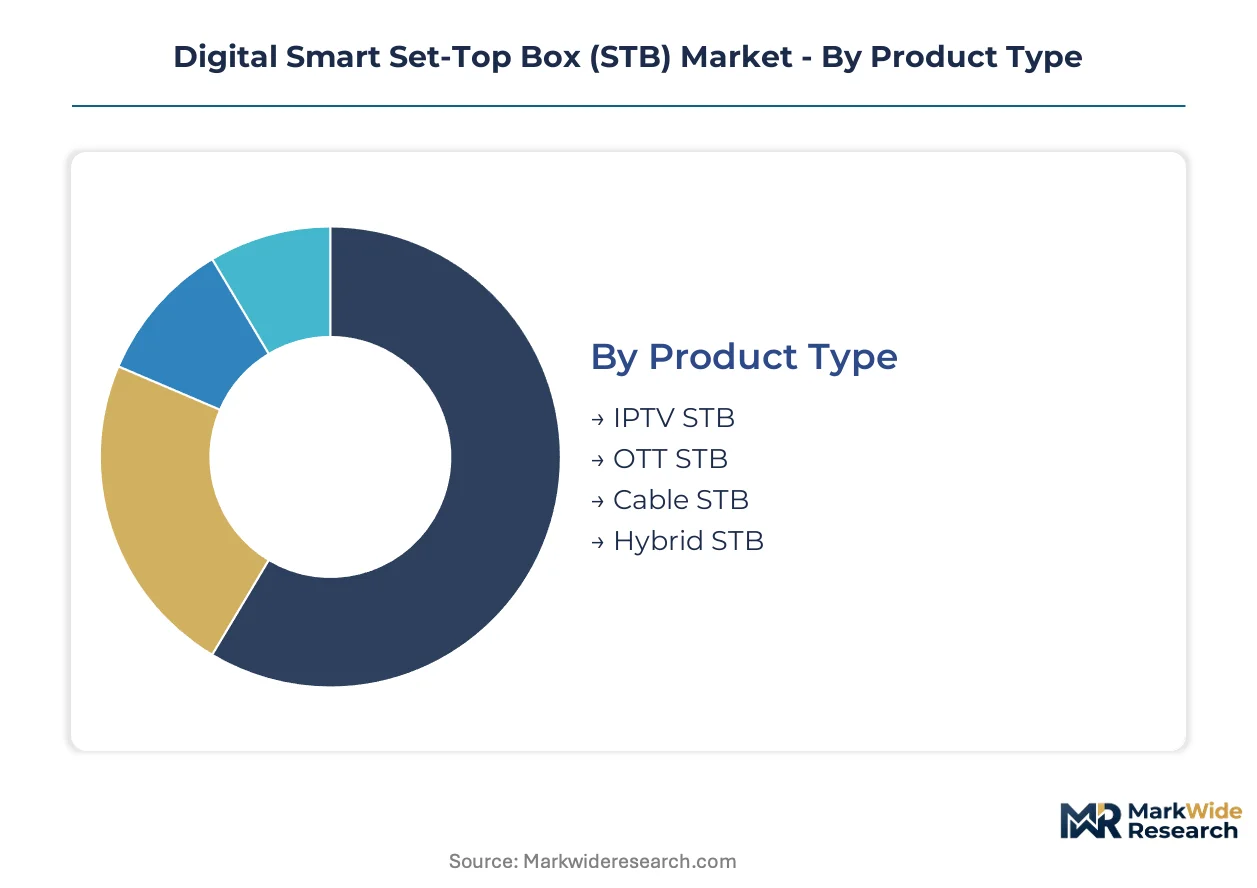
STB procurement patterns diverge sharply between operator-integrated deployments and retail consumer purchases, with middleware compatibility and content protection requirements driving category-specific sourcing decisions. Understanding these segment boundaries clarifies why certain technology stacks dominate specific channels while remaining absent from others.
Product Type:
Integration depth separates standalone decoders from embedded gateway functions, with hybrid architectures now absorbing capabilities that previously required separate devices.
- IPTV STB:IP-only reception hardware delivering multicast and unicast streams over fiber or DSL infrastructure. Indian operators deploying BharatNet infrastructure in tier-2 municipalities are specifying these units for rural broadband extensions where broadcast tuners add unnecessary cost.
- Hybrid STB:Combined DVB-C/DVB-S/DVB-T reception with IP streaming capability within unified chassis designs. European cable operators facing REACH substance compliance deadlines are consolidating procurement around these units to simplify fleet management and reduce certification overhead.
- OTT STB:Broadband-dependent streaming appliances without broadcast tuner modules, optimized for retail channels and hospitality retrofit deployments.
- Cable STB:QAM-modulated signal decoders for legacy coaxial networks, now declining as operators accelerate IP migration.
Volume placements concentrate in Hybrid STB configurations; the faster expansion belongs to IPTV STB as fiber buildouts accelerate.
Technology:
Middleware licensing economics create stark margin differentiation, with open-source stacks enabling operator customization while commercial platforms accelerate retail time-to-market.
- Android:Google's mobile-originated stack adapted for television through Android TV and Google TV interfaces. Retail channels across North America and Western Europe are prioritizing these units for voice-controlled cross-app search capabilities that match consumer navigation preferences.
- RDK:Open-source middleware specification governed by RDK Management for North American cable operator customization. Comcast and Charter Communications are extending RDK specifications into broadband gateway functions, enabling single-device CPE consolidation.
- Linux:Vendor-customized embedded distributions offering maximum operator control over user interface and security policy. HUMAX maintains European market positioning through specialized Linux middleware partnerships.
- Proprietary:Closed ecosystems including Roku OS, Tizen, and vendor-specific stacks optimized for hardware-software integration. Samsung Electronics leverages captive semiconductor supply to sustain proprietary decoder lines.
Operator procurement concentrates in RDK and Linux stacks; Android is climbing the fastest in retail and hospitality segments.
End User:
Application environment dictates durability, remote management, and content protection requirements, with commercial deployments tolerating higher unit costs for centralized control capabilities.
- Residential:Consumer household deployments representing the foundational volume base for retail and operator-subsidized distribution. Smart TV native streaming is eroding external decoder demand in North American and Western European households where display-embedded platforms eliminate separate hardware.
- Hospitality:Hotel, hospital, and institutional deployments requiring centralized content management and guest billing integration. Mid-tier hotel chains in Vietnam, Indonesia, and the Philippines still rely on analog RF distribution, creating upgrade whitespace for hybrid STB deployments with IPTV middleware.
- Commercial:Corporate, retail, and public venue installations including digital signage and waiting room entertainment.
- Educational:Campus and classroom deployments with specific content filtering and administrative control requirements.
Residential volumes dominate unit shipments; hospitality represents the steepest expansion trajectory as analog infrastructure ages out.
Distribution Channel:
Channel structure determines margin capture, with direct operator relationships enabling volume commitments that retail channels cannot match.
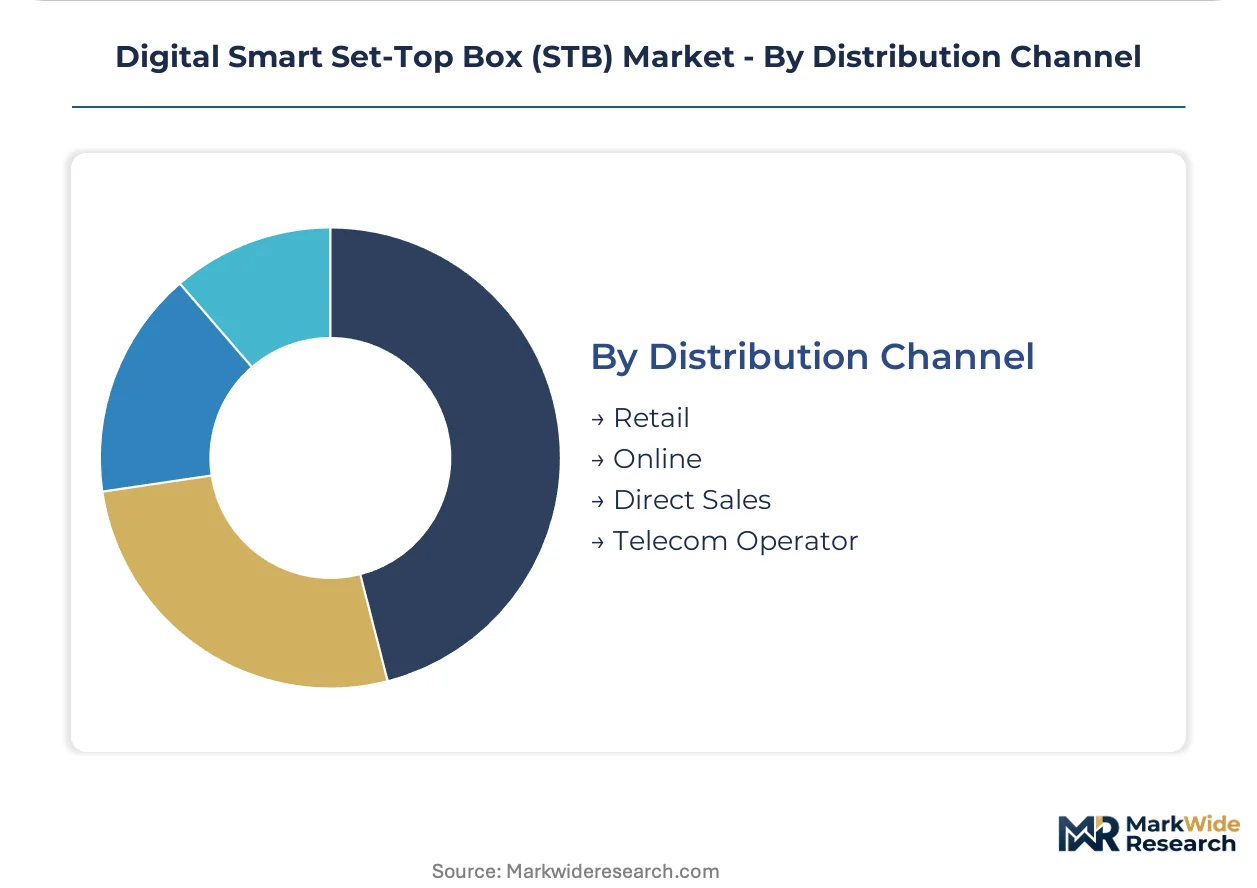
- Telecom Operator:Direct procurement relationships between pay-TV providers and OEM/ODM manufacturers, often with multi-year volume commitments. Reliance Jio's fiber expansion across Indian tier-2 and tier-3 cities is channeling substantial volume through this pathway.
- Retail:Consumer electronics stores and big-box chains including Amazon and Best Buy in North American markets. Memory cost volatility in DDR4 and NAND flash pricing directly compresses margins for Android-based manufacturers serving this channel.
- Direct Sales:Manufacturer-to-enterprise relationships for hospitality and commercial bulk deployments.
- Online:E-commerce platforms serving consumer and small commercial purchasers with reduced logistical overhead.
Telecom operator channels capture the largest volume commitments; online distribution is gaining share fastest as direct-to-consumer streaming aggregation reshapes purchase behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Dongguan electronics corridors anchor motherboard fabrication for this market, with vertically integrated assembly lines concentrating global supply. Operator procurement cycles now compress as fiber buildouts accelerate across multiple geographies.
India
Reliance Jio's fiber expansion and BharatNet rural broadband initiative drive concentrated demand for IP-only STB configurations in tier-2 and tier-3 municipalities. TRAI regulations mandate interoperability standards for set-top boxes, enabling consumer equipment portability across operators. Manufacturing clusters in Noida and Chennai assemble units for domestic operator contracts.
United States
FCC enforcement of 47 CFR Part 76 energy benchmarks and navigation device interoperability rules shapes operator procurement specifications. RDK middleware retains strong positioning among cable operators prioritizing open-source customization. Silicon Valley semiconductor design houses and Austin-based systems integrators supply chipset and software stacks to North American deployments.
China
MIIT standards for digital television broadcasting equipment govern domestic STB certification requirements. Shenzhen and Dongguan electronics corridors account for the majority of global motherboard fabrication through vertically integrated assembly lines. Shanghai and Beijing house R&D centers for next-generation decoder SoC designs.
Germany
EU Ecodesign Directive delegated regulations capping standby consumption below 0.5 watts accelerate power-management semiconductor upgrades across operator fleets. REACH substance restrictions on cadmium and lead force solder composition changes at contract manufacturers. Bavaria and Baden-Württemberg host systems integrators serving Central European cable operators.
South Korea
Live sports broadcast latency constraints drive deployment of ARM Cortex-A55 and A76-based SoCs with edge AI acceleration for real-time upscaling. MFDS electromagnetic compatibility certification applies to imported consumer electronics. Seoul Capital Area semiconductor foundries supply memory and processing components to regional OEM assembly operations.
Digital Smart Set-Top Box (STB) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hospitality IPTV and retail streaming aggregation as adjacent spaces. The vendor base stratifies across captive semiconductor supply, middleware specialization, and retail platform ecosystems. Three archetypes dominate: vertically integrated electronics conglomerates with in-house foundry access, Linux-based middleware specialists serving operator customization requirements, and proprietary streaming OS platforms targeting direct-to-consumer channels. Competitive moves center on RDK-B middleware convergence for broadband gateway consolidation and Android TV Operator Tier licensing to compress certification timelines.
Within the vertically integrated tier, Samsung Electronics anchors positioning through captive semiconductor supply chains. HUMAX GmbH exemplifies European operator partnership models through middleware specialization. Roku, Inc. occupies the retail streaming platform vector with proprietary OS distribution. These three entities represent distinct competitive archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Huawei Technologies |
| Samsung Electronics |
| CommScope |
| Roku |
| HUMAX |
| Advanced Digital Broadcast |
| Sagemcom |
| EchoStar |
| Broadcom |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap ODMs concentrated in Shenzhen and Dongguan electronics corridors anchor motherboard fabrication, translating captive assembly-line control into pricing discipline that resists commodity erosion despite memory cost volatility. Their ownership structure enables long-term operator contract pricing without quarterly earnings pressure, while financing flexibility supports inventory buffering against DDR4 and NAND flash price swings.
Pricing Analysis
Warranty and after-sales service bundling separates operator procurement from retail channel transactions, with multi-year fleet management agreements commanding 15-25% premiums over unbundled hardware. Pricing stratifies across premium 4K HDR units with HDCP 2.3 certification, standard HEVC-compliant configurations, and economy-tier MPEG-4 legacy replacements. Cost compression in Android-based retail segments is intensifying because smart TV native streaming eliminates external decoder use cases in North American households. Hospitality buyers show highest price sensitivity due to bulk procurement scale, while European cable operators prioritize REACH compliance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for operator fleet refreshes create refurbishment revenue streams, with returned STBs from European cable networks feeding secondary markets in Southeast Asia. Motherboard fabrication concentrates in China, Malaysia, and Vietnam, drawing from DDR4 memory modules sourced from South Korean foundries, NAND flash from Taiwanese suppliers, and ARM-based SoCs from US fabless designers. Single-source vulnerability in Shenzhen-Dongguan corridor assembly exposes procurement to regional disruption risks. Distribution runs through direct telecom operator relationships for volume commitments, supplemented by retail channels for consumer purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase where HEVC and AV1 codecs displace legacy MPEG-4 infrastructure, forcing replacement cycles that favor silicon-integrated suppliers over pure-play hardware assemblers.
For Market Incumbents: Deploy RDK-B middleware convergence as the primary lever to consolidate broadband gateway and video decoder functions into single CPE units, reducing operator procurement complexity. Deepen backward integration into power-management semiconductor design to meet EU Ecodesign standby limits below 0.5 watts without margin sacrifice. Smart TV native streaming poses existential substitution threat; counter with hospitality IPTV specialization where display-embedded platforms lack centralized management capabilities. For New Entrants and Emerging Players: The 40-60% price-point gap between premium Android TV Operator Tier deployments and economy-tier Linux-based operator units creates entry whitespace for mid-tier hybrid STB specialists. Target Vietnam, Indonesia, and Philippines hospitality retrofits where analog RF distribution still dominates mid-tier hotel chains. Pursue Google's reduced-certification Android TV Operator Tier pathway to compress time-to-market against established Linux middleware incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor ODMs with captive Shenzhen-Dongguan assembly capacity and active EU operator contracts facing REACH substance compliance deadlines. Long-term viability hinges on silicon-design capabilities rather than pure hardware integration, positioning ARM-based SoC integrators favorably across the next decade. Monitor TRAI interoperability mandate enforcement in India as inflection indicator for operator equipment portability and hardware-agnostic platform plays.| Strategic Initiative | Industry Significance |
|---|---|
| Android TV Operator Tier Certification | Google's streamlined pathway accelerates regional pay-TV brand deployment timelines against RDK incumbents. |
| RDK-B Middleware Convergence | Comcast and Charter specifications enable single-device CPE consolidation across North American cable footprints. |
| Edge AI SoC Integration | ARM Cortex-A55 and A76 chipsets with neural acceleration displace external scaler boxes for live sports latency requirements. |
| REACH Substance Compliance Transition | Tin-silver-copper solder requalification maintains CE marking eligibility for European-bound production lines. |
| Hospitality IPTV Platform Deployment | Centralized content management integration captures upgrade whitespace in Vietnam and Philippines hotel chains. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with pay-TV operator procurement directors, ODM manufacturing executives, semiconductor distributor account managers, and hospitality technology integrators. FCC 47 CFR Part 76 filings, EU Ecodesign delegated regulations, TRAI interoperability standards, and MIIT certification databases provided compliance benchmarking. Bottom-up unit shipment estimates triangulated against top-down operator capex disclosures.
Data-stream reconciliation across operator procurement databases, retail channel sell-through reports, and component supplier order books enabled volume and value modeling across the projection horizon. Segmentation dimensions included product type integration depth, middleware technology stack, end-user application environment, and distribution channel structure. CAGRs derived from regression analysis of historical replacement cycles, fiber buildout trajectories, and codec transition timelines, with specific inputs from BharatNet rural broadband deployment schedules and EU energy regulation phase-in dates.
Inputs from operator procurement directors and ODM manufacturing executives were available through the study window; gaps in hospitality IPTV deployment data and emerging market operator capex plans introduce uncertainty bands around Southeast Asia expansion rates. Forecasts reflect assumptions regarding HEVC mandate enforcement timing, smart TV penetration curves, and memory pricing normalization. Practitioners should monitor TRAI interoperability implementation, EU REACH substance restriction enforcement, and RDK Management specification updates for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Africa Small Cell Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
LPWAN Market
Telecom Hardware
Very Small Aperture Terminal (VSAT) Market
Telecom Hardware
Base Station Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
Point-To-Point Antenna Market
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
Communication Base Station Equipment Pcb Market
Telecom Hardware
Industrial Transceivers Market
Telecom Hardware
5G Radio Unit Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Global LTE Modems Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Global Time Sensitive Networking Market