
 Subscriber Identity Module (SIM) Market | 2026-2036
Subscriber Identity Module (SIM) Market Size, Share, and Industry Trends Forecast 2026-2036
Subscriber Identity Module (SIM) Market Analytics
Subscription-based eSIM provisioning is rebalancing what carriers and chip vendors monetize, shifting revenue from hardware units toward recurring platform fees. Thales Group leverages its secure element manufacturing scale to anchor European telecom operator contracts. Giesecke+Devrient competes through specialized government and defense-grade SIM certifications. Apple Inc. controls end-user activation flows through proprietary eSIM interfaces in its device ecosystem.
A Subscriber Identity Module is a removable or embedded smart card containing an integrated circuit that stores an international mobile subscriber identity (IMSI) number and related cryptographic keys for network authentication, typically manufactured through micromodule embedding or wafer-level chip-scale packaging for embedded variants. Its primary commercial purpose is to enable secure subscriber authentication across cellular networks while supporting over-the-air profile management. The eSIM segment leads product type value generation as automotive OEMs and industrial IoT deployers adopt soldered form factors that eliminate physical swap requirements. NFC-enabled SIM technology differentiates payment and transit applications, though GSM-based regular SIM cards still occupy substantial volume in cost-sensitive retail channels across developing markets.
The GSM Association sets technical specifications for remote SIM provisioning that shape product interoperability requirements across carrier networks. ETSI standards for embedded universal integrated circuit cards constrain form factor miniaturization and security certification pathways for semiconductor vendors. In Europe, the EU Cybersecurity Act and RED certification frameworks mandate baseline resilience for connected devices using integrated SIM architectures. Stakeholders must monitor whether regional fragmentation in eSIM certification timelines creates divergent go-to-market costs for chipset suppliers serving multiple regulatory jurisdictions.
Market Dynamics
Remote SIM provisioning standards from the GSM Association are compressing carrier authentication infrastructure into software-defined platforms, eliminating physical card logistics while redistributing value from hardware manufacturers toward subscription orchestration services.
Growth Catalysts
- Automotive eSIM mandates:Vehicle OEMs in Germany and Japan are embedding soldered SIM modules to enable over-the-air firmware updates and emergency call systems.
- MIIT interoperability testing:China's Ministry of Industry and Information Technology requires integrated SIM chipset certification, accelerating domestic supplier consolidation.
- Industrial IoT fleet deployments:Manufacturing and logistics operators across Brazil and Mexico are adopting eSIM for asset tracking devices that must survive harsh field conditions without physical access.
Market Restraints
- Secure element foundry concentration:Advanced packaging capacity for tamper-resistant chips concentrates among three semiconductor fabrication clusters in Taiwan and South Korea.
- Legacy M2M protocol fragmentation:Existing machine-to-machine installations using proprietary remote provisioning systems resist migration to GSMA standards.
- Input cost volatility:Silicon wafer prices and noble metal contacts for contact-based SIM interfaces fluctuate with energy-intensive smelting operations in China.
Strategic Opportunities
- India's PLI scheme for semiconductors:Production-linked incentives for domestic chip assembly create localized manufacturing alternatives to import-dependent supply chains.
- Convergence of eSIM and satellite connectivity:Direct-to-device satellite messaging services are integrating embedded SIM authentication for off-grid emergency communications.
- Healthcare device authentication:Remote patient monitoring systems in the United States require cellular-enabled wearables with secure identity modules for HIPAA-compliant data transmission.
Industry Challenges
- Certification timeline compression:Common Criteria EAL4+ security evaluations for government-grade SIM products require 18-24 months, delaying product launches.
- Multi-profile orchestration complexity:Enterprise IT departments struggle to manage simultaneous carrier profiles across thousands of deployed IoT endpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subscriber Identity Module (SIM) Market |
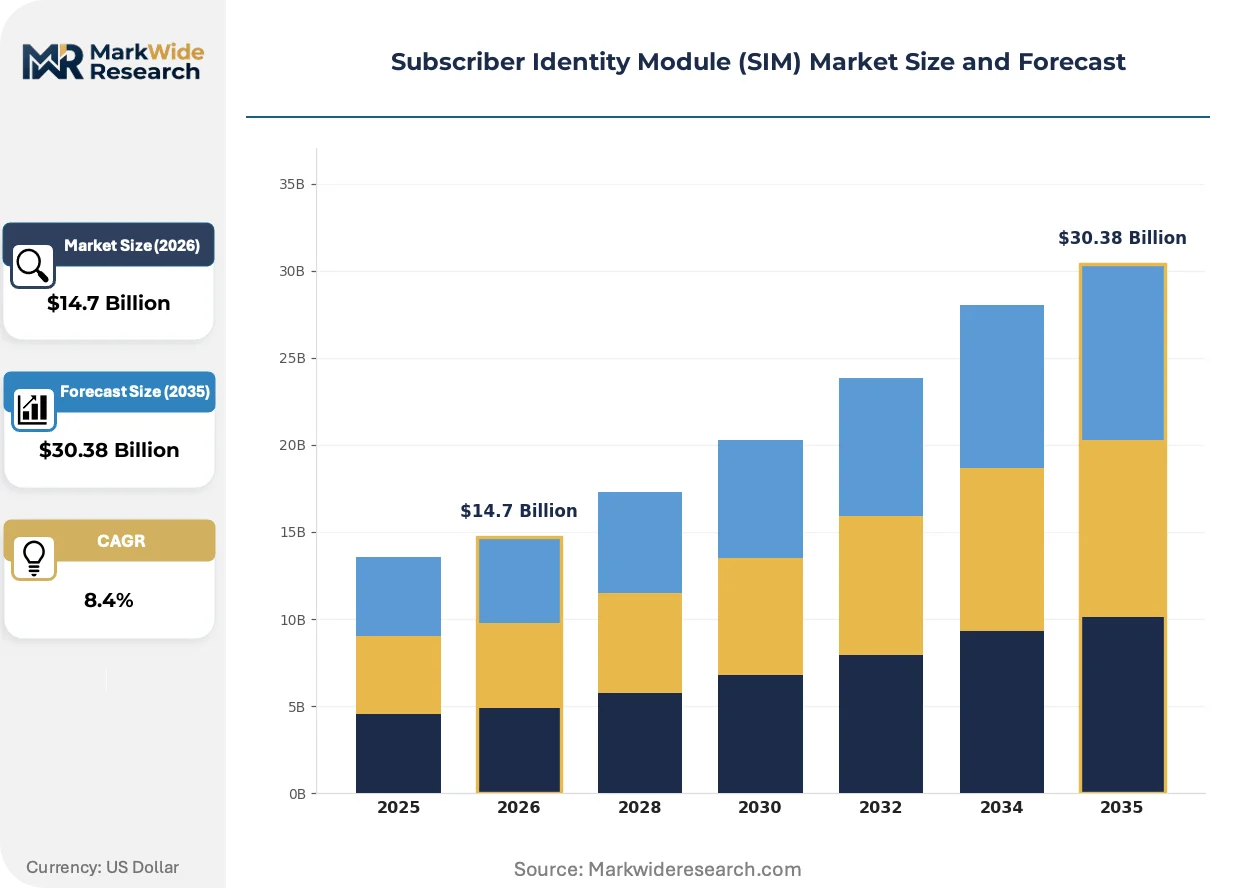
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.38 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular SIM, eSIM, iSIM, Multi-SIM Technology: NFC, GSM, CDMA, USIM End User: Telecom Operators, Enterprises, OEMs, Retailers Application: Mobile Communication, IoT Solutions, M2M, Wearables |
| Companies Covered | Giesecke+Devrient, Thales Group, STMicroelectronics, NXP Semiconductors, Infineon Technologies, Gemalto, Apple Inc., Sequans Communications, Telit Cinterion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subscriber Identity Module (SIM) Market Evolving Landscape
Zero-touch provisioning architectures are eliminating manual intervention from subscriber onboarding, compressing carrier operational costs while enabling dynamic carrier switching. Three developments define this transformation.
Integrated Universal Integrated Circuit Card (iUICC) technology is automating the migration of SIM functionality from discrete hardware into system-on-chip designs. Automotive Tier 1 suppliers in Germany and Japan are adopting iUICC for next-generation telematics control units. This consolidation is automating the elimination of separate SIM component procurement, inventory, and assembly steps from vehicle manufacturing lines.
The EU Cybersecurity Act and Radio Equipment Directive certification frameworks now mandate baseline resilience standards for connected devices using integrated SIM architectures. Semiconductor vendors must demonstrate resistance to side-channel attacks and fault injection. European telecom operators are responding by pre-certifying chipset platforms to accelerate device manufacturer time-to-market.
Enterprise procurement of cellular connectivity is fragmenting from single-carrier contracts toward multi-IMSI platform subscriptions. Fleet managers in logistics and agriculture now source connectivity through specialized IoT MVNOs rather than direct MNO relationships. This shift is most visible in the United States, where agricultural equipment OEMs bundle connectivity as a service rather than as a hardware component sale.
Subscriber Identity Module (SIM) Market Segmentation
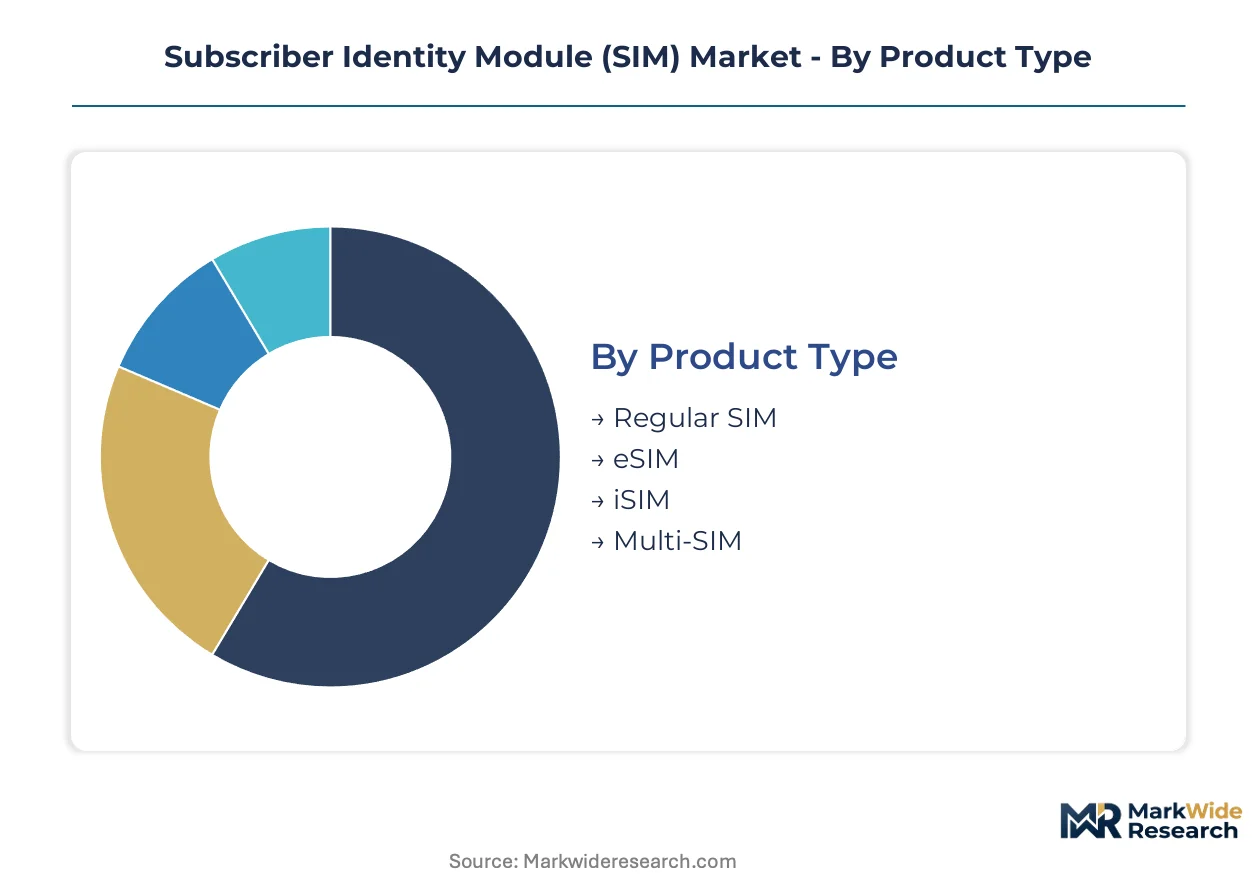
SIM market segmentation reveals how authentication hardware fragments across removable, embedded, and fully integrated deployment models. Each product architecture carries distinct supply chain implications, certification pathways, and margin profiles that reshape vendor competitive positioning.
Product Type:
Integration depth separates standalone removable cards from soldered and system-on-chip implementations, with each tier demanding different manufacturing scale and security certification intensity.
- eSIM:Embedded chips in MFF2 and smaller form factors enable remote profile provisioning without physical access. Automotive OEMs in Germany and Japan specify soldered eSIM for telematics units, driven by GSMA remote provisioning standards that eliminate supply chain logistics for physical card distribution.
- iSIM:Integrated Universal Integrated Circuit Card functionality migrates SIM operations directly into cellular baseband or application processors. This architecture attracts smartphone manufacturers seeking to reclaim PCB space and simplify bill-of-materials management, constrained by Common Criteria EAL4+ certification timelines.
- Regular SIM:Removable UICC cards in mini, micro, and nano form factors persist in prepaid retail channels and developing market subscriber acquisition.
- Multi-SIM:Dual or triple SIM configurations serve subscriber segments managing multiple carrier relationships for cost arbitrage or coverage optimization.
Regular SIM leads volumes today; iSIM is gaining share fastest.
Technology:
Protocol generation and contactless capability define security architecture and interoperability requirements across carrier network generations.
- USIM:Universal Subscriber Identity Module cards support 3G, 4G, and 5G authentication algorithms with enhanced key length and mutual authentication protocols. Network operators in South Korea and Japan mandate USIM for advanced network access, driven by 5G standalone core deployments requiring stronger cryptographic guarantees than legacy GSM authentication.
- NFC:Near-field communication-enabled SIMs host secure element applications for contactless payment and transit credential storage. Demand concentrates in urban transit authorities and mobile wallet providers, constrained by secure element foundry capacity concentration in Taiwan and South Korea.
- GSM:Legacy 2G authentication technology persists in machine-to-machine installations and cost-optimized IoT endpoints.
- CDMA:Remnant technology serving specialized operator networks and certain legacy industrial telemetry systems.
GSM anchors installed base volumes; USIM demonstrates the steepest expansion trajectory.
End User:
Procurement authority and technical integration responsibility determine contract structure, with direct carrier relationships differing sharply from OEM-embedded sourcing models.
- OEMs:Original equipment manufacturers in automotive, consumer electronics, and industrial equipment embed SIM functionality during product assembly. Vehicle manufacturers specify eSIM for emergency call mandates and over-the-air update capability, with procurement shifting toward multi-IMSI platform subscriptions rather than single-carrier contracts.
- Telecom Operators:Mobile network operators remain the primary volume channel for consumer SIM distribution, though their role diminishes as OEMs and enterprises intermediate connectivity procurement.
- Enterprises:Fleet managers and industrial operators source connectivity through specialized IoT MVNOs for asset tracking and remote monitoring deployments.
- Retailers:Physical and digital distribution channels serve prepaid subscriber acquisition and replacement SIM demand.
Telecom operators lead volumes today; OEMs are climbing the fastest as embedded connectivity standardizes.
Application:
Use case environment and device lifecycle expectations drive form factor selection, with stationary infrastructure tolerating different authentication architectures than mobile or wearable deployments.
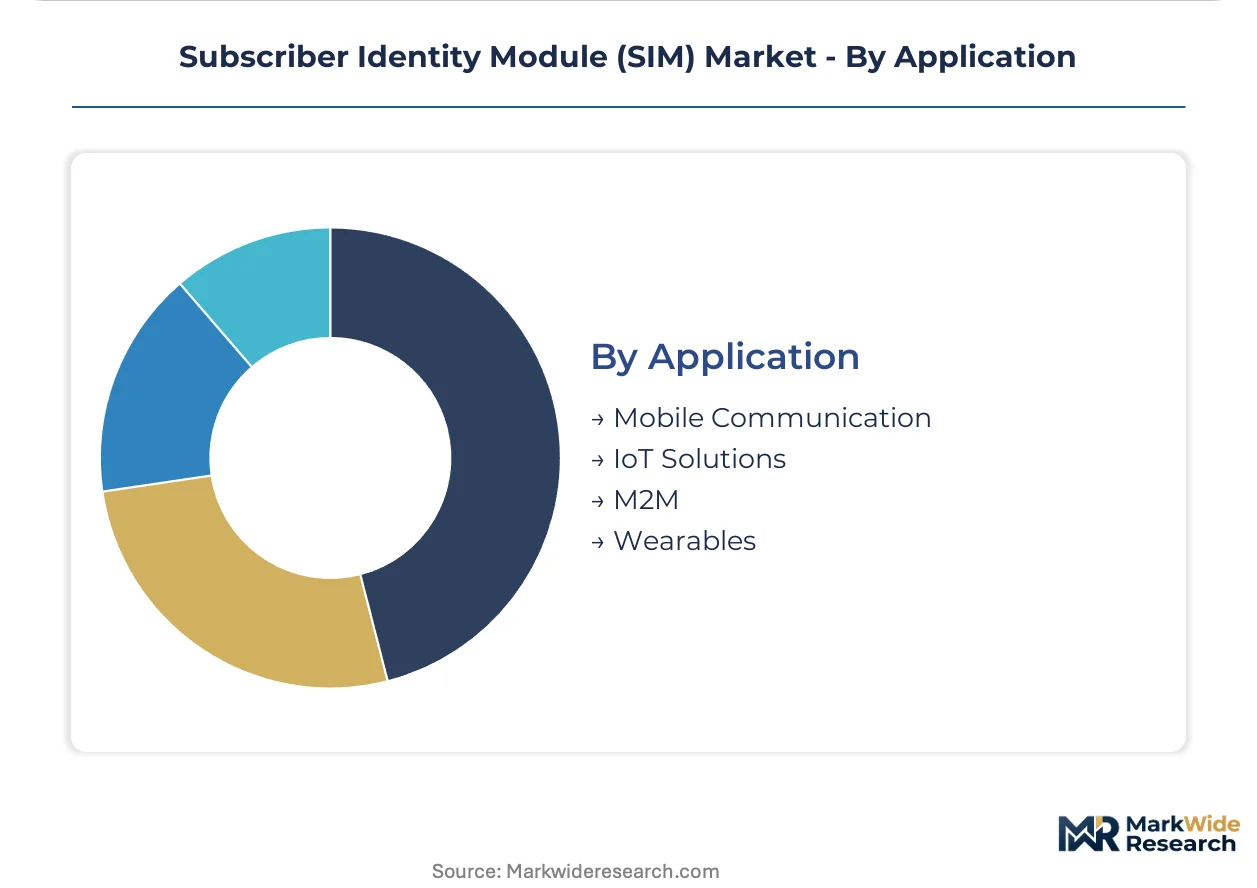
- IoT Solutions:Industrial sensors, smart meters, and agricultural monitors require ruggedized embedded SIMs surviving temperature extremes and vibration without physical service access. Brazil and Mexico manufacturing operators specify eSIM for asset tracking devices deployed across harsh field conditions.
- Mobile Communication:Smartphone and tablet connectivity remains the volume foundation, though subscriber identity is increasingly virtualized through eSIM and iSIM architectures.
- M2M:Machine-to-machine installations using proprietary remote provisioning systems resist migration to GSMA standards, fragmenting the addressable market for standardized embedded solutions.
- Wearables:Smartwatches and health monitoring devices demand the smallest form factors and lowest power consumption, pushing toward iSIM integration.
Mobile communication leads volumes today; IoT solutions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT certification mandates accelerate domestic supplier consolidation while Germany's automotive OEMs embed soldered eSIM for telematics standardization. These divergent regulatory paths illustrate how national industrial policy shapes authentication hardware deployment trajectories.
China
Industrial IoT fleet operators and smart meter deployers drive integrated SIM chipset procurement. MIIT mandates interoperability testing for iUICC designs, compressing supplier qualification timelines. Shenzhen and Shanghai semiconductor clusters concentrate advanced packaging capacity for tamper-resistant secure elements.
Germany
Automotive OEMs specify eSIM modules for emergency call systems and over-the-air firmware updates. The EU Cybersecurity Act and RED certification frameworks mandate baseline resilience for connected vehicle architectures. Munich and Stuttgart telematics engineering centers anchor Continental and Bosch Tier 1 supplier integration programs.
United States
Healthcare device manufacturers and agricultural equipment OEMs procure cellular-enabled wearables requiring HIPAA-compliant authentication modules. FCC equipment authorization rules govern integrated SIM transmitter certification for medical and industrial endpoints. California's remote patient monitoring startups and Midwest agricultural IoT deployers source connectivity through specialized MVNO platforms.
Japan
Automotive manufacturers and consumer electronics OEMs adopt iUICC architectures for PCB space optimization. METI standards for connected vehicle security shape embedded SIM certification requirements. Nagoya and Tokyo semiconductor design houses collaborate with baseband processor vendors on system-on-chip integration.
India
Domestic mobile handset assembly and industrial IoT pilot programs stimulate UICC demand. The PLI scheme for semiconductors incentivizes localized chip packaging and testing capacity. Karnataka and Telangana electronics manufacturing clusters attract SIM micromodule embedding operations from import-dependent supply chains.
Subscriber Identity Module (SIM) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with secure element foundries and remote provisioning platform operators occupying distinct value chain tiers. The vendor base concentrates among semiconductor fabrication clusters in Taiwan and South Korea for advanced tamper-resistant packaging, while software-defined provisioning services fragment across carrier-owned and independent platform providers. Three archetypes dominate: secure element manufacturers with Common Criteria certification, remote SIM orchestration platform operators, and integrated device OEMs controlling end-user activation flows. Competitive moves center on pre-certification of chipset platforms to accelerate device manufacturer time-to-market, and strategic partnerships between automotive Tier 1 suppliers and telecom operators for embedded connectivity bundling.
Among European secure element specialists, Thales Group and Giesecke+Devrient occupy positions anchoring carrier contract structures. Thales leverages its manufacturing scale across European telecom operator relationships, while Giesecke+Devrient exemplifies the defense-grade certification specialist archetype through government and high-assurance market focus. Apple Inc. represents the integrated OEM vector, controlling end-user activation flows through proprietary eSIM interfaces within its device ecosystem and displacing traditional carrier-mediated provisioning relationships.
| Leading Market Players |
|---|
| Giesecke+Devrient |
| Thales Group |
| STMicroelectronics |
| NXP Semiconductors |
| Infineon Technologies |
| Gemalto |
| Apple Inc. |
| Sequans Communications |
| Telit Cinterion |
| Others |
Value Network & Pricing Analysis
Silicon wafer costs feed directly into eSIM module pricing tiers, with Taiwanese foundry capacity utilization determining contract premiums for automotive-grade secure elements before downstream bundling into telematics subscription packages.
Pricing Analysis
Capacity additions in India's semiconductor assembly corridors are reshaping price floors for mid-tier UICC products while premium eSIM segments retain margin insulation through Common Criteria certification requirements. Pricing stratifies across defense-grade EAL4+ modules, commercial automotive soldered chips, and economy prepaid removable cards. Cost compression in standard-grade removable SIMs intensifies because Chinese micromodule embedding operations achieve scale efficiencies. Retail distributors exhibit highest price sensitivity, whereas German automotive OEMs prioritize supply assurance over unit cost.
Supply Chain Analysis
Reverse logistics for defective secure elements flows through specialized refurbishment centers in Taiwan and South Korea, recovering noble metal contacts for reprocessing into new contact-based SIM interfaces. Raw material dependencies include silicon wafers from Japanese suppliers, noble metals from Chinese smelters, and epoxy molding compounds from South Korean chemical producers. Single-source vulnerability concentrates in advanced packaging capacity at three Taiwanese foundry clusters. Distribution runs through carrier procurement divisions for consumer segments and direct Tier 1 supplier contracts for automotive embedding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SIM market represents a late-cycle quality story as automotive OEMs and industrial IoT deployers shift procurement criteria from per-unit hardware cost toward guaranteed certification pedigree and remote provisioning reliability.
For Market Incumbents: Deploy pre-certification partnerships with automotive Tier 1 suppliers to lock in telematics platform selection before competitor qualification cycles complete. Accelerate iUICC integration roadmaps to capture PCB space consolidation in smartphone designs. Counter emerging fabless secure element challengers by deepening foundry relationships at Taiwanese packaging clusters. Resist margin erosion in prepaid removable cards through channel exclusivity arrangements with African and Southeast Asian distributors. For New Entrants and Emerging Players: Agricultural equipment OEMs in the American Midwest represent an underserved buyer archetype seeking bundled connectivity-as-service rather than component procurement. Penetrate Brazil's industrial IoT asset tracking segment by specializing in eSIM modules rated for extreme temperature and vibration tolerance. Pursue certification shortcuts through partnerships with established Common Criteria laboratories to compress 18-month evaluation timelines. Target India's PLI scheme beneficiaries with localized micromodule embedding services to circumvent import dependency. For Investors and Strategic Acquirers: Consolidation pressure builds where remote SIM provisioning platform operators lack captive secure element manufacturing and face margin compression from carrier self-provisioning investments. Frame long-term viability around 5-10 year horizon authentication hardware demand from connected vehicle mandates and healthcare HIPAA compliance requirements. Prioritize acquisition targets with dual-use government-commercial certification capabilities and established GSMA standards compliance. Monitor MIIT certification timeline acceleration in China as inflection indicator for domestic supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Provisioning Platform Integration | Enables Thales and Giesecke+Devrient to capture recurring subscription revenue from automotive OEM telematics contracts. |
| iUICC System-on-Chip Partnership | Allows STMicroelectronics and NXP to displace discrete SIM components in smartphone baseband processor designs. |
| Common Criteria EAL4+ Pre-Certification | Accelerates German automotive Tier 1 supplier time-to-market for emergency call system mandates. |
| PLI Scheme Localized Assembly Investment | Positions entrants to serve India's domestic handset manufacturing and industrial IoT pilot programs. |
| Multi-IMSI Orchestration Platform Launch | Supports specialized IoT MVNOs in the United States bundling connectivity for agricultural equipment fleets. |
Research Methodology
Multiple input streams — executive interviews with secure element procurement leads at European automotive Tier 1 suppliers, technical consultations with GSMA standards working group participants, and regulatory filings with China's MIIT certification database — were reconciled against secondary validation from semiconductor trade data, ETSI specification documents, and carrier remote provisioning platform disclosures. Primary engagement spanned secure element manufacturing directors, telecom operator IoT platform managers, and industrial fleet connectivity procurement officers. Bottom-up demand modeling triangulated against top-down market sizing from cellular module shipment aggregates.
Data-stream reconciliation applied across the projection horizon linked installed base estimates for connected vehicles, smartphone eSIM adoption curves, and industrial IoT endpoint deployment trajectories. Segmentation dimensions modeled include product architecture depth (removable, embedded, integrated), certification grade tier, end-use industry vertical, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to technology substitution patterns. Forecast inputs incorporated MIIT certification timeline acceleration, EU Cybersecurity Act enforcement phasing, and automotive emergency call mandate implementation schedules.
Underlying measurement precision varies by segment; automotive eSIM volumes carry tighter precision than emerging iSIM smartphone adoption given established OEM procurement visibility. Forecasts reflect assumptions regarding GSMA standards migration completion, foundry capacity expansion timing, and carrier self-provisioning platform investment intensity. Practitioners should monitor MIIT supplier qualification announcements, EU RED certification backlog releases, and Indian PLI scheme beneficiary designations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
5G BTS Antenna Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
Digital TV Soc Market
Telecom Hardware
Global FPGA in Telecom Sector Market
Telecom Hardware
Satellite Communication Terminal Market
Telecom Hardware
Global Ultra Portable Internet Device Market
Telecom Hardware
LPWAN Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Commercial Antennas Market
Telecom Hardware
United States Set-Top Box Market
Telecom Hardware
Set-Top Box Market
Telecom Hardware
Global Volte Market