
 Microwave Antenna Market | 2026-2036
Microwave Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Microwave Antenna Market Foresight
A shift from single-source to multi-source procurement is rebalancing supply relationships across the microwave antenna value chain. CommScope leverages its manufacturing scale to secure carrier-grade contracts in North America. Tongyu Communication anchors its position through cost-optimized parabolic antenna production for emerging markets. Radio Frequency Systems differentiates via specialized high-frequency assemblies for defense applications.
A microwave antenna converts electromagnetic energy between guided wave structures and free space, typically operating in the 1 GHz to 300 GHz range with gains from 10 dBi to over 40 dBi depending on aperture geometry and surface precision. These devices enable long-haul backhaul, radar target illumination, and satellite uplink/downlink functions across civil and military infrastructure. Parabolic antennas retain the largest installed base due to proven reliability in point-to-point links, though phased array technology is displacing mechanically steered systems in radar and satellite terminals where beam agility commands premium pricing. Horn antennas occupy a mature niche in test and measurement laboratories, while microstrip configurations sustain growth in space-constrained aerospace platforms.
The FCC governs spectrum allocation and equipment authorization for microwave links in the United States, directly constraining antenna bandwidth and power density specifications. ETSI harmonizes cross-border standards within Europe, reducing certification fragmentation for vendors serving multiple member states. China's MIIT and GB standards mandate domestic testing protocols that shape product design cycles for suppliers targeting base station deployment. Stakeholders must monitor spectrum auction schedules and evolving national security review thresholds to align R&D roadmaps with accessible addressable markets.
Market Dynamics
Spectrum reallocation mandates from the FCC and China's MIIT are compressing design cycles and forcing antenna manufacturers to requalify products across multiple frequency bands simultaneously.
Growth Catalysts
- 5G backhaul densification:Mobile network operators in India and Southeast Asia deploy microwave links to connect small cells where fiber deployment proves uneconomical.
- Rural broadband mandates:Government subsidy programs in Brazil and South Africa prioritize wireless backhaul over terrestrial infrastructure for last-mile connectivity.
- Defense modernization budgets:Phased array technology adoption accelerates in military radar and electronic warfare platforms requiring beam-steering agility.
Market Restraints
- Aluminum and copper price volatility:Raw material cost swings compress margin buffers for parabolic antenna manufacturers dependent on stamped metal reflectors.
- GaN substrate supply concentration:Gallium nitride wafer production clusters in Japan and the United States, creating chokepoints for high-power amplifier integration.
- Millimeter-wave atmospheric attenuation:Rain fade and oxygen absorption limit reliable link distances above 30 GHz, constraining E-band deployment.
Strategic Opportunities
- Low Earth orbit ground terminals:Constellation operators require flat-panel phased arrays for consumer broadband, creating volume demand absent in traditional telecom.
- India's BharatNet Phase 3:The rural broadband program specifies microwave backhaul for gram panchayat connectivity, opening procurement windows for cost-optimized equipment.
- AI-driven RF optimization:Machine learning algorithms embedded in antenna control units enable real-time beam adaptation, differentiating premium product tiers.
Industry Challenges
- Multi-band certification complexity:Equipment vendors must navigate simultaneous FCC Part 101, ETSI EN 302 217, and MIIT SRRC testing protocols, extending time-to-market.
- Electromagnetic compatibility integration:Co-site interference mitigation between 5G massive MIMO and microwave backhaul requires specialized filter design expertise in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwave Antenna Market |
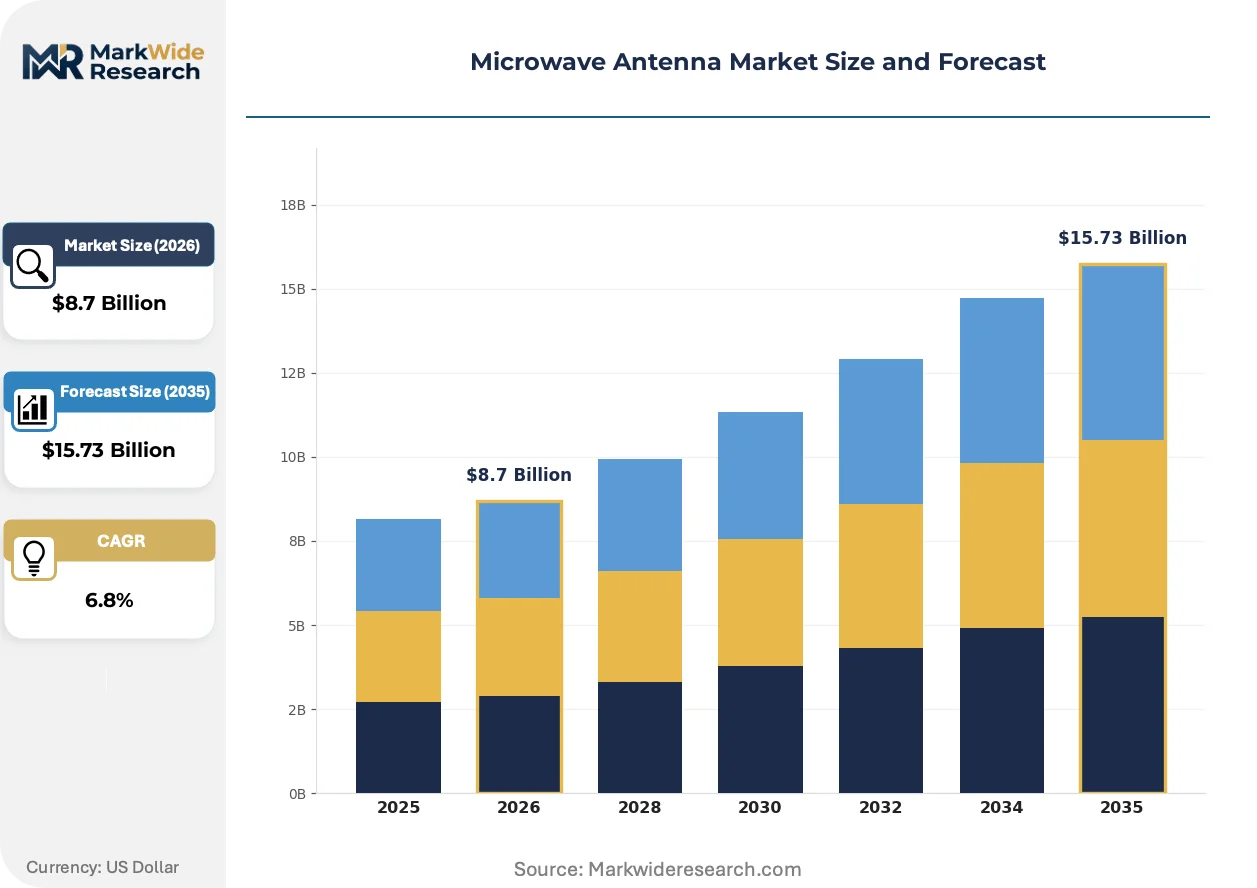
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parabolic Antennas, Horn Antennas, Microstrip Antennas, Reflective Antennas Technology: Passive Technology, Active Technology, Phased Array Technology, Smart Technology End User: Aerospace, Telecommunications, Military, Research Institutions Application: Satellite Communication, Point-to-Point Communication, Radar Systems, Remote Sensing |
| Companies Covered | Alaris mWAVE, Radio Frequency Systems, CommScope, Tongyu Communication, Wireless Excellence, Rosenberger, Shenglu, Comba Telecom, RadioWaves, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwave Antenna Market Shifts & Advancements
Active electronically scanned arrays are migrating from defense-exclusive applications into commercial satellite and backhaul markets, compressing the traditional dominance of mechanically steered parabolic systems.
Phased array architectures are electrifying antenna performance benchmarks. These systems enable microsecond beam steering without mechanical rotation. Satellite terminal manufacturers and 5G infrastructure vendors adopt the technology for tracking non-geostationary constellations and dynamic load balancing. The shift is electrifying demand for compound semiconductor foundry capacity and thermal management subsystems.
ETSI's harmonized standard EN 302 217 now mandates stricter spurious emission limits for point-to-point equipment. Manufacturers must redesign filter architectures and power amplifier bias networks to comply. The constraint bites hardest on vendors serving cross-border European links, forcing portfolio consolidation around modular platforms.
Carrier procurement departments now unbundle installation and maintenance from equipment purchases, treating antennas as capital commodities while sourcing services through separate MSO contracts. This bifurcation pressures OEMs to develop certified installer networks or cede margin to systems integrators. The pattern is most pronounced in India's tower company market, where Indus Towers and ATC India standardize on multi-vendor interoperability.
Microwave Antenna Market Segmentation
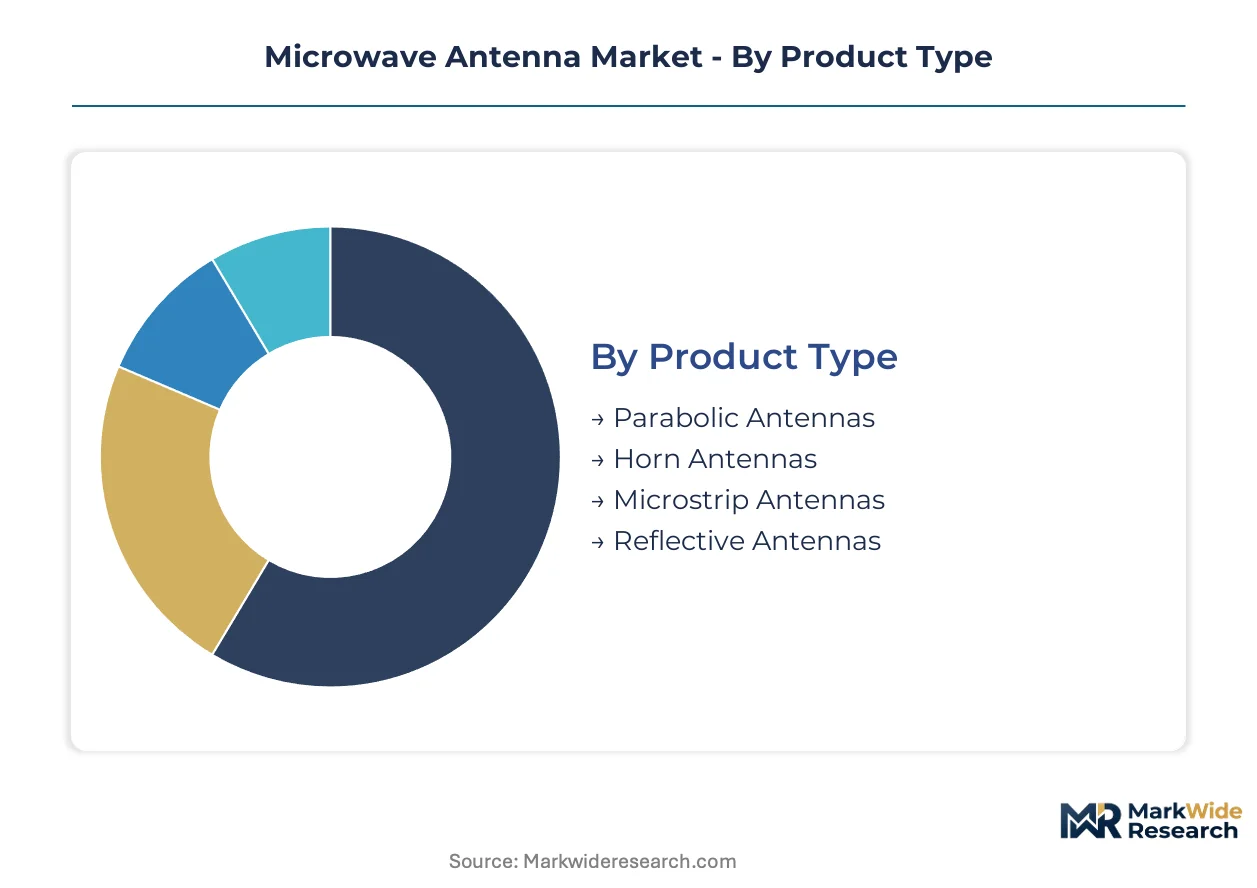
Microwave antenna procurement diverges sharply across certification regimes. Product architecture determines whether equipment faces FCC Part 101, ETSI EN 302 217, or MIIT SRRC testing protocols. Segment-specific technical requirements reshape vendor R&D allocation and geographic market access.
Product Type:
Parabolic and horn antenna configurations carry distinct certification burdens under FCC Part 101 and ETSI EN 302 217 spurious emission limits. Surface precision tolerances and aperture geometry dictate testing complexity for each form factor.
- Parabolic Antennas:These dish-shaped reflectors concentrate electromagnetic energy through precise curvature geometry, typically achieving gains exceeding 30 dBi. Demand concentrates in India's BharatNet rural backhaul deployments where cost-optimized stamped aluminum reflectors meet subsidy program specifications. FCC and ETSI requalification pressures compress design cycles for multi-band variants.
- Horn Antennas:Flared waveguide terminations provide broadband impedance matching with predictable radiation patterns. Research institutions and defense calibration facilities in Germany and Japan sustain procurement volumes despite limited volume scale. ETSI EN 302 217 compliance remains straightforward due to inherent electromagnetic cleanliness.
- Microstrip Antennas:Printed circuit board implementations integrate feed networks directly onto dielectric substrates for aerospace platforms.
- Reflective Antennas:Deployable mesh and solid-surface variants serve satellite ground terminals requiring transportable configurations.
Parabolic antennas sit at the top of the volume ranking, with phased array derivatives climbing the fastest in defense and satellite terminal applications.
Technology:
Technology tiering separates capital expenditure levels and semiconductor content. Passive architectures minimize GaN and GaAs foundry exposure while active implementations concentrate supply risk in Japanese and US wafer fabrication.
- Passive Technology:Waveguide and coaxial feed networks without amplification dominate legacy point-to-point infrastructure. Brazil's rural broadband subsidies specify passive microwave links to minimize maintenance complexity in remote terrain. Aluminum and copper price volatility directly compresses margin buffers for these metal-intensive assemblies.
- Phased Array Technology:Active electronically scanned arrays eliminate mechanical steering through solid-state beamforming. Low Earth orbit constellation operators in the United States and Europe specify flat-panel terminals for consumer broadband, creating volume demand absent in traditional telecom procurement. Thermal management and compound semiconductor foundry capacity constrain scaling.
- Active Technology:Integrated low-noise amplifiers and power amplifiers extend link budgets for challenging terrain.
- Smart Technology:Embedded control units with machine learning enable real-time beam adaptation for dynamic spectrum environments.
Passive technology commands the largest installed base, though phased array implementations are expanding most quickly in commercial satellite terminals.
End User:
End user categories map to distinct procurement rhythms and technical specifications. Military programs prioritize beam agility and electronic counter-countermeasures while telecom operators optimize for total cost of ownership across decade-long depreciation cycles.
- Telecommunications:Mobile network operators in India and Southeast Asia deploy microwave backhaul to connect 5G small cells where fiber proves uneconomical. Tower companies standardize on multi-vendor interoperability, unbundling installation and maintenance from equipment purchases. TRAI spectrum allocation decisions reshape addressable bandwidth for domestic suppliers.
- Military:Defense modernization budgets in the United States, United Kingdom, and Japan accelerate phased array adoption for radar and electronic warfare platforms. GaN substrate supply concentration in Japan and the United States creates procurement chokepoints for high-power amplifier integration. National security review thresholds constrain vendor selection.
- Aerospace:Satellite manufacturers and launch providers specify mass-optimized antennas with qualification heritage requirements.
- Research Institutions:National laboratories and universities sustain niche demand for calibration standards and experimental configurations.
Telecommunications generates the highest shipment volumes, with military applications showing the steepest technology premium expansion.
Application:
Application segmentation determines environmental qualification severity and lifecycle cost structures. Satellite communication terminals face thermal cycling and radiation exposure while point-to-point links prioritize rain fade mitigation.
- Satellite Communication:Ground segment infrastructure spans geostationary tracking antennas and non-geostationary terminal arrays. Constellation operators require flat-panel phased arrays for consumer broadband, creating procurement windows distinct from traditional telecom equipment cycles. Atmospheric attenuation above 30 GHz constrains E-band link reliability.
- Point-to-Point Communication:Line-of-sight microwave backhaul connects cellular base stations and enterprise networks across challenging terrain. India's BharatNet Phase 3 specifies microwave links for gram panchayat connectivity, opening volume procurement for cost-optimized parabolic equipment. Millimeter-wave deployment faces oxygen absorption limits.
- Radar Systems:Target illumination and surveillance applications demand beam-steering agility for track-while-scan operation.
- Remote Sensing:Synthetic aperture radar and radiometer payloads require precise calibration for earth observation missions.
Point-to-point communication holds the largest equipment population, with satellite communication terminals gaining share fastest through constellation deployment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the microwave antenna supply base with concentrated compound semiconductor foundry capacity and vertically integrated assembly operations serving constellation terminal manufacturers.
United States
Defense modernization programs and Low Earth orbit constellation deployments drive procurement volumes for phased array terminals. The FCC's spectrum reallocation policies reshape equipment authorization timelines for multi-band products. California's aerospace cluster concentrates flat-panel antenna development for satellite broadband operators.
China
MIIT 5G infrastructure mandates accelerate base station backhaul deployment across provincial network buildouts. GB standards and SRRC testing protocols constrain product design cycles for domestic suppliers. Guangdong province hosts the densest concentration of parabolic antenna stamping operations and export assembly facilities.
India
BharatNet Phase 3 rural broadband specifications create procurement windows for cost-optimized microwave backhaul equipment. TRAI spectrum allocation decisions reshape addressable bandwidth for domestic tower companies. Karnataka's telecom equipment manufacturing corridor concentrates assembly operations for Indus Towers and ATC India multi-vendor deployments.
Germany
ETSI harmonized standards enforcement drives filter architecture redesigns for cross-border point-to-point links. Defense research institutions sustain niche demand for horn antenna calibration standards. Bavaria's RF engineering cluster concentrates test and measurement laboratory procurement for aerospace qualification programs.
Japan
GaN substrate production concentration creates supply chokepoints for high-power amplifier integration into phased array systems. METI industrial policy supports compound semiconductor foundry expansion for defense and satellite applications. Kyushu's semiconductor materials corridor anchors wafer fabrication for microwave device integration.
Microwave Antenna Market Competitive Landscape
Global majors compete with regional champions across certification expertise and manufacturing scale. The vendor base stratifies into three tiers: integrated telecom infrastructure suppliers, specialized antenna fabricators, and defense-focused RF subsystem houses. Two strategic archetypes dominate procurement outcomes: scale-driven commodity producers serving carrier-grade volume contracts, and agility-focused specialists capturing premium pricing in phased array applications. Competitive moves concentrate on multi-band certification pre-qualification and installer network certification to capture unbundled service contracts.
Within the integrated infrastructure tier, CommScope represents North American carrier-grade positioning, while Tongyu Communication exemplifies cost-optimized emerging market supply. Radio Frequency Systems occupies a position within the defense-specialist archetype, anchoring high-frequency assembly expertise for military radar and electronic warfare platforms. These three entities illustrate the geographic and technological segmentation that structures competitive outcomes across procurement channels.
| Leading Market Players |
|---|
| Alaris mWAVE |
| Radio Frequency Systems |
| CommScope |
| Tongyu Communication |
| Wireless Excellence |
| Rosenberger |
| Shenglu |
| Comba Telecom |
| RadioWaves |
| Others |
Supply & Pricing Matrix
Aluminum sheet and copper waveguide costs transmit directly from commodity exchanges to parabolic antenna landed pricing in India and Brazil, with stamped reflector manufacturers absorbing margin compression when carrier procurement teams unbundle installation services.
Pricing Analysis
Input-cost pass-through from aluminum and copper volatility dominates transactional pricing for passive parabolic assemblies. Three-tier pricing structure across premium, standard, and economy levels separates FCC-certified multi-band equipment from single-frequency ETSI variants and unbranded emerging market supply. Pricing pressure stems from tower company unbundling of installation and maintenance contracts in India. Rural broadband subsidy recipients exhibit highest price sensitivity, while defense phased array procurement shows lowest elasticity due to electronic warfare specification rigidity.
Supply Chain Analysis
GaN wafer supply rests on Japanese and United States specialty semiconductor foundries, constraining high-power amplifier integration for active electronically scanned arrays. Aluminum sheet feedstock draws from Chinese and Russian primary smelters, while precision stamping equipment concentrates in German and Italian machine tool builders. Single-source vulnerability in compound semiconductor substrates threatens phased array scaling timelines. Distribution runs through carrier-direct contracts for volume telecom deployment and systems integrator channels for defense and satellite terminal integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in microwave antennas hinges on GaN cost-down curves and the shift from commodity parabolic supply to premium phased array tiers in satellite ground terminals.
For Market Incumbents: Extend certification pre-qualification across FCC Part 101, ETSI EN 302 217, and MIIT SRRC protocols simultaneously to compress competitor time-to-market. Anchor backward integration into aluminum stamping operations in Guangdong or Karnataka to defend margin position against raw material volatility. Threats from flat-panel phased array entrants in Low Earth orbit terminals demand captive thermal management subsystem development. For New Entrants and Emerging Players: BharatNet Phase 3 specifications in India open a window for cost-optimized parabolic antenna supply with gram panchayat connectivity mandates. Target Brazil's rural broadband subsidy programs where passive microwave links face limited incumbent saturation. Go-to-market leverage rests on certified installer network partnerships with Indus Towers or ATC India rather than equipment-only positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-band certification complexity and GaN foundry access barriers strand sub-scale antenna fabricators. Long-term viability favors compound semiconductor-integrated subsystem houses with defense heritage and satellite terminal commercialization capability. Watch Low Earth orbit constellation deployment schedules as volume inflection signal for phased array demand.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Band Certification Pre-Qualification | FCC, ETSI, and MIIT simultaneous approval compresses competitor entry timelines across three regulatory regimes. |
| Backward Integration into Aluminum Stamping | Captive Guangdong or Karnataka reflector production insulates margin from LME price volatility in carrier contracts. |
| Phased Array Thermal Management Development | Proprietary heat dissipation subsystems differentiate flat-panel satellite terminals from mechanically steered alternatives. |
| Certified Installer Network Partnership | MSO contract capture with Indus Towers or ATC India recovers service margin ceded in unbundled equipment procurement. |
| GaN Foundry Capacity Reservation | Japanese and United States wafer fabrication commitments secure amplifier supply for defense and satellite volume ramps. |
Research Methodology
Direct dialogue with antenna design engineers, carrier procurement managers at Bharti Airtel and Reliance Jio, tower company technical directors, and defense RF subsystem program officers grounded qualitative assessment. Secondary validation drew from FCC equipment authorization databases, ETSI EN 302 217 certification registries, MIIT SRRC approval filings, and aluminum commodity exchange data. Bottom-up shipment modeling across product type, technology tier, and end-use segments triangulated against top-down infrastructure capex projections from mobile network operators.
Top-down infrastructure investment analysis across telecommunications, military, and aerospace verticals anchored value projections. Segmentation dimensions spanned product architecture, technology implementation, end-user procurement rhythm, and application environmental severity. CAGRs derived from regression against historical backhaul deployment cycles and constellation terminal shipment trajectories. Forecast inputs incorporated TRAI spectrum allocation timelines and METI compound semiconductor subsidy disbursement patterns.
Revisions become necessary when FCC spectrum reallocation schedules shift, GaN substrate supply disruptions materialize, or Low Earth orbit constellation deployment timelines compress. Forecasts reflect documented assumptions regarding aluminum price stability and defense modernization budget continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Africa Small Cell Market
Telecom Hardware
LPWAN Market
Telecom Hardware
Land Mobile Radio System Market
Telecom Hardware
Industrial Transceivers Market
Telecom Hardware
Very Small Aperture Terminal (VSAT) Market
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
Telecom Equipment Market
Telecom Hardware
United States Set-Top Box Market
Telecom Hardware
SATCOM Transceivers Market
Telecom Hardware
Communication Base Station Equipment Pcb Market
Telecom Hardware
Satellite Communication Terminal Market
Telecom Hardware
Point-To-Point Antenna Market
Telecom Hardware
Repeaters Market
Telecom Hardware
Set-Top Box Market
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
Europe Set-Top Box Market