
 Laser Communications Terminals (Lcts) Market | 2026-2036
Laser Communications Terminals (Lcts) Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Communications Terminals (Lcts) Market Insights
Modular terminal packaging is rebalancing procurement economics across defense and commercial programs. TESAT Spacecom leverages its heritage in coherent optical payloads to anchor European supply chains for institutional customers. Mynaric AG competes through serial production of standardized spaceborne units, while Ball Aerospace extends its position via deep integration with prime satellite platforms.
Laser Communications Terminals are electro-optical transceivers that encode data onto infrared laser beams for transmission through free space, typically operating at wavelengths near 1550 nanometers with aperture diameters ranging from tens of millimeters to several centimeters depending on link distance and atmospheric conditions. Their primary purpose is to deliver orders-of-magnitude higher data rates than radio-frequency systems while reducing size, weight, and power consumption for spacecraft and airborne platforms. Spaceborne terminals lead current revenue pools due to constellation deployment schedules, though airborne terminals represent the fastest-growing category as unmanned platforms demand high-bandwidth intelligence, surveillance, and reconnaissance datalinks. Coherent optical communication technology dominates performance-sensitive segments, while direct detection systems occupy cost-optimized applications where atmospheric turbulence is less severe.
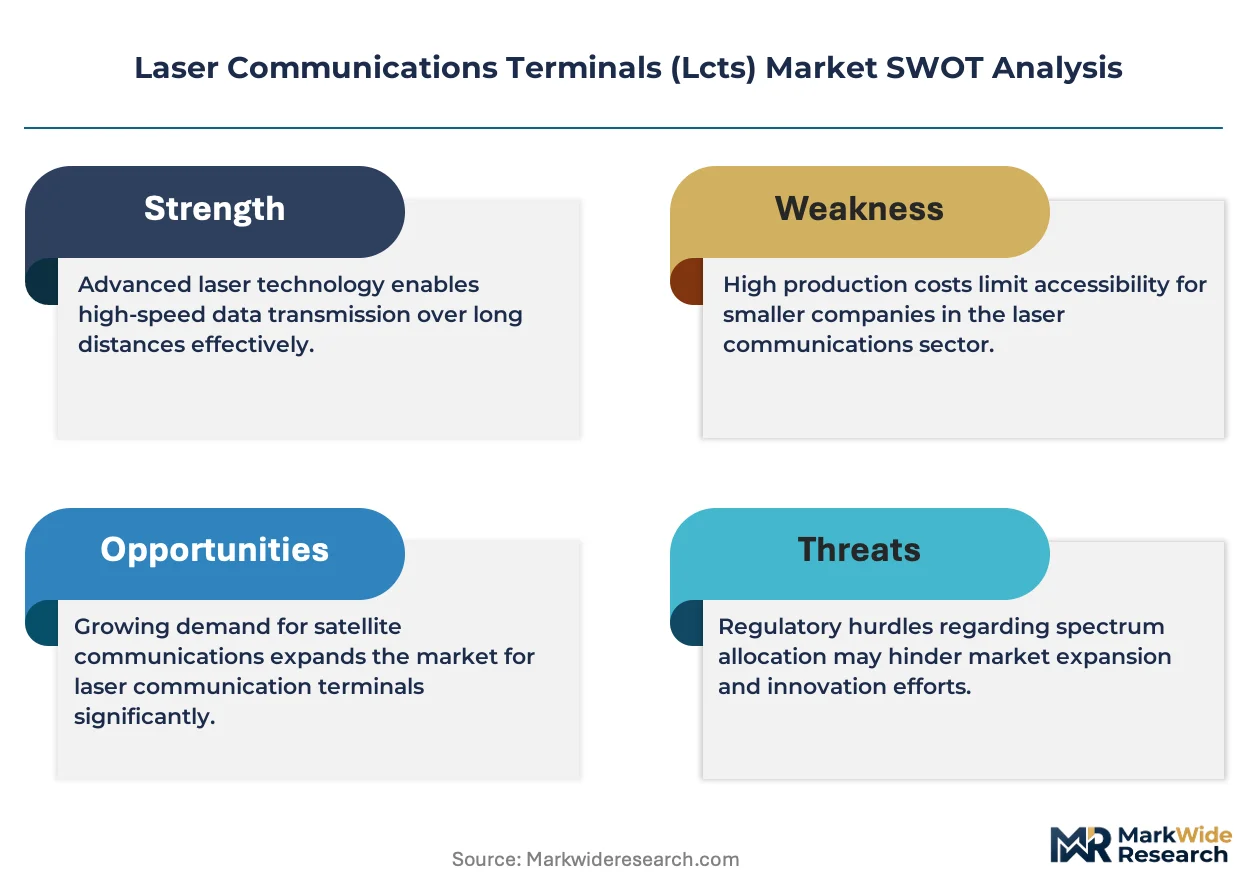
The FCC governs spectrum allocation and licensing timelines for domestic optical links, while ITU-R coordination frameworks shape international frequency registrations and orbital slot assignments. EAR and ITAR controls administered by the US Department of State and Commerce restrict technology transfer for terminals above specified performance thresholds, constraining supplier geography for defense-grade systems. Stakeholders must monitor evolving export control classifications and emerging national security reviews of foreign investment in photonics supply chains as procurement volumes scale.
Market Dynamics
Defense procurement schedules are compressing terminal qualification cycles while commercial constellation operators demand unit cost reductions at scale, creating dual-track pressure on suppliers to bifurcate product architectures.
Growth Catalysts
- SDA Tranche procurements:The Space Development Agency's proliferated warfighter space architecture mandates optical crosslinks on every satellite, institutionalizing laser terminal demand across prime contractor supply chains.
- FCC optical licensing streamlining:Reduced administrative barriers for experimental special temporary authority filings accelerate commercial deployment timelines for low-earth orbit constellations.
- Coherent optical encoding:Advanced modulation formats enable higher spectral efficiency over atmospheric channels, expanding addressable link budgets for airborne intelligence platforms.
Market Restraints
- Precision optomechanical input costs:Beam expander assemblies and fast-steering mirrors rely on specialized aluminum beryllium alloys and diamond-turned substrates subject to aerospace supply constraints.
- ITAR-controlled subsystem concentration:High-performance optical amplifiers and radiation-hardened focal plane arrays face restricted vendor pools concentrated in US defense industrial base corridors.
- Atmospheric scintillation physics:Turbulence-induced beam wander and intensity fading impose fundamental link availability limits for low-elevation ground-to-air applications.
Strategic Opportunities
- Indian constellation buildouts:NSIL and private operators like Pixxel are procuring indigenous optical payloads, creating localization partnerships for terminal subsystem suppliers.
- Quantum key distribution integration:Convergence of free-space quantum communication with classical high-rate lasers enables cryptographic services for financial and government verticals.
- Japanese H3 launch cost reductions:JAXA's reusable vehicle program lowers per-kilogram insertion expenses, improving terminal mass budget economics for commercial missions.
Industry Challenges
- Adaptive optics engineering scarcity:Wavefront sensor design and real-time deformable mirror control algorithms require specialized expertise concentrated in academic and national laboratory settings.
- Space qualification timeline compression:Thermal vacuum cycling and radiation testing protocols for COTS component uprating extend development schedules beyond constellation deployment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Communications Terminals (Lcts) Market |
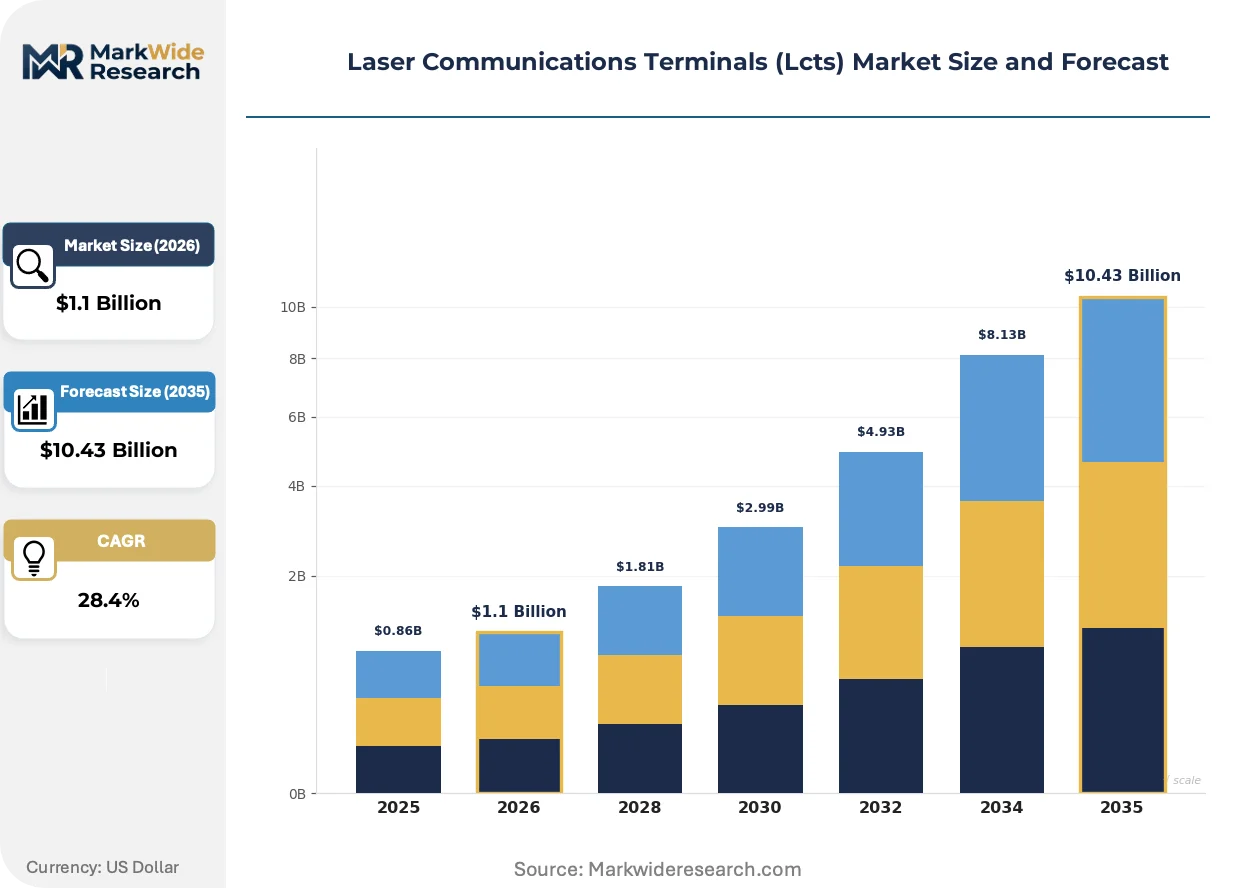
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $10.43 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spaceborne Terminals, Airborne Terminals, Ground Stations, Mobile Terminals, Submarine Terminals Technology: Coherent Optical Communication, Direct Detection, Quantum Communication, Free Space Optical, Wavelength Division Multiplexing Application: Satellite Data Relay, Secure Military Networks, Broad Band Internet, Scientific Research, Emergency Communication End User: Defense Agencies, Space Research Organizations, Telecommunication Providers, Disaster Management Authorities |
| Companies Covered | Mynaric AG, TESAT Spacecom, Thales Alenia Space, Ball Aerospace, General Atomics, Hensoldt, Space Micro, Fibertek, BridgeComm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Communications Terminals (Lcts) Market Trends and Innovations
Terminal architectures are fragmenting into reconfigurable building blocks that accommodate divergent defense and commercial specifications without full redesign cycles, compressing non-recurring engineering amortization.
Photonic integrated circuits are consolidating discrete optical functions—lasers, modulators, amplifiers—onto indium phosphide substrates. Smallsat operators are qualifying these chip-scale packages for radiation tolerance. The technology is modularizing subsystem supply chains, enabling third-party terminal integrators to bypass heritage prime relationships.
The FCC's streamlined experimental licensing framework for optical spectrum bands reduces pre-deployment regulatory lead times from months to weeks. Commercial operators now file coordinated batch applications for entire constellation planes. Low-earth orbit broadband providers are responding by accelerating in-orbit demonstration schedules to secure priority spectrum registrations.
Constellation operators are unbundling terminal procurement from satellite prime contracts, directly sourcing optical payloads from specialized vendors. This disintermediation concentrates volume with terminal specialists while eroding traditional platform integrator margins. The United States exhibits the most pronounced shift, where Space Development Agency contracting vehicles explicitly separate payload from bus procurement.
Laser Communications Terminals (Lcts) Market Segmentation
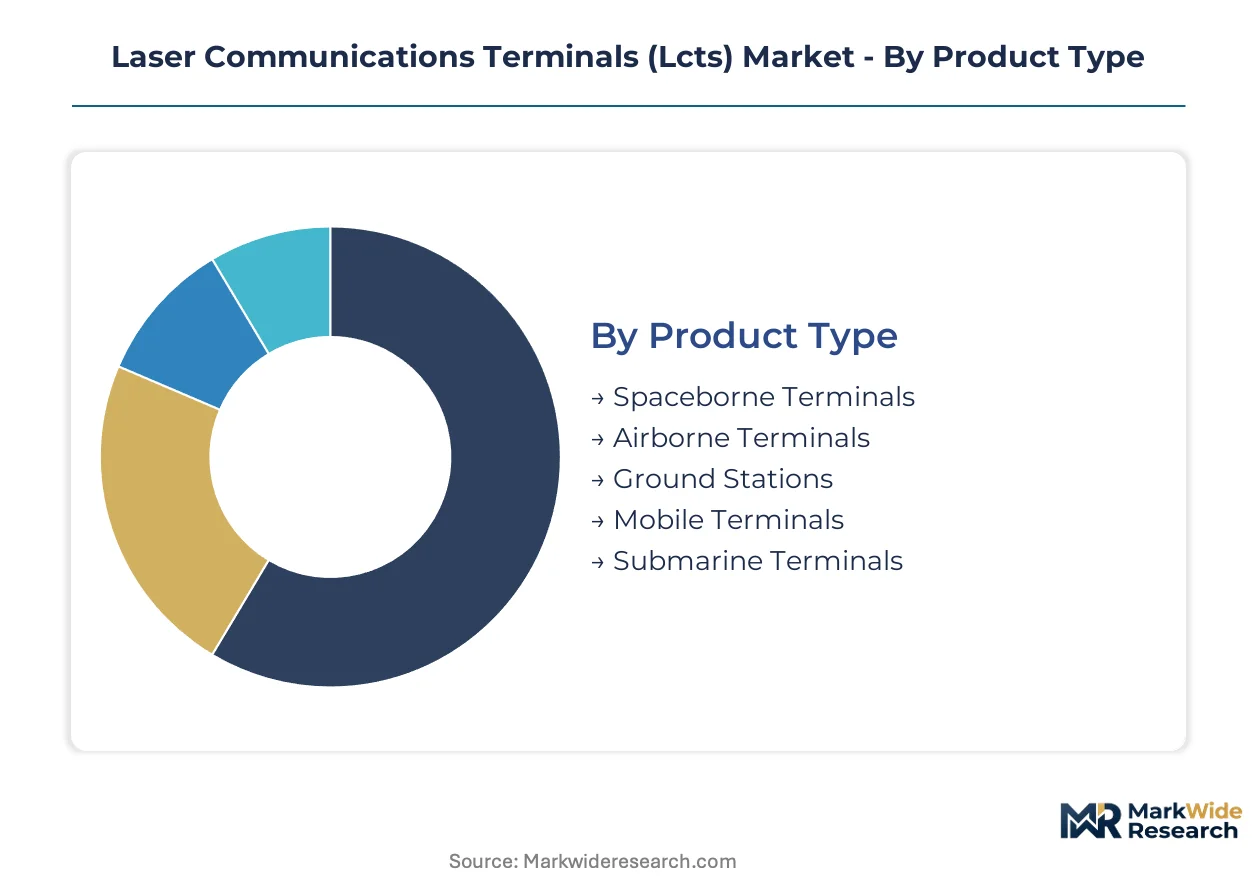
Terminal procurement patterns diverge sharply across defense and commercial constituencies. Product architecture choices cascade through qualification timelines, supply chain geography, and regulatory exposure.
Product Type:
Physical packaging and environmental hardening requirements separate orbital, aerial, and terrestrial form factors.
- Spaceborne Terminals:Radiation-hardened transceivers with thermal cycling tolerance anchor current revenue pools. Space Development Agency constellation schedules pull volumes through prime contractor supply chains in the United States.
- Airborne Terminals:Compact units with atmospheric turbulence compensation enable high-bandwidth intelligence, surveillance, and reconnaissance datalinks. Unmanned platform procurement across NATO member states drives the steepest expansion trajectory as endurance requirements stretch mission durations.
- Ground Stations:Fixed-site optical gateways with large-aperture telescopes terminate satellite-to-earth links. Teleport operators in the United States and Germany concentrate procurement for low-earth orbit broadband downlinks.
- Mobile Terminals:Vehicle-mounted or man-portable units with rapid acquisition capabilities serve expeditionary military units. Portability constraints limit aperture size and link budget.
- Submarine Terminals:Pressure-hull penetrators with blue-green wavelength options enable covert communications. Naval programs in the United States and United Kingdom sustain limited production runs.
Mature deployment sits with spaceborne terminals. Newer deployment is concentrated in airborne terminals.
Technology:
Modulation and detection architectures determine spectral efficiency, atmospheric resilience, and export control classification.
- Coherent Optical Communication:Phase-encoded signals with digital signal processing recovery maximize data rates over impaired channels. Defense agencies mandate this architecture for crosslink applications requiring jam resistance.
- Direct Detection:Intensity-modulated beams with simple photodiode receivers reduce cost and complexity. Commercial constellation operators in the United States favor this approach for inter-satellite links in benign orbital environments.
- Quantum Communication:Entanglement-based key distribution integrated with classical laser channels. Financial sector pilots in Switzerland and Singapore test metropolitan quantum networks.
- Free Space Optical:Generic term covering unguided laser transmission through atmosphere or vacuum. Standardized interfaces enable multi-vendor interoperability.
- Wavelength Division Multiplexing:Multiple optical carriers on single apertures multiply aggregate throughput. Ground station operators deploy this to maximize fiber backhaul utilization.
Established deployment centers on coherent optical communication. Emerging deployment clusters around quantum communication.
Application:
Mission requirements dictate link availability targets, security protocols, and integration complexity.
- Satellite Data Relay:Constellation-to-constellation and satellite-to-ground high-rate pipes. Space Development Agency proliferated architectures institutionalize this demand across prime contractor supply chains.
- Secure Military Networks:Anti-jam, low-probability-of-intercept links for command and control. NATO member state procurement compresses qualification cycles for cleared suppliers.
- Broad Band Internet:Consumer and enterprise connectivity via low-earth orbit constellations. FCC streamlined licensing accelerates deployment timelines for commercial operators.
- Scientific Research:Deep space and earth observation payload data return. NASA and ESA mission schedules anchor long-lead procurement.
- Emergency Communication:Rapidly deployable links for disaster response coordination. FEMA and analogous agencies in Japan provision mobile terminal inventories.
Institutionalized demand flows through satellite data relay. Accelerating uptake characterizes secure military networks.
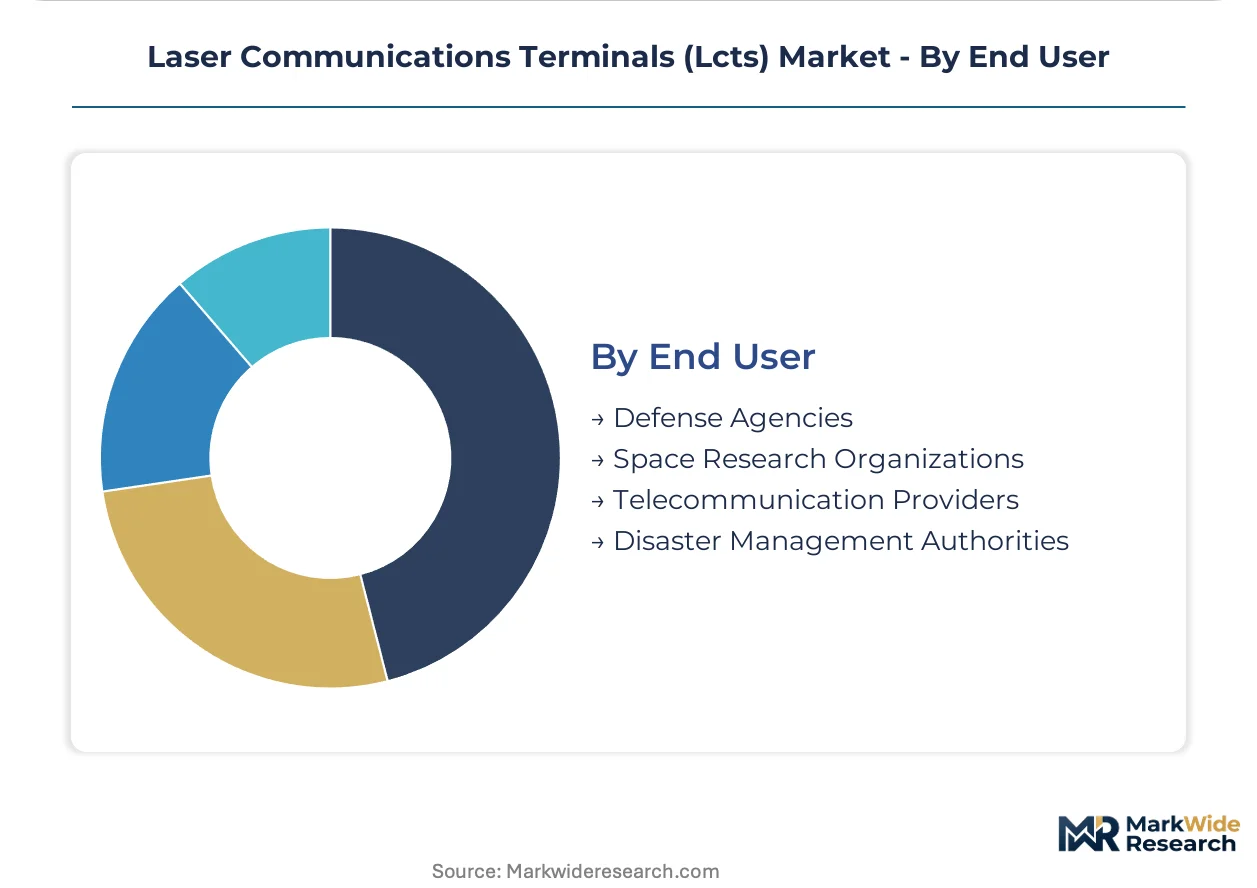
End User:
Procurement authority and funding mechanisms shape specification rigor and contract vehicle selection.
- Defense Agencies:Classified requirements with ITAR-controlled subsystem mandates. United States Space Development Agency and analogous NATO bodies drive qualification standards.
- Space Research Organizations:Civilian missions with extended development horizons. NASA, ESA, and JAXA programs concentrate demand for radiation-hardened components.
- Telecommunication Providers:Commercial constellation operators with unit cost targets at scale. United States-based low-earth orbit broadband providers unbundle terminal procurement from satellite prime contracts.
- Disaster Management Authorities:Intermittent demand with rapid deployment requirements. FEMA maintains mobile terminal reserves for continental United States response.
Contract concentration favors defense agencies. Procurement flexibility expands most quickly with telecommunication providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of precision optomechanical subsystems concentrates in Germany and the United States, while terminal integration and constellation deployment demand centers on American defense procurement and European institutional programs.
United States
Space Development Agency Tranche awards institutionalize optical crosslink demand across Lockheed Martin, Northrop Grumman, and York Space Systems supply chains. FCC streamlined experimental licensing for optical spectrum bands compresses pre-deployment timelines from months to weeks for commercial constellation operators. Colorado's aerospace corridor hosts Ball Aerospace and Fibertek facilities serving both defense primes and direct commercial procurement.
Germany
TESAT Spacecom and Hensoldt anchor European supply chains for coherent optical payloads serving institutional customers. Germany's national space program through DLR prioritizes optical communication technology for Earth observation data relay missions. Bavaria's Munich-Stuttgart aerospace cluster concentrates precision manufacturing of beam expander assemblies and fast-steering mirror mechanisms.
France
Thales Alenia Space leverages satellite prime contractor relationships to integrate proprietary laser terminals into institutional and commercial platforms. CNES technology development programs fund advancement of photonic integrated circuits for spaceborne applications. Toulouse's aerospace valley hosts specialized optomechanical suppliers feeding prime contractor terminal programs.
Japan
JAXA's optical data relay satellite program and H3 launch vehicle development create domestic demand for radiation-hardened terminal components. METI funding for space industry competitiveness supports qualification of indigenous optical payload suppliers. Tsukuba's space science cluster concentrates academic and national laboratory expertise in adaptive optics and wavefront sensing.
India
NSIL constellation procurement and private operators like Pixxel drive demand for localized optical payload integration. ISRO's technology transfer policies encourage domestic manufacturing of satellite subsystems including laser communication terminals. Bengaluru's aerospace and defense electronics cluster hosts emerging terminal integrators serving both government and commercial programs.
Laser Communications Terminals (Lcts) Market Competitive Landscape
The competitive structure tilts toward defense-heritage primes with platform integration capabilities. Vendor concentration remains moderate, with five to eight firms capturing institutional procurement while specialized component suppliers serve commercial constellation buildouts. Two strategic archetypes dominate: coherent optical payload specialists with radiation-hardening expertise, and serial production houses optimizing standardized units for cost-at-scale. Competitive moves center on disintermediation of terminal procurement from satellite prime contracts, and photonic integrated circuit partnerships to consolidate discrete optical functions.
Among German coherent optical specialists, TESAT Spacecom GmbH and Mynaric AG exemplify divergent strategic positioning within European supply chains. TESAT occupies the institutional-heritage tier, leveraging decades of space-qualified payload delivery for ESA and national programs. Mynaric represents the scale-production archetype, optimizing manufacturing throughput for standardized spaceborne units across commercial and defense constituencies. At the platform-integration end, Ball Aerospace & Technologies Corp. anchors American supply chains through deep relationships with Space Development Agency contracting vehicles and major satellite primes. These three firms collectively illustrate how terminal procurement unbundling is redistributing value capture between payload specialists and traditional platform integrators.
| Leading Market Players |
|---|
| Mynaric AG |
| TESAT Spacecom |
| Thales Alenia Space |
| Ball Aerospace |
| General Atomics |
| Hensoldt |
| Space Micro |
| Fibertek |
| BridgeComm |
| Others |
Pricing and Supply Chain Analysis
Aluminum beryllium alloy spot indices cascade through beam expander assembly costs into three-tier pricing stratification across defense, dual-use, and commercial terminal tiers. ITAR-controlled subsystem premiums widen spreads between cleared and non-cleared supply channels.
Pricing Analysis
Cost-down pressure on serial-production spaceborne units accelerates as constellation operators unbundle terminal procurement from prime satellite contracts. Pricing stratifies across ITAR-restricted, EAR-controlled, and uncontrolled tiers, with certification level and volume scale as primary differentiation drivers. Commercial low-earth orbit providers exhibit highest price sensitivity; defense agencies demonstrate lowest sensitivity due to mission-critical jam-resistance requirements.
Supply Chain Analysis
Regional distribution centers in Colorado, Bavaria, and Toulouse consolidate precision optomechanical subsystems before final integration. Manufacturing gravity centers on Germany and the United States for beam expander assemblies, with Japan and India emerging for photonic integrated circuits. The supply chain draws from aluminum beryllium alloys, diamond-turned substrates, and indium phosphide wafers. Single-source vulnerability concentrates in radiation-hardened focal plane arrays. Distribution runs through prime contractor logistics networks and direct commercial procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Laser Communications Terminals market functions as a cost-of-compliance story where ITAR and EAR controls erect barrier-to-entry moats for cleared suppliers. Regulatory clearance investments separate sustainable participants from marginal operators.
For Market Incumbents: Deploy photonic integrated circuit partnerships to consolidate discrete optical functions and defend against modular subsystem disintermediation. Incumbents should anchor platform-integration relationships with Space Development Agency primes while qualifying second-source suppliers for ITAR-controlled optical amplifiers to mitigate single-source concentration risk.
For New Entrants and Emerging Players: Capture Indian constellation buildouts through NSIL and private operator localization partnerships for non-ITAR terminal subsystems. The most penetrable white-space sits with commercial airborne terminals for NATO unmanned platforms, approached via adaptive optics engineering collaborations with Tsukuba academic clusters.
For Investors and Strategic Acquirers: Distressed-cycle entries favor coherent optical payload specialists with radiation-hardening expertise in Germany and the United States over scale-production houses facing margin compression. Long-term viability favors suppliers with dual-use revenue streams spanning defense and commercial constellations. Watch Space Development Agency Tranche award timing as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Partnership | Consolidates lasers, modulators, and amplifiers onto indium phosphide substrates for chip-scale terminal packaging. |
| ITAR Certification Investment | Opens Space Development Agency and NATO procurement channels for high-performance crosslink terminals. |
| Indian Localization Partnership | Positions suppliers for NSIL constellation procurement and Pixxel commercial operator integration. |
| Adaptive Optics Capability Acquisition | Addresses engineering scarcity in wavefront sensing for airborne turbulence compensation. |
| Direct Commercial Procurement Channel | Bypasses traditional satellite prime relationships as constellation operators unbundle terminal sourcing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews across terminal program managers at defense primes, optical payload procurement leads at constellation operators, precision manufacturing engineers at optomechanical suppliers, and regulatory compliance officers handling ITAR classifications. FCC experimental licensing databases, EAR commodity jurisdiction rulings, and Space Development Agency contract award notices provided demand-side validation. Bottom-up unit economics and top-down addressable market sizing converged through iterative reconciliation.
Granularity-level modeling distinguished spaceborne, airborne, ground station, mobile, and submarine terminal form factors; coherent, direct detection, quantum, and wavelength division multiplexing technologies; and defense agency, space research organization, telecommunication provider, and disaster management authority end users. CAGRs derived from deployment schedule phasing and unit cost trajectory assumptions across the projection horizon. Constellation launch manifests and radiation-hardening qualification timelines served as industry-specific forecast inputs.
The model holds under stable ITAR/EAR classification regimes and continued Space Development Agency procurement acceleration; deviation in export control expansion or constellation operator bankruptcy waves would shift volume and value outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
Point-To-Point Antenna Market
Telecom Hardware
LPWAN Market
Telecom Hardware
DWDM Transceiver Market
Telecom Hardware
Broadcast Antenna Market
Telecom Hardware
Satellite Communication Terminal Market
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
Commercial Antennas Market
Telecom Hardware
Synchronous Optical Network (SONET) Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Infiniband Market
Telecom Hardware
Microwave Antenna Market