
 Communication Base Station Equipment Pcb Market | 2026-2036
Communication Base Station Equipment Pcb Market Size, Share, and Industry Trends Forecast 2026-2036
Communication Base Station Equipment Pcb Market Analysis
Modular substrate packaging is realigning procurement patterns across base station supply chains. Samsung Electro-Mechanics leverages its captive materials science portfolio to dominate high-frequency laminate supply. AT&S Austria Technologie & Systemtechnik AG anchors European production capacity for advanced sequential lamination processes. Shenzhen Kinwong Electronic competes on scale across multi-layer and rigid-flex configurations for tier-one telecom equipment manufacturers.
Communication base station equipment PCB denotes printed circuit boards engineered for radio frequency signal processing, power distribution, and digital control within cellular transmission infrastructure, typically fabricated on low-loss dielectric substrates with controlled impedance traces and thermal management vias to maintain signal integrity across microwave frequencies. These boards serve as the physical interconnect layer between baseband processors, power amplifiers, and antenna arrays in macro cells, small cells, and distributed antenna systems. Multi-layer configurations command the dominant share of value given their complexity in routing high-speed differential pairs and RF traces across twelve or more conductive layers. Rigid-flex technology represents the fastest-growing product category as base station architects adopt foldable interconnect schemes to reduce connector count and improve reliability in outdoor enclosures. Microwave technology segments carry elevated margin pools due to specialized substrate materials and tighter manufacturing tolerances required for millimeter-wave operation.
FCC equipment authorization rules in the United States shape product validation timelines and testing costs for PCB assemblies destined for commercial 5G deployment. China's MIIT enforces national standards for electromagnetic emissions and environmental ruggedness that filter non-compliant suppliers from state-backed telecom tenders. REACH substance restrictions in Europe constrain halogenated flame retardant formulations, pushing laminate suppliers toward phosphorus-based alternatives. Stakeholders must monitor evolving spectrum allocation decisions and corresponding radio head designs that will dictate layer counts, material specifications, and thermal management requirements across the next deployment cycle.
Market Dynamics
Millimeter-wave spectrum allocation is compressing development cycles for base station PCBs, forcing laminate suppliers to certify ultra-low-loss dielectrics ahead of deployment timelines. This frequency push is restructuring procurement relationships between telecom equipment manufacturers and substrate vendors.
Growth Catalysts
- MIIT electromagnetic compatibility mandates:China's stricter certification requirements for base station components are filtering supplier pools and elevating technical barriers that favor established substrate specialists with in-house testing capabilities.
- Vietnam manufacturing corridor clustering:Contract equipment assembly concentration in northern Vietnamese industrial zones is generating localized PCB demand from telecom infrastructure OEMs establishing regional fulfillment hubs.
- Sequential lamination process maturation:Advanced multi-layer fabrication techniques enabling twelve-plus conductive layer configurations are supporting complex RF routing requirements for massive MIMO antenna arrays.
Market Restraints
- High-frequency laminate supply concentration:Captive production of ultra-low-loss substrates by vertically integrated Japanese and Korean material suppliers limits second-source options for European and North American PCB fabricators.
- Copper foil and resin cost volatility:Raw material price swings for rolled annealed copper and hydrocarbon ceramic laminates compress gross margins for mid-tier PCB manufacturers lacking long-term supply agreements.
- Millimeter-wave thermal dissipation limits:Existing substrate thermal conductivity specifications constrain power amplifier integration density in compact radio head designs targeting 28 GHz and 39 GHz bands.
Strategic Opportunities
- India telecom infrastructure buildout:Reliance Jio and Bharti Airtel's 5G network expansion creates demand for cost-optimized multi-layer PCBs in a market historically dependent on Chinese imports.
- Phosphorus-based flame retardant transition:REACH substance restrictions on halogenated compounds in Europe are accelerating qualification of alternative laminate chemistries that meet environmental compliance without sacrificing signal integrity.
- Rigid-flex antenna interconnect convergence:Foldable PCB schemes replacing discrete cable assemblies in outdoor small cell enclosures reduce connector failure points while enabling three-dimensional packaging geometries.
Industry Challenges
- RF simulation and measurement talent scarcity:Base station PCB design requires specialized expertise in electromagnetic field solvers and vector network analyzer protocols that outpaces university engineering program output.
- FCC equipment authorization timeline compression:Commercial 5G deployment schedules demand parallel-track regulatory submission and production ramp, compressing validation windows for new substrate material qualifications.
- Legacy 4G infrastructure interoperability:Mixed-generation network architectures require PCB designs supporting both sub-6 GHz and millimeter-wave protocols without duplicate radio chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Communication Base Station Equipment Pcb Market |
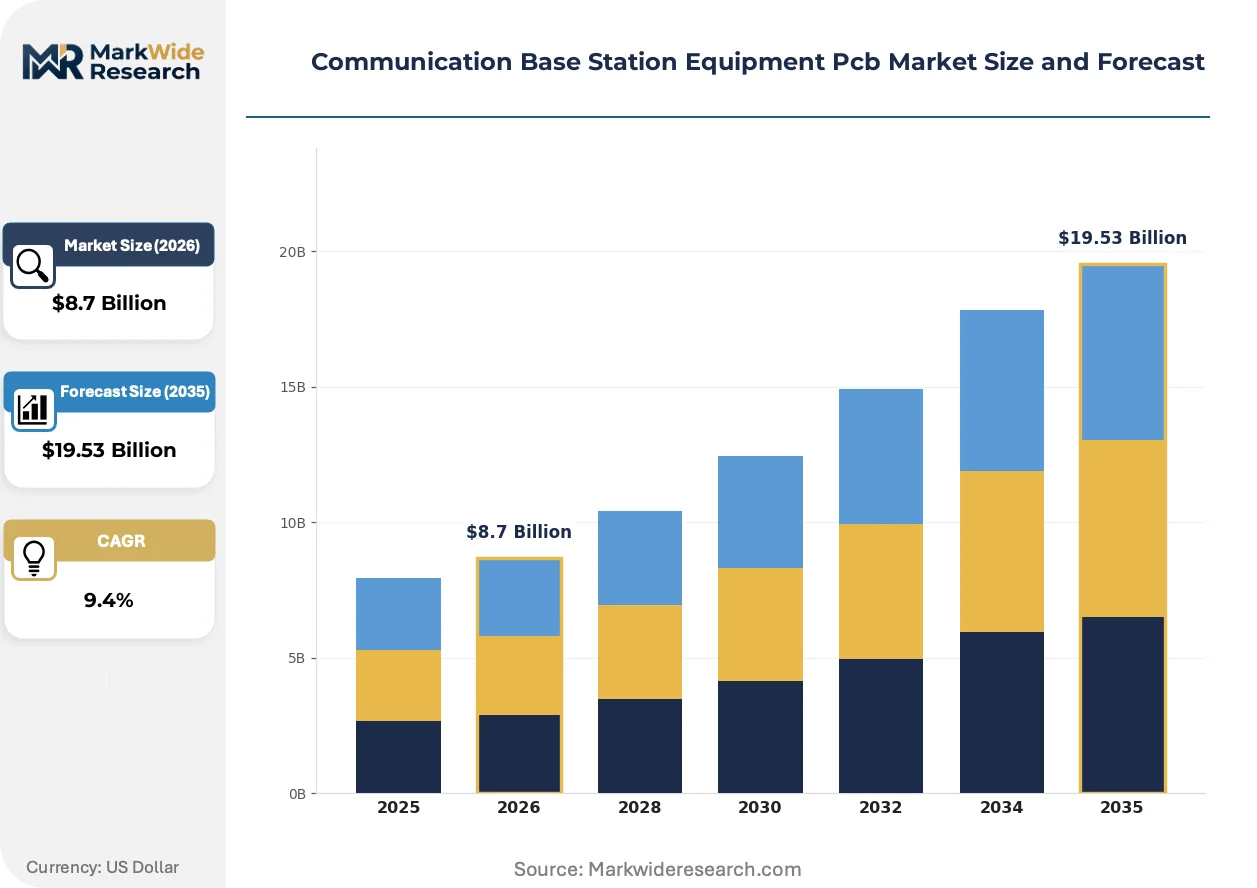
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Multi-Layer, Rigid-Flex Technology: RFID, Microwave, Optical Fiber, Satellite Application: Telecommunication, Broadcasting, Military, Industrial Automation End User: Telecom Operators, Equipment Manufacturers, Government Agencies, Infrastructure Providers |
| Companies Covered | Samsung Electro-Mechanics, AT&S Austria Technologie & Systemtechnik AG, Murata Manufacturing, TDK Corporation, Ibiden Co., Ltd., Unimicron Technology Corporation, Vishay Intertechnology, TT Electronics, Shenzhen Kinwong Electronic Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Communication Base Station Equipment Pcb Market Emerging Trajectories
Substrate material science is outpacing fabrication equipment capabilities, creating a capability gap that favors suppliers with captive R&D infrastructure. Three developments are restructuring competitive positioning.
Modified epoxy and hydrocarbon-ceramic hybrid laminates are rewriting performance benchmarks for base station RF applications. These materials combine dielectric constant stability across temperature extremes with mechanical properties compatible with standard PCB fabrication flows. Telecom equipment manufacturers in South Korea and Japan are adopting these substrates for 28 GHz small cell deployments, compressing the qualification cycle for alternative suppliers.
REACH substance restrictions on halogenated flame retardants are forcing laminate reformulation across European supply chains. The ECHA regulatory pressure is elevating phosphorus-based and inorganic filler alternatives that must match legacy material electrical properties while meeting environmental compliance. High-frequency microwave segments face the steepest reformulation burden given the narrow performance tolerances required for millimeter-wave operation.
Consolidated procurement through telecom operator direct sourcing is displacing traditional distributor channels for high-volume base station programs. Equipment manufacturers now negotiate substrate specifications directly with laminate suppliers, bypassing PCB fabricator material selection. This pattern concentrates most visibly in China's state-backed 5G tenders where MIIT-mandated component traceability requirements favor direct supplier relationships over fragmented sourcing.
Communication Base Station Equipment Pcb Market Segmentation
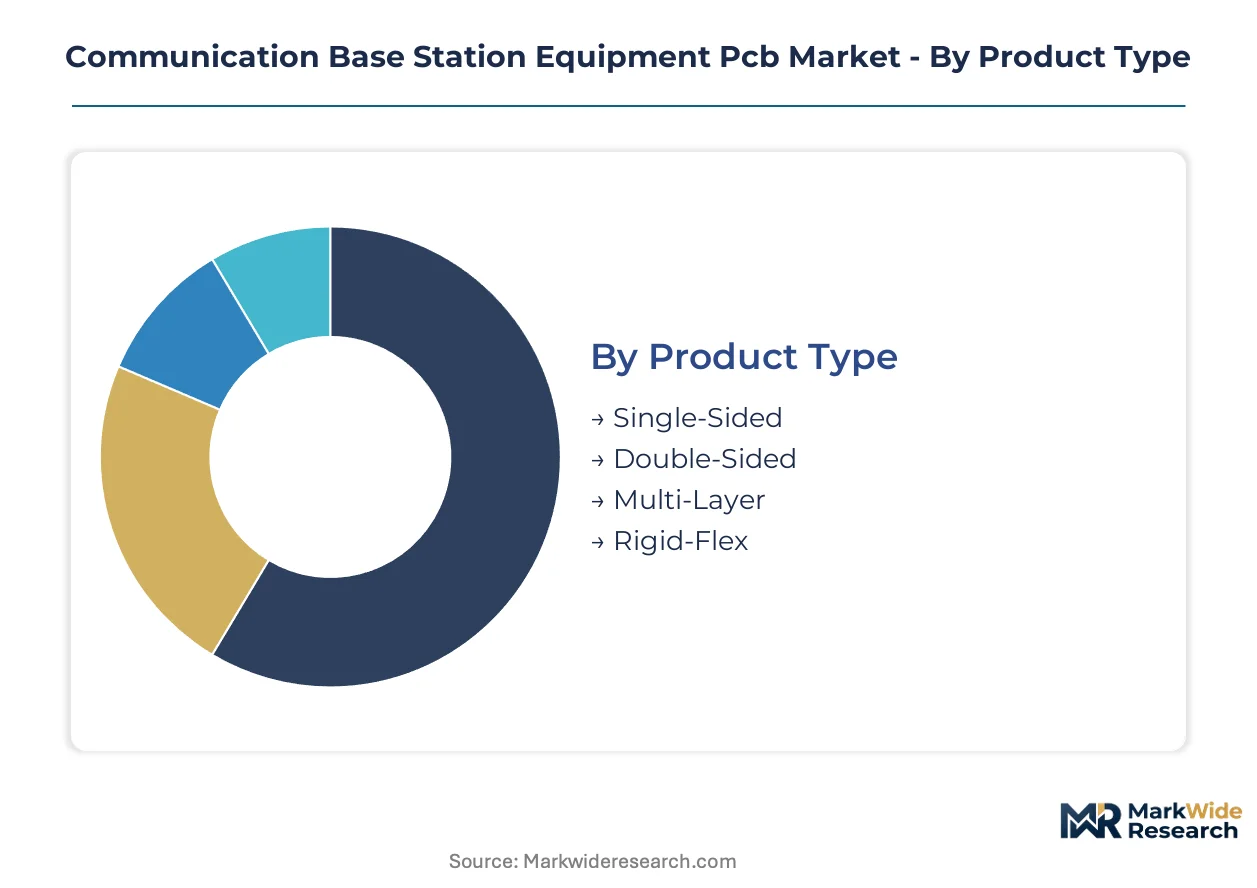
Segmentation in base station PCBs reveals how certification requirements, thermal specifications, and signal integrity demands vary sharply across product tiers. Procurement teams use these distinctions to match substrate complexity with deployment environment and regulatory jurisdiction.
Product Type:
MIIT electromagnetic compatibility certification applies differentially across product tiers, with multi-layer configurations facing the most extensive testing protocols for interlayer crosstalk and thermal cycling endurance.
- Multi-Layer:Twelve or more conductive layers route high-speed differential pairs and RF traces through sequential lamination processes. China's state-backed 5G tenders concentrate demand here, driven by massive MIMO antenna array complexity and MIIT traceability mandates.
- Rigid-Flex:Foldable interconnect schemes replace discrete cable assemblies in outdoor small cell enclosures, reducing connector failure points while enabling three-dimensional packaging geometries. Vietnam's manufacturing corridors show fastest uptake as contract equipment assembly clusters regional fulfillment hubs.
- Double-Sided:Standard configurations serve legacy 4G infrastructure and cost-optimized rural deployments with simpler thermal management requirements.
- Single-Sided:Basic power distribution boards appear in auxiliary equipment and test fixtures rather than active RF chains.
Multi-Layer sits at the top of the volume ranking, with Rigid-Flex climbing the fastest.
Technology:
Cost tier stratification separates premium microwave substrates from commodity RFID implementations, with material science investments determining margin capture.
- Microwave:Ultra-low-loss dielectric substrates with hydrocarbon-ceramic formulations enable millimeter-wave operation at 28 GHz and 39 GHz bands. South Korean and Japanese telecom equipment manufacturers drive qualification cycles for these specialized laminates.
- Optical Fiber:Hybrid electro-optical backplanes integrate photonic interconnects with traditional copper layers for fronthaul aggregation in dense urban deployments. European REACH substance restrictions accelerate phosphorus-based flame retardant adoption here.
- Satellite:Radiation-hardened specifications serve terrestrial-satellite convergence architectures in remote coverage extension.
- RFID:Passive tag infrastructure uses standard FR-4 derivatives with minimal certification burden for inventory and asset tracking applications.
Microwave commands the steepest pricing tier, while Optical Fiber gains share fastest in metropolitan fronthaul builds.
Application:
End-use maturity shapes procurement volume, with established telecommunication infrastructure contrasting against emerging industrial automation deployments.
- Telecommunication:Macro cells, small cells, and distributed antenna systems constitute the core demand pool, requiring controlled impedance traces and thermal management vias for sustained microwave operation.
- Military:Tempest and MIL-STD-810G environmental ruggedness specifications filter supplier pools to domestic security-cleared fabricators in each procurement jurisdiction.
- Broadcasting:High-power amplifier integration drives substrate thermal conductivity requirements in terrestrial transmission infrastructure.
- Industrial Automation:Private 5G networks for manufacturing floors create emerging demand for ruggedized boards with extended temperature range specifications.
Telecommunication anchors absolute volume, with Industrial Automation expanding most quickly as private network deployments accelerate.
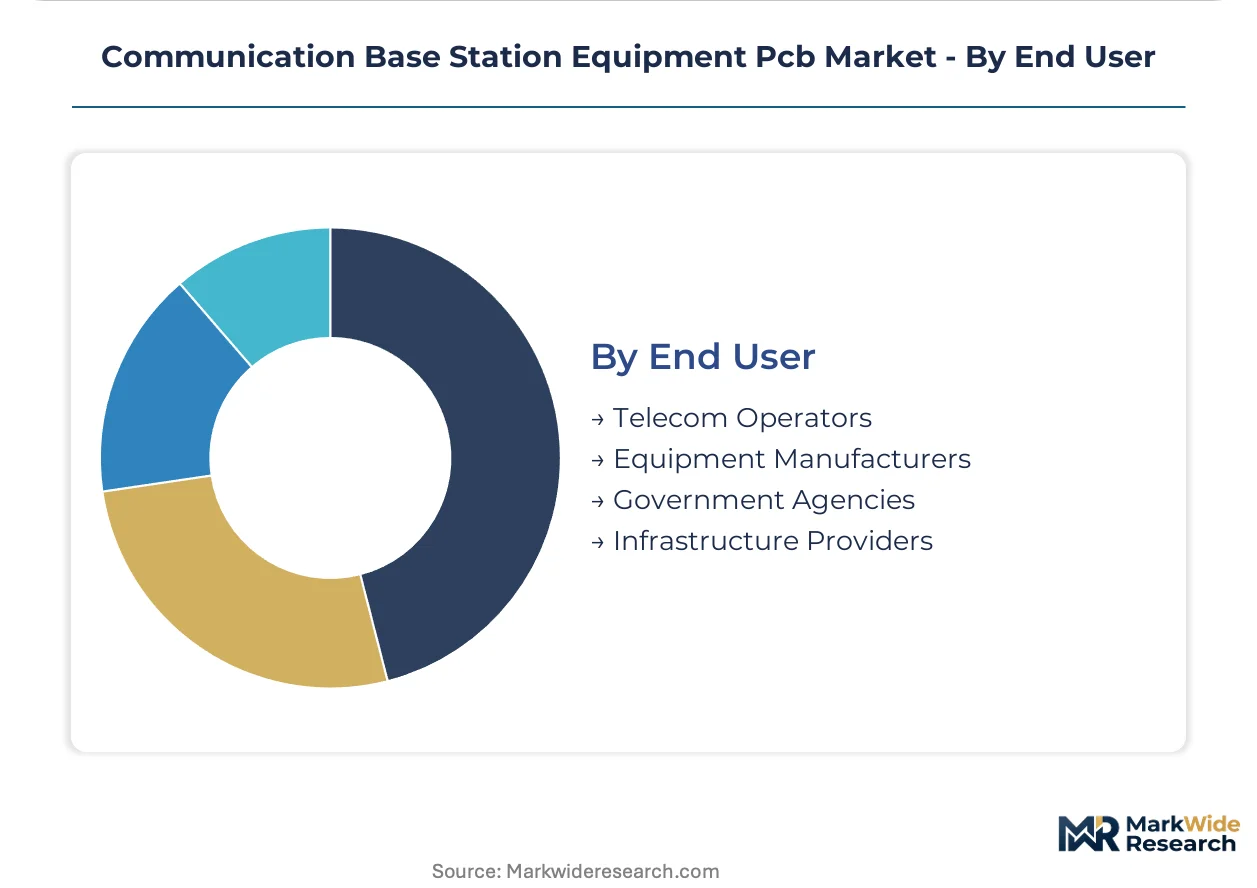
End User:
Customer type determines specification authority, with direct operator sourcing displacing traditional distributor channels for high-volume programs.
- Telecom Operators:Reliance Jio, Bharti Airtel, and Chinese state carriers negotiate substrate specifications directly with laminate suppliers, bypassing PCB fabricator material selection to satisfy component traceability mandates.
- Equipment Manufacturers:Ericsson, Nokia, and Huawei procurement teams manage multi-source qualification for second-source resilience in baseband processor and power amplifier integration.
- Infrastructure Providers:Tower companies and neutral host operators specify boards for outdoor enclosure reliability without direct RF design responsibility.
- Government Agencies:Spectrum allocation authorities and defense procurement offices influence standards adoption through tender specifications and research funding.
Telecom Operators sit at the top of the volume ranking, with Equipment Manufacturers climbing the fastest as consolidated procurement concentrates specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Base station PCB manufacturing traces its industrial lineage to post-war Japanese electronics clusters, later migrating to South Korean chaebols and Taiwanese substrate specialists before China's state-backed 5G buildout concentrated mass-scale fabrication capacity.
China
MIIT electromagnetic compatibility mandates filter supplier pools for state-backed 5G tenders. The ministry's traceability requirements favor direct laminate supplier relationships over fragmented sourcing. Shenzhen and Dongguan manufacturing corridors concentrate contract equipment assembly for domestic telecom operators.
South Korea
Samsung Electro-Mechanics leverages captive materials science for high-frequency laminate supply. METI-equivalent spectrum allocation decisions drive 28 GHz small cell deployment timelines. Seoul Capital Area fabrication clusters anchor premium substrate production for millimeter-wave applications.
Japan
Murata Manufacturing and TDK Corporation anchor hydrocarbon-ceramic laminate supply for ultra-low-loss applications. METI industrial policy supports domestic substrate R&D against Korean competition. Kyushu and Chubu industrial zones maintain specialized sequential lamination capacity.
Vietnam
Northern industrial zones in Bac Ninh and Hai Phong provinces cluster contract equipment assembly for regional fulfillment hubs. Foreign direct investment from Chinese and Korean telecom OEMs generates localized PCB demand. The country's manufacturing corridors represent the fastest-growing procurement geography.
India
Reliance Jio and Bharti Airtel's 5G network expansion creates demand for cost-optimized multi-layer boards. TRAI spectrum allocation frameworks shape equipment deployment timelines. Gujarat and Maharashtra industrial corridors attract PCB fabricators seeking alternatives to Chinese imports.
Communication Base Station Equipment Pcb Market Vendor Landscape
Premium-margin players sit above commodity-margin players across substrate material complexity and certification burden. The vendor base stratifies into three tiers: vertically integrated material suppliers with captive R&D infrastructure, specialized fabricators with sequential lamination expertise, and scale-driven assemblers competing on multi-layer throughput. Consolidation pressures concentrate among mid-tier players lacking long-term supply agreements for rolled annealed copper and hydrocarbon ceramic laminates. Dominant competitive moves include backward integration into substrate material production and geographic expansion toward Vietnam's manufacturing corridors.
Among Asian material specialists, Samsung Electro-Mechanics exemplifies the vertically integrated archetype with captive high-frequency laminate production. AT&S Austria Technologie & Systemtechnik AG anchors European fabrication capacity for advanced sequential lamination processes. Shenzhen Kinwong Electronic Co., Ltd. occupies a position within the scale-driven tier, competing across multi-layer and rigid-flex configurations for telecom equipment manufacturers.
| Leading Market Players |
|---|
| Samsung Electro-Mechanics |
| AT&S Austria Technologie & Systemtechnik AG |
| Murata Manufacturing |
| TDK Corporation |
| Ibiden Co., Ltd. |
| Unimicron Technology Corporation |
| Vishay Intertechnology |
| TT Electronics |
| Shenzhen Kinwong Electronic Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade stratification between MIIT-compliant laminates and standard multi-layer substrates splits both pricing power and procurement networks across the base station PCB market. This bifurcation concentrates margin capture among vertically integrated material specialists while compressing returns for fabricators locked into commodity copper-resin sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the market, with MIIT electromagnetic compatibility certification and hydrocarbon-ceramic substrate grade serving as the primary price differentiation drivers. Cost compression in standard multi-layer tiers is intensifying because Vietnamese contract manufacturers are consolidating procurement volumes for price leverage. Equipment manufacturers purchasing microwave-grade laminates for millimeter-wave deployments show the least price sensitivity, while rural 4G infrastructure buyers drive aggressive negotiation in economy segments.
Supply Chain Analysis
Returns and refurbishment flows for decommissioned base station equipment remain underdeveloped, creating stranded copper recovery opportunities that could reshape secondary material economics. Raw material dependencies center on rolled annealed copper from Japanese smelters, hydrocarbon ceramic laminates from South Korean chemical specialists, and phosphorus-based flame retardant resins subject to ECHA REACH restrictions. Single-source vulnerability concentrates in ultra-low-loss substrate supply from Murata Manufacturing and TDK Corporation. Distribution runs through direct laminate supplier relationships negotiated by telecom operators, bypassing traditional PCB fabricator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Base station PCB demand has shifted decisively toward premium microwave specifications as millimeter-wave spectrum deployment accelerates, marking a late-cycle quality transition where certification depth and material science capabilities determine competitive survival.
For Market Incumbents: To counter captive laminate production by Samsung Electro-Mechanics and Japanese material specialists, established fabricators must secure long-term supply agreements for rolled annealed copper and hydrocarbon ceramic substrates while building in-house electromagnetic compatibility testing laboratories to satisfy MIIT traceability mandates without third-party dependency.
For New Entrants and Emerging Players: Capture the rigid-flex antenna interconnect segment where foldable PCB schemes displace cable assemblies in Vietnam's manufacturing corridors, leveraging proximity to contract equipment assembly clusters and targeting cost-optimized multi-layer qualification for India's Reliance Jio and Bharti Airtel procurement programs.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized sequential lamination fabricators possessing captive phosphorus-based flame retardant formulation capabilities, as REACH substance restrictions force incumbent laminate suppliers into costly reformulation cycles. Monitor ECHA regulatory expansion timelines and MIIT certification backlog durations as inflection indicators for substrate material pricing power recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Material Production | Captive hydrocarbon-ceramic laminate supply secures margin capture against Japanese and Korean material specialists. |
| Geographic Expansion toward Vietnam Manufacturing Corridors | Proximity to Bac Ninh and Hai Phong contract assembly clusters reduces logistics costs for regional fulfillment. |
| MIIT Electromagnetic Compatibility Certification Investment | In-house testing capability filters competitors from Chinese state-backed 5G tenders requiring component traceability. |
| Phosphorus-Based Flame Retardant Formulation Qualification | REACH-compliant laminate chemistry opens European procurement channels closed to halogenated alternatives. |
| Rigid-Flex Sequential Lamination Capacity Addition | Foldable interconnect expertise addresses fastest-growing product category in outdoor small cell enclosures. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with base station equipment procurement managers, laminate supplier technical directors, PCB fabrication plant engineers, and telecom operator network deployment leads with secondary validation against FCC equipment authorization databases, MIIT electromagnetic compatibility certification registries, ECHA REACH substance restriction filings, and customs trade data for rolled annealed copper and hydrocarbon ceramic laminate flows. Bottom-up fabrication capacity estimates and top-down telecom infrastructure capex allocations were triangulated for cross-verification.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation models incorporating product type complexity tiers, substrate technology performance bands, application maturity stages, and end-user specification authority levels. CAGRs were derived from elasticity-adjusted demand curves tied to spectrum allocation timelines and radio head deployment densities. Millimeter-wave thermal dissipation constraints and raw material cost volatility served as key forecast sensitivity inputs.
MIIT regulatory enforcement intensity, ECHA substance restriction expansion, and copper-resin commodity price swings are the dominant revision risks that could alter trajectory assumptions. Practitioners should monitor these triggers for early signals of substrate supply constraints or certification timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Land Mobile Radio System Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
United States Set-Top Box Market
Telecom Hardware
Base Station Market
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
Set-Top Box Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Repeaters Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Very Small Aperture Terminal (VSAT) Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market
Telecom Hardware
Point-To-Point Antenna Market
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
Global FPGA in Telecom Sector Market