
 United States Safes and Vaults Market | 2026-2036
United States Safes and Vaults Market Size, Share, and Industry Trends Forecast 2026-2036
United States Safes and Vaults Market Intelligence
Aftermarket service revenue is reshaping profit pools across the United States safes and vaults industry. Liberty Safe leverages its dealer network to capture recurring maintenance and upgrade cycles in residential gun safe ownership. American Security Products anchors its position through in-house steel fabrication that controls cost structures across burglary-rated product lines. Diebold Nixdorf competes in bank vault servicing contracts where long-term relationships protect installed base revenue streams.
Safes and vaults are hardened steel enclosures engineered to resist forced entry, fire exposure, or both, typically constructed from 10- to 14-gauge steel with composite fireboard insulation layers rated for 30 to 120 minutes at specified temperatures. Gun safes command the largest product-type volume pool as state-level storage mandates expand ownership requirements among firearm households. Commercial-use applications generate premium pricing relative to home-use segments due to TL-rated burglary resistance and integrated alarm interfaces demanded by jewelry retailers and cannabis dispensaries. Steel remains the dominant material substrate, though composite constructions gain share where weight reduction enables upper-floor installation without structural reinforcement.
The Department of Justice, Underwriters Laboratories, and state-level firearm storage statutes collectively determine product compliance thresholds and market access conditions across the United States. UL 72 fire endurance ratings and UL 608 burglary resistance classifications function as de facto gatekeepers for commercial insurance eligibility and municipal building code approval. Stakeholders must monitor evolving state preemption battles over local gun safe mandates, as these regulatory fractures will determine which manufacturers bear certification cost burdens and which distribution channels gain preferential access to compliant inventory.
Market Dynamics
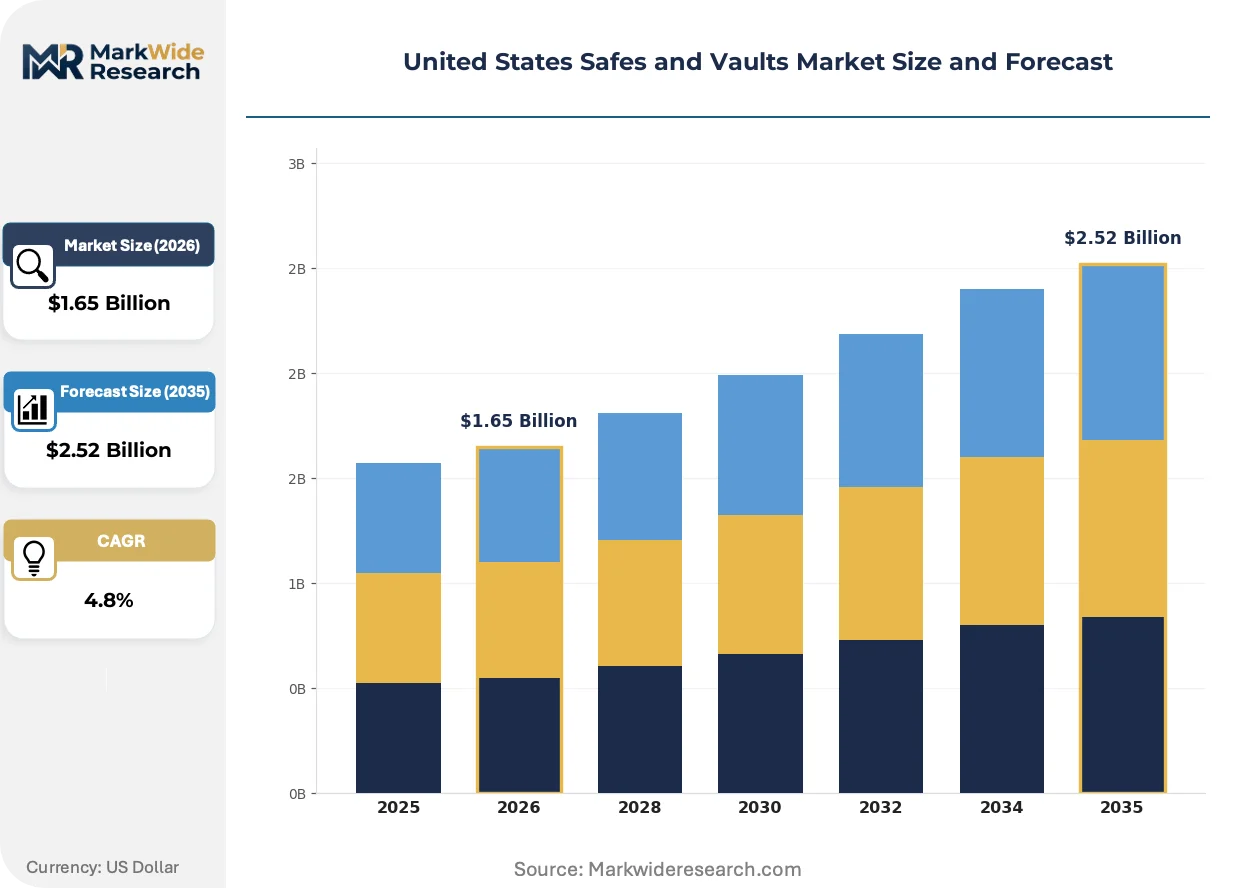
The United States safes and vaults market is being fundamentally restructured by state-level firearm storage mandates that are converting voluntary gun safe purchases into compliance-driven procurement cycles. These statutes are compressing replacement timelines and elevating UL certification from optional premium feature to baseline market access requirement.
Growth Catalysts
- State Firearm Storage Mandates:California, New York, and Massachusetts now require locked storage for firearms in households with children, directly expanding residential gun safe demand among 40 million firearm owners.
- Digital Asset Custody Infrastructure:Financial institutions are deploying specialized vault systems to secure cryptographic key hardware for cryptocurrency custody, creating a new institutional customer segment.
- UL 72 Fire Endurance Standards:Tightened fire resistance ratings for 120-minute protection at 1,700°F are driving replacement cycles in commercial document storage and residential high-value collections.
Market Restraints
- Steel Input Cost Volatility:Cold-rolled steel price swings of 30-40% since 2021 compress fabrication margins for domestic manufacturers dependent on Nucor and Cleveland-Cliffs supply contracts.
- Installation Labor Scarcity:Certified safe technicians capable of TL-30 vault door installation command premium wages in Texas and Florida, limiting dealer network expansion velocity.
- Modular Security Substitutes:Cloud-based surveillance and remote monitoring systems are displacing physical cash safes in small retail operations, particularly among cannabis dispensaries prioritizing real-time visibility.
Strategic Opportunities
- Upper-Floor Residential Installation:Composite-construction gun safes under 600 pounds enable sales to urban condominium owners in Chicago and Seattle without structural reinforcement costs.
- Cannabis Dispensary Cash Handling:State-legal marijuana retailers in Michigan and Illinois require TL-15 rated depositories with integrated alarm interfaces, a segment with minimal incumbent saturation.
- Aftermarket Service Unbundling:Independent service contracts for combination changes, bolt work maintenance, and fire seal replacement represent recurring revenue streams separate from hardware sales.
Industry Challenges
- UL Certification Timeline Compression:Extended testing queues at Underwriters Laboratories facilities delay product launches by 4-6 months, forcing manufacturers to pre-certify speculative designs.
- Dealer Technical Training Gaps:Proper installation of TL-rated vault doors requires mechanical and electronic security expertise that rural dealer networks struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Safes and Vaults Market |
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fireproof Safes, Burglary Safes, Gun Safes, Wall Safes Application: Home Use, Commercial Use, Industrial Use, Vehicle Use Material: Steel, Aluminum, Composite, Plastic Customer Type: Residential, Small Business, Large Enterprise, Government |
| Companies Covered | Liberty Safe, American Security Products, SentrySafe, Mesa Safe Company, Alpha Safe & Vault, Diebold Nixdorf, FireKing Security Group, Brown Safe Manufacturing, Gunnebo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Safes and Vaults Market Strategic Shifts & Innovations
Active innovation across the United States safes and vaults market centers on material science breakthroughs, biometric integration, and the convergence of physical security with digital authentication protocols. These developments are compressing product lifecycles and elevating performance benchmarks.
Biometric locking systems are hybridizing traditional mechanical bolt work with capacitive fingerprint sensors and Bluetooth-enabled audit trails. Jewelry retailers and high-net-worth residential buyers in California and Florida are adopting these systems at accelerating rates, replacing dial combination locks within three-year replacement windows. This convergence is compressing price premiums between electronic and mechanical offerings while creating new failure-mode liabilities for manufacturers.
The Department of Justice is coordinating with state attorneys general to enforce firearm safe storage statutes through civil liability frameworks that expose non-compliant manufacturers to product defect claims. This regulatory pressure is forcing redesigns of entry-level gun safes to meet UL 1037 residential security container standards previously reserved for premium tiers. Manufacturers serving the Texas and Arizona markets are responding by pre-integrating cable-lock compatibility and tamper-evident sealing mechanisms.
Direct-to-consumer channels are capturing share from traditional locksmith and sporting goods dealer networks, particularly for gun safes under 750 pounds shippable via LTL freight. Millennials purchasing first firearms prefer online configuration tools with video installation guidance over in-store consultation. This behavioral shift is most visible in the Pacific Northwest and Mountain West regions where rural dealer density remains low and Amazon delivery infrastructure penetrates remote addresses.
United States Safes and Vaults Market Segmentation
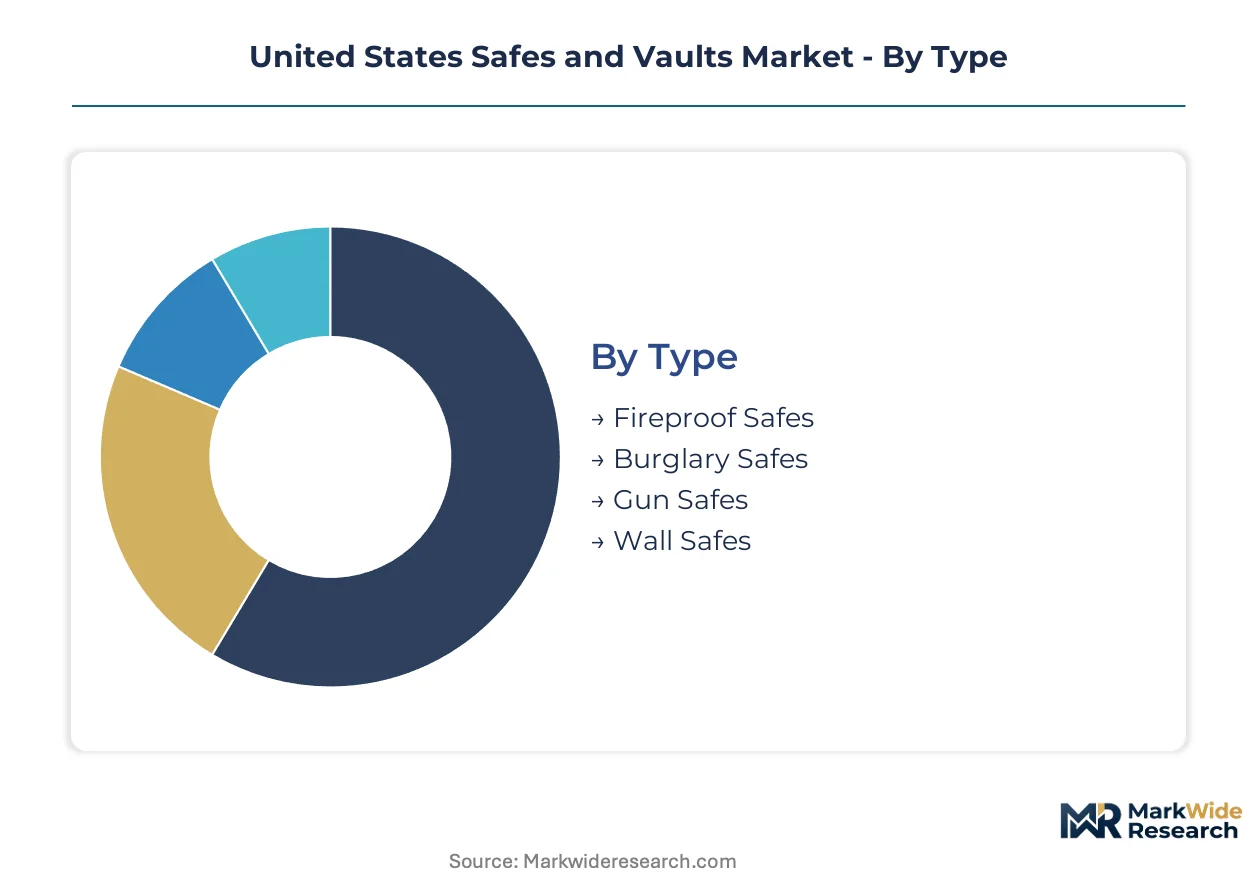
Segmentation in the United States safes and vaults market reveals how regulatory pressure, material science, and end-use specialization create distinct profit pools. Each dimension exposes different competitive dynamics and certification burdens.
Type:
Mature product lines dominate volume while emerging categories reshape growth trajectories across residential and institutional channels.
- Fireproof Safes:Constructed with composite fireboard insulation rated for 30 to 120 minutes at specified temperatures, these enclosures protect documents and digital media from thermal damage. Demand concentrates in California and Florida where wildfire risk and hurricane exposure elevate insurance requirements for residential collections and small business records.
- Gun Safes:Hardened steel cabinets engineered for firearm storage incorporate UL 1037 residential security container compliance and cable-lock compatibility. State mandates in Texas, Arizona, and Massachusetts convert voluntary purchases into compliance-driven procurement among 40 million firearm-owning households.
- Burglary Safes:TL-rated steel enclosures resist forced entry through reinforced bolt work and drill-resistant hardplates. Jewelry retailers and cannabis dispensaries in Michigan and Illinois specify TL-15 and TL-30 ratings for insurance eligibility.
- Wall Safes:Recessed installation between studs enables concealed storage in residential and light commercial settings. Urban condominium owners in Chicago and Seattle favor these units where floor loading restricts freestanding alternatives.
Gun Safes handles the majority of throughput; Wall Safes is climbing the fastest on share.
Application:
Cost tier differentiation separates premium institutional installations from mass-market residential procurement.
- Commercial Use:TL-rated vault systems with integrated alarm interfaces serve cash-intensive operations. Cannabis dispensaries in Illinois and Michigan require specialized depositories with real-time monitoring connectivity.
- Home Use:Residential gun safes and fireproof cabinets protect firearms and valuables in single-family dwellings. State storage mandates in New York and Massachusetts accelerate replacement cycles among compliance-conscious owners.
- Industrial Use:Heavy-duty enclosures secure tools, hazardous materials, and operational assets in manufacturing facilities. OSHA documentation requirements drive specification of lockout-tagout compatible storage.
- Vehicle Use:Compact steel vaults mount within automobiles, trucks, and fleet vehicles for secure transport. Armored car operators and law enforcement agencies in Texas and Florida specify these for mobile asset protection.
Home Use generates the highest unit volume; Commercial Use commands the steepest expansion trajectory as cannabis retail cash handling requirements proliferate.
Material:
Supply concentration in domestic steel production shapes cost structures and availability constraints.
- Steel:Cold-rolled 10- to 14-gauge carbon steel remains the dominant substrate for burglary-rated and fire-rated enclosures. Nucor and Cleveland-Cliffs supply contracts determine fabrication margins for domestic manufacturers.
- Composite:Layered constructions combining steel skins with fire-resistant cores reduce weight for upper-floor installation. Chicago and Seattle condominium owners access these units without structural reinforcement costs.
- Aluminum:Lightweight corrosion-resistant alloys serve marine and vehicle applications where weight reduction priorities exceed burglary resistance requirements.
- Plastic:Polymer enclosures address low-security portable storage needs and temporary document protection. Minimal penetration in regulated commercial segments due to UL certification ineligibility.
Steel dominates fabrication throughput; Composite is gaining share fastest among urban residential buyers.
Customer Type:
Procurement authority and compliance exposure separate institutional buyers from discretionary consumers.
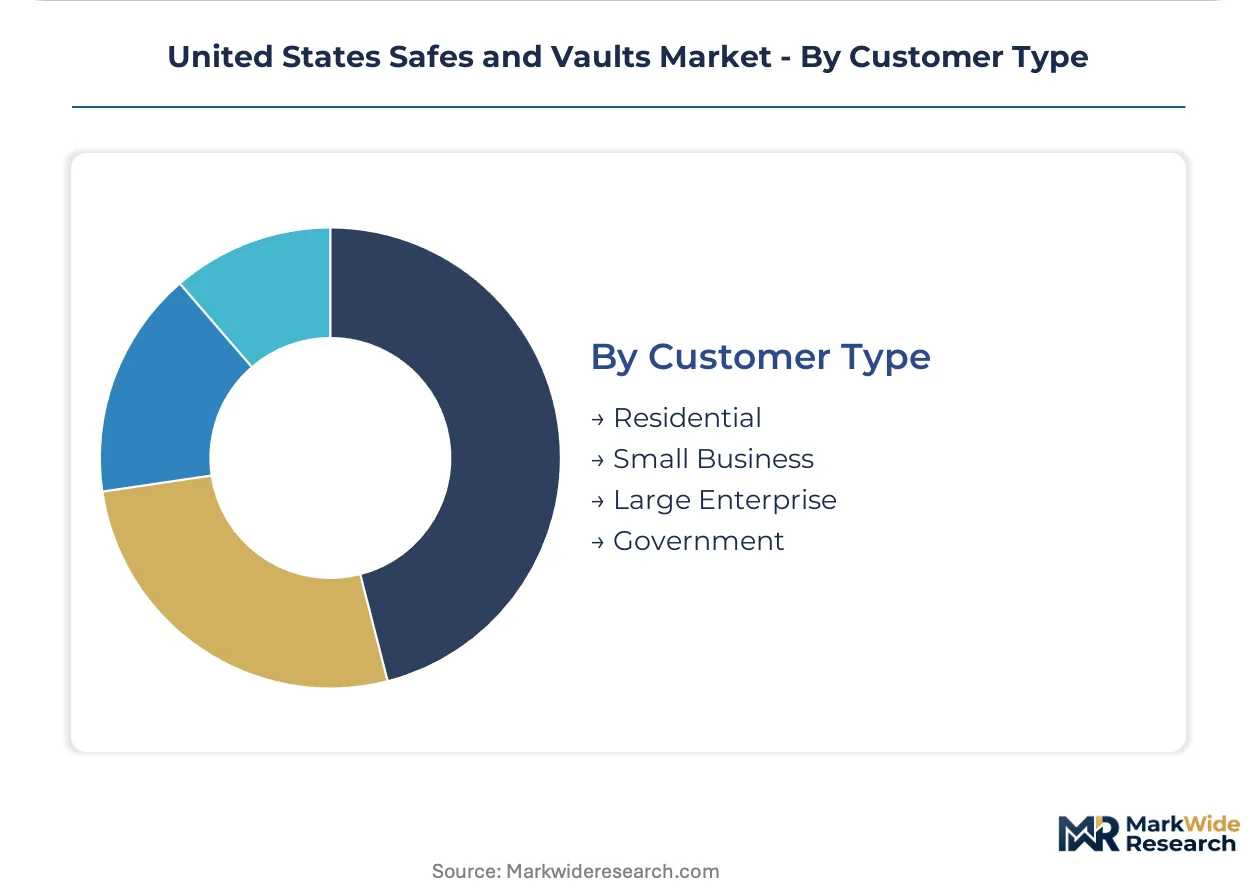
- Residential:Individual households purchase gun safes and fireproof cabinets through dealer networks and direct-to-consumer channels. Millennial first-time firearm owners in the Pacific Northwest prefer online configuration tools with video installation guidance.
- Small Business:Independent retailers, cannabis dispensaries, and jewelry stores specify TL-rated depositories for insurance and regulatory compliance. Limited technical staff drives preference for integrated alarm interfaces and maintenance contracts.
- Large Enterprise:Financial institutions deploy specialized vault infrastructure for digital asset custody keys and physical records. Long-term servicing contracts protect installed base revenue for incumbent vendors.
- Government:Federal, state, and municipal agencies procure GSA-approved containers for classified materials and evidence storage. Procurement runs through specified vendor schedules with extended qualification timelines.
Residential accounts for the greatest unit movement; Small Business shows the steepest growth curve as state-legal cannabis retail expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across U.S. sub-regions. Coastal metropolitan buyers absorb premium pricing for UL-certified fire ratings and biometric features. Inland and Sun Belt markets prioritize volume throughput and dealer network density over certification tiers.
California
Wildfire exposure and seismic building codes drive demand for 120-minute UL 72 fire-rated enclosures. The California Department of Justice enforces firearm storage mandates through civil liability frameworks. Los Angeles and San Diego metropolitan clusters concentrate jewelry retailer procurement of TL-30 burglary-rated vault systems.
Texas
Firearm ownership density and cash-intensive energy sector operations sustain dual demand streams. State preemption statutes block municipal gun safe ordinances, preserving voluntary purchase patterns. Houston and Dallas-Fort Worth anchor commercial vault installation capacity for bank and credit union infrastructure.
Florida
Hurricane exposure elevates insurance-driven fireproof safe specifications for residential document protection. Florida statute mandates locked firearm storage in households with minors, accelerating replacement cycles. Miami and Tampa Bay corridor cannabis dispensaries specify TL-15 depositories with integrated alarm interfaces.
Illinois
Chicago condominium density restricts floor loading, favoring composite-construction gun safes under 600 pounds. State-legal cannabis retail creates regulated cash-handling requirements without incumbent vault vendor saturation. Cook County and collar counties concentrate small business TL-rated depository demand.
Michigan
Automotive supplier cash operations and recreational firearm ownership generate bifurcated demand profiles. Michigan cannabis dispensary regulations mandate secure cash storage with audit trail capabilities. Detroit and Grand Rapids metropolitan areas exhibit fastest-growing commercial vault installation velocity.
United States Safes and Vaults Market Key Industry Players
Capability concentration sits with fabrication specialists controlling in-house steel forming and UL certification pipelines; scale advantage sits with diversified security conglomerates leveraging installed base servicing contracts. The market structures around three archetypes: domestic steel fabricators with captive heat-treating capacity, electronic security integrators bundling physical and digital authentication, and regional safe dealers capturing aftermarket maintenance revenue. Competitive moves center on vertical integration into cold-rolled steel supply and pre-certification of speculative product designs to compress UL testing timelines.
Among domestic specialists, Liberty Safe and American Security Products exemplify the fabrication-centric archetype with dealer network density in Sun Belt firearm markets. Diebold Nixdorf occupies the institutional servicing tier where long-term bank relationships protect recurring revenue streams. These three anchors illustrate how competitive positioning splits between residential volume throughput and commercial installed base retention.
| Leading Market Players |
|---|
| Liberty Safe |
| American Security Products |
| SentrySafe |
| Mesa Safe Company |
| Alpha Safe & Vault |
| Diebold Nixdorf |
| FireKing Security Group |
| Brown Safe Manufacturing |
| Gunnebo |
| Others |
Cost & Logistics Intelligence
Cold-rolled steel supply concentration at Nucor and Cleveland-Cliffs anchors margin distribution across fabrication tiers, with captive heat-treating capacity determining who captures premium pricing in UL-certified segments.
Pricing Analysis
Aftermarket service contracts and maintenance subscriptions drive lifetime value accumulation across residential and commercial installed bases. Three-tier pricing structure across premium, standard, and economy levels stratifies by UL certification grade and integrated alarm capability. Pricing pressure stems from cold-rolled steel input volatility compressing fabrication margins at the standard tier. Small business buyers exhibit highest price sensitivity, while financial institutions absorb premium positioning for digital asset custody infrastructure.
Supply Chain Analysis
Upstream feedstock dependence on domestic cold-rolled steel production centers on Nucor and Cleveland-Cliffs mill capacity. The supply chain draws from 10- to 14-gauge carbon steel coils, composite fireboard insulation, and electronic lock components. Single-source vulnerability at UL testing facilities creates certification bottlenecks extending product launch timelines. Distribution runs through locksmith networks, sporting goods dealers, and direct-to-consumer LTL freight channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
State-level firearm storage mandates are accelerating early-cycle penetration among compliance-driven buyers, converting voluntary purchases into regulated procurement cycles.
For Market Incumbents: Insulate recurring revenue streams by deepening aftermarket service contract penetration and pre-certifying speculative designs to compress UL testing queues. Threat from modular security substitutes displacing physical cash safes demands accelerated biometric integration investment. Backward integration into captive steel supply hedges margin compression from cold-rolled price volatility. For New Entrants and Emerging Players: Build out composite-construction capabilities targeting Chicago and Seattle condominium owners restricted by floor loading constraints. Cannabis dispensary cash-handling requirements in Michigan and Illinois present underpenetrated white space with minimal incumbent saturation. Direct-to-consumer configuration tools with video installation guidance capture millennial first-time firearm owners. For Investors and Strategic Acquirers: Capital is best deployed toward fabrication specialists with captive heat-treating capacity and established UL certification pipelines. Long-term viability over the coming decade hinges on regulatory tailwinds from firearm storage mandates and digital asset custody infrastructure buildout. Monitor state preemption battles over local gun safe ordinances as inflection indicator for certification cost burden distribution.| Strategic Initiative | Industry Significance |
|---|---|
| UL Certification Pre-Investment | Compresses testing timelines at Underwriters Laboratories facilities by 4-6 months for competitive launch velocity. |
| Biometric Lock Integration | Captures jewelry retailer and high-net-worth residential replacement cycles in California and Florida markets. |
| Aftermarket Service Unbundling | Generates recurring revenue from combination changes, bolt work maintenance, and fire seal replacement contracts. |
| Composite Construction Scale-Up | Enables upper-floor installation in Chicago and Seattle condominiums without structural reinforcement costs. |
| Cannabis Dispensary Channel Development | Addresses TL-15 depository demand in Michigan and Illinois with integrated alarm interface specifications. |
Research Approach
A spread of perspectives from safe manufacturing executives, UL certification specialists, locksmith dealer network operators, and cannabis dispensary compliance officers converged on the working assumptions. Primary fieldwork combined with secondary validation against UL certification databases, state legislative tracking systems, and steel industry production reports. Bottom-up unit demand modeling triangulated against top-down market value reconstruction across the analysis window.
Demand-supply-balance framing anchored the analytical approach throughout the projection horizon. Segmentation dimensions modeled include product type, application, material substrate, and customer procurement authority. CAGRs were derived from regression analysis of historical replacement cycles and regulatory mandate implementation timelines. Fire resistance rating adoption curves and firearm ownership density projections served as industry-specific forecast inputs.
Stress conditions across steel price volatility bands, UL testing queue durations, and state regulatory preemption outcomes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding mandate enforcement intensity and cryptocurrency custody infrastructure buildout. Cross-checking against Nucor and Cleveland-Cliffs production capacity disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Hazard and Safety Indicator Control Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Mask Particulate Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Eye Protection Lamp Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Machine Safeguarding Solution Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Guards Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Cryogenic PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Smart PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Combat Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Booster Seat Type Child Safety Seats Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market