
 Cryogenic PPE Market | 2026-2036
Cryogenic PPE Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic PPE Market Analysis
Multi-source procurement for cryogenic safety equipment is shifting toward consolidated supplier agreements with integrated certification support. Honeywell International Inc. leverages its respiratory protection heritage to bundle thermal garments with gas detection systems. 3M Company anchors its position through proprietary Thinsulate thermal barrier technologies across glove and suit product lines. DuPont de Nemours Inc. differentiates via Kevlar-reinforced aramid composites that withstand both cryogenic splash and mechanical abrasion hazards.
Cryogenic PPE encompasses engineered personal protective equipment designed to shield workers from thermal injuries caused by exposure to materials below minus 150 degrees Celsius, typically constructed with multilayer insulation systems combining vapor barriers, thermal liners, and outer shells rated to liquid nitrogen temperatures. The equipment serves critical functions in preventing frostbite, cryogenic burns, and embrittlement-related trauma during handling of liquefied gases. Gloves and suits command the largest share of product-type revenue due to mandatory full-coverage requirements in LNG and industrial gas operations, while aramid and insulated fabric materials capture premium positioning through extended service life and multi-hazard compatibility. Research institutions represent the fastest-growing end-user segment as cryo-electron microscopy and quantum computing laboratories proliferate, though manufacturing and oil & gas operations still dominate absolute volume procurement.
OSHA's 1910.132 general PPE standard and the EPA's risk management program under 40 CFR Part 68 collectively mandate hazard assessments that specify cryogenic PPE selection criteria for covered facilities. The EU's PPE Regulation 2016/425 imposes CE marking and module B conformity assessment requirements that filter non-compliant suppliers from European industrial gas markets. ISO 20345 and ISO 20347 footwear standards further shape boot segment specifications for cold-work environments. Stakeholders must monitor evolving hydrogen economy infrastructure codes, as liquid hydrogen handling protocols will recalibrate thermal protection ratings and demand new certification benchmarks.
Market Dynamics
Consolidated supplier agreements are displacing fragmented multi-vendor procurement as LNG terminal operators seek integrated certification support and unified liability coverage across thermal protection systems.
Growth Catalysts
- Liquefaction capacity expansion:LNG infrastructure buildout across Qatar, Australia, and the United States is mandating full-body cryogenic suit deployment for terminal commissioning crews.
- OSHA 1910.132 enforcement tightening:Updated hazard assessment protocols are forcing petrochemical facilities to upgrade thermal protection ratings for sub-zero exposure scenarios.
- Aramid composite advancement:Multi-hazard compatibility in Kevlar-reinforced liners is extending replacement cycles and reducing total cost of ownership for industrial gas handlers.
Market Restraints
- Helium supply volatility:Leak-testing protocols for vapor barrier integrity depend on helium, whose price swings directly inflate quality assurance costs.
- DuPont-Honeywell duopoly concentration:Proprietary Thinsulate and Kevlar technologies lock mid-tier manufacturers out of premium thermal barrier supply.
- ISO 20345 certification bottlenecks:Extended third-party testing timelines for cold-work footwear delay product launches by 8-14 months.
Strategic Opportunities
- Research institution underpenetration:Cryo-electron microscopy and quantum computing laboratories in Germany and Japan lack standardized PPE procurement frameworks.
- Hydrogen economy codes:Liquid hydrogen handling protocols under development will recalibrate thermal protection ratings and create first-mover certification advantages.
- CE marking module B acceleration:EU PPE Regulation 2016/425 conformity assessment pre-approval is filtering non-compliant suppliers and opening share for certified entrants.
Industry Challenges
- Cryogenic materials engineering talent scarcity:Vapor barrier design and multilayer insulation optimization require specialized expertise concentrated at a handful of polymer science programs.
- Legacy system integration friction:New thermal garments must interface with existing respiratory protection and gas detection infrastructure without compromising mobility ratings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic PPE Market |
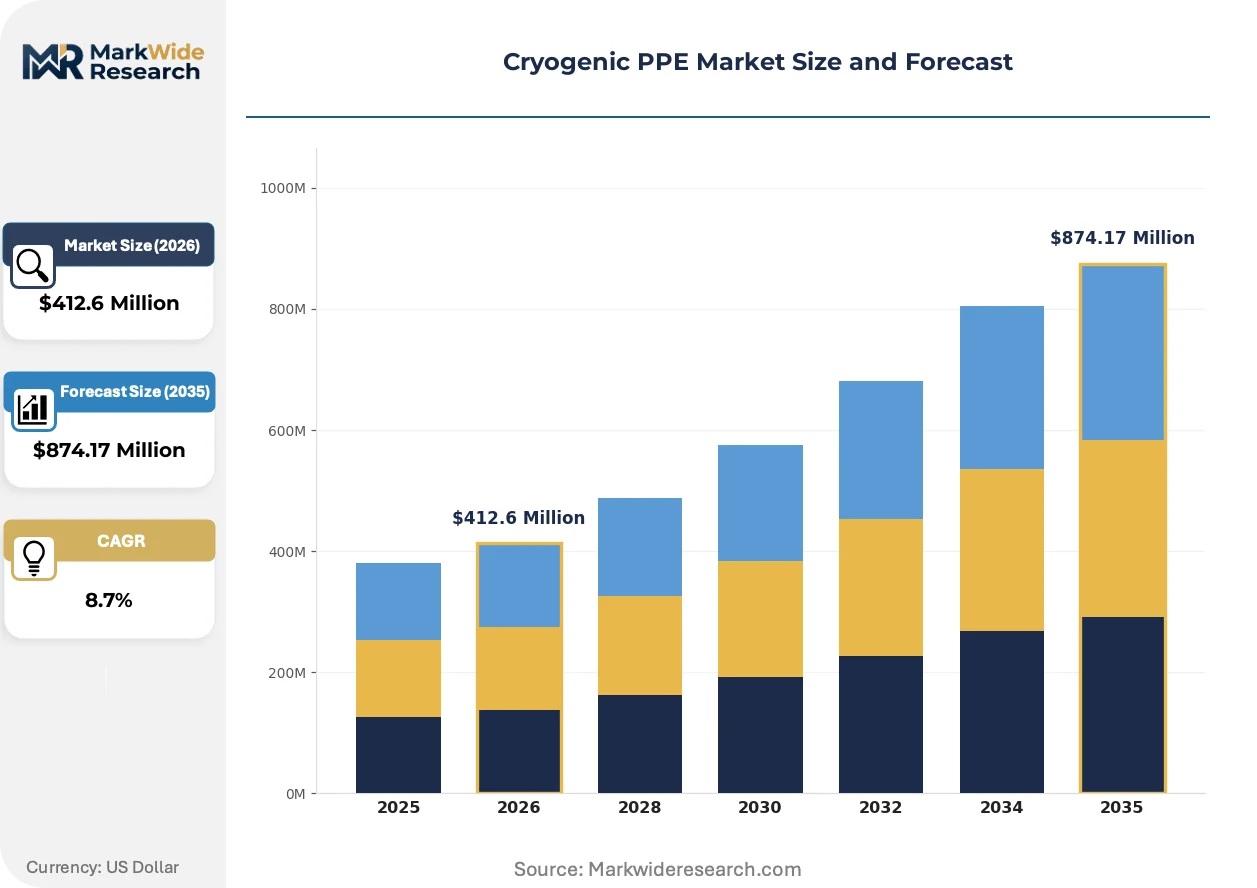
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Suits, Boots, Helmets Material: Polyurethane, Neoprene, Aramid, Insulated Fabrics End User: Manufacturing, Oil & Gas, Research Institutions, Medical Facilities Application: Storage, Transportation, Handling, Maintenance |
| Companies Covered | Honeywell International Inc., 3M Company, DuPont de Nemours Inc., Linde plc, Air Products and Chemicals Inc., Air Liquide, Ansell Ltd., Avantor Inc., Bunzl Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic PPE Market Emerging Trajectories
Material science breakthroughs and regulatory harmonization pressures are compressing product development cycles while elevating certification requirements across thermal protection categories.
Multilayer insulation systems are modularizing around standardized vapor barrier interfaces that allow end-users to swap thermal liners without replacing complete garment assemblies. Research institutions and industrial gas facilities are adopting this approach to reduce spare parts inventory and accelerate field repairs. The shift is compressing supplier service revenue streams while expanding attach-rate opportunities for consumable liner components.
EU PPE Regulation 2016/425 is tightening CE marking enforcement for cryogenic protective equipment entering European industrial gas markets. Module B conformity assessment pre-approval now filters approximately one-third of previously active suppliers from tender participation. German and French LNG terminal operators are responding by pre-qualifying vendors against harmonized EN standards before procurement initiation.
Integrated safety system bundling is displacing standalone garment purchasing as Honeywell leverages respiratory protection heritage to attach thermal garments to gas detection contracts. Oil and gas majors along the US Gulf Coast are consolidating supplier relationships to reduce compliance documentation overhead. This pattern is most pronounced in Qatar and Australia, where national oil companies mandate single-source accountability for worker safety systems.
Cryogenic PPE Market Segmentation
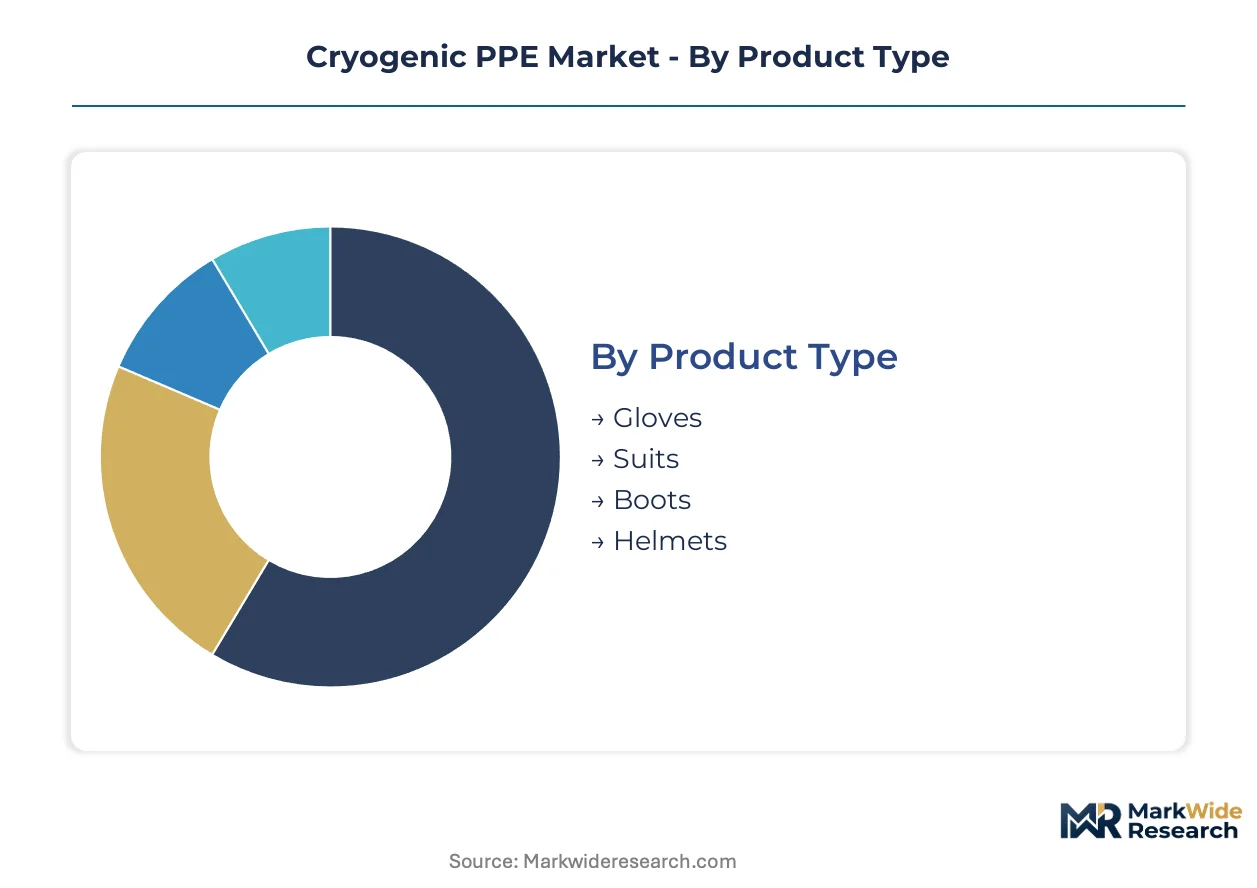
Cryogenic PPE procurement patterns diverge sharply across product categories and end-use environments. Capital deployment, certification complexity, and replacement cycle economics vary by segment in ways that reshape supplier priorities and buyer negotiation leverage.
Product Type:
Capital intensity concentrates most heavily in full-body systems requiring integrated respiratory interfaces and multilayer vapor barrier engineering.
- Suits:Full-body cryogenic suits demand the highest upfront investment due to complex multilayer construction combining vapor barriers, thermal liners, and Kevlar-reinforced outer shells. LNG terminal operators across Qatar, Australia, and the United States drive procurement volume as liquefaction capacity expands and OSHA thermal protection mandates tighten.
- Gloves:Hand protection represents the highest-volume procurement category with mandatory full-coverage requirements in industrial gas operations. Replacement cycles accelerate in shale gas processing corridors where mechanical abrasion and thermal stress degrade palm and finger insulation most rapidly.
- Boots:Footwear specifications follow ISO 20345 and ISO 20347 standards for cold-work environments, with third-party testing timelines extending product launches by 8-14 months.
- Helmets:Head and face protection integrates with existing respiratory infrastructure, creating interface compatibility requirements that complicate supplier selection.
Suits absorb the bulk of installed capacity; gloves are expanding most quickly.
Material:
Raw material sourcing strategies separate premium thermal barrier suppliers from commodity fabric converters.
- Aramid:Kevlar-reinforced composites command premium positioning through multi-hazard compatibility against both cryogenic splash and mechanical abrasion. DuPont proprietary supply chains limit mid-tier manufacturer access to certified fiber inputs.
- Insulated Fabrics:3M Thinsulate thermal barriers anchor glove and suit product lines with proprietary lofted fiber construction that maintains insulating properties at liquid nitrogen temperatures.
- Polyurethane:Vapor barrier films depend on helium leak-testing protocols for integrity verification, exposing quality assurance costs to helium price volatility.
- Neoprene:Synthetic rubber liners offer cost-competitive alternatives for lower-temperature applications where extreme cryogenic exposure is intermittent rather than continuous.
Aramid dominates premium contract value; insulated fabrics claim the steepest expansion trajectory as modular liner systems gain adoption.
End User:
Procurement sophistication and certification documentation requirements fragment sharply across buyer categories.
- Oil & Gas:Integrated majors along the US Gulf Coast petrochemical corridor consolidate supplier relationships to reduce compliance overhead, with national oil companies in Qatar and Australia mandating single-source accountability for worker safety systems.
- Manufacturing:Industrial gas handlers prioritize total cost of ownership metrics, extending replacement cycles through aramid composite durability.
- Research Institutions:Cryo-electron microscopy and quantum computing laboratories in Germany and Japan lack standardized procurement frameworks, creating underpenetrated demand for certified thermal protection.
- Medical Facilities:Healthcare applications center on liquid nitrogen handling for cryopreservation and dermatological procedures, with biobanking infrastructure expansion driving incremental volume.
Oil & Gas commands absolute procurement volume; research institutions are gaining share fastest.
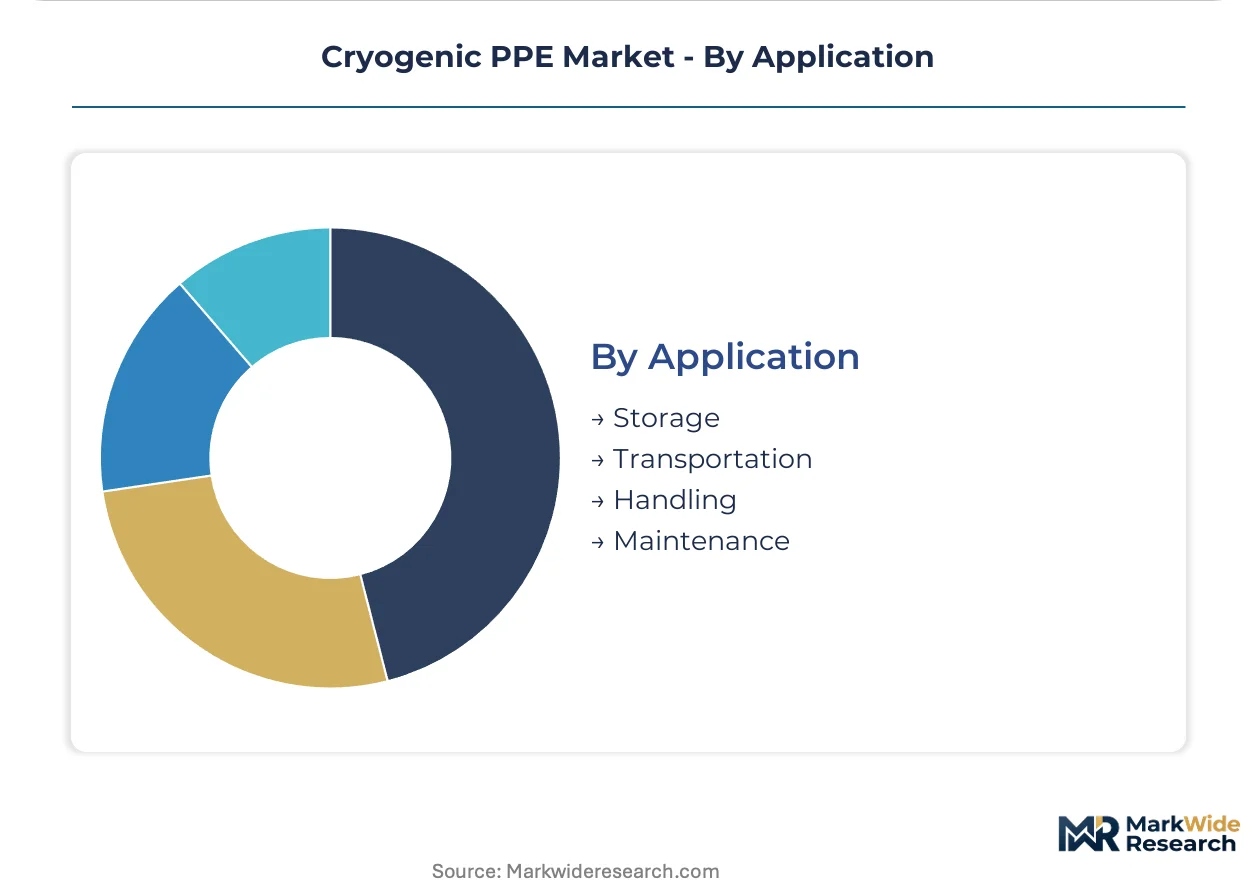
Application:
Operational risk profiles and exposure duration determine thermal protection rating requirements and garment specification intensity.
- Handling:Direct contact with liquefied gases mandates highest thermal protection ratings and full-body coverage, driving specification intensity for gloves and suits in LNG transfer operations.
- Maintenance:Repair and inspection activities require compatibility with existing respiratory and gas detection infrastructure without compromising mobility ratings.
- Storage:Static containment monitoring involves lower thermal stress but demands prolonged wear comfort for extended shift durations.
- Transportation:Mobile cryogenic systems expose workers to variable ambient conditions and splash hazards during loading and unloading sequences.
Handling applications concentrate the most demanding specifications; maintenance is climbing the fastest as legacy infrastructure ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's North Field expansion and Australia's Prelude FLNG facility anchor liquefaction capacity buildouts that concentrate cryogenic PPE procurement in coastal industrial zones. Shale gas processing corridors across the United States Gulf Coast drive replacement cycles for thermal protection equipment as OSHA enforcement tightens.
United States
LNG export terminals along the Texas and Louisiana coastlines mandate full-body cryogenic suits for commissioning crews as liquefaction trains come online. OSHA's updated 1910.132 hazard assessment protocols force petrochemical facilities to upgrade thermal protection ratings for sub-zero exposure scenarios. The Houston Ship Channel petrochemical corridor concentrates procurement volume for insulated gloves and face shields.
Qatar
North Field East and North Field South expansion projects represent the largest single concentration of new LNG capacity under construction globally. The national oil company mandates single-source accountability for worker safety systems across integrated terminal operations. Ras Laffan Industrial City clusters liquefaction, storage, and marine loading infrastructure that drives concentrated PPE deployment.
Australia
Prelude FLNG and Ichthys onshore processing facilities maintain steady demand for cryogenic suits and gloves in offshore and coastal environments. The country's national regulator enforces workplace health and safety standards that align with ISO thermal protection benchmarks. The Burrup Peninsula in Western Australia hosts multiple gas processing trains that sustain replacement cycle economics.
Germany
Cryo-electron microscopy laboratories and quantum computing research facilities in Munich and Heidelberg lack standardized PPE procurement frameworks. The EU's PPE Regulation 2016/425 imposes CE marking and module B conformity assessment requirements that filter non-compliant suppliers from industrial gas markets. The Bavarian research corridor represents underpenetrated demand for certified thermal protection in academic settings.
Japan
Quantum computing laboratories and cryogenic research facilities in Tsukuba and Osaka drive emerging demand for specialized thermal protection equipment. The country's Ministry of Economy, Trade and Industry oversees industrial safety standards that incorporate cryogenic handling protocols. The Kanto region's concentration of advanced research infrastructure positions it as the fastest-growing end-user segment for laboratory-grade PPE.
Cryogenic PPE Market Vendor Landscape
Global majors compete with regional champions across certification breadth and integrated safety system bundling. The market structure tilts toward consolidation as LNG terminal operators seek unified liability coverage and streamlined compliance documentation. Three archetypes dominate: diversified industrial conglomerates with respiratory protection heritage, specialty materials suppliers with proprietary thermal barrier technologies, and industrial gas operators with captive PPE distribution channels. Competitive moves center on strategic partnerships for integrated safety systems and geographic expansion into underpenetrated research institution markets.
Within the diversified conglomerate tier, Honeywell International Inc. and 3M Company exemplify players leveraging respiratory protection heritage to attach thermal garments to broader safety contracts. DuPont de Nemours Inc. occupies a position representing specialty materials suppliers with proprietary aramid composite technologies. Among industrial gas operators with captive distribution, Linde plc and Air Liquide anchor positions that bundle PPE procurement with gas supply agreements. These named entities represent archetypal competitive positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| 3M Company |
| DuPont de Nemours Inc. |
| Linde plc |
| Air Products and Chemicals Inc. |
| Air Liquide |
| Ansell Ltd. |
| Avantor Inc. |
| Bunzl Plc |
| Others |
Supply Flow & Price Mechanics
Helium price volatility cascades through cryogenic PPE manufacturing into three distinct pricing tiers, with vapor barrier integrity testing costs dictating premium-mid-economy pricing differentiation across LNG terminal procurement contracts.
Pricing Analysis
Warranty and service bundling separates premium contracts from transactional procurement, with integrated certification support and unified liability coverage commanding substantial premiums in Qatar and Australian national oil company tenders. Price differentiation centers on CE marking module B pre-approval status and ISO 20347 cold-work footwear certification tier, with unbundled spare liner components eroding service revenue streams. Cost compression in standard-grade aramid composites is intensifying as mid-tier manufacturers seek alternative thermal barrier inputs. Research institutions in Germany and Japan exhibit highest price sensitivity due to unstandardized procurement frameworks, while integrated oil and gas majors prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Reverse logistics for thermal liner refurbishment and vapor barrier remanufacturing flows through specialized service centers in the United States, Germany, and Japan, extending garment lifecycle economics for industrial gas handlers. Raw material sourcing draws from DuPont's Kevlar fiber production in the United States, 3M's Thinsulate lofted fiber facilities in Minnesota, and polyurethane film suppliers concentrated in South Korea. Single-source vulnerability in certified aramid composite supply creates structural risk for mid-tier manufacturers locked out of proprietary thermal barrier networks. Distribution runs through industrial gas operators' captive channels and consolidated supplier agreements with integrated safety system bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryogenic PPE supply remains constrained by specialized polymer science talent scarcity and extended ISO 20345 certification timelines, propping pricing power for incumbent suppliers with pre-qualified thermal barrier technologies.
For Market Incumbents: Deploy modular liner system architectures to capture attach-rate revenue from consumable components while compressing competitor service income. DuPont and Honeywell should deepen backward integration into vapor barrier polymer production to defend against emerging aramid composite substitutes. Capacity addition in Germany and Japan addresses underpenetrated research institution demand before standardization takes hold. For New Entrants and Emerging Players: EU PPE Regulation 2016/425 in Europe opens a window for CE marking module B pre-approved specialists to capture share from filtered non-compliant suppliers. Target cryo-electron microscopy laboratories in Munich and Heidelberg through direct academic procurement frameworks bypassing industrial distributor markups. Partner with national hydrogen economy code development committees to establish first-mover certification benchmarks for liquid hydrogen handling protocols. For Investors and Strategic Acquirers: The window for entry favors vertically integrated material science specialists with captive vapor barrier engineering capabilities and existing respiratory protection infrastructure. Long-term viability hinges on positioning for hydrogen economy thermal protection standard-setting rather than commoditized LNG terminal replacement cycles. Monitor liquid hydrogen infrastructure code finalization timelines as the critical inflection signal for thermal protection rating recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Liner System Expansion | Captures recurring revenue from consumable thermal liner replacements in LNG operations. |
| CE Marking Module B Pre-Approval | Filters non-compliant competitors from European industrial gas tender participation. |
| Hydrogen Economy Code Engagement | Positions suppliers for first-mover certification advantages in liquid hydrogen handling. |
| Research Institution Direct Distribution | Bypasses industrial markups in underpenetrated German and Japanese academic markets. |
| Integrated Safety System Bundling | Leverages respiratory protection heritage to attach thermal garments to gas detection contracts. |
Methodological Framework
Independent corroboration across primary interviews with LNG terminal safety officers, industrial gas procurement leads, and cryogenic materials R&D directors, combined with secondary validation through OSHA enforcement records, EU PPE Regulation 2016/425 conformity assessment databases, and ISO 20345 certification timelines, underwrites the qualitative findings. Bottom-up demand modeling from liquefaction capacity buildouts and replacement cycle economics triangulates against top-down market sizing from supplier revenue disclosures and national oil company tender documentation.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, material technology tier, end-user sophistication level, and regional regulatory enforcement intensity. CAGRs derive from multivariate regression incorporating LNG train commissioning schedules, OSHA 1910.132 inspection frequency trends, and research institution cryo-electron microscopy facility buildout rates. Hydrogen economy infrastructure deployment assumptions and helium price index volatility feed scenario-weighted forecast distributions.
The model assumes a particular technology adoption path for modular multilayer insulation systems; alternative pathways for solid-state thermal barrier materials would alter the outlook for liner replacement revenue streams. Forecasts reflect documented assumptions regarding certification timeline compression and regulatory harmonization pace. Practitioners should monitor liquid hydrogen handling protocol finalization and CE marking enforcement intensity for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Hand Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Combat Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplied Air Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Protective Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Security System Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market