
 Self-Contained Breathing Apparatus (SCBA) Cylinders Market | 2026-2036
Self-Contained Breathing Apparatus (SCBA) Cylinders Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Contained Breathing Apparatus (SCBA) Cylinders Market Insights
Multi-source procurement for high-pressure composite wraps is decoupling from legacy steel supply chains. Luxfer Gas Cylinders leverages its vertical manufacturing footprint to sustain cost advantages in aluminum liner production. Worthington Industries anchors North American distribution through its metals processing network, while Hexagon Composites specializes in Type IV all-composite designs for weight-sensitive applications.
Self-contained breathing apparatus cylinders are pressure vessels designed to store compressed breathing air at service pressures typically ranging from 4,500 to 5,500 psi, constructed with aluminum or composite overwraps to minimize weight for mobile emergency personnel. Their primary purpose is to provide respiratory protection in oxygen-deficient or toxic atmospheres during firefighting, industrial rescue, and hazardous materials response. Composite cylinders now command the fastest expansion trajectory as fiber-reinforced designs slash carried weight by up to seventy percent versus steel alternatives, while firefighting services remain the dominant end-user segment given mandatory turnout-gear replacement cycles and NFPA 1981 compliance deadlines. The sixty-minute capacity tier captures outsized margin attention due to its balance of operational duration and portability across structural fire attack scenarios.
The U.S. Department of Transportation and the National Fire Protection Association govern cylinder recertification intervals and material burst-test protocols, directly dictating replacement demand and manufacturing qualification barriers. The EU Pressure Equipment Directive and ISO 9809 standards harmonize cross-border certification requirements, enabling European manufacturers to export without duplicate testing regimes. Stakeholders must monitor evolving hydrogen-compatible composite manufacturing capabilities, as shared filament-winding infrastructure between SCBA and alternative-fuel cylinder production is reshaping capacity allocation decisions.
Market Dynamics
Fleet replacement cycles across firefighting services are compressing as NFPA 1981 compliance deadlines force municipal buyers to abandon legacy steel cylinders regardless of remaining service life. Composite overwrap technology has crossed the cost-performance threshold, making aluminum-lined Type III designs the default specification for new apparatus procurement.
Growth Catalysts
- NFPA 1981 Recertification Mandates:The U.S. National Fire Protection Association's five-year hydrostatic retest and fifteen-year retirement rules for composite cylinders create predictable replacement demand regardless of economic conditions.
- Carbon Fiber Filament Winding:Automated fiber placement systems are reducing production cycle times for pressure vessel overwraps, enabling manufacturers to scale output without proportional labor expansion.
- Municipal Budget Recovery:Federal infrastructure allocations through the U.S. Department of Homeland Security are restoring apparatus procurement timelines that stalled during prior fiscal contractions.
Market Restraints
- High-Grade Carbon Fiber Supply Concentration:Aerospace and automotive sectors dominate Toray Industries and Hexcel Corporation output, constraining filament availability for cylinder manufacturers during demand spikes.
- EU Pressure Equipment Directive Certification Burden:Module B design examination and Module D production quality assurance impose six-to-nine month approval timelines that freeze product launches.
- Steel Cylinder Residual Value:Existing aluminum-wound and all-steel inventories in secondary markets delay full fleet conversions where budget constraints favor partial replacement strategies.
Strategic Opportunities
- Industrial Confined-Space Rescue:Petrochemical and wastewater treatment facilities are adopting SCBA protocols beyond fire service specifications, opening specification channels outside municipal procurement.
- Hydrogen Storage Infrastructure Overlap:Shared filament-winding equipment between Type IV hydrogen cylinders and breathing apparatus vessels allows capacity pivoting toward whichever segment shows stronger near-term demand.
- ISO 9809 Harmonization:Cross-border testing equivalence is eliminating duplicate certification costs for European manufacturers exporting to Asia-Pacific markets.
Industry Challenges
- Composite Repair Technician Certification:The specialized skill set for carbon fiber damage assessment and liner inspection remains scarce relative to metal welding qualifications.
- Legacy Cylinder Disposal Compliance:DOT hazardous materials regulations govern decommissioned pressure vessel destruction, adding logistics complexity to replacement programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Contained Breathing Apparatus (SCBA) Cylinders Market |
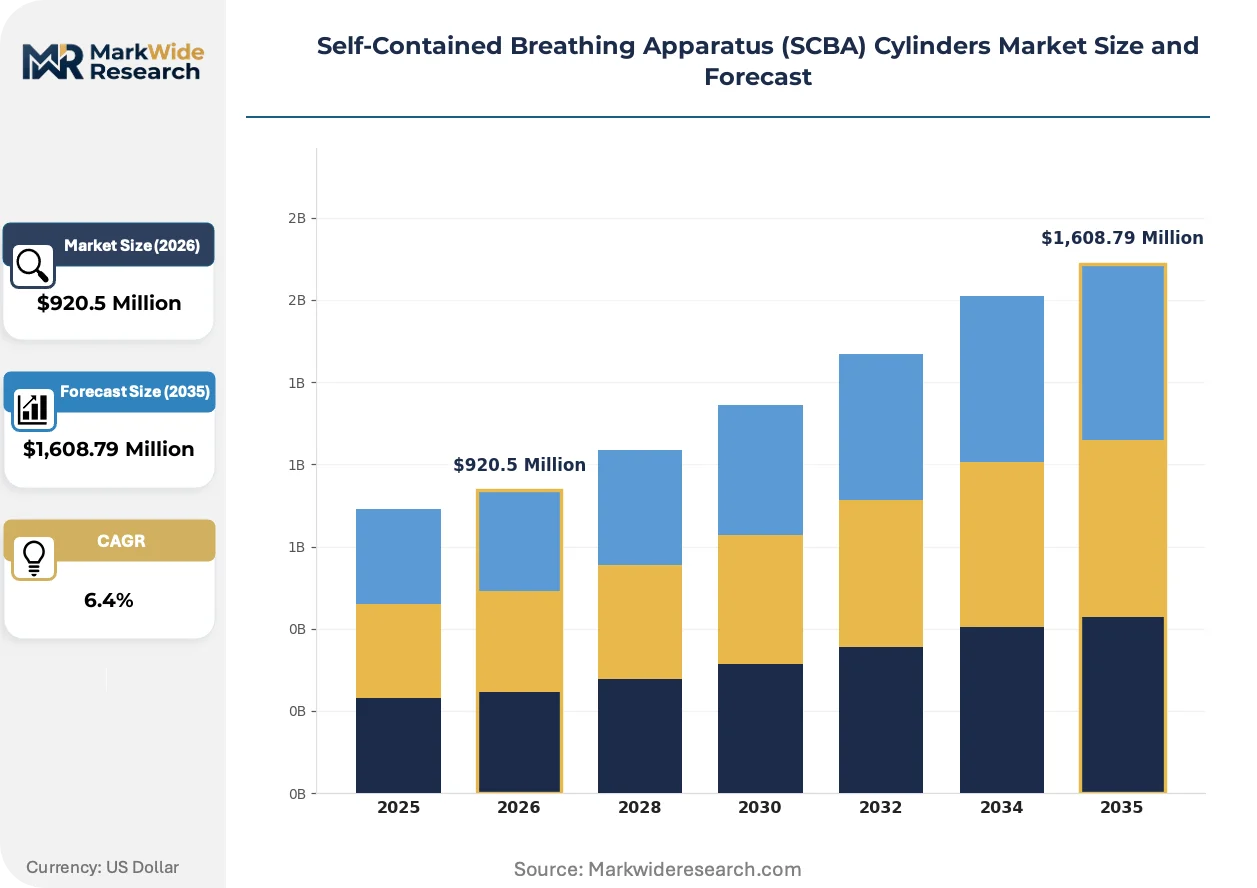
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,608.79 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Cylinders, Aluminum Cylinders, Composites, Fiber-Reinforced End User: Firefighting Services, Industrial Facilities, Military, Rescue Operations Capacity: 30 Minutes, 45 Minutes, 60 Minutes, 90 Minutes Delivery Mode: Direct Sale, Online Retail, Distribution, Rental Services |
| Companies Covered | Luxfer Gas Cylinders, Worthington Industries, Faber Industrie Spa, Hexagon Composites, MSA Safety, Dräger, 3M Scott Fire & Safety, Honeywell, Avon Protection, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Contained Breathing Apparatus (SCBA) Cylinders Market Trends and Innovations
Material science advances and regulatory harmonization are converging to reshape cylinder specifications and procurement patterns. Manufacturers are repositioning around weight reduction, service-life extension, and cross-platform manufacturing flexibility.
Type IV all-composite cylinder construction is electrifying the lightweight segment by eliminating metallic liners entirely. Wildland firefighting crews and technical rescue specialists are adopting these designs for extended pack-in operations. The technology is electrifying competitive positioning among filament-winding specialists who can achieve the void-free resin saturation required for oxygen service.
REACH chemical registration requirements in Europe are tightening scrutiny on epoxy resin formulations used in cylinder overwraps. Manufacturers face reformulation costs or supplier switches to maintain CE marking eligibility. Fire service distributors in Germany and France are prioritizing suppliers with pre-registered substance portfolios to avoid import delays.
Bulk purchasing consortia among mid-sized municipal fire departments are consolidating specification authority. Regional cooperative agreements are displacing individual department procurement, concentrating volume with fewer vendors. This pattern is most visible across the U.S. Northeast and Midwest, where interlocal contracts now govern apparatus and cylinder acquisitions.
Self-Contained Breathing Apparatus (SCBA) Cylinders Market Segmentation
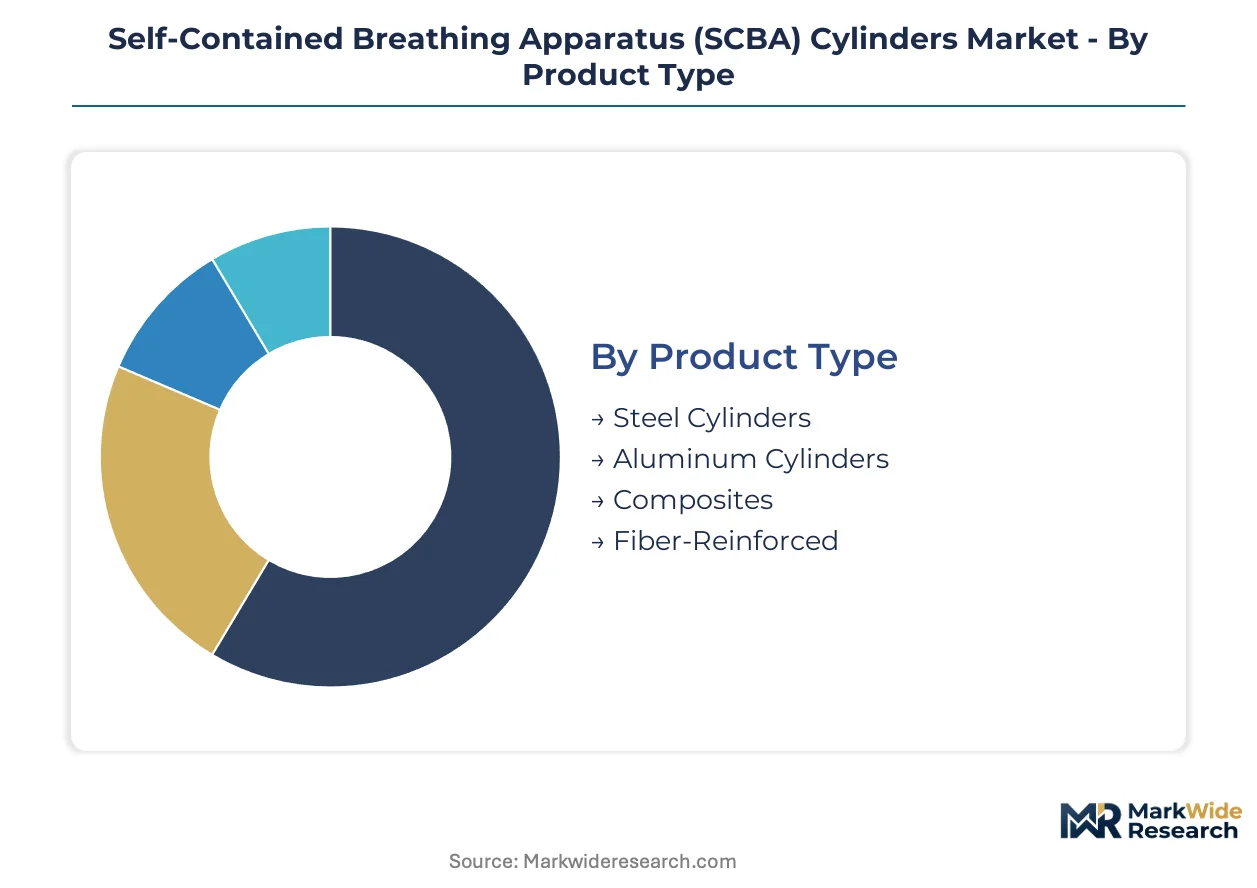
SCBA cylinder procurement patterns diverge sharply across material specifications, operational durations, and institutional buyer types. Manufacturers must align production capacity with distinct certification requirements and replacement cycles that vary by end-use environment.
Product Type:
Material selection hinges on weight tolerance versus budget constraints across different emergency response scenarios.
- Steel Cylinders:All-metal construction withstands extreme impact and abrasion in industrial settings. Budget-constrained municipal fire departments in rural counties retain these for secondary apparatus where weight penalties are acceptable.
- Aluminum Cylinders:Seamless aluminum liners provide corrosion resistance for maritime and chemical plant deployments. Coast Guard stations and port authority fire units specify these for salt-air environments.
- Composites:Hybrid aluminum-composite wraps dominate new apparatus procurement across NFPA-compliant fire services. Urban departments in Chicago and Los Angeles have standardized on Type III designs for structural attack teams.
- Fiber-Reinforced:All-composite Type IV construction eliminates metallic components entirely. Wildland hotshot crews and technical rescue specialists operating in remote terrain adopt these for extended pack-in operations where every pound determines operational range.
Composites lead volumes today; fiber-reinforced designs are gaining share fastest.
End User:
Buyer sophistication and procurement authority vary dramatically across institutional categories.
- Firefighting Services:Municipal departments operate under NFPA 1981 mandatory replacement cycles and federal grant funding timelines. Consolidated regional purchasing cooperatives in the U.S. Northeast now govern specification authority for dozens of departments simultaneously.
- Industrial Facilities:Petrochemical refineries and semiconductor cleanrooms maintain captive SCBA inventories for confined-space rescue protocols. OSHA 29 CFR 1910.146 compliance drives acquisition independent of municipal fire service standards.
- Military:Defense procurement emphasizes NATO standardization and battlefield durability over weight minimization. U.S. Navy shipboard damage control teams specify cylinders with enhanced salt-spray resistance.
- Rescue Operations:Technical rescue and urban search-and-teams prioritize interoperability with multiple breathing apparatus platforms. FEMA USAR task forces require cylinders compatible with both SCBA and supplied-air systems.
Firefighting services anchor current demand; industrial facilities are expanding procurement most rapidly.
Capacity:
Duration selection reflects operational tactics and egress distance calculations specific to each deployment scenario.
- 30 Minutes:Compact cylinders suit rapid intervention crews and confined-space entries with short egress paths. Industrial maintenance teams favor these for routine vessel inspections.
- 45 Minutes:Intermediate duration balances mobility with operational margin for residential structure fires. Suburban departments with mixed commercial-residential districts specify these as standard issue.
- 60 Minutes:Full-hour capacity dominates structural fire attack specifications where interior operations extend beyond initial knockdown. This tier commands premium positioning due to its versatility across ventilation-limited environments.
- 90 Minutes:Extended-duration cylinders support technical rescue and hazmat operations with prolonged on-air requirements. Nuclear facility response teams and tunnel rescue units require these for scenarios with no immediate egress.
Sixty-minute configurations dominate current procurement; ninety-minute specifications are climbing fastest in specialized rescue applications.
Delivery Mode:
Channel selection correlates with buyer scale, urgency requirements, and technical support needs.
- Direct Sale:Large municipal fleet replacements and federal defense contracts bypass intermediaries for volume pricing and custom specifications. Manufacturers assign dedicated account teams to major metropolitan fire departments.
- Online Retail:Small industrial buyers and volunteer fire companies access standardized cylinders through e-commerce platforms. Limited technical consultation accompanies these transactions.
- Distribution:Regional fire equipment distributors maintain inventory for emergency replacement and warranty service. These intermediaries handle hydrostatic retesting and recertification logistics.
- Rental Services:Temporary cylinder provision supports training academies, special event coverage, and disaster surge capacity. Turnkey rental packages include delivery, maintenance, and end-of-service retrieval.
Distribution channels capture the largest transaction volume today; rental services are expanding most quickly for non-fire-service applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between the U.S. DOT cylinder recertification regime and the EU Pressure Equipment Directive's Module B/D approval pathways creates compliance-cost arbitrage that favors North American production for export markets. Manufacturers exploit this gap by centralizing filament-winding capacity in jurisdictions with streamlined pressure-vessel certification timelines.
United States
Federal infrastructure allocations through the Department of Homeland Security are restoring municipal fire department procurement timelines. OSHA 29 CFR 1910.146 mandates for confined-space rescue equipment drive parallel industrial demand. Chicago and Los Angeles fire departments have standardized on Type III composite cylinders for structural attack teams.
Germany
REACH chemical registration requirements are tightening scrutiny on epoxy resin formulations used in cylinder overwraps. The EU Pressure Equipment Directive's Module D production quality assurance imposes six-to-nine month approval timelines. Fire equipment distributors in Bavaria prioritize suppliers with pre-registered substance portfolios to avoid import delays.
China
GB standards for pressure equipment are converging with ISO 9809 specifications to facilitate export qualification. MIIT industrial policy supports carbon fiber filament-winding capacity expansion for both SCBA and hydrogen storage applications. Yangtze River Delta manufacturing clusters are scaling automated fiber placement systems.
Japan
METI energy transition programs are repurposing composite cylinder production lines toward hydrogen infrastructure. JIS standards for breathing apparatus maintain stringent burst-test protocols that exceed baseline ISO requirements. Kansai region industrial gas suppliers are integrating SCBA distribution with medical oxygen cylinder logistics.
United Kingdom
Post-Brexit regulatory autonomy has preserved CE marking equivalence for pressure equipment while streamlining UKCA transition timelines. The Health and Safety Executive enforces confined-space rescue equipment standards aligned with former EU frameworks. London and Southeast England fire authorities participate in bulk purchasing consortia consolidating specification authority.
Self-Contained Breathing Apparatus (SCBA) Cylinders Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hydrogen storage adjacencies to leverage shared filament-winding infrastructure. The vendor base stratifies across integrated metals processors, composite specialists, and breathing apparatus system integrators. Archetypes include upstream material controllers, downstream specification influencers, and platform-agnostic cylinder fabricators. Capacity expansion and strategic partnerships dominate competitive moves as firms secure carbon fiber supply agreements and cross-license pressure-vessel designs.
Among integrated industrial gas and cylinder specialists, Luxfer Gas Cylinders and Worthington Industries occupy positions anchored in aluminum liner production and metals processing networks respectively. Hexagon Composites exemplifies the pure-composite archetype with specialization in Type IV all-composite designs. These three entities represent distinct strategic postures: backward integration into liner manufacturing, distribution channel control through metals processing scale, and weight-minimization focus for technical rescue applications.
| Leading Market Players |
|---|
| Luxfer Gas Cylinders |
| Worthington Industries |
| Faber Industrie Spa |
| Hexagon Composites |
| MSA Safety |
| Dräger |
| 3M Scott Fire & Safety |
| Honeywell |
| Avon Protection |
| Others |
Pricing and Supply Chain Analysis
Toray Industries carbon fiber price indices cascade through SCBA cylinder manufacturing into three distinct procurement tiers. Municipal fire departments absorb premium positioning for NFPA 1981-compliant Type III composites, while industrial buyers negotiate standard-grade aluminum-lined alternatives, and rural volunteer units trade weight penalties for economy steel specifications.
Pricing Analysis
Input-cost pass-through from aerospace-grade carbon fiber contracts governs composite cylinder pricing tiers. Pricing stratifies across premium NFPA-certified Type III designs, standard industrial-grade aluminum-composite wraps, and economy steel alternatives based on certification grade and volume scale. Cost compression in the premium tier is intensifying because Toray and Hexcel prioritize aviation and automotive offtake during demand spikes. Municipal procurement consortia exhibit lowest price sensitivity due to federal grant backing, while volunteer fire companies face acute budget constraints.
Supply Chain Analysis
Domestic-content mandates under the U.S. Buy American Act and EU Pressure Equipment Directive localization requirements are reshaping sourcing patterns for aluminum liner forging and filament-winding equipment. Manufacturing concentrates in the United States, Germany, and China, with raw material feeds drawing from Japanese carbon fiber precursors, Chinese epoxy resin formulations, and U.S. aluminum billet supplies. Single-source vulnerability runs through Toray's PAN-based fiber output for pressure vessel grades. Distribution runs through regional fire equipment distributors who manage hydrostatic retesting logistics and emergency replacement inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SCBA cylinder procurement has entered a late-cycle quality phase as fire departments prioritize Type III and Type IV specifications over legacy steel regardless of residual service life. This shift toward premium composite construction rewards manufacturers with certified fiber-winding capacity and penalizes pure metals processors.
For Market Incumbents: Anchor filament-winding capacity in jurisdictions with streamlined DOT or EU Pressure Equipment Directive certification timelines to defend against hydrogen storage competitors repurposing shared equipment. Secure long-term carbon fiber supply agreements with Toray or Hexcel before aerospace allocation peaks. Prioritize backward integration into aluminum liner forging to preserve margin structure against composite specialists.
For New Entrants and Emerging Players: Begin with industrial confined-space rescue specifications outside municipal fire service procurement channels, where OSHA 29 CFR 1910.146 compliance creates parallel demand without NFPA certification barriers. Target petrochemical facilities and wastewater treatment plants in the U.S. Gulf Coast and Rotterdam port complexes. Pursue direct sales relationships with safety managers rather than distributor intermediaries to capture specification influence.
For Investors and Strategic Acquirers: Asymmetric upside sits with composite cylinder fabricators possessing dual-use hydrogen storage capabilities and pre-registered REACH substance portfolios. Long-term viability hinges on five-to-ten year positioning around alternative-fuel cylinder adjacencies rather than pure breathing apparatus exposure. Monitor hydrogen infrastructure deployment rates as the inflection signal for capacity allocation decisions between SCBA and energy storage applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Supply Agreement | Secures Toray or Hexcel allocation ahead of aerospace and automotive demand spikes. |
| Dual-Use Manufacturing Capacity | Enables pivoting between Type IV SCBA and hydrogen storage cylinders based on demand signals. |
| REACH Pre-Registration Investment | Maintains CE marking eligibility for epoxy resin formulations under tightening ECHA scrutiny. |
| Regional Purchasing Consortium Partnership | Captures consolidated volume from U.S. Northeast and Midwest interlocal fire department contracts. |
| Composite Repair Technician Certification Program | Addresses scarce skilled labor for carbon fiber damage assessment and liner inspection protocols. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews incorporated cylinder manufacturing executives, municipal fire department procurement officers, industrial safety managers, and carbon fiber supply specialists. Secondary sources included DOT hazardous materials filings, EU Pressure Equipment Directive Module B/D approval records, NFPA standards documentation, and customs trade data for pressure vessel imports. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Rate-of-change decomposition anchored the analytical framework across the analysis window. Segmentation dimensions modeled included material specification, operational duration tier, end-user institutional category, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to replacement cycle projections and fleet conversion timelines. Industry-specific forecast inputs incorporated NFPA 1981 retirement schedules, federal homeland security grant allocation patterns, and hydrogen infrastructure deployment trajectories.
Several conditions sit outside the modeled scope, including sudden carbon fiber supply disruptions from aerospace demand spikes, unanticipated regulatory delays in EU Pressure Equipment Directive harmonization, and accelerated steel cylinder retirement mandates beyond current NFPA timelines. Forecasts reflect documented assumptions regarding municipal budget recovery trajectories and filament-winding automation adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Respirator Filter Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Prefilled Safety Device Market
Safety Equipment and Personal Protective Equipment (PPE)
Arc Flash Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
US Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Panic Exit Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Hazard and Safety Indicator Control Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Cuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market