
 Smart Hazard and Safety Indicator Control Modules Market | 2026-2036
Smart Hazard and Safety Indicator Control Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Hazard and Safety Indicator Control Modules Market Insights
Asset-light leasing arrangements for safety system fleets is narrowing the capital barrier for mid-tier industrial operators. Continental leverages captive sensor manufacturing to sustain margin control across European automotive contracts. FORVIA HELLA anchors its position through specialized LED indicator architectures for premium commercial vehicles. Robert Bosch competes by extending its IoT-enabled module portfolio into chemical plant alerting applications.
Smart hazard and safety indicator control modules integrate photoelectric sensors, piezoelectric actuators, and microprocessor-driven signal processing units to detect anomalous conditions and broadcast alerts through visual, audible, or wireless channels. These systems serve critical industrial and commercial environments where rapid hazard communication prevents personnel injury and equipment damage. LED indicators dominate module type demand due to energy efficiency and extended operational lifespan in harsh environments. IoT-enabled technology segments are expanding fastest as facilities pursue centralized monitoring dashboards. Manufacturing safety applications command the largest application share while mining operations represent an emerging margin pool for ruggedized wireless sensor configurations.
NHTSA and OSHA frameworks in the United States mandate minimum visibility and response standards for hazard signaling in commercial and industrial settings. The EU Machinery Directive and CE marking requirements shape product certification pathways for European market access. China's GB standards and MIIT technical specifications govern electromagnetic compatibility and wireless transmission protocols for imported safety electronics. Stakeholders must monitor evolving interoperability standards between legacy hardwired systems and emerging Bluetooth Low Energy networks to preserve upgrade pathways without full infrastructure replacement.
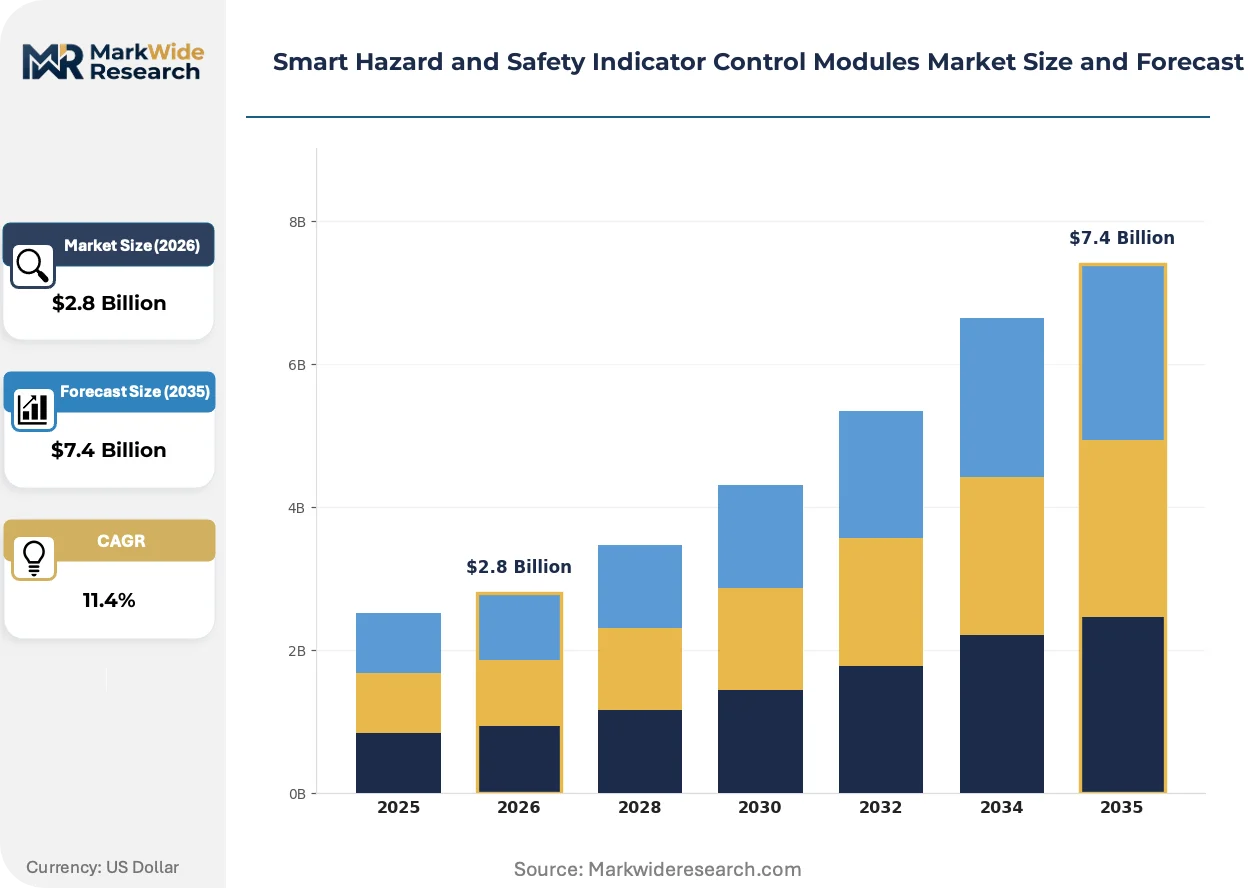
Market Dynamics
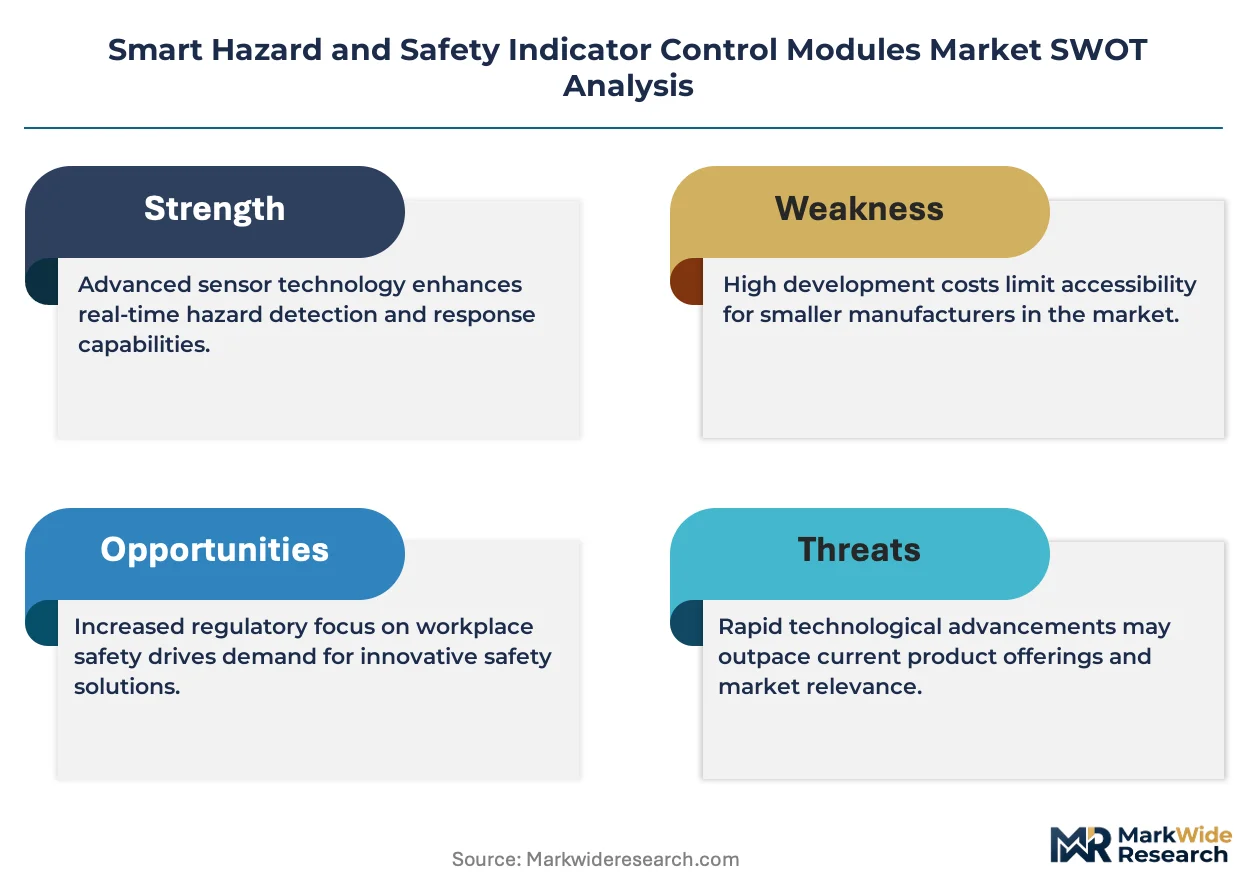
IoT-enabled module architectures are compressing installation timelines and enabling centralized dashboard integration, forcing legacy hardwired system manufacturers to accelerate wireless protocol development or lose specification battles in automotive and chemical plant tenders.
Growth Catalysts
- NHTSA visibility mandates:Federal Motor Vehicle Safety Standards now require enhanced hazard signaling for commercial vehicle platforms, embedding advanced indicator modules into OEM production schedules.
- LED photoelectric convergence:Solid-state indicator technology delivers energy efficiency and operational lifespan advantages that halve replacement cycles in heavy industrial environments.
- German automotive OEM demand:Commercial vehicle manufacturers in Stuttgart and Wolfsburg specify integrated safety indicator systems as standard equipment, creating specification pull through European supply chains.
Market Restraints
- Rare earth magnet supply concentration:Piezoelectric actuator manufacturing depends on neodymium supply chains concentrated in Chinese processing facilities, exposing module producers to input volatility.
- CE marking certification timelines:EU Machinery Directive compliance testing extends product launch windows by 8-14 months for non-European manufacturers seeking market access.
- Bluetooth Low Energy substitution threat:Emerging wireless mesh protocols risk obsoleting proprietary RF indicator modules before full depreciation cycles complete.
Strategic Opportunities
- Underpenetrated mining operations:Ruggedized wireless sensor configurations for underground hazard alerting remain underspecified relative to surface manufacturing applications.
- OSHA chemical plant mandates:Process Safety Management rule updates create specification windows for IoT-enabled gas leak indicator modules with centralized alerting capabilities.
- Leasing model channel innovation:Asset-light fleet arrangements for safety system modules narrow capital barriers for mid-tier industrial operators previously excluded from premium indicator procurement.
Industry Challenges
- Embedded systems firmware talent scarcity:Microprocessor-driven signal processing development requires specialized skill sets concentrated in automotive electronics clusters, constraining module producer hiring pipelines.
- Legacy hardwired integration complexity:Facilities with 1990s-era alerting infrastructure face full infrastructure replacement costs when upgrading to wireless-enabled indicator networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Hazard and Safety Indicator Control Modules Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Module Type: LED Indicators, Audible Alarms, Wireless Sensors, Vibration Sensors, Optical Sensors Technology: IoT Enabled, Bluetooth Low Energy, Zigbee, NFC, RFID, Ultrasonic Application: Manufacturing Safety, Construction Site Monitoring, Chemical Plant Alerting, Mining Operations, Laboratory Security End User: Oil & Gas Facilities, Aviation Maintenance, Public Safety Agencies, Utilities Infrastructure, Maritime Operations |
| Companies Covered | Tokai Rika, Continental, FORVIA HELLA, Valeo, Aptiv, Alps Alpine, Methode Electronics, Robert Bosch, DENSO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Hazard and Safety Indicator Control Modules Market Trends and Innovations
Photoelectric sensor miniaturization and edge-computing integration are redefining module form factors, compressing the traditional separation between detection hardware and signal processing intelligence into single-unit architectures.
Silicon photomultiplier arrays are collapsing the cost-performance tradeoff in low-light hazard detection, enabling automotive Tier-1 suppliers to specify solid-state alternatives to legacy photomultiplier tubes in commercial vehicle indicator systems. German OEMs have accelerated qualification timelines for these components, accepting reduced sensitivity margins in exchange for vibration resistance and temperature stability. The structural consequence is collapsing differentiation between premium and standard indicator module tiers.
OSHA's updated Hazard Communication Standard alignment with GHS Revision 7 is mandating multi-modal alert protocols—visual, audible, and wireless—for chemical manufacturing facilities above threshold quantities. Process operators in Texas and Louisiana Gulf Coast clusters are retrofitting existing indicator networks to comply with synchronized alert timing requirements. Mining operations in Appalachia are adopting similar specifications ahead of formal MSHA rulemaking, creating regulatory anticipation demand.
Buyer procurement committees are consolidating safety system specifications under single-source framework agreements, displacing the historical pattern of discrete indicator module purchasing. Automotive fleet operators in Michigan and Ohio now require five-year total cost of ownership guarantees that bundle hardware, installation, and wireless connectivity fees. Chemical plant engineering-procurement-construction firms in the US Gulf Coast are responding by pre-qualifying module suppliers against interoperability standards before tender participation.
Smart Hazard and Safety Indicator Control Modules Market Segmentation
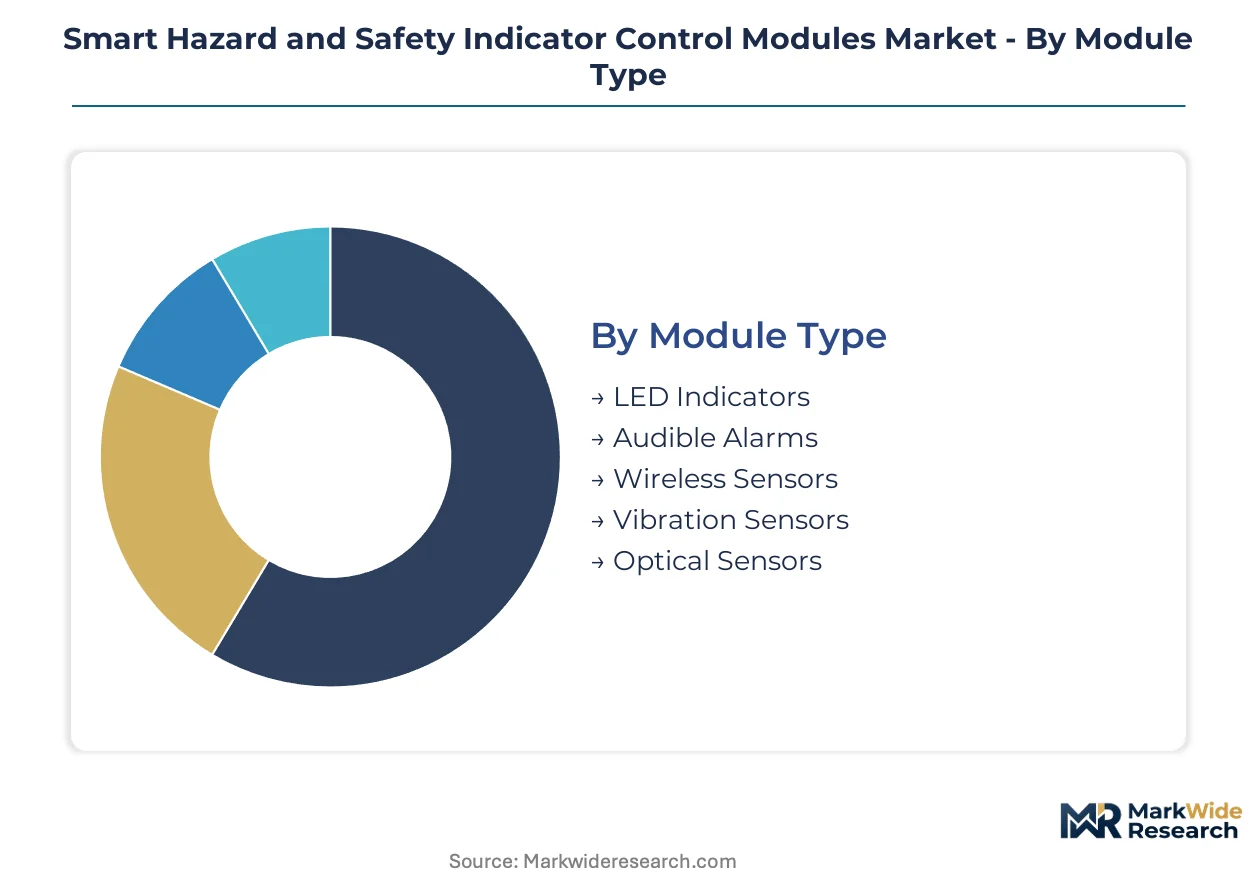
Smart hazard and safety indicator control modules serve heterogeneous operational environments where specification requirements diverge sharply by hazard type, connectivity protocol, and regulatory jurisdiction. Segmentation reveals which module configurations command premium positioning versus commodity economics, guiding procurement strategy and supplier selection across automotive, industrial, and infrastructure verticals.
Module Type:
Replacement cycle velocity separates this category: LED indicators and optical sensors operate on 5-7 year depreciation schedules in heavy industrial settings, while wireless sensors and audible alarms face 2-3 year technology obsolescence pressures from protocol evolution.
- LED Indicators:Solid-state photoelectric assemblies with silicon photomultiplier arrays deliver vibration resistance and temperature stability for commercial vehicle platforms. German automotive OEMs in Stuttgart specify these as standard equipment, embedding modules directly into chassis wiring harnesses during initial assembly.
- Wireless Sensors:Battery-powered RF transceivers with edge-computing capabilities enable centralized dashboard integration for distributed hazard monitoring. Chemical plant operators in Texas and Louisiana Gulf Coast clusters are retrofitting legacy hardwired networks with these units to comply with synchronized alert timing mandates.
- Audible Alarms:Piezoelectric actuator-driven sound generators with multi-frequency pattern recognition for OSHA-mandated multi-modal alert protocols.
- Vibration Sensors:MEMS accelerometer-based modules detecting mechanical anomaly signatures in rotating equipment for predictive maintenance integration.
- Optical Sensors:Photoelectric detection units with miniaturized form factors collapsing hardware-signal processing separation into single-unit architectures.
LED Indicators anchors the volume base while Wireless Sensors gains share at the steepest rate.
Technology:
Deployment cost tiers structure supplier competition: IoT-enabled and Bluetooth Low Energy modules carry 40-60% hardware premiums over Zigbee and RFID alternatives, but compress total installation expenditure through reduced wiring infrastructure.
- IoT Enabled:Cloud-connected modules with centralized monitoring dashboards and predictive analytics capabilities for enterprise-scale facility management. Manufacturing safety applications in Michigan and Ohio automotive clusters drive specification pull through five-year total cost of ownership procurement frameworks.
- Bluetooth Low Energy:Mesh networking protocols with sub-10 millisecond latency for synchronized alert propagation across chemical plant process units. MSHA rulemaking anticipation in Appalachia mining operations is accelerating adoption ahead of formal mandate publication.
- Zigbee:Proprietary RF mesh standards with established interoperability certifications for legacy industrial automation integration.
- NFC:Near-field commissioning interfaces for rapid module configuration and maintenance technician authentication.
- RFID:Passive identification tags for asset tracking and location-aware hazard alerting in warehouse environments.
- Ultrasonic:High-frequency detection modules for gas leak localization and personnel proximity sensing in confined spaces.
IoT Enabled commands the revenue concentration while Bluetooth Low Energy climbs the fastest as wireless mesh protocols displace proprietary RF alternatives.
Application:
Margin profiles diverge by operational harshness: surface manufacturing and laboratory applications permit standard-grade enclosures, while underground mining and chemical processing demand ruggedized configurations with 3-4x unit cost multiples.
- Manufacturing Safety:Conveyor system emergency stop integration and robotic workcell perimeter monitoring for automotive and heavy industrial facilities. OSHA machinery guarding standards mandate minimum response visibility specifications that embed advanced indicator modules into production line designs.
- Mining Operations:Ruggedized wireless sensor configurations for underground hazard alerting with explosion-proof enclosures and extended battery autonomy. Surface applications remain overspecified relative to this underpenetrated underground segment where wireless mesh networks overcome cabling infrastructure constraints.
- Construction Site Monitoring:Temporary deployment configurations with rapid-install mounting systems and weather-resistant housings for mobile equipment fleets.
- Chemical Plant Alerting:Gas leak detection modules with multi-modal alert protocols synchronized across process safety management perimeters.
- Laboratory Security:Biosafety cabinet and fume hood status indication with HEPA filter pressure differential monitoring integration.
Manufacturing Safety carries the installed base volume while Mining Operations expands most quickly as wireless ruggedization costs decline.
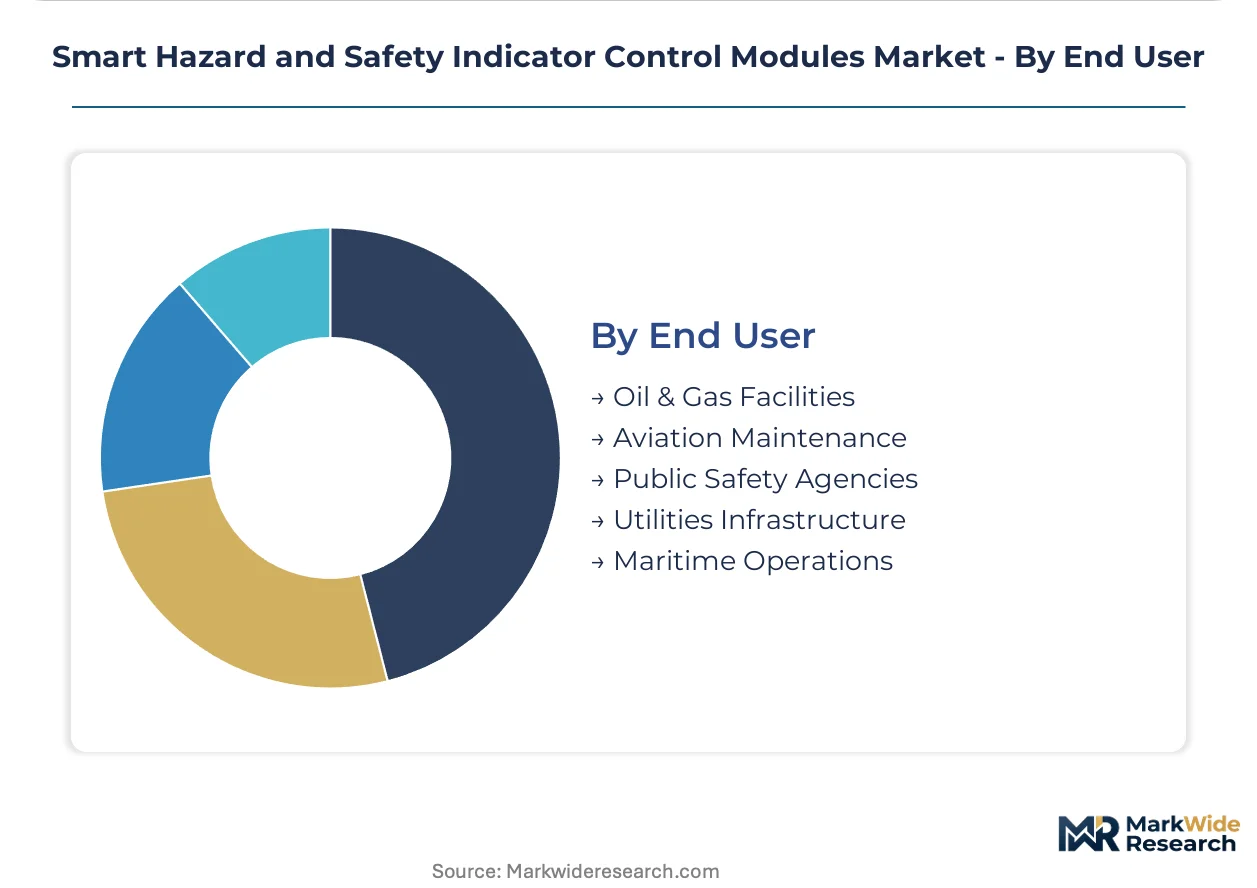
End User:
Procurement authority concentration shapes channel strategy: Oil & Gas Facilities and Utilities Infrastructure consolidate safety system specifications under single-source framework agreements, while Aviation Maintenance and Public Safety Agencies retain discrete module purchasing with technical specification committees.
- Oil & Gas Facilities:Offshore platform and refinery process unit integration requiring SIL-rated safety instrumented system compatibility. US Gulf Coast engineering-procurement-construction firms pre-qualify module suppliers against interoperability standards before tender participation, consolidating vendor selection under multi-year framework agreements.
- Public Safety Agencies:Emergency vehicle lightbar and siren control modules with programmable pattern sequencing for municipal police and fire departments. State-level procurement consortiums in Ohio and Michigan aggregate demand through cooperative purchasing agreements that narrow supplier pools to pre-certified vendors.
- Aviation Maintenance:Hangar and runway ground support equipment hazard signaling with FAA obstruction lighting compliance requirements.
- Utilities Infrastructure:Substations and transmission corridor perimeter monitoring with FERC reliability standard alignment for critical infrastructure protection.
- Maritime Operations:Vessel engine room and cargo hold alerting with SOLAS convention navigation light control integration.
Oil & Gas Facilities dominates contract value concentration while Public Safety Agencies diversifies procurement most rapidly through municipal consortium aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in safety indicator modules tilt toward net-import positions in industrializing economies while established manufacturing bases sustain trade surpluses through component specialization. Module trade concentrates in corridors linking German automotive electronics clusters to assembly plants in North America and Asia. Currency volatility and rare earth magnet supply constraints are reshaping regional sourcing strategies.
United States
NHTSA Federal Motor Vehicle Safety Standards and OSHA Process Safety Management mandates embed advanced indicator modules into commercial vehicle and chemical plant specifications. Michigan and Ohio automotive clusters specify five-year total cost of ownership procurement frameworks that consolidate vendor selection. Gulf Coast petrochemical facilities in Texas and Louisiana retrofit legacy hardwired networks with IoT-enabled gas leak alerting systems.
Germany
Commercial vehicle OEMs in Stuttgart and Wolfsburg specify integrated safety indicator systems as standard equipment, creating specification pull through European supply chains. EU Machinery Directive and CE marking requirements shape product certification pathways with 8-14 month compliance timelines for non-European entrants. Bavarian and Baden-Württemberg automotive electronics corridors concentrate silicon photomultiplier qualification programs for solid-state indicator architectures.
China
GB standards and MIIT technical specifications govern electromagnetic compatibility and wireless transmission protocols for imported safety electronics. Domestic module producers leverage captive rare earth processing for piezoelectric actuator manufacturing. Yangtze River Delta industrial automation clusters are adopting Bluetooth Low Energy mesh protocols ahead of formal standardization.
Japan
METI industrial safety guidelines and JIS standards shape module specifications for precision manufacturing and semiconductor fabrication facilities. Kanto and Kansai electronics corridors concentrate MEMS accelerometer development for vibration sensing applications. Automotive Tier-1 suppliers in Nagoya-Chubu region qualify miniaturized photoelectric sensors for commercial vehicle integration.
India
BIS certification requirements and PLI scheme incentives for electronics manufacturing are attracting module assembly investments. Maharashtra and Gujarat industrial corridors deploy wireless hazard alerting systems in automotive and textile manufacturing facilities. State-level safety inspectorates in Tamil Nadu and Karnataka are aligning facility audit protocols with OSHA-aligned multi-modal alert standards.
Smart Hazard and Safety Indicator Control Modules Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in photoelectric sensor and piezoelectric actuator fabrication. The vendor base arranges into three concentration tiers: multinational automotive electronics suppliers with captive sensor manufacturing, specialized indicator module producers with regional certification expertise, and emerging wireless sensor entrants with edge-computing architectures. Consolidation pressure concentrates in the mid-tier as procurement committees consolidate specifications under single-source framework agreements. Dominant competitive moves include backward integration into silicon photomultiplier arrays and strategic partnerships for Bluetooth Low Energy protocol certification.
Among German-origin automotive electronics specialists, Continental and FORVIA HELLA exemplify platform-tier positioning through integrated wiring harness and LED indicator architectures. Robert Bosch occupies a position spanning both automotive and industrial safety applications with IoT-enabled module portfolios. These three entities represent the archetype of multinational suppliers leveraging scale and certification breadth to capture specification mandates across NHTSA, OSHA, and EU Machinery Directive jurisdictions.
| Leading Market Players |
|---|
| Tokai Rika |
| Continental |
| FORVIA HELLA |
| Valeo |
| Aptiv |
| Alps Alpine |
| Methode Electronics |
| Robert Bosch |
| DENSO |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta-to-Hamburg freight corridor compresses logistics premiums for silicon photomultiplier arrays and piezoelectric actuators, concentrating margin pressure on module producers who lack captive sensor fabrication or long-term rare earth offtake agreements.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on CE marking certification grade and volume scale commitments. Price differentiation stems from SIL-rated safety instrumented system compatibility and German automotive OEM specification adherence. Cost compression in the standard tier intensifies because Chinese module producers leverage captive neodymium processing. Tier 2 chemical plant operators exhibit highest price sensitivity, while oil and gas supermajors accept premium positioning for explosion-proof configurations.
Supply Chain Analysis
Foxconn and Jabil EMS facilities in Shenzhen and Penang hold concentrated contract-manufacturing capacity for microprocessor-driven signal processing units. Component sourcing draws from Taiwan for MEMS accelerometers, Japan for silicon photomultiplier dies, and China for rare earth magnet refining. Single-source vulnerability in neodymium supply chains exposes module producers to export restriction shocks. Distribution runs through automotive Tier 1 supplier networks and industrial automation distributors with regional certification expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth Low Energy mesh protocol standardization and OSHA multi-modal alert mandate expansion are compressing specification windows, creating high-growth disruption for incumbents who accelerate wireless certification and entrants who bypass legacy hardwired integration complexity.
For Market Incumbents: Entrench specification control by accelerating backward integration into silicon photomultiplier array fabrication and securing exclusive Bluetooth Low Energy protocol certification partnerships with German automotive OEMs. The substitution threat from emerging wireless sensor entrants with edge-computing architectures demands defensive consolidation of five-year total cost of ownership procurement frameworks with Michigan and Ohio automotive clusters.
For New Entrants and Emerging Players: Underground mining operations in Appalachia and surface manufacturing facilities in India's Maharashtra corridor represent the most penetrable entry points where wireless ruggedization costs are declining and regulatory anticipation demand precedes formal mandate publication. A leasing-model channel innovation targeting mid-tier industrial operators previously excluded from premium indicator procurement offers the clearest go-to-market angle.
For Investors and Strategic Acquirers: Specialist indicator module producers with regional CE marking expertise and established MSHA pre-qualification relationships present the most attractive acquisition archetype for platform integrators seeking certification breadth expansion. Long-term viability hinges on 5-10 year wireless protocol standardization trajectories. The signal to monitor is NHTSA rulemaking momentum on commercial vehicle hazard signaling visibility standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Photomultiplier Arrays | Continental and Robert Bosch secure margin control against Chinese rare earth volatility. |
| Bluetooth Low Energy Protocol Certification | FORVIA HELLA anchors German automotive OEM specification pull through European supply chains. |
| Leasing Model Channel Innovation | Asset-light fleet arrangements narrow capital barriers for mid-tier chemical plant operators. |
| Ruggedized Wireless Sensor Development | Underground mining configurations in Appalachia overcome cabling infrastructure constraints. |
| Five-Year Total Cost of Ownership Guarantees | Michigan automotive clusters consolidate vendor selection under single-source framework agreements. |
Research Methodology
A spread of perspectives from automotive Tier 1 procurement directors, chemical plant engineering managers, mining safety officers, and industrial automation distributors converged on the working assumptions. Primary fieldwork combined with secondary validation against NHTSA Federal Motor Vehicle Safety Standards filings, EU Machinery Directive compliance databases, OSHA Process Safety Management enforcement records, and vehicle production registration data. Bottom-up module shipment analysis and top-down industrial safety equipment expenditure triangulation anchored volume estimates.
Demand-supply balance modeling across the analysis window incorporated module type segmentation by replacement cycle velocity, technology tier by installation cost premium, application harshness by ruggedization requirement, and end-user procurement authority concentration. CAGRs derived from segment-level growth rate reconciliation with macro industrial automation capex indicators. Forecast inputs included German automotive OEM specification timelines and MSHA rulemaking anticipation effects in mining operations.
Stress conditions across rare earth magnet supply disruption, Bluetooth protocol substitution velocity, and CE marking timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on wireless adoption curves and regulatory mandate implementation schedules. Quarterly review of NHTSA rulemaking dockets, OSHA enforcement priority shifts, and German KBA type-approval timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Radar Speed Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplied Air Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Combat Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Tube and Dressing Securement Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Armor Accessories Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Arc Flash Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Booster Seat Type Child Safety Seats Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market