
 Global Radiation Protection Apron Market | 2026-2036
Global Radiation Protection Apron Market Size, Share, and Industry Trends Forecast 2026-2036
Global Radiation Protection Apron Market Foresight
Lead-free composite certification is redrawing competitive boundaries in the radiation protection apron market. Burlington Medical leverages proprietary tungsten-vinyl formulations to sustain premium positioning across North American hospital networks. Infab Corporation anchors its market presence through deep manufacturing scale in standard lead-core vest aprons. Amray Radiation Protection differentiates via specialized two-piece designs for interventional suites.
A radiation protection apron is a wearable shielding garment constructed from lead sheet, lead-free composite, or heavy metal alternatives such as bismuth, tin, or tungsten, designed to attenuate scatter radiation during fluoroscopic, radiographic, or nuclear medicine procedures to personnel. The garment typically achieves 0.25 mm to 0.5 mm lead-equivalence protection across frontal, wraparound, or skirt-vest configurations depending on procedural exposure vectors. Apron material segmentation shows lead-free composites capturing accelerated preference as facilities confront disposal regulations and ergonomic injury claims from orthopedics and radiologic technologist user categories. Product form dynamics favor wraparound and two-piece apron architectures in interventional radiology and cardiology application areas where lateral scatter exposure is pronounced and mobility requirements are stringent.
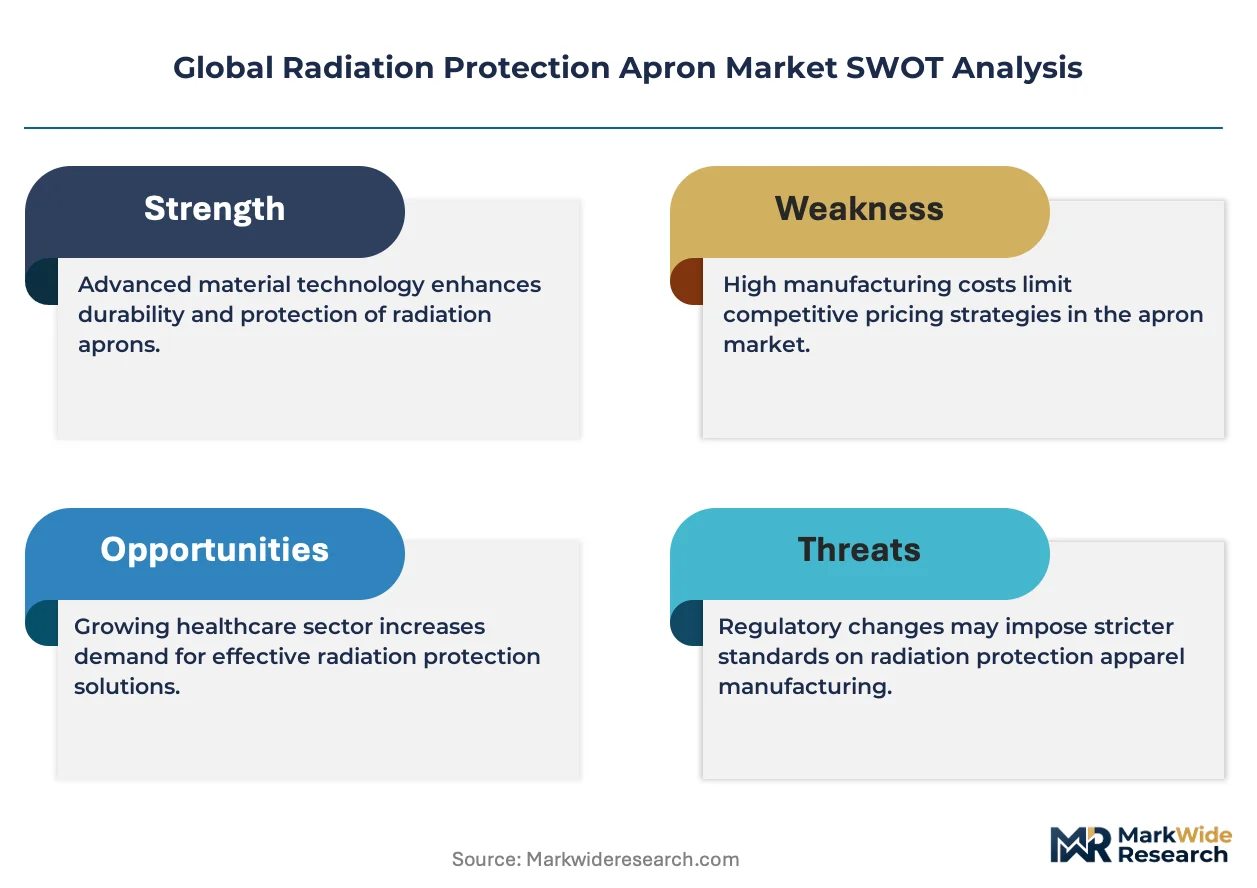
The FDA enforces 21 CFR performance standards for diagnostic x-ray systems including personnel shielding, while the EU MDR requires renewed technical documentation and clinical evaluation for protective device reclassification by notified bodies. Germany's KBA and France's ANSM coordinate national interpretations of CE marking requirements that directly determine market access timelines for apron manufacturers. Stakeholders must monitor evolving lead-content thresholds in REACH annex restrictions and anticipate procurement specification shifts as health systems prioritize lifecycle weight reduction and recycling compliance.
Market Dynamics
Material substitution timelines are compressing as tertiary care networks confront EU MDR recertification deadlines and FDA performance standard updates simultaneously, forcing apron manufacturers to accelerate lead-free composite validation while maintaining legacy lead-core supply continuity.
Growth Catalysts
- EU MDR recertification:The EU Medical Device Regulation's 2024-2026 technical documentation deadlines are compelling European hospital systems to replace aging aprons with certified lead-free alternatives ahead of compliance cutoffs.
- Interventional cardiology expansion:Tertiary cardiac catheterization labs in the United States, Germany, and Japan are standardizing two-piece apron architectures to address lateral scatter exposure during prolonged fluoroscopic procedures.
- Ergonomic injury litigation:Orthopedic and radiologic technologist compensation claims related to repetitive strain from heavy lead aprons are driving procurement specification shifts toward tungsten-vinyl composite formulations.
Market Restraints
- Tungsten supply concentration:Over 80% of tungsten ore processing occurs in China, exposing lead-free apron manufacturers to export quota volatility and geopolitical supply disruption risks.
- REACH annex restrictions:Evolving lead-content thresholds in EU chemical registration requirements are creating compliance friction for manufacturers maintaining dual lead-core and lead-free product lines.
- Bismuth-tin composite limitations:Alternative heavy metal formulations exhibit attenuation performance gaps at higher kVp ranges, constraining adoption in interventional radiology suites requiring 0.5 mm lead-equivalence protection.
Strategic Opportunities
- Indian tertiary care expansion:India's hospital accreditation standards under the National Accreditation Board for Hospitals are mandating radiation protection protocols in newly constructed cardiac centers, opening procurement channels for certified apron suppliers.
- Direct-to-facility distribution:Bypassing traditional medical device distributors through hospital group purchasing organization contracts is compressing margin leakage and accelerating replacement cycle capture.
- Recycling compliance premiums:REACH and EPA hazardous waste regulations are enabling certified recyclers to capture end-of-life apron disposal contracts as a recurring revenue attachment to initial equipment sales.
Industry Challenges
- Notified body capacity constraints:EU MDR recertification backlogs at German and French notified bodies are extending lead-free apron approval timelines from 12 to 24 months, freezing product launches.
- Composite manufacturing scale-up:Tungsten-vinyl formulation consistency at production volumes exceeding 10,000 units annually requires capital-intensive extrusion equipment that mid-tier suppliers cannot finance.
- Legacy inventory stranding:Hospital systems holding 5-7 year lead-core apron depreciation schedules are resisting premature replacement despite ergonomic and disposal regulation pressures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Radiation Protection Apron Market |
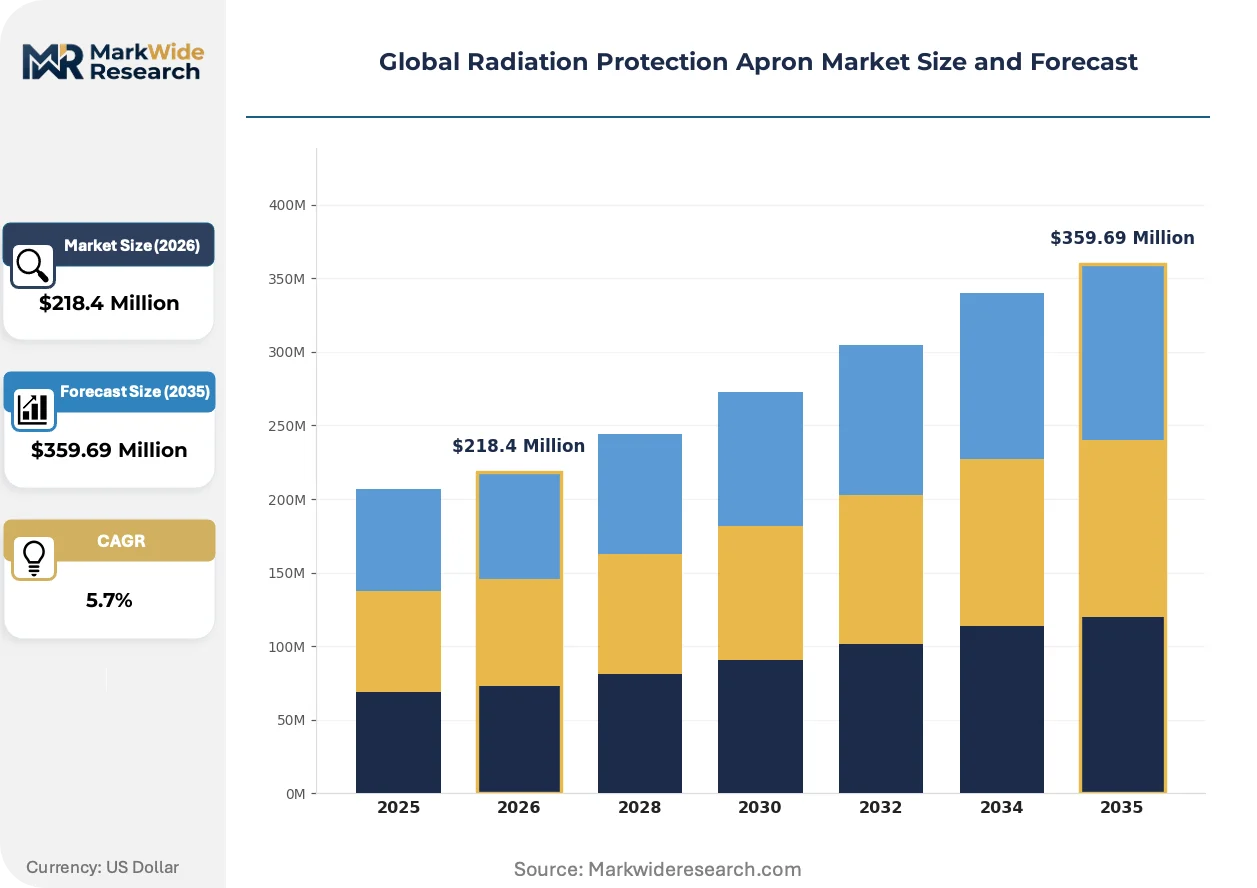
| Market Size in 2026 | $218.4 Million |
| Market Size in 2035 | $359.69 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Apron Material: Lead, Lead-Free Composite, Bismuth, Tin, Tungsten Application Area: Interventional Radiology, Nuclear Medicine, Cardiology, Dental Radiography, Orthopedics User Type: Radiologists, Radiologic Technologists, Surgeons, Dentists, Medical Physicists Product Form: Wraparound Aprons, Vest Aprons, Skirt Aprons, Coat Aprons, Two-Piece Aprons |
| Companies Covered | AliMed, Amray Radiation Protection, Barrier Technologies, Burlington Medical, BLOXR Solutions, Infab Corporation, Shielding International, Rampart International Corporation, Wolf X-Ray Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Radiation Protection Apron Market Shifts & Advancements
Active material experimentation is fragmenting established supply relationships as compounders and medical textile converters compete to certify proprietary heavy metal-polymer matrices before MDR deadlines solidify procurement preferences.
Lead-free composite formulation is fragmenting the apron material landscape. Tungsten-vinyl and bismuth-tin-epoxy compounds are capturing procurement preference in German and Japanese interventional suites where disposal cost accounting now includes hazardous waste fees. The technology is fragmenting vendor consolidation patterns by enabling compounders without historical medical device exposure to enter through materials certification partnerships.
REACH annex XVII restrictions on lead content in consumer and professional goods are forcing reformulation investments across EU-manufactured protective equipment categories. Industrial consequence includes accelerated R&D allocation toward tungsten and rare-earth alternatives as bismuth supply faces concurrent demand from solder and pharmaceutical applications. Interventional radiology departments in France and Germany are responding by consolidating procurement specifications around pre-certified lead-free suppliers to minimize compliance verification burden.
Hospital group purchasing organizations are consolidating radiation protection apron sourcing into multi-year enterprise contracts with standardized material specifications. The traditional distributor-mediated model is contracting as United States health systems like Kaiser Permanente and Mayo Clinic direct-negotiate with manufacturers for system-wide replacement programs. This concentration is most visible in California and Minnesota where integrated delivery networks control sufficient procedure volume to justify dedicated supply agreements.
Global Radiation Protection Apron Market Segmentation
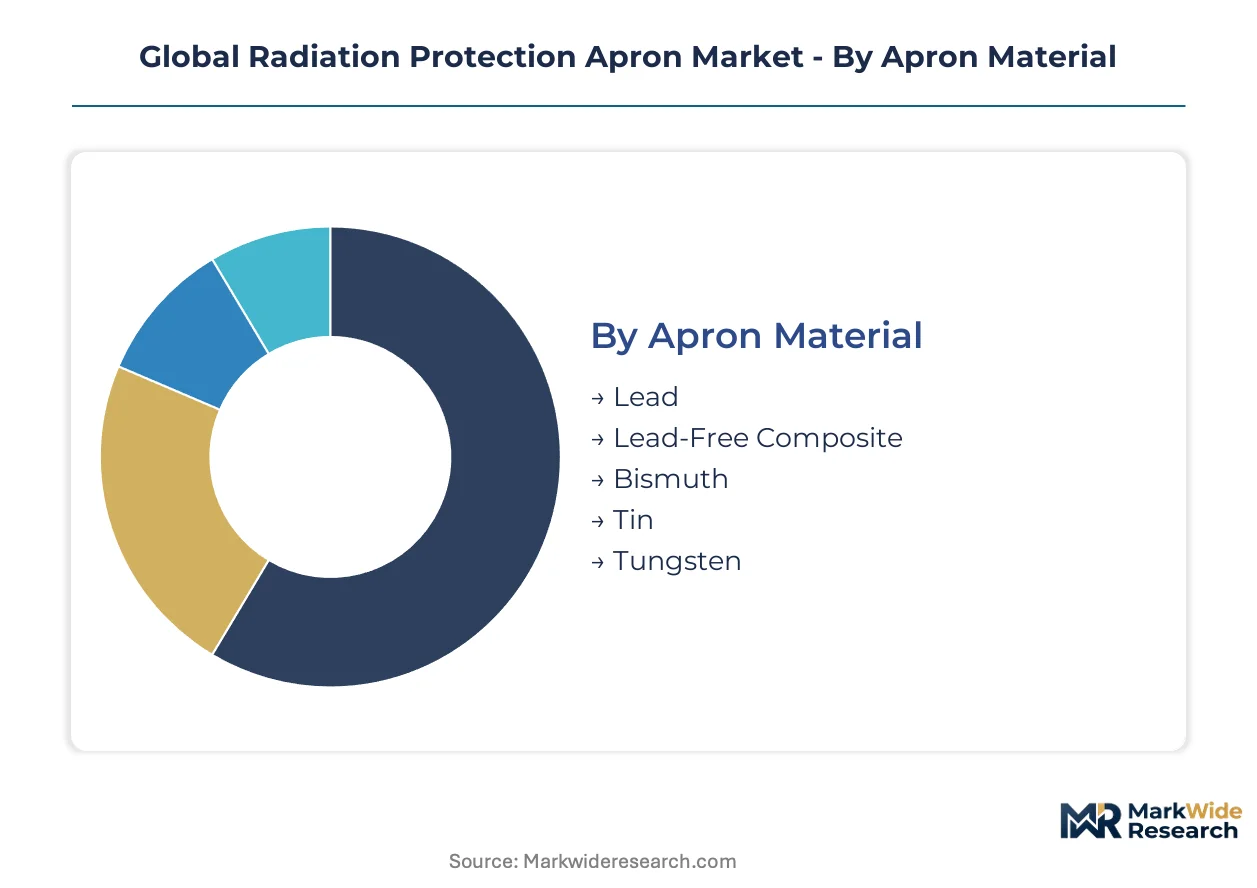
Radiation protection apron procurement channels diverge sharply by material certification status and end-use environment. Hospital group purchasing organizations consolidate high-volume contracts around standardized lead-free specifications, while independent dental practices purchase through distributor networks with less stringent material mandates.
Apron Material:
Material selection determines distribution pathway: lead-core aprons flow through traditional medical device distributors with established hazardous waste handling relationships, while lead-free composites increasingly move through direct manufacturer contracts with integrated delivery networks.
- Lead:Traditional lead sheet construction delivers 0.5 mm lead-equivalence attenuation through proven manufacturing processes. Demand concentrates in United States rural hospitals and cost-sensitive procurement environments where disposal regulation enforcement remains fragmented and replacement cycles extend toward seven-year depreciation schedules.
- Lead-Free Composite:Tungsten-vinyl and bismuth-polymer matrices achieve equivalent attenuation at 30-40% reduced weight. German interventional cardiology departments and Japanese tertiary cardiac centers are standardizing these formulations to preempt EU MDR recertification deadlines and mitigate orthopedic injury litigation exposure.
- Bismuth:Heavy metal-polymer compounds serve niche applications requiring flexible shielding geometries. Pharmaceutical demand for bismuth compounds constrains raw material allocation to apron manufacturers.
- Tin:Lower-density alternative exhibits attenuation degradation above 100 kVp, limiting adoption to dental and extremity imaging applications with controlled exposure parameters.
- Tungsten:Highest-density lead-free element enables thinnest profile garments. Chinese export quota volatility on processed tungsten ore concentrates supply risk for manufacturers dependent on Asian raw material sourcing.
By volume, Lead maintains position across replacement markets. By growth pace, Lead-Free Composite is climbing the fastest.
Application Area:
Procedure complexity and fluoroscopy duration determine apron specification tier, with high-exposure environments commanding premium lightweight composites and low-exposure settings tolerating standard lead-core alternatives.
- Interventional Radiology:Prolonged fluoroscopic procedures with lateral scatter exposure demand wraparound and two-piece apron architectures. United States academic medical centers are consolidating procurement around 0.5 mm lead-equivalence tungsten-vinyl systems to address cumulative occupational dose concerns.
- Nuclear Medicine:Gamma-emitting isotope handling requires frontal shielding optimized for specific energy spectra. German nuclear medicine departments specify bismuth-tin composites for technetium-99m and iodine-131 procedures.
- Cardiology:Cardiac catheterization labs generate the highest apron utilization rates per facility. Japanese tertiary networks standardize two-piece designs to enable rapid donning during emergency PCI procedures.
- Dental Radiography:Low-dose panoramic and cephalometric imaging permits lighter 0.25 mm lead-equivalence garments. Independent dental practices in France purchase through regional distributor networks with limited material specification enforcement.
- Orthopedics:Intraoperative fluoroscopy for fracture fixation drives demand in trauma centers. Orthopedic surgeon preference for mobility-optimized vest aprons is displacing traditional coat designs in United States hospital systems.
Cardiology generates the highest unit volume per installation. Interventional Radiology exhibits the steepest specification upgrade trajectory.
User Type:
Professional liability exposure and repetitive strain injury risk vary across clinical roles, concentrating premium apron investment in high-frequency fluoroscopy operators.
- Radiologists:Interventional subspecialists face cumulative lifetime dose exposure requiring maximum protection. United States interventional radiologists are driving demand for ergonomic two-piece systems with thyroid collar integration.
- Radiologic Technologists:Positioning assistance during prolonged procedures generates repetitive lifting strain. Compensation claims from this category are accelerating hospital procurement specification shifts toward sub-5 kg garment weights.
- Surgeons:Orthopedic and vascular surgeons utilize fluoroscopy intermittently but require rapid donning capability. Japanese surgical suites prefer front-closing vest designs over overhead donning configurations.
- Dentists:Solo practitioners prioritize cost minimization over ergonomic optimization. French dental equipment distributors bundle standard lead aprons with panoramic imaging system purchases.
- Medical Physicists:Quality assurance testing and shielding verification roles require portable protection. German medical physics consultants specify lightweight alternatives for mobile testing across multiple facilities.
Radiologic Technologists represent the largest installed base by headcount. Radiologists command the highest per-unit expenditure.
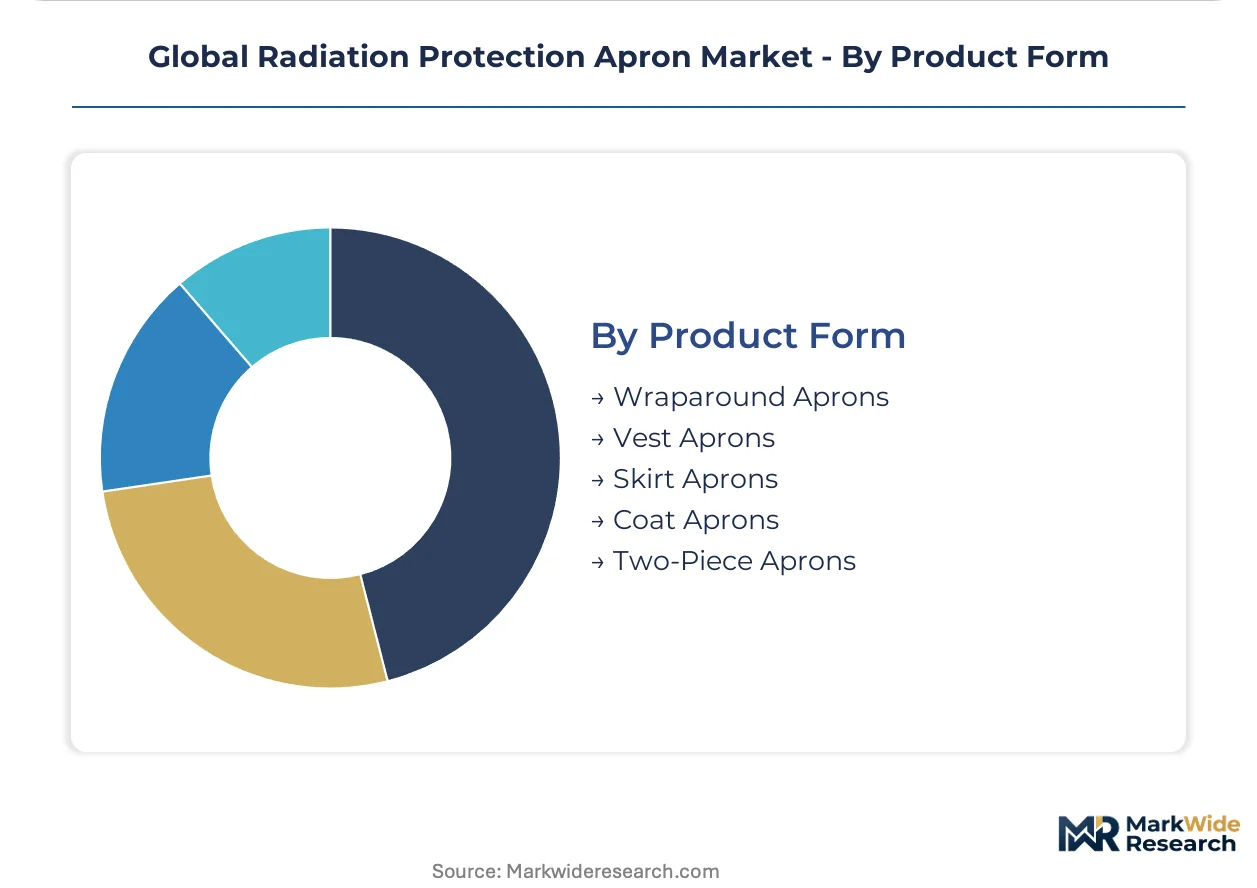
Product Form:
Garment architecture selection reflects procedural mobility requirements and scatter exposure geometry, with hybrid designs capturing preference in multi-procedure environments.
- Wraparound Aprons:360-degree protection for high-lateral-scatter environments including interventional suites. German cardiac catheterization labs specify these for electrophysiology procedures with extended fluoroscopy duration.
- Vest Aprons:Frontal protection with rear adjustability for seated operators. United States radiologic technologists prefer vest configurations for general radiography rooms with patient positioning demands.
- Skirt Aprons:Lower-body protection for seated nuclear medicine technologists. Japanese PET-CT facilities standardize skirt-vest combinations for isotope handling protocols.
- Coat Aprons:Traditional overhead-donning design with full frontal coverage. Declining preference in high-throughput environments due to donning time and shoulder strain concerns.
- Two-Piece Aprons:Separate skirt and vest components enable customized fit and weight distribution. United States interventional cardiology departments are consolidating procurement around these systems for physician and staff standardization.
Vest Aprons dominate unit volume through general radiography deployment. Two-Piece Aprons are gaining share fastest in interventional specialties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese tungsten ore processing dominates raw material supply for lead-free apron manufacturers, concentrating upstream vulnerability for fabricators across North America and Europe. Hospital procurement patterns diverge sharply between mature markets with MDR compliance deadlines and emerging economies building initial radiation protection infrastructure.
United States
Kaiser Permanente and Mayo Clinic direct-negotiate multi-year enterprise contracts for system-wide apron replacement programs. FDA 21 CFR performance standards for diagnostic x-ray systems drive specification upgrades across integrated delivery networks. California and Minnesota health systems concentrate procurement volume through group purchasing organizations, displacing traditional distributor-mediated channels.
Germany
KBA coordinates national interpretations of CE marking requirements that determine market access timelines for apron manufacturers. EU MDR recertification deadlines through 2026 compel hospital systems to replace aging aprons with certified lead-free alternatives. Bavarian and North Rhine-Westphalian cardiac catheterization labs standardize tungsten-vinyl formulations to preempt compliance cutoffs.
Japan
Japanese tertiary cardiac centers generate the highest apron utilization rates per facility through emergency PCI procedure volumes. METI industrial standards influence procurement specifications for radiation protection equipment. Tokyo and Osaka metropolitan hospital networks consolidate sourcing around two-piece apron designs for rapid donning protocols.
India
National Accreditation Board for Hospitals mandates radiation protection protocols in newly constructed cardiac centers, opening procurement channels for certified suppliers. CDSCO medical device regulations create compliance pathways for imported protective equipment. Maharashtra and Karnataka hospital construction booms concentrate demand in western and southern states.
France
ANSM interprets EU MDR requirements for protective device reclassification by notified bodies, extending approval timelines. REACH annex XVII restrictions on lead content accelerate reformulation investments across EU-manufactured equipment. Paris and Lyon interventional radiology departments consolidate procurement around pre-certified lead-free suppliers.
Global Radiation Protection Apron Market Competitive Landscape
Concentration sits with specialized medical device fabricators possessing notified body relationships and hazardous waste handling certifications. The vendor base spans three tiers: premium composite specialists, scale-driven lead-core manufacturers, and regional distributors. Strategic moves center on M&A for manufacturing scale and partnerships with tungsten compounders for raw material security.
Within the premium composite tier, Burlington Medical and Amray Radiation Protection exemplify divergent positioning strategies. Burlington Medical occupies a position anchored in proprietary material formulations for North American hospital networks. Amray Radiation Protection represents specialization in procedural-specific garment architectures. Infab Corporation sits within the scale-driven tier, leveraging manufacturing volume for cost-sensitive procurement environments. These three anchors illustrate how material certification status and distribution channel control separate competitive positions.
| Leading Market Players |
|---|
| AliMed |
| Amray Radiation Protection |
| Barrier Technologies |
| Burlington Medical |
| BLOXR Solutions |
| Infab Corporation |
| Shielding International |
| Rampart International Corporation |
| Wolf X-Ray Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between tungsten compounders and North American apron fabricators lock in raw material access while providing price visibility against Chinese export quota volatility. These arrangements concentrate procurement power among integrated delivery networks in California and Minnesota, forcing mid-tier distributors toward spot-market exposure on bismuth-tin alternatives.
Pricing Analysis
FDA 21 CFR performance standards and EU MDR recertification requirements dictate the pricing tier structure across the radiation protection apron market. Three-tier pricing structure across premium, standard, and economy levels separates tungsten-vinyl composites certified for interventional suites from uncertified lead-core alternatives sold through dental distributors. Cost compression in the standard tier is intensifying as German notified body backlogs delay premium product launches and extend legacy lead-apron depreciation schedules. Independent dental practices in France exhibit the highest price sensitivity, while United States academic medical centers prioritize certification grade over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes are elevating inbound logistics costs for tungsten ore concentrates and finished polymer compounds. Raw material supply draws from Chinese tungsten processing facilities, South Korean vinyl compounders, and German textile converters. Single-source vulnerability concentrates in Chinese export quotas for processed tungsten. Distribution runs through hospital group purchasing organizations for lead-free composites and traditional medical device distributors for lead-core alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR recertification deadlines and FDA performance standard updates are accelerating material substitution timelines, compressing competitive windows for manufacturers lacking lead-free composite certification.
For Market Incumbents: Consolidate manufacturing scale in tungsten-vinyl extrusion capacity to preempt mid-tier competitors from achieving production volumes exceeding 10,000 units annually. Deepen notified body relationships in Germany and France to navigate approval timeline extensions from 12 to 24 months. Anchor supply security through backward integration into tungsten compounder partnerships or captive offtake agreements. For New Entrants and Emerging Players: End-of-life apron recycling services represent an underserved layer where incumbents under-serve hospital systems facing REACH and EPA hazardous waste regulations. Target Indian tertiary cardiac centers constructing new catheterization labs under National Accreditation Board for Hospitals mandates. Pursue direct-to-facility distribution contracts bypassing traditional medical device distributors to capture margin leakage. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale compounders possessing proprietary heavy metal-polymer matrices and existing notified body technical documentation. Long-term viability hinges on certification moats rather than manufacturing scale alone. Monitor EU MDR approval velocity at German and French notified bodies as the inflection indicator for procurement preference consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR recertification at German notified bodies accelerates lead-free apron procurement consolidation. |
| Backward Integration | Captive tungsten compounder partnerships insulate manufacturers from Chinese export quota volatility. |
| Hospital System Partnership | Direct contracts with Kaiser Permanente and Mayo Clinic displace distributor-mediated channels. |
| Reimbursement Strategy | Ergonomic injury claim documentation supports premium pricing for sub-5 kg garment weights. |
| Software Companion Development | Dose tracking integration positions apron suppliers within radiation safety management platforms. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and radiation safety officers; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contracts, and customs trade records. Bottom-up unit demand modeling triangulated against top-down market sizing across apron material, application area, and product form dimensions.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmented demand curves for lead-core and lead-free composite alternatives. CAGRs were derived from replacement cycle analysis, procedure volume growth in interventional cardiology, and regulatory compliance deadline clustering. Forecast inputs incorporated tungsten ore price volatility indices and notified body capacity utilization rates.
Forecasts assume regulatory continuity in FDA 21 CFR enforcement and EU MDR implementation; material policy shifts in REACH annex restrictions or Chinese export licensing would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Radar Speed Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Latin America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Fluid Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Powered Air Purifying Respirator (PAPR) Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market