
 Respirator Mask Particulate Market | 2026-2036
Respirator Mask Particulate Market Size, Share, and Industry Trends Forecast 2026-2036
Respirator Mask Particulate Market Analytics
Healthcare providers are bifurcating from industrial buyers as the dominant procurement archetype for high-filtration disposables. 3M leverages its captive meltblown supply chain to secure hospital system contracts across North America. Honeywell International Inc. anchors its position through dual certification under NIOSH and EN 149 standards, enabling cross-border tender participation. MSA Safety Incorporated differentiates via integrated head, eye, and respiratory protection platforms for first responder agencies.
A respirator mask particulate is a personal protective device engineered to filter airborne solid particulates through nonwoven polypropylene media with electrostatic charge enhancement, typically achieving filtration efficiencies at 0.3 micron particle sizes. Its primary commercial purpose is occupational hazard mitigation in environments with elevated concentrations of mineral dust, biological aerosols, or combustion particulates. Disposable masks command the largest volume share due to pandemic-normalized hospital consumption patterns, while powered air-purifying respirators represent the fastest-expanding category as battery weight reduction extends wear-time tolerance in heavy industrial settings. Activated carbon composite materials capture premium margin pools where nuisance vapor removal accompanies particulate filtration.
NIOSH certification under 42 CFR Part 84 governs minimum filtration efficiency and breathing resistance for US-market respirators, while EN 149 defines FFP1 through FFP3 performance tiers across European Economic Area jurisdictions. OSHA's updated silica and lead exposure standards are mandating shift from single-use nuisance masks to fit-tested elastomeric half-face designs in construction and foundry applications. ASTM F2100 and ISO 16975-3 convergence pressures are forcing manufacturers to harmonize test protocols or maintain parallel quality systems. Stakeholders must monitor emerging state-level stockpile mandates and determine whether regional assembly investments offset tariff exposure on finished Asian-origin disposables.
Market Dynamics
OSHA's silica permissible exposure limit reduction is forcing construction and foundry operators to abandon nuisance dust masks in favor of fit-tested elastomeric respirators, compressing upgrade cycles and reshaping supplier qualification criteria across North American industrial channels.
Growth Catalysts
- REACH-compliant filter mandates:ECHA enforcement in Germany is disqualifying non-certified suppliers and consolidating procurement toward validated media sources for industrial applications.
- Battery weight reduction:Lithium-ion cell density improvements are extending powered air-purifying respirator wear-time tolerance in heavy industrial settings, expanding addressable use cases.
- Hospital system contract consolidation:Integrated delivery networks in the United States are centralizing N95-equivalent purchasing through sole-source agreements with captive meltblown producers.
Market Restraints
- Polypropylene resin concentration:Asian petrochemical complexes control over 60 percent of nonwoven-grade feedstock, exposing converters to freight and tariff volatility.
- NIOSH certification backlog:42 CFR Part 84 testing queue delays are extending new product time-to-market by 8-14 months for domestic manufacturers.
- Surgical mask substitution:ASTM F2100 Level 3 disposables are capturing low-hazard industrial demand where employers prioritize unit cost over fit assurance.
Strategic Opportunities
- Indian industrial expansion:BIS certification requirements under the PLI scheme for technical textiles are creating first-mover advantages for filter media investors establishing local meltblown capacity.
- Wearable sensor convergence:Integration of real-time fit monitoring electronics with elastomeric platforms is enabling outcome-based respiratory protection programs for high-exposure employers.
- State stockpile mandates:Subnational emergency preparedness legislation in multiple US jurisdictions is institutionalizing forward purchasing agreements for pandemic-grade disposable reserves.
Industry Challenges
- Electrostatic charge retention expertise:Coronal treatment and tribocharging process engineering talent is concentrated among a narrow cohort of polymer scientists, constraining new entrant scale-up velocity.
- Dual quality system maintenance:Manufacturers serving both NIOSH and EN 149 jurisdictions face redundant testing costs and protocol harmonization gaps between 42 CFR Part 84 and ISO 16975-3.
- Legacy fit test infrastructure:Quantitative fit testing equipment deployment lags regulatory mandate expansion, creating compliance execution bottlenecks for distributed construction workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respirator Mask Particulate Market |
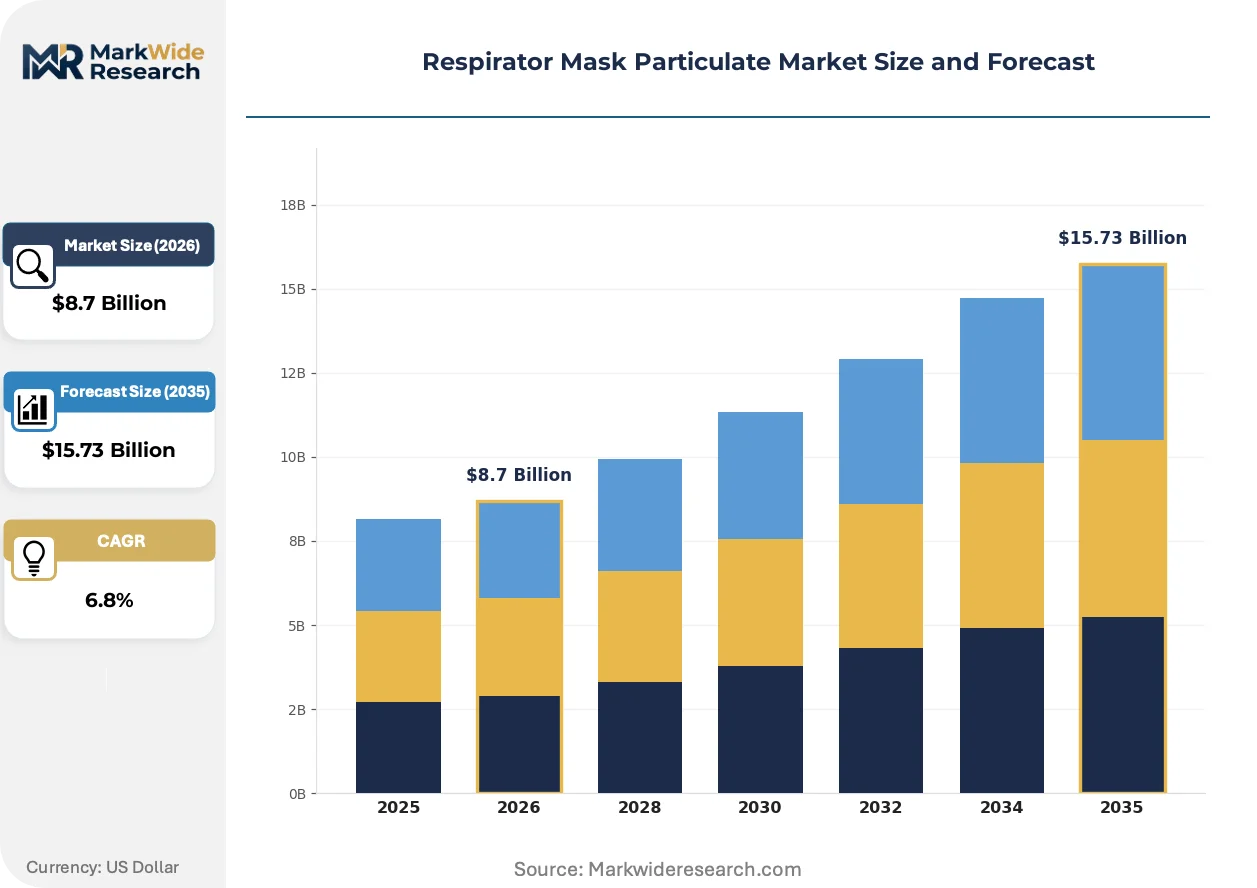
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Masks, Reusable Masks, Powered Air-Purifying Respirators, Half Face Masks Material: Polypropylene, Polyester, Activated Carbon, Silicone End User: Healthcare Providers, Industrial Workers, Construction Sites, First Responders Regulatory Standards: NIOSH, EN 149, ASTM, ISO |
| Companies Covered | 3M, Honeywell International Inc., Moldex-Metric, Kimberly-Clark Professional, Drägerwerk AG & Co. KGaA, MSA Safety Incorporated, Bullard, Alpha Pro Tech, Sundstrom Safety, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respirator Mask Particulate Market Evolving Landscape
Electrospun nanofiber media, biometric fit verification, and procurement centralization are converging to redefine performance benchmarks and commercial relationships across respiratory protection categories.
Electrospun polyurethane nanofiber webs are achieving sub-micron interception with lower breathing resistance than conventional meltblown polypropylene. Mining operators in Australia are piloting these media in hot, humid underground conditions where comfort compliance drives actual protection. The technology is decomposing the traditional trade-off between filtration efficiency and wearer tolerance that has constrained elastomeric adoption rates.
REACH Annex XVII restrictions on persistent organic pollutants are accelerating filter media reformulation across European Economic Area supply chains. German industrial safety distributors are now requiring full material disclosure documentation upstream of tender participation. Construction consortia in France and the Netherlands are responding by pre-qualifying only REACH-registered suppliers for multi-year framework agreements.
Hospital procurement departments are consolidating SKU rationalization authority previously held by individual facility materials managers. Group purchasing organizations are displacing spot-market purchasing through committed volume contracts with penalty clauses for supply interruption. This concentration is most visible in Texas and California, where mega-systems are forcing filter media suppliers to absorb inventory carrying costs in exchange for exclusive supply status.
Respirator Mask Particulate Market Segmentation
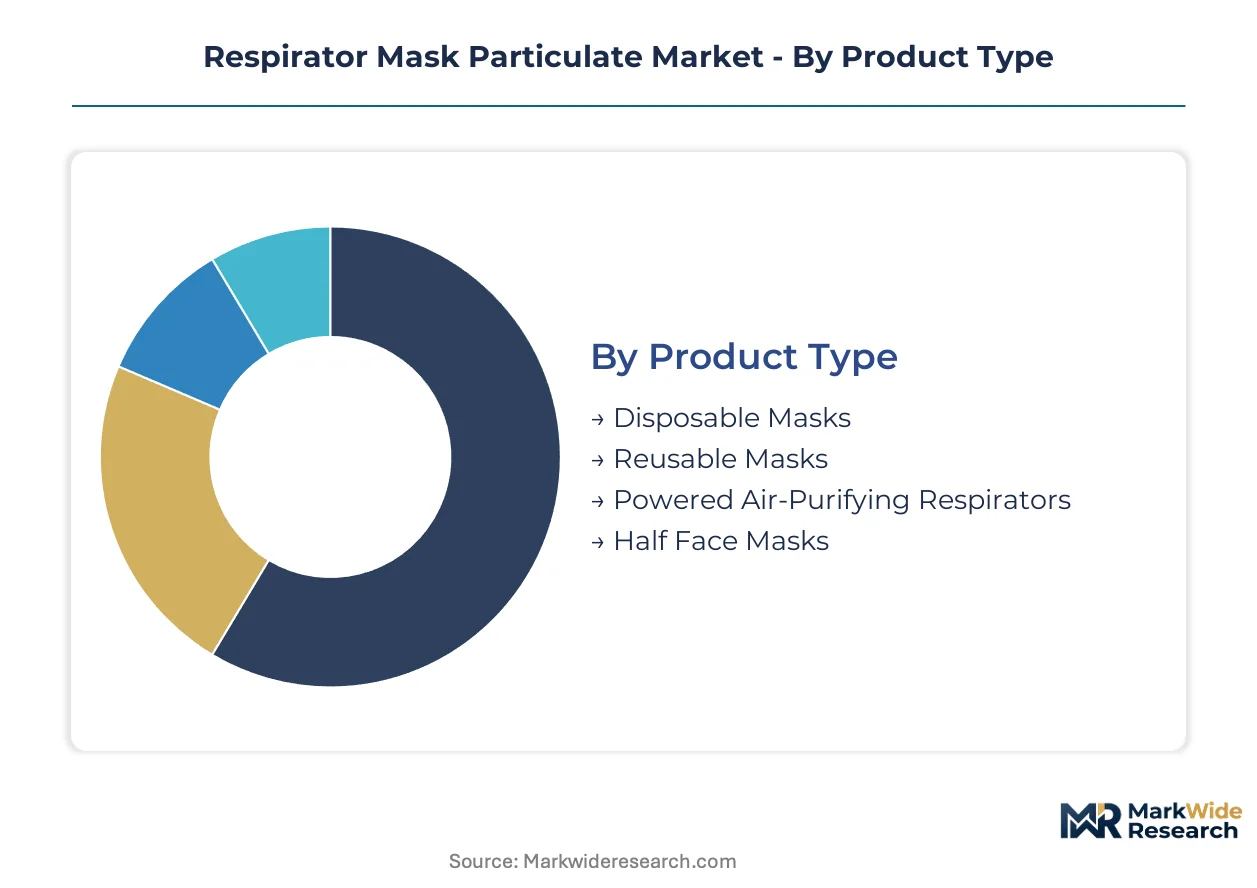
Respirator mask particulate demand fragments sharply across product architectures, with procurement channels diverging between hospital system GPOs, industrial safety distributors, and government tender boards. Material selection and certification tier determine margin capture, while end-use specialization dictates fit-testing infrastructure requirements and replacement cycle economics.
Product Type:
Channel mix varies dramatically: disposable masks flow through healthcare GPOs and emergency stockpile tenders, while elastomeric platforms and PAPRs concentrate in industrial safety distribution and first responder agency procurement.
- Disposable Masks:Nonwoven polypropylene media with electrostatic charge enhancement achieve filtration at 0.3 micron particle sizes. Hospital systems in the United States and Germany dominate procurement through sole-source agreements with captive meltblown producers, though silica rule tightening is compressing industrial upgrade cycles toward fit-tested alternatives.
- Powered Air-Purifying Respirators:Battery-powered blower units force ambient air through high-efficiency filters, reducing breathing resistance and extending wear-time tolerance. Mining operators in Australia and heavy manufacturing facilities in Germany are piloting these systems in hot, humid conditions where comfort compliance drives actual protection, with lithium-ion cell density improvements expanding addressable use cases.
- Reusable Masks:Elastomeric facepieces with replaceable filter cartridges serve high-exposure industrial environments. Foundry and construction operators facing OSHA silica limit reductions are abandoning nuisance masks for fit-tested half-face designs.
- Half Face Masks:Silicone or thermoplastic elastomer face seals with dual cartridge attachment points. First responder agencies and industrial maintenance crews prioritize these for chemical splash protection combined with particulate filtration.
By volume, disposable masks lead. By growth pace, powered air-purifying respirators are climbing the fastest.
Material:
Cost tier stratification separates commodity feedstocks from performance composites, with premium margin pools concentrating where nuisance vapor removal accompanies particulate filtration.
- Polypropylene:Meltblown nonwoven webs with electrostatic charging dominate disposable mask production. Asian petrochemical complexes control the majority of nonwoven-grade feedstock, exposing converters to freight and tariff volatility.
- Activated Carbon:Impregnated filter media capture organic vapors and acid gases alongside particulates. REACH Annex XVII restrictions on persistent organic pollutants are accelerating reformulation across European supply chains, with German distributors requiring full material disclosure documentation.
- Polyester:Spunbond support layers provide structural integrity to multilayer filter packs. Lower-cost alternatives for nuisance dust applications where filtration efficiency requirements are less stringent.
- Silicone:Face seal materials for reusable elastomeric platforms offer chemical resistance and facial conformity. Medical-grade specifications command premium positioning in healthcare and first responder channels.
Polypropylene dominates unit economics. Activated carbon composites capture the steepest margin expansion.
End User:
Customer type determines certification requirements, with healthcare procurement bifurcating from industrial buyers as the dominant archetype for high-filtration disposables.
- Healthcare Providers:Hospital systems and outpatient clinics consume N95-equivalent disposables under pandemic-normalized stocking patterns. Group purchasing organizations in Texas and California are centralizing authority and forcing suppliers to absorb inventory carrying costs.
- Industrial Workers:Manufacturing, mining, and processing facilities face tightening exposure limits for silica and lead. OSHA enforcement is mandating shift from single-use nuisance masks to fit-tested elastomeric designs.
- Construction Sites:Distributed workforces with high turnover struggle with quantitative fit testing equipment deployment. ASTM F2100 Level 3 surgical mask substitution captures low-hazard demand where employers prioritize unit cost.
- First Responders:Fire departments, hazmat teams, and emergency medical services require integrated head, eye, and respiratory protection platforms. Agency-level tenders favor suppliers with dual NIOSH and EN 149 certification.
Healthcare channels move the highest unit volumes. Industrial replacement cycles are gaining share fastest as regulatory pressure intensifies.
Regulatory Standards:
Geography determines certification burden, with manufacturers serving multiple jurisdictions facing redundant testing costs and protocol harmonization gaps.
- NIOSH:42 CFR Part 84 governs minimum filtration efficiency and breathing resistance for US-market respirators. Certification backlog delays are extending new product time-to-market by 8-14 months for domestic manufacturers.
- EN 149:Defines FFP1 through FFP3 performance tiers across European Economic Area jurisdictions. ECHA enforcement of REACH-compliant filter media is reshaping supplier qualification requirements in Germany.
- ASTM:F2100 establishes barrier protection levels for surgical masks, with Level 3 disposables capturing industrial substitution demand. Convergence pressures with ISO 16975-3 are forcing parallel quality system maintenance.
- ISO:16975-3 and related standards provide international test protocol frameworks. Harmonization gaps with NIOSH and EN 149 methods create compliance complexity for multinational suppliers.
NIOSH and EN 149 dominate commercial access. ISO framework adoption is expanding most quickly as manufacturers seek protocol rationalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German filter media exports flow primarily to industrial buyers across France, the Netherlands, and Belgium, while Chinese meltblown converters supply hospital systems in the United States and Southeast Asia through distributor networks.
United States
Hospital procurement centralization in Texas and California is displacing spot-market purchasing through committed volume contracts with penalty clauses. OSHA's updated silica permissible exposure limits are mandating shift from nuisance masks to fit-tested elastomeric respirators in construction and foundry applications. The Ohio River Valley manufacturing corridor is seeing accelerated deployment of powered air-purifying respirators in heavy industrial facilities.
Germany
ECHA enforcement of REACH-compliant filter media is disqualifying non-certified suppliers and consolidating procurement toward validated media sources. Industrial safety distributors in Bavaria and North Rhine-Westphalia now require full material disclosure documentation upstream of tender participation. The Ruhr industrial basin is piloting electrospun nanofiber media in hot, humid underground mining conditions where comfort compliance drives actual protection.
China
Asian petrochemical complexes control the majority of nonwoven-grade polypropylene feedstock, exposing converters to freight and tariff volatility. GB standards alignment with ISO frameworks is expanding protocol rationalization for multinational suppliers serving domestic and export markets. The Yangtze River Delta cluster maintains concentrated meltblown capacity serving both healthcare and industrial channels.
India
BIS certification requirements under the PLI scheme for technical textiles are creating first-mover advantages for filter media investors establishing local meltblown capacity. Maharashtra and Gujarat industrial zones are attracting capital deployment as procurement shifts from imported disposables to domestically certified alternatives. The Delhi-NCR corridor is seeing state-level emergency preparedness legislation institutionalize forward purchasing agreements for pandemic-grade reserves.
Australia
Mining operators in Western Australia and Queensland are piloting electrospun polyurethane nanofiber webs in hot, humid underground conditions where comfort compliance drives actual protection. The country's national occupational health regulator is tightening enforcement of fit-testing infrastructure deployment across distributed construction workforces. The Perth metropolitan area is emerging as a hub for outcome-based respiratory protection programs integrating wearable sensor convergence.
Respirator Mask Particulate Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and channel access. The vendor base concentrates around three to five integrated multinationals with captive meltblown supply chains, while mid-scale specialists occupy niche positions in first responder or mining-specific applications. Strategic archetypes include certification-dualists serving both NIOSH and EN 149 jurisdictions, captive-media producers with backward integration into polymer feedstock, and integrated-platform suppliers bundling head, eye, and respiratory protection. Dominant competitive moves center on hospital system sole-source contract capture and regional assembly investments to offset tariff exposure on finished Asian-origin disposables.
Within the certification-dualist tier, 3M and Honeywell International Inc. exemplify multinational scale positions spanning healthcare GPO and industrial safety distribution channels. MSA Safety Incorporated occupies a specialist position in integrated protection platforms for first responder agency procurement. These three anchors represent divergent strategic postures: captive supply chain control, cross-border regulatory arbitrage, and end-use application bundling respectively.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| Moldex-Metric |
| Kimberly-Clark Professional |
| Drägerwerk AG & Co. KGaA |
| MSA Safety Incorporated |
| Bullard |
| Alpha Pro Tech |
| Sundstrom Safety |
| Others |
Value Network & Pricing Analysis
NIOSH certification under 42 CFR Part 84 gates both supply qualification and price differentiation simultaneously, creating tiered access where certified manufacturers command premium positioning over uncertified converters while hospital GPOs exploit sole-source contracts to compress margins on standard disposables.
Pricing Analysis
Electrospun nanofiber media commands 40-60% premiums over conventional meltblown polypropylene, while legacy nuisance dust masks face commoditization as OSHA silica rules force industrial buyers toward fit-tested elastomeric platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and captive meltblown integration, with N95-equivalent disposables under hospital GPO pressure seeing cost compression while powered air-purifying respirators capture value from battery density improvements. Price differentiation hinges on dual NIOSH-EN 149 certification and backward integration into polymer feedstock. Construction employers show highest price sensitivity, substituting ASTM F2100 Level 3 surgical masks where hazard levels permit.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes are amplifying landed cost volatility for finished mask imports, forcing procurement departments to reassess inventory carrying strategies. Asian petrochemical complexes in China and South Korea control the majority of nonwoven-grade polypropylene feedstock, while German filter media specialists and US captive producers serve premium industrial channels. Raw material dependencies center on propylene monomer, electrostatic charging additives, and lithium-ion cells for PAPR power packs. Single-source vulnerability concentrates in Yangtze River Delta meltblown capacity. Distribution runs through hospital GPOs, industrial safety distributors, and government tender boards with diverging qualification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA's silica permissible exposure limit reduction constitutes a high-growth disruption, compressing industrial upgrade cycles and reallocating procurement spend toward fit-tested elastomeric platforms and powered air-purifying systems.
For Market Incumbents: Secure sole-source hospital system contracts in Texas and California through captive meltblown capacity commitments, while accelerating REACH-compliant filter media reformulation to defend German industrial distributor relationships against ECHA enforcement disqualification. Prioritize electrostatic charge retention talent acquisition to constrain new entrant scale-up velocity. For New Entrants and Emerging Players: BIS certification fast-track under India's PLI scheme for technical textiles unlocks first-mover positioning in Maharashtra and Gujarat industrial zones, where procurement shifts from imported disposables to domestically certified alternatives. Target state-level stockpile mandates in Delhi-NCR corridor through forward purchasing agreement structures. Pursue wearable sensor integration partnerships with elastomeric platform specialists to enable outcome-based respiratory protection programs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized respiratory protection divisions lacking dual NIOSH-EN 149 certification infrastructure. Long-term viability centers on regulatory arbitrage capability and backward integration into polymer feedstock. Watch NIOSH certification backlog resolution as inflection indicator for new product velocity and competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Meltblown Capacity Expansion | Hospital GPOs in Texas and California prioritize sole-source suppliers with backward-integrated polymer feedstock control. |
| Dual Certification Investment | Simultaneous NIOSH and EN 149 qualification enables cross-border tender participation in Germany and North America. |
| Wearable Sensor Integration | Real-time fit monitoring electronics differentiate elastomeric platforms for high-exposure mining and foundry employers. |
| Regional Assembly Footprint | Localized production in India and Southeast Asia offsets tariff exposure on finished Asian-origin disposable imports. |
| REACH-Compliant Media Reformulation | ECHA enforcement in Germany disqualifies non-certified suppliers from Bavaria and North Rhine-Westphalia industrial tenders. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings in this analysis. Primary engagement spanned hospital procurement directors, industrial safety distributors, respiratory protection product managers, polymer scientists specializing in electrostatic charging, and regulatory affairs leads at certification bodies. Secondary validation drew from OSHA enforcement records, NIOSH 42 CFR Part 84 certification databases, ECHA REACH registration documentation, hospital GPO contract disclosures, and customs trade data on polypropylene nonwoven imports. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Sensitivity analysis around battery weight reduction trajectories and silica rule enforcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, material composition, end-user industry, certification standard, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, pandemic-normalized consumption pattern persistence, and industrial regulatory compliance upgrade elasticity. Forecast inputs incorporated lithium-ion cell density improvement curves and BIS certification throughput capacity under India's PLI scheme.
Decision-makers should treat outputs as directional under base assumptions of sustained OSHA enforcement intensity and REACH Annex XVII expansion; material deviation would warrant model refresh. Specific risk factors include NIOSH certification queue resolution delays, polypropylene resin price volatility from Asian petrochemical complex utilization shifts, and surgical mask substitution elasticity in low-hazard construction segments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Armor Accessories Market
Safety Equipment and Personal Protective Equipment (PPE)
Driving Protection Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Arc Flash Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Protective Coating Market
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market