
 Pest Control Devices Market | 2026-2036
Pest Control Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pest Control Devices Market Analytics
The pest control devices market is decoupling sharply between premium connected systems and commodity mechanical traps. Woodstream Corporation leverages its century-old trap manufacturing heritage and retail shelf dominance to anchor the mass-market tier. Rentokil Initial plc competes through its digital pest-control platform and service-led model, integrating sensors with recurring revenue contracts. Spectrum Brands Holdings Inc differentiates via ultrasonic and thermal repellent lines sold through home improvement channels, occupying the mid-premium consumer segment.
Pest control devices encompass electromechanical and chemical-delivery apparatus engineered to capture, repel, or eliminate arthropod and rodent populations, typically operating through ultrasonic emission, pheromone lures, or precision-spray mechanisms with calibrated dosage between 0.5 and 5 milliliters per activation. These systems serve commercial facilities, agricultural operations, and residential structures where integrated pest management protocols mandate documented intervention thresholds. Insect traps lead device-type revenue due to food safety audits requiring continuous monitoring documentation, while electronic baits represent the fastest-growing technology segment as connectivity enables real-time catch alerts. Ultrasonic technology dominates residential channels, though biological methods gain share in agricultural applications where export markets enforce maximum residue limits.
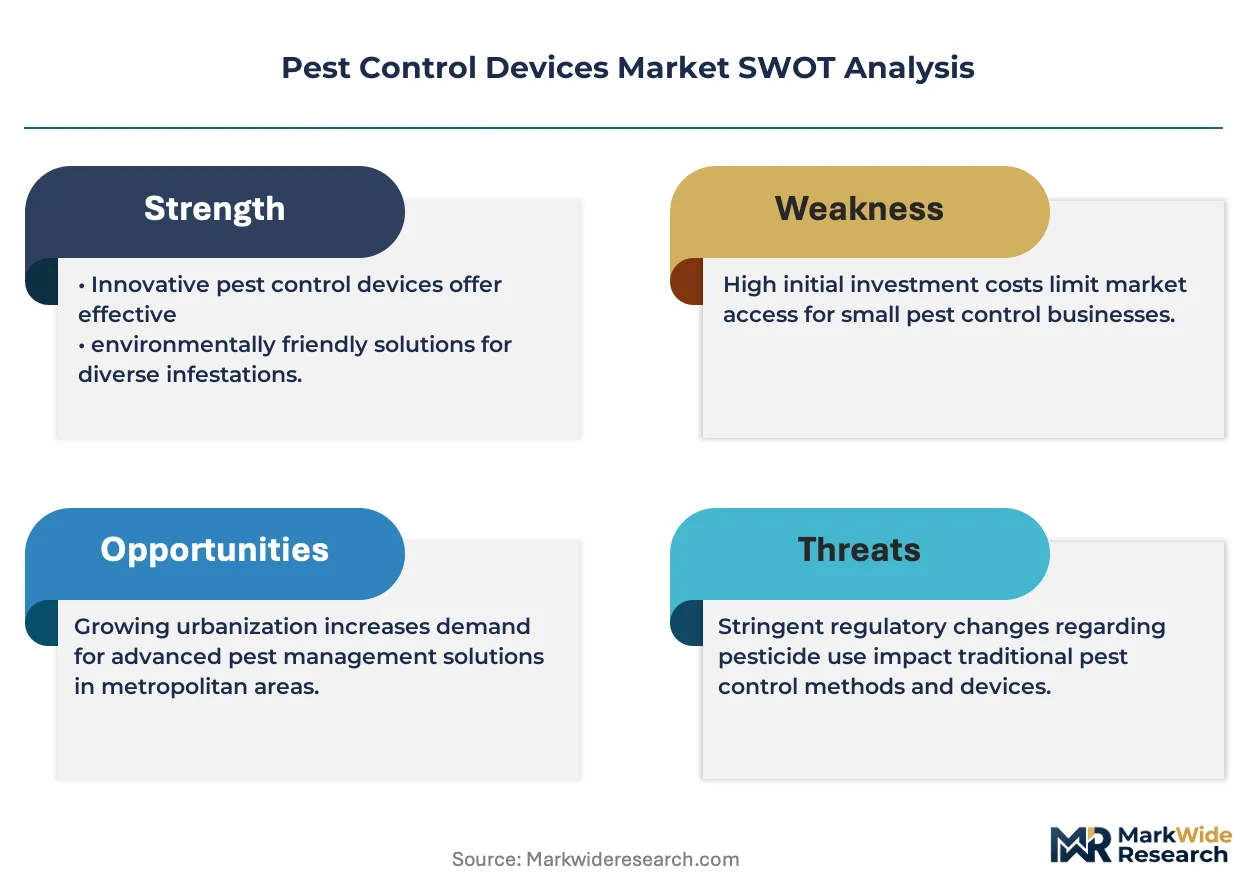
EPA registration under FIFRA shapes product chemistry and labeling requirements, determining which active ingredients enter the U.S. market and how devices qualify as minimum-risk alternatives. The EU REACH regulation and RoHS directives constrain material composition for electronics-heavy units exported to European markets, pushing manufacturers toward lead-free circuit boards and restricted substance compliance. Stakeholders must monitor evolving state-level neonicotinoid restrictions and emerging biopesticide pathways, as regulatory fragmentation between jurisdictions will determine which technology portfolios warrant scaled investment versus geographic divestment.
Market Dynamics
EPA and FIFRA regulatory shifts toward reduced-risk pesticides are compressing chemical-based solutions while accelerating hardware substitution across commercial and agricultural channels. This structural force is redrawing competitive boundaries between electromechanical device manufacturers and traditional pesticide formulators.
Growth Catalysts
- Neonicotinoid Restrictions:State-level bans on systemic insecticides in the United States are forcing agricultural operations toward pheromone-based monitoring systems and precision-spray electromechanical alternatives.
- Food Safety Audits:Continuous monitoring documentation requirements in commercial food processing facilities are mandating deployment of connected insect traps with automated catch logging capabilities.
- Sun Belt Season Extension:Extended pest pressure across Florida, Texas, Arizona, and California is sustaining year-round hardware replacement cycles and service contract renewals.
Market Restraints
- Electronics Supply Concentration:Lead-free circuit board sourcing for RoHS-compliant units faces dependency on East Asian PCB fabrication clusters, creating input volatility.
- Sensor Calibration Drift:Ultrasonic emitters and thermal detectors require field recalibration every 18-24 months, elevating total cost of ownership beyond initial hardware acquisition.
- Active Ingredient Registration:EPA FIFRA registration timelines for novel biopesticide-compatible devices extend 36-48 months, delaying product commercialization.
Strategic Opportunities
- Export Market Residue Limits:European Union maximum residue limit enforcement on agricultural imports is creating demand for non-chemical pest management documentation in developing producer countries.
- IoT-Enabled Predictive Models:Convergence of edge computing sensors with machine learning analytics is enabling population threshold forecasting that reduces reactive trap deployment.
- Home Improvement Channel Expansion:Mid-premium ultrasonic and thermal repellent lines are penetrating previously underserved rural residential markets through farm supply retailers.
Industry Challenges
- Integrated Pest Management Certification:Technician credentialing requirements for documented intervention threshold protocols are constraining field service expansion velocity.
- Legacy System Interoperability:Retrofitting connected monitoring platforms into existing building management systems requires proprietary API development that fragments vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pest Control Devices Market |
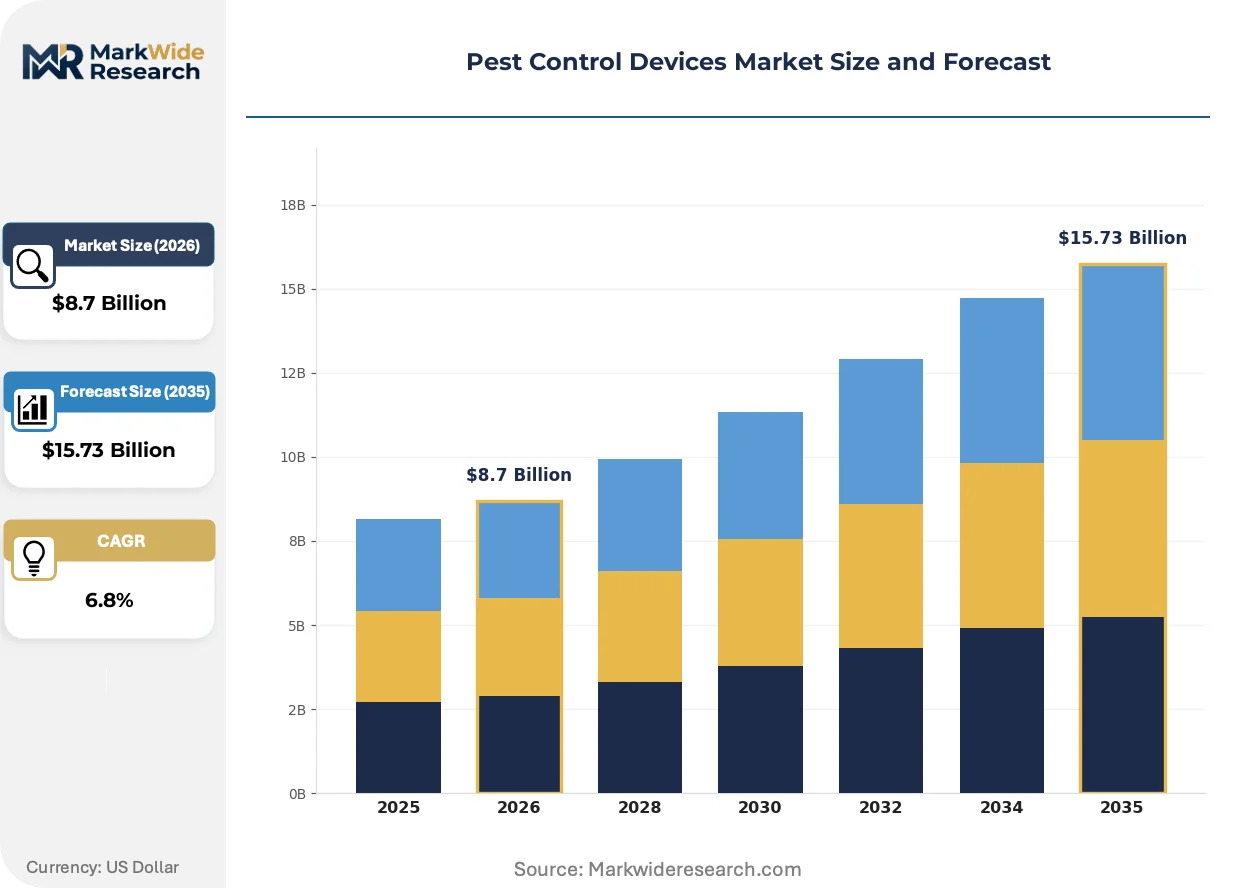
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Insect Traps, Rodent Repellents, Electronic Baits, Spraying Equipment Technology: Ultrasonic, Chemical, Biological, Thermal Application: Residential, Commercial, Agricultural, Industrial End User: Homeowners, Pest Control Services, Farmers, Hospitality |
| Companies Covered | Woodstream Corporation, Bell Laboratories Inc, Rentokil Initial plc, Spectrum Brands Holdings Inc, Thermacell Repellents Inc, Bird-X Inc, Nixalite of America Inc, The Scotts Miracle-Gro Company, FlyBye Bird Control Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pest Control Devices Market Evolving Landscape
Connectivity infrastructure and biological method integration are converging to redefine device functionality and service delivery architectures. These developments are compressing the gap between detection and intervention while elevating data documentation requirements.
Electromechanical precision-spray apparatus with calibrated dosage mechanisms is expanding into specialty crop operations where manual pesticide application faces labor scarcity and exposure liability. California almond and wine grape growers are piloting these systems at accelerating velocity. The technology is expanding into previously inaccessible terrain by enabling targeted delivery without ground crew deployment.
EU REACH regulation substance restriction amendments are compelling manufacturers to reformulate polymer housings and electronic encapsulants for devices exported to European markets. Industrial consequence includes accelerated R&D expenditure for compliant material substitution. Agricultural electromechanical units with extended field deployment cycles face the most acute compliance pressure, driving consolidation among smaller component suppliers unable to certify alternative chemistries.
Facility managers in food processing and pharmaceutical manufacturing are consolidating vendor relationships around full-service pest management contracts that bundle hardware, monitoring, and documentation. The segment being disrupted is transactional trap and repellent procurement through distributor channels. This concentration is most visible across the Midwest industrial corridor where audit frequency and documentation stringency have intensified.
Pest Control Devices Market Segmentation
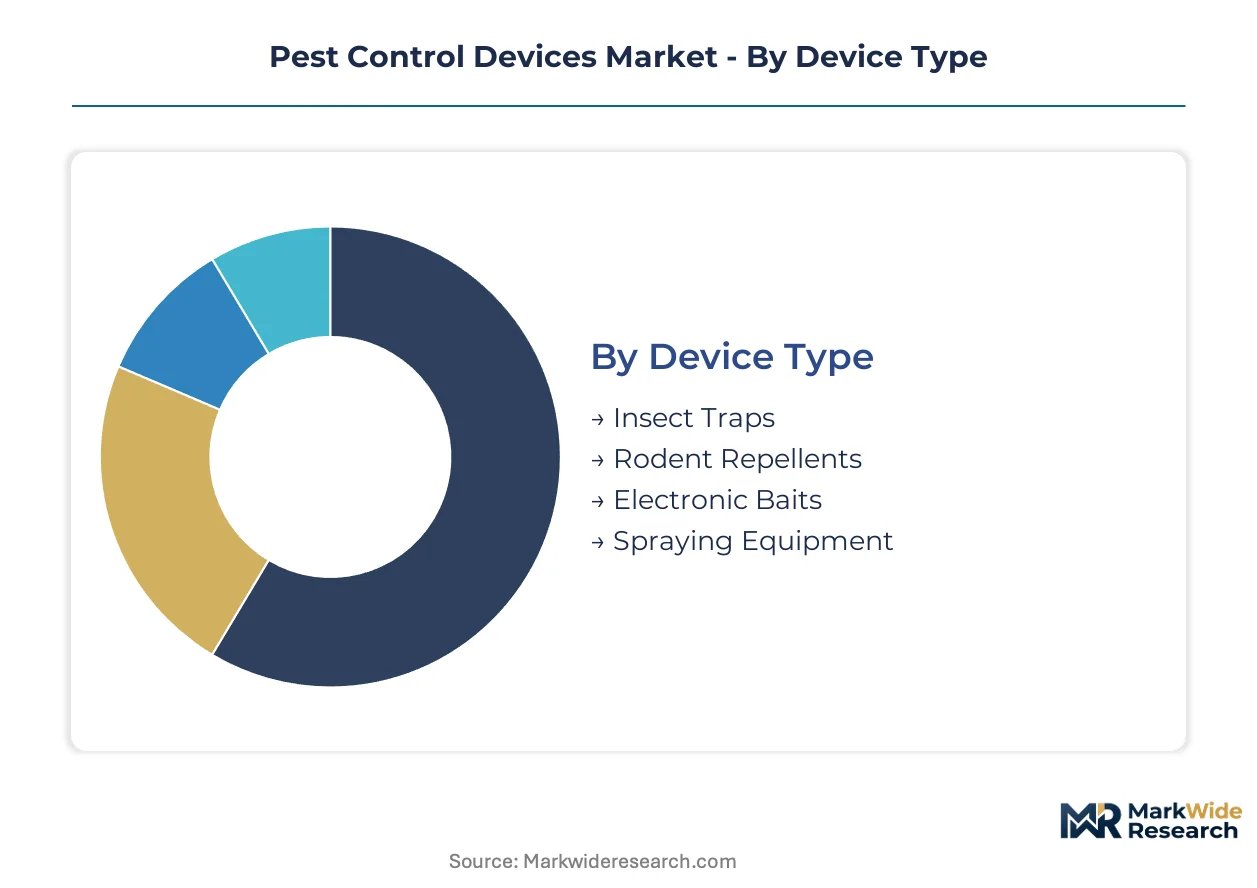
Pest control device segmentation reveals divergent margin profiles across mechanical hardware and connected systems. Procurement patterns vary sharply between transactional retail purchases and bundled service contracts with recurring revenue structures.
Device Type:
Volume concentrates in legacy mechanical traps while premium capture shifts toward sensor-integrated systems with telemetry capabilities.
- Insect Traps:Electromechanical capture systems with pheromone lures or UV light attraction dominate commercial food processing procurement. Continuous monitoring documentation requirements from FDA food safety audits drive demand for connected units with automated catch logging across California and Texas processing corridors.
- Electronic Baits:Sensor-equipped dispensers with real-time activation alerts and consumption tracking represent the steepest expansion trajectory. IoT-enabled population threshold forecasting reduces reactive deployment for pest control services in Sun Belt metropolitan markets.
- Rodent Repellents:Ultrasonic and electromagnetic emission devices serve residential perimeter protection with 18-24 month recalibration cycles elevating total ownership cost.
- Spraying Equipment:Precision-spray apparatus with calibrated 0.5-5 milliliter dosage mechanisms targets agricultural labor scarcity in California specialty crop operations.
Today's leader: Insect Traps. Tomorrow's challenger: Electronic Baits.
Technology:
Application context determines technology selection, with regulatory pressure on active ingredients reshaping viable pathways.
- Ultrasonic:Frequency emission systems dominate residential channel distribution through home improvement retailers. EPA minimum-risk device classification avoids FIFRA registration delays for manufacturers targeting consumer segments.
- Chemical:Pheromone-based and reduced-risk pesticide delivery systems face state-level neonicotinoid restriction compression. Agricultural operations in jurisdictions with systemic insecticide bans pivot toward electromechanical alternatives.
- Biological:Biopesticide-compatible devices with documented non-chemical intervention protocols serve export-oriented agriculture facing EU maximum residue limit enforcement.
- Thermal:Heat-based repellent systems occupy mid-premium consumer positioning through farm supply retail expansion into rural residential markets.
Regulatory compression on chemical pathways advantages biological and ultrasonic deployment.
Application:
Customer procurement authority separates transactional hardware purchases from contracted integrated pest management programs.
- Commercial:Food processing and pharmaceutical facilities mandate vendor consolidation around full-service contracts bundling hardware, monitoring, and audit documentation. Midwest industrial corridor audit frequency intensification accelerates this concentration.
- Agricultural:Specialty crop growers pilot precision-spray systems for terrain-inaccessible applications, with California almond and wine grape operations leading hardware adoption.
- Residential:Homeowners procure through retail and e-commerce channels with ultrasonic repellents capturing mid-premium positioning.
- Industrial:Warehouse and logistics facilities require continuous monitoring integration with building management systems, creating proprietary API fragmentation challenges.
Service contract penetration deepest in commercial; hardware transactionalism persists in residential.
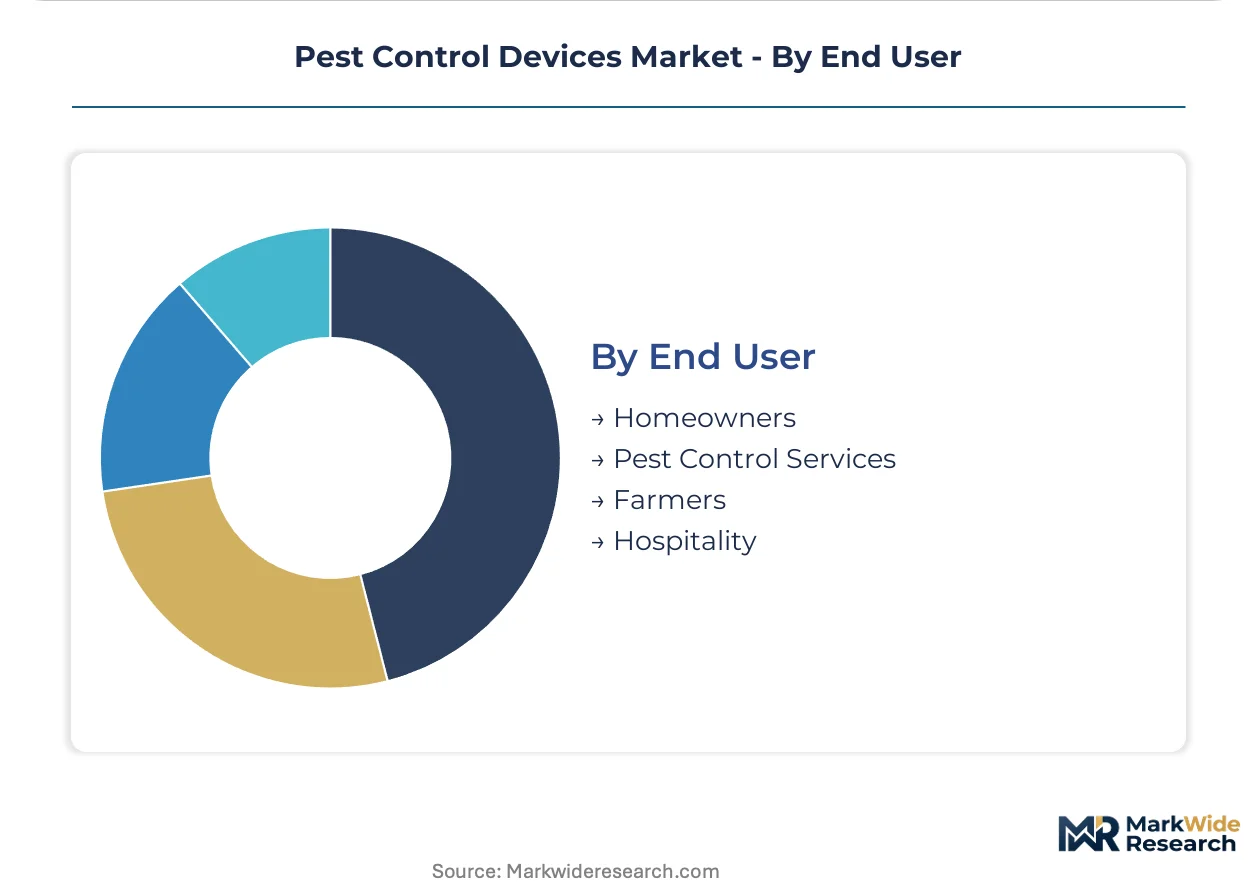
End User:
Credential requirements and procurement scale create distinct competitive dynamics across user categories.
- Pest Control Services:Technician credentialing requirements for documented intervention threshold protocols constrain field expansion velocity. Recurring revenue contracts with connected platform integration dominate competitive positioning.
- Farmers:Export market documentation requirements for non-chemical pest management drive biological method adoption in developing producer countries supplying EU markets.
- Homeowners:Price-sensitive retail procurement favors established trap manufacturing heritage brands with shelf presence dominance.
- Hospitality:Brand reputation risk from visible pest activity drives premium connected system deployment with real-time alert capabilities.
Professional service providers capture margin through platform integration; farmers face compliance-driven technology substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled pest management technicians and entomology specialists concentrate in the United States, Germany, China, Japan, and Brazil, anchoring regional device innovation and service deployment density.
United States
Commercial food processing facilities in California and Texas drive connected trap procurement for FDA audit documentation. EPA FIFRA registration pathways determine which electromechanical alternatives reach agricultural markets. The Sun Belt corridor from Florida to Arizona sustains year-round hardware replacement cycles and service contract renewals.
Germany
Precision engineering heritage supports electromechanical spray apparatus development for specialty crop applications. ECHA REACH substance restrictions compel polymer housing reformulation for export-compliant devices. Bavarian industrial clusters manufacture sensor-integrated monitoring systems for EU food safety compliance.
China
Domestic agricultural labor scarcity accelerates precision-spray electromechanical adoption in Yangtze River Delta specialty crop operations. MIIT standards for electronic device safety shape circuit board certification requirements. Shenzhen electronics manufacturing clusters supply RoHS-compliant components for export-bound ultrasonic repellent production.
Japan
Metropolitan food retail chains mandate connected monitoring for HACCP documentation in Tokyo-Osaka corridors. METI energy efficiency guidelines influence ultrasonic emitter power consumption specifications. Nagoya industrial districts fabricate compact electromechanical traps for high-density urban commercial deployment.
Brazil
Soybean and coffee export operations pivot toward biopesticide-compatible devices for EU maximum residue limit compliance. ANVISA agrochemical registration timelines extend hardware substitution decisions. São Paulo state agricultural cooperatives pilot pheromone-based monitoring systems for integrated pest management certification.
Pest Control Devices Market Competitive Landscape
Top-tier vendors anchor premium connected platforms, while mid-tier fabricators compete on mechanical trap heritage and retail channel presence. The vendor base stratifies across three tiers: multinational service integrators with recurring revenue contracts, consumer electronics specialists with home improvement distribution, and legacy trap manufacturers with century-old brand recognition. Dominant competitive moves include sensor platform acquisition for connectivity capabilities and geographic licensing partnerships for regulatory market entry.
Within the heritage manufacturing tier, Woodstream Corporation exemplifies retail shelf dominance through mass-market mechanical trap positioning. Rentokil Initial plc occupies the service-integrated vector, bundling hardware deployment with monitoring contracts. Spectrum Brands Holdings Inc represents the consumer electronics pathway, penetrating mid-premium residential segments through ultrasonic and thermal repellent distribution. These three archetypes illustrate how competitive positioning separates transactional hardware vendors from platform-integrated service providers.
| Leading Market Players |
|---|
| Woodstream Corporation |
| Bell Laboratories Inc |
| Rentokil Initial plc |
| Spectrum Brands Holdings Inc |
| Thermacell Repellents Inc |
| Bird-X Inc |
| Nixalite of America Inc |
| The Scotts Miracle-Gro Company |
| FlyBye Bird Control Products |
| Others |
Value Network & Pricing Analysis
Precision-spray electromechanical adoption in California almond and wine grape operations is compressing per-acre chemical application costs while concentrating component sourcing among RoHS-certified PCB fabricators in Shenzhen and Dongguan. This production-method transition simultaneously elevates upfront hardware expenditure and reduces recurring chemical procurement, reshaping how growers evaluate total cost of ownership against subscription-based service contracts.
Pricing Analysis
Bundled full-service contracts versus unbundled hardware transactionalism defines the pricing architecture across commercial food processing and agricultural channels. Three-tier pricing structure across premium connected platforms, standard electromechanical units, and economy mechanical traps separates Rentokil's sensor-integrated recurring revenue from Woodstream's retail shelf dominance. Price differentiation rests on FDA audit documentation capabilities and EPA FIFRA registration tier. Cost compression in mid-premium ultrasonic residential lines is intensifying because of 18-24 month recalibration cycles elevating true ownership cost. Homeowners show highest price sensitivity; pharmaceutical manufacturing facilities show lowest.
Supply Chain Analysis
Regional distribution centers in Memphis and Chicago anchor hub-and-spoke fulfillment patterns for commercial trap deployment across the Sun Belt corridor. Manufacturing concentrates in China for RoHS-compliant circuit boards, Germany for precision-spray apparatus engineering, and the United States for pheromone lure formulation. Raw material dependencies include lead-free solder alloys, UV-stabilized polymer housings, and synthetic pheromone substrates. Single-source vulnerability in East Asian PCB fabrication clusters threatens input continuity. Distribution runs through farm supply retailers, home improvement chains, and contracted service fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market derives from IoT-enabled predictive analytics reducing reactive trap deployment frequency and associated service labor intensity.
For Market Incumbents: Deploy sensor platform acquisition as the primary consolidation lever. Integrate edge computing capabilities to preempt pure-play connectivity specialists from dislodging established service relationships. Acquire pheromone synthesis capabilities to secure biopesticide-compatible supply chains against EPA registration delays for novel active ingredients. Defend against emerging ultrasonic consumer electronics specialists by locking exclusive distribution through farm supply retail networks. For New Entrants and Emerging Players: Enter via white-space targeting of developing agricultural producer countries facing EU maximum residue limit enforcement. Brazil soybean cooperatives and Southeast Asian coffee operations present penetrable demand for documented non-chemical intervention protocols. Pursue licensing partnerships with established EPA registrants to bypass 36-48 month FIFRA approval timelines. Anchor go-to-market through agricultural export cooperatives requiring compliance documentation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier mechanical trap fabricators lacking connectivity roadmaps yet possessing century-old brand recognition and retail shelf access. Long-term viability favors vendors with integrated hardware-monitoring-documentation bundles over pure hardware transactionalists. Watch for state-level neonicotinoid restriction acceleration as inflection signal compressing chemical pathway margins and accelerating electromechanical substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Platform Acquisition | Connectivity capabilities differentiate service contracts from transactional hardware in FDA-audited food processing facilities. |
| RoHS-Compliant Material Reformulation | ECHA REACH amendments compel polymer housing substitution for European market access. |
| Pheromone Synthesis Integration | Backward control over biopesticide-compatible inputs secures supply against EPA registration bottlenecks. |
| IoT-Enabled Predictive Deployment | Machine learning analytics reduce reactive service labor and elevate recurring contract margins. |
| Farm Supply Retail Expansion | Rural residential channel penetration captures underserved ultrasonic repellent demand beyond home improvement saturation. |
Research Methodology
Bottom-up commercial facility and agricultural operation modeling reconciled against top-down electromechanical device production tracking forms the analytical core of this study. Primary interviews with pest control service technicians, food safety audit coordinators, agricultural cooperative procurement managers, and polymer formulation chemists were validated against secondary sources including EPA FIFRA registration databases, ECHA REACH substance restriction amendments, FDA food safety audit protocols, and customs trade records for electromechanical apparatus imports. Triangulation between demand-side deployment data and supply-side manufacturing output ensures cross-validation.
Historical trendline analysis of connected trap adoption rates and precision-spray apparatus deployment velocity informed projection frameworks across the analysis window. Segmentation dimensions modeled include device type, technology pathway, application context, and end-user procurement authority. CAGRs were derived from installed base expansion rates and replacement cycle compression in Sun Belt markets. Forecast inputs incorporate state-level neonicotinoid restriction timelines and EU maximum residue limit enforcement intensity.
Inputs from EPA registration databases and agricultural cooperative procurement disclosures were available through the study window; gaps in real-time sensor calibration cost data introduce uncertainty bands around total cost of ownership estimates. Forecasts reflect documented intervention threshold assumptions and connectivity infrastructure penetration curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
Electronic Siren Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Functional Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Rodent Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Power Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Protective Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market