
 Security System Tester Market | 2026-2036
Security System Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Security System Tester Market Outlook
Software-defined diagnostics is hardening into a mandatory subscription layer that reshapes how security system testers monetize recurring revenue. Honeywell International Inc. leverages its building automation footprint to bundle firmware updates with hardware deployments. Siemens AG anchors its European installed base through long-term service contracts that reduce customer churn. Bosch Security Systems competes on R&D intensity, sustaining patent pipelines across wireless signal validation protocols.
A security system tester is a calibrated instrument or software platform that verifies the functional integrity of intrusion detection, access control, fire alarm, and surveillance circuits against specified voltage thresholds, response latency benchmarks, and protocol compliance matrices. Its primary commercial purpose is to certify that installed security infrastructure performs within design parameters before regulatory inspection or operational handover. The intrusion detection and fire alarm product type segments command the deepest margin pools due to mandatory recertification cycles, while cloud-based technology is displacing wired architectures in mid-scale commercial deployments where remote diagnostics reduce truck-roll costs. The government end user segment maintains the most rigid procurement standards, creating a barrier that favors established vendors with existing certification frameworks.
The US National Electrical Code and NFPA 72 standards shape product design by mandating specific signal-path verification intervals, while the EU Construction Products Regulation enforces CE-marked conformity for testers deployed in member state infrastructure projects. Germany's KBA and France's CNIL add layered compliance requirements for transportation and data-handling applications respectively. Stakeholders must monitor how fragmented national certification timelines affect go-to-market speed when introducing unified hardware platforms across multiple jurisdictions.
Market Dynamics
Cloud-based diagnostic platforms are compressing calibration cycles while NFPA 72 inspection mandates in the United States and updated German building codes force facility managers toward automated verification workflows that reduce manual labor dependence.
Growth Catalysts
- NFPA 72 Recertification Mandates:United States commercial building operators face compressed inspection intervals that accelerate tester replacement cycles and expand addressable hardware volume.
- German Building Code Acceleration:Facility managers across Germany confront shortened compliance timelines that favor integrated testing platforms over standalone instruments.
- Wireless Signal Validation Protocols:IoT-enabled intrusion detection networks require continuous circuit verification that sustains recurring diagnostic software subscriptions.
Market Restraints
- Semiconductor Component Concentration:Analog-to-digital converter supply tightens around Taiwanese foundry capacity, creating lead-time volatility for precision calibration modules.
- CE Marking Fragmentation:EU Construction Products Regulation conformity assessment diverges across notified bodies, delaying unified hardware launches by six to eighteen months.
- Manual Calibration Substitution:Low-cost handheld multimeters from industrial distributors capture price-sensitive maintenance contracts in smaller commercial buildings.
Strategic Opportunities
- India Smart City Infrastructure:Municipal surveillance and fire safety deployments under the country's urban renewal programs lack established tester supply chains.
- Healthcare Facility Convergence:Hospital access control and patient monitoring circuits merge onto unified IP networks that demand multi-protocol validation instruments.
- Subscription Diagnostic Layers:Firmware-over-the-air capabilities transform one-time hardware sales into recurring revenue streams anchored by cybersecurity patch delivery.
Industry Challenges
- Certified Technician Scarcity:NICET-certified fire alarm system technicians command wage premiums that inflate service delivery costs across North American metropolitan markets.
- Legacy Protocol Integration:Decades-old hardwired notification appliance circuits resist seamless integration with cloud-native diagnostic platforms without expensive retrofit hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security System Tester Market |
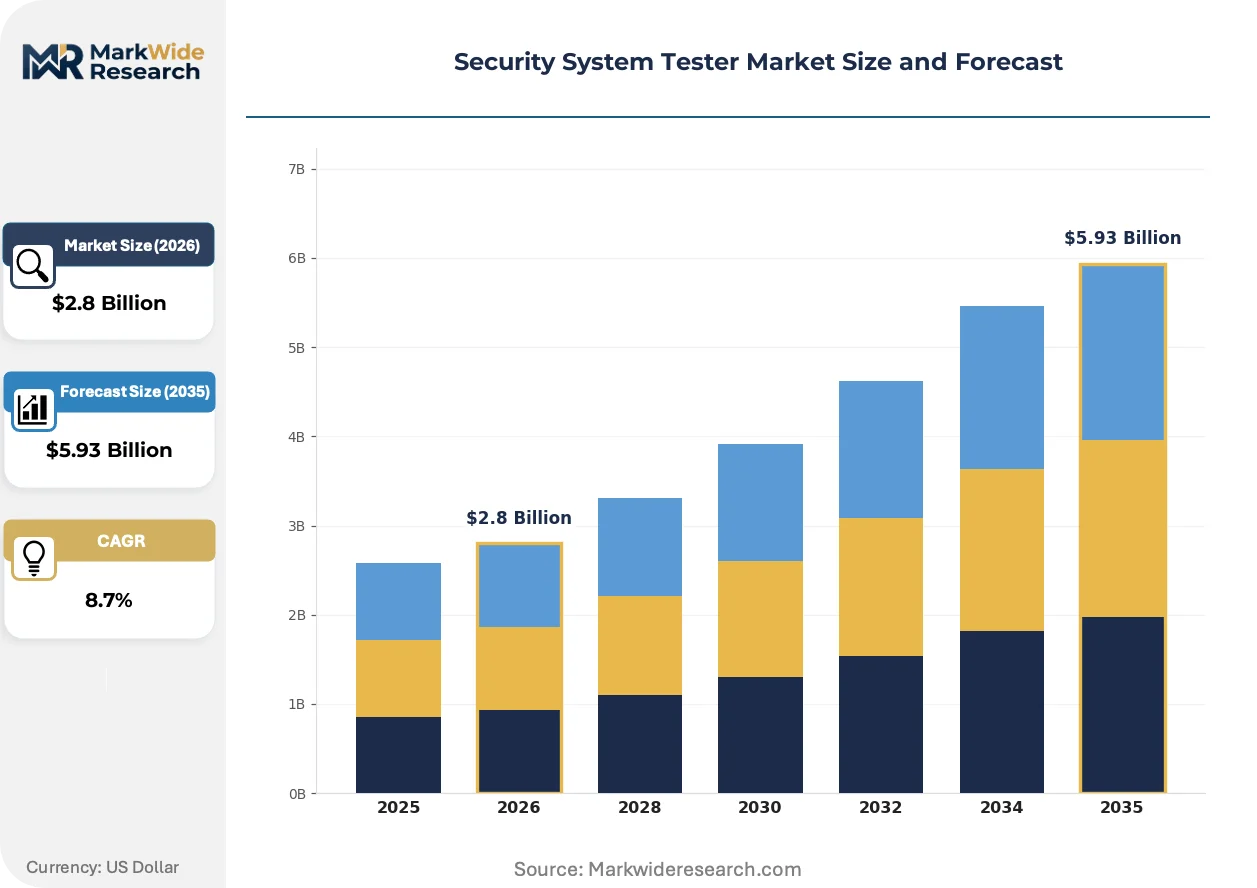
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrusion Detection, Access Control, Fire Alarm, Surveillance System End User: Residential, Commercial, Industrial, Government Technology: Wireless, Wired, Hybrid, Cloud-Based Application: Home Security, Business Security, Infrastructure Protection, Critical Systems |
| Companies Covered | Honeywell International Inc., Siemens AG, Bosch Security Systems, Johnson Controls International plc, Schneider Electric SE, United Technologies Corporation, ABB Ltd., Emerson Electric Co, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security System Tester Market Strategic Shifts
Software-defined instrumentation is collapsing the boundary between hardware calibration and predictive analytics, enabling remote circuit health monitoring that preempts regulatory failure events before inspection.
Edge-computing diagnostic nodes are electrifying security system architecture by embedding signal validation directly within sensor housings. Mid-scale commercial property managers in Western Europe adopt these distributed units fastest. The technology is electrifying traditional truck-roll service models into continuous remote monitoring subscriptions that capture margin from previously unmonitored maintenance intervals.
EU AI Act risk classification rules now capture automated threat detection algorithms within high-risk system categories. Security tester manufacturers must document training data provenance and algorithmic transparency for CE-marked products. German transportation infrastructure projects under KBA oversight face the strictest documentation burdens, slowing deployment timelines for machine-learning-enhanced diagnostic platforms.
Facility management procurement teams now unbundle hardware acquisition from long-term service contracts, forcing vendors to compete on discrete performance metrics rather than relationship lock-in. Third-party calibration laboratories in France and the Netherlands capture growing volume from this disintermediation. The shift concentrates buying power among multi-site retail and logistics operators who standardize tester fleets across national footprints.
Security System Tester Market Segmentation
Security system tester procurement patterns diverge sharply across facility types and compliance regimes. Facility managers select validation platforms based on inspection cycle frequency, circuit complexity, and whether cloud-native diagnostics can displace legacy calibration labor.
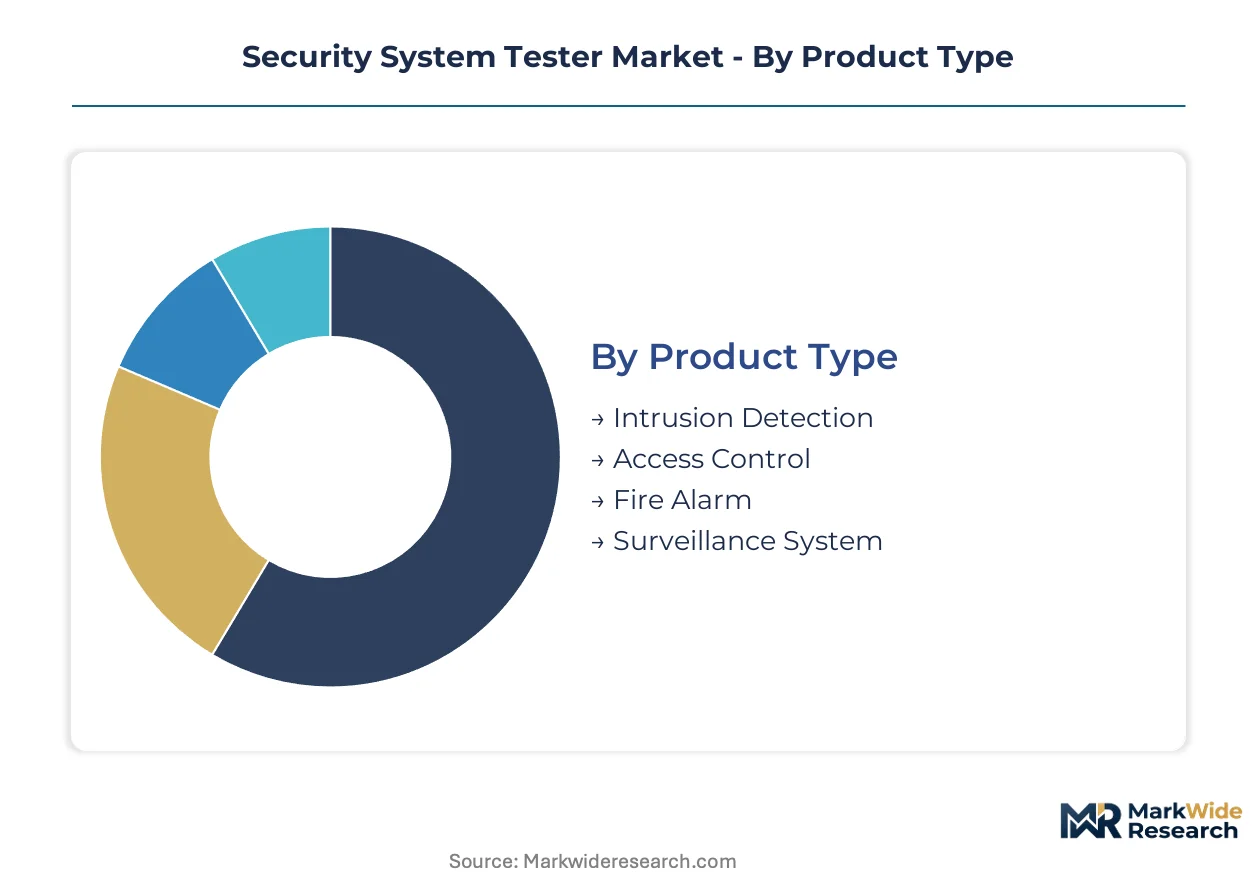
Product Type:
Margin structures align with recertification mandates rather than installation volume alone.
- Intrusion Detection:Multi-zone circuit validators verify resistance thresholds and response latency across motion sensor loops. Demand concentrates in Germany where facility managers face accelerated inspection cycles under updated building codes that compress manual testing windows.
- Fire Alarm:Addressable loop analyzers test notification appliance circuit integrity against NFPA 72 signal-path verification intervals. US commercial building operators drive replacement cycles as compressed inspection mandates expand addressable hardware volume.
- Access Control:Credential reader and door position switch testers validate Wiegand and OSDP protocol compliance.
- Surveillance System:IP camera and NVR circuit analyzers verify PoE voltage stability and bandwidth throughput.
Fire Alarm leads volumes today; Intrusion Detection is gaining share fastest.
End User:
Procurement sophistication scales with regulatory exposure and multi-site operational complexity.
- Government:Federal and municipal security infrastructure demands NICET-certified validation with documented chain-of-custody protocols. US defense and transportation facilities maintain rigid procurement standards that favor established vendors with existing certification frameworks.
- Commercial:Retail, logistics, and office property managers standardize tester fleets across national footprints. Western European facility management teams unbundle hardware acquisition from service contracts fastest.
- Industrial:Manufacturing and warehouse operators prioritize ruggedized instruments for high-electromagnetic-interference environments.
- Residential:Smart home integrators specify compact wireless validators for single-family and multi-tenant deployments.
Commercial captures the deepest revenue pool; Government maintains the stickiest vendor relationships.
Technology:
Architecture choices determine whether diagnostics remain on-premises or migrate to subscription-based remote monitoring.
- Cloud-Based:Firmware-over-the-air platforms embed predictive analytics that preempt regulatory failure events before inspection. Mid-scale commercial property managers in Western Europe adopt these fastest where remote diagnostics reduce truck-roll costs.
- Wireless:IoT-enabled validation nodes sustain recurring software subscriptions through continuous circuit verification. Signal validation protocols for intrusion detection networks command premium pricing.
- Hybrid:Edge-computing nodes combine local processing with cloud synchronization for bandwidth-constrained sites.
- Wired:Legacy handheld units persist in price-sensitive maintenance contracts and facilities with air-gapped security requirements.
Wired architectures dominate installed base; Cloud-Based climbs the fastest.
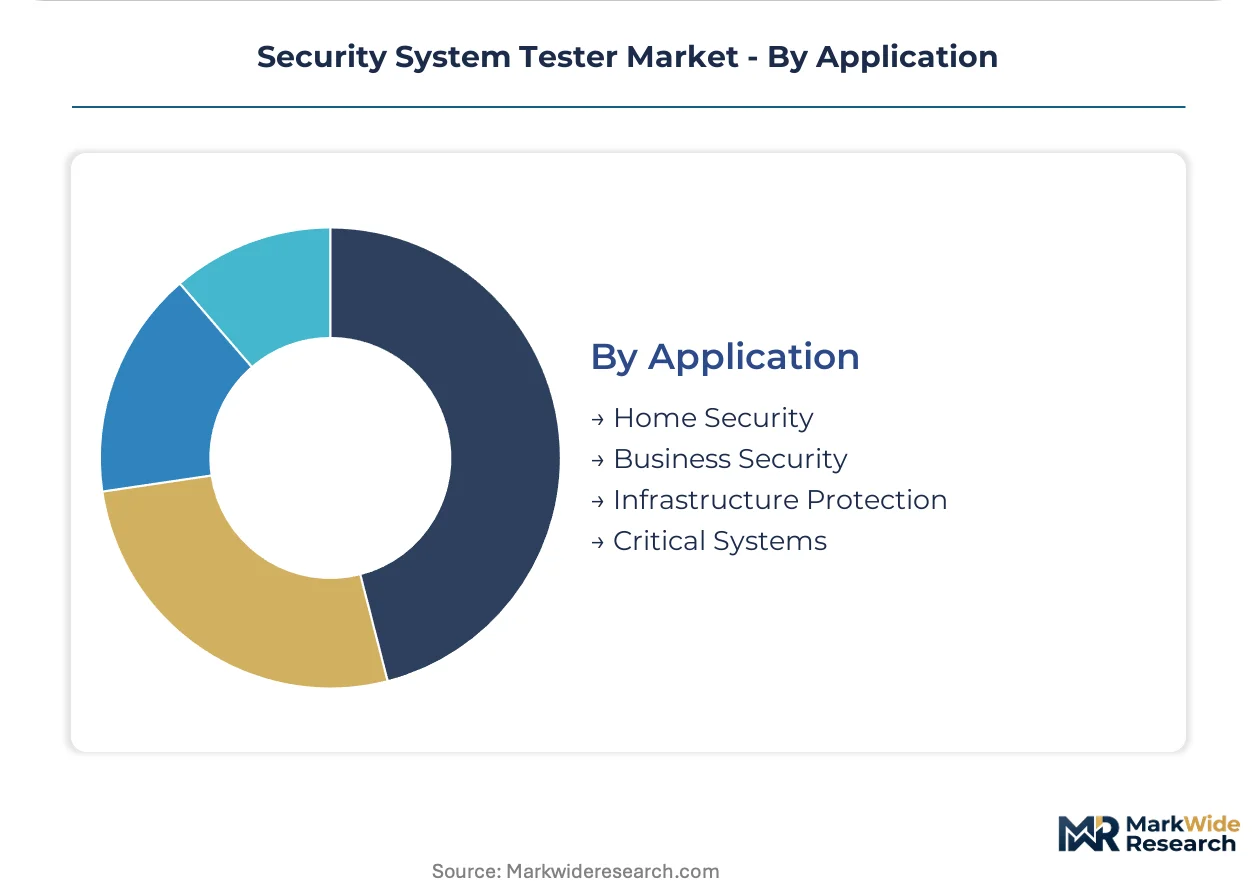
Application:
Use case severity dictates whether testers require multi-protocol capability or single-function specialization.
- Critical Systems:Data centers, power plants, and healthcare facilities demand multi-protocol instruments that validate access control, fire alarm, and surveillance circuits on unified IP networks. Hospital convergence of patient monitoring and security infrastructure drives specification complexity.
- Infrastructure Protection:Transportation hubs and utility substations require KBA-compliant documentation for German deployments and hardened environmental specifications.
- Business Security:Corporate campuses and retail chains prioritize fleet standardization across dispersed locations.
- Home Security:Residential integrators favor smartphone-integrated validators for consumer-facing installation services.
Business Security leads unit shipments; Critical Systems commands the highest average selling prices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany compresses inspection cycles faster than the United States, while India accelerates smart city deployments without established tester supply chains. Facility managers in Western Europe unbundle hardware from service contracts fastest. Cloud-based diagnostics reduce truck-roll costs across mid-scale commercial portfolios.
United States
Commercial building operators face compressed NFPA 72 inspection intervals that accelerate hardware replacement cycles. The National Electrical Code mandates specific signal-path verification intervals that shape product design. Metropolitan clusters in Texas and California concentrate demand from multi-site retail and logistics operators standardizing tester fleets.
Germany
Facility managers confront shortened compliance timelines under updated building codes that favor integrated testing platforms. KBA oversight of transportation infrastructure projects imposes strict documentation burdens on machine-learning-enhanced diagnostic platforms. Industrial concentration in Bavaria and North Rhine-Westphalia drives specification complexity for unified IP network validation.
India
Municipal surveillance and fire safety deployments under urban renewal programs lack established tester supply chains. BIS standards for construction products create conformity assessment requirements for imported hardware. Metropolitan clusters in Maharashtra and Karnataka concentrate procurement from smart city infrastructure projects.
United Kingdom
Commercial property managers standardize tester fleets across national footprints amid procurement team unbundling of hardware from service contracts. Building regulations enforce specific inspection intervals for fire alarm systems in multi-tenant developments. London and Southeast England concentrate demand from corporate campus and retail chain operators.
Japan
Facility management teams adopt edge-computing diagnostic nodes for bandwidth-constrained sites in dense urban environments. METI standards for building automation systems influence specification requirements for multi-protocol validation instruments. Industrial clusters in Kanto and Kansai regions drive demand from manufacturing and warehouse operators prioritizing ruggedized instruments.
Security System Tester Market Competitive Environment
Top-tier vendors anchor premium-tier positioning, while mid-scale specialists occupy price-sensitive maintenance contract segments. The vendor base stratifies across building automation conglomerates, industrial electronics manufacturers, and software-defined diagnostic platforms. Three archetypes dominate: automation-integrated hardware bundlers, long-term service contract anchors, and R&D-intensive protocol specialists. Consolidation through strategic partnerships and firmware-over-the-air capability expansion shapes competitive moves.
Within the automation-integrated tier, Honeywell International Inc. and Siemens AG exemplify divergent geographic anchoring strategies. Honeywell leverages North American building automation footprints through bundled firmware update deployments. Siemens anchors European installed bases through long-term service contract structures. Bosch Security Systems occupies a position within the R&D-intensive archetype, sustaining patent pipelines that represent competitive differentiation in wireless signal validation protocols. Johnson Controls International plc and Schneider Electric SE sit within the industrial-electronics segment, reflecting scale-driven positioning across facility management procurement channels.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Bosch Security Systems |
| Johnson Controls International plc |
| Schneider Electric SE |
| United Technologies Corporation |
| ABB Ltd. |
| Emerson Electric Co |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Multi-site commercial property managers concentrate procurement power through fleet standardization mandates that favor subscription-based diagnostic platforms over transactional hardware sales. This buyer archetype consolidation compresses margin capture for standalone instrument vendors while rewarding integrated platform providers with recurring revenue visibility.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for precision calibration modules as foundry capacity constraints ease. Three-tier pricing structure across premium, standard, and economy levels separates NICET-certified validation suites from entry-level handheld units. Cost compression in the economy tier intensifies because industrial distributors source low-cost multimeters from unbranded Asian manufacturers. Government procurement programs exhibit the lowest price sensitivity due to mandated certification documentation, while residential integrators face acute margin pressure from smartphone-integrated alternatives.
Supply Chain Analysis
CE marking requirements and NFPA 72 compliance documentation gate market access for non-certified manufacturers, creating qualification barriers that protect incumbent margin structures. Component sourcing concentrates in Taiwan for analog-to-digital converters, Germany for precision sensor modules, and China for enclosure fabrication. Raw material dependencies span semiconductor wafers, lithium battery cells, and flame-retardant polymers. Single-source vulnerability around Taiwanese foundry capacity for precision ADCs threatens delivery continuity for calibration-intensive product lines. Distribution runs through industrial electronics distributors in North America and specialized security integrators in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Security system tester margins expand through firmware-over-the-air capabilities that transform capital equipment sales into recurring diagnostic subscriptions. Cloud-native platforms capture premium pricing by preempting regulatory failure events through predictive analytics.
For Market Incumbents: Lock in European installed bases through long-term service contract extensions that reduce customer churn to emerging software-defined diagnostic platforms. Deepen backward integration into precision ADC supply by qualifying secondary foundry sources in South Korea. Defend against unbundling pressure from third-party calibration laboratories by embedding proprietary analytics that require authenticated hardware pairing.
For New Entrants and Emerging Players: Begin with India's smart city infrastructure deployments where municipal surveillance programs lack established tester supply chains and BIS conformity assessment creates qualification runway for patient capital. Target mid-scale commercial property managers in Western Europe who prioritize remote diagnostics over legacy truck-roll service models. Pursue channel partnerships with industrial electronics distributors rather than direct sales investments.
For Investors and Strategic Acquirers: Building automation conglomerates represent the most active acquirer category in this space as they seek firmware-over-the-air capabilities to bundle with existing hardware footprints. Long-term viability hinges on subscription revenue attachment rates exceeding hardware replacement cycles. Monitor NICET technician wage inflation as an inflection indicator for automated verification platform adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Over-The-Air Platform Launch | Transforms Honeywell and Siemens hardware deployments into recurring revenue streams through cybersecurity patch delivery. |
| CE Marking Acceleration Program | Reduces six-to-eighteen month conformity assessment delays that fragment unified hardware launches across EU member states. |
| Indian Smart City Channel Partnership | Establishes supply chain presence ahead of Maharashtra and Karnataka municipal surveillance procurement waves. |
| NICET Certification Training Investment | Addresses technician scarcity that inflates service delivery costs across North American metropolitan markets. |
| Edge-Computing Diagnostic Node Development | Captures Western European mid-scale commercial demand for bandwidth-constrained site monitoring without cloud dependency. |
Study Parameters
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region synthesized through structured stakeholder engagement. Facility management procurement directors, fire alarm system technicians, industrial electronics distributors, and cloud platform engineering leads provided operational perspective. Secondary validation drew from NFPA 72 technical documentation, EU Construction Products Regulation filings, BIS construction product standards, and SEC disclosures from building automation conglomerates. Bottom-up tester shipment modeling triangulated against top-down facility construction and regulatory inspection cycle data.
Granularity-level modeling captured product type, end user, technology architecture, and application severity dimensions at the country level for the United States, Germany, India, United Kingdom, and Japan. Deployment model segmentation separated cloud-native, wireless, hybrid, and wired architectures to isolate subscription revenue trajectories. CAGRs derived from regression analysis against inspection interval compression rates and smart city infrastructure investment announcements. Forecast inputs incorporated foundry capacity utilization projections and NICET certification program enrollment trends.
Several conditions sit outside the modeled scope, including potential harmonization of EU notified body conformity assessment timelines and breakthrough advances in passive sensor self-calibration. Forecasts reflect assumptions about sustained NFPA 72 mandate enforcement and continued KBA documentation burdens for German transportation infrastructure. A model refresh is warranted upon material change in analog-to-digital converter foundry capacity allocation or substantial relaxation of BIS import conformity requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
North America Self-Contained Breathing Apparatus Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Africa Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Smart PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Combat Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Booster Seat Type Child Safety Seats Market
Safety Equipment and Personal Protective Equipment (PPE)
Panic Exit Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Latin America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Guards Market