
 AI Surveillance Camera Market | 2026-2036
AI Surveillance Camera Market Size, Share, and Industry Trends Forecast 2026-2036
AI Surveillance Camera Market Outlook
Silicon carbide-based edge processors is expanding thermal camera capabilities while lowering power consumption for continuous outdoor deployment. Hangzhou Hikvision Digital Technology Co., Ltd. leverages in-house semiconductor design to control component costs across its dome and bullet camera lines. Dahua Technology Co., Ltd. sustains manufacturing scale through vertically integrated production facilities in Zhejiang province. Axis Communications AB differentiates through open-platform architecture that integrates third-party video analytics software.
AI surveillance cameras combine optical sensors with onboard neural processing units to execute real-time facial recognition, object detection, and behavioral analysis without cloud dependency, typically operating at 30-60 frames per second with latency below 50 milliseconds for security-critical applications. Dome cameras and bullet cameras occupy the volume core as standardized form factors for retail chains and educational institutions, while thermal cameras command premium positioning in perimeter defense and critical infrastructure. Facial recognition and video analytics represent the fastest-expanding technology layers as government agencies mandate automated threat detection in transportation hubs and public squares.
FCC certification requirements in the United States and ETSI cybersecurity standards in Europe constrain market access for manufacturers lacking encryption and data governance capabilities, while GDPR in Europe directly limits facial recognition deployment in public spaces without explicit consent frameworks. China's GB standards and network security regulations shape domestic procurement criteria for government agency installations. Stakeholders must monitor evolving biometric privacy legislation across multiple jurisdictions to anticipate product feature roadmaps and geographic deployment restrictions.
Market Dynamics
Edge AI chip integration is compressing cloud dependency costs while municipal governments accelerate facial recognition procurement for smart city infrastructure, creating a bifurcation between on-device processing leaders and cloud-reliant laggards.
Growth Catalysts
- GB Standards Compliance:China's network security regulations and domestic procurement criteria mandate AI-enabled surveillance for government agency installations, creating captive demand for compliant manufacturers.
- Silicon Carbide Edge Processors:Thermal camera capabilities are expanding through wide-bandgap semiconductor integration, enabling continuous outdoor deployment with reduced power draw for perimeter defense applications.
- Transportation Hub Mandates:Government agencies across multiple jurisdictions require automated threat detection in public squares and transit terminals, accelerating facial recognition layer adoption.
Market Restraints
- GDPR Facial Recognition Limits:Europe's explicit consent frameworks directly constrain public space deployment, forcing feature roadmaps to exclude biometric capture in EU municipal contracts.
- ETSI Cybersecurity Certification:European encryption and data governance standards block market access for manufacturers lacking certified firmware architectures, creating a compliance moat.
- FCC Hardware Certification:United States radio frequency and electromagnetic interference testing adds six-to-nine month lead times for non-domestic suppliers seeking federal installation eligibility.
Strategic Opportunities
- India Public Safety Networks:Critical infrastructure monitoring expansion and urban safety initiatives create underpenetrated procurement channels for thermal and bullet camera form factors.
- Open-Platform Analytics Convergence:Third-party video analytics software integration with neural processing units enables solution bundling beyond hardware margins.
- Behavioral Analysis Layer:Real-time anomaly detection for educational institutions and retail chains represents an emerging application with limited incumbent specialization.
Industry Challenges
- Neural Processing Unit Talent Scarcity:On-chip AI accelerator design requires specialized embedded systems engineers, with competition intensifying from automotive and consumer electronics sectors.
- Legacy Analog Infrastructure Integration:Municipal retrofit projects demand hybrid architectures bridging coaxial cable networks with IP-based AI cameras, complicating deployment timelines.
- Biometric Privacy Litigation Exposure:Multi-jurisdictional consent framework variations create compliance engineering overhead and product liability risk for facial recognition-enabled systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Surveillance Camera Market |
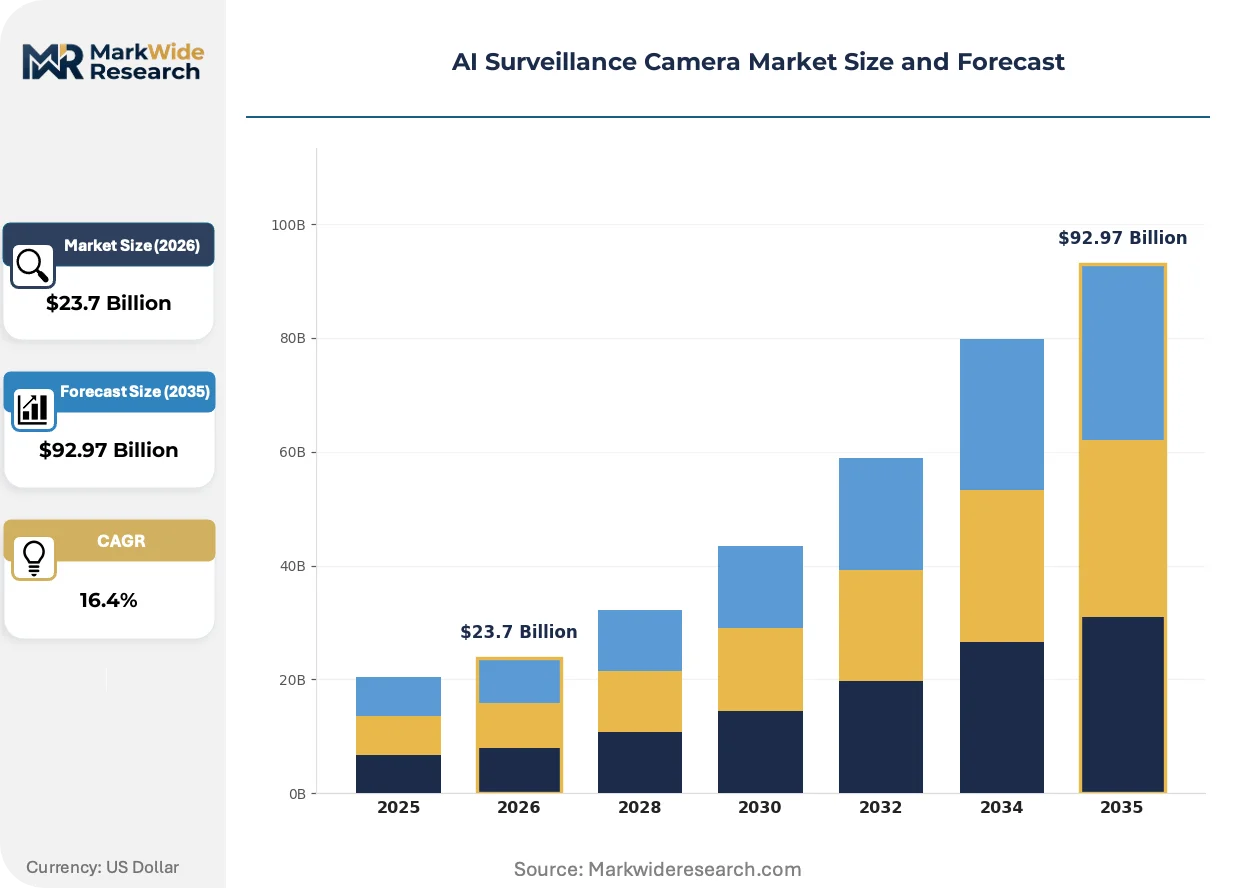
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $92.97 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Cameras, Bullet Cameras, PTZ Cameras, Thermal Cameras Technology: Facial Recognition, Object Detection, Video Analytics, Night Vision Installation Type: Indoor Cameras, Outdoor Cameras, Wall-Mounted Cameras, Ceiling-Mounted Cameras End User: Retail Chains, Healthcare Facilities, Educational Institutions, Government Agencies |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Axis Communications AB, Bosch Security and Safety Systems GmbH, Honeywell International Inc., Hanwha Vision Co., Ltd., Milestone Systems A/S, Genetec Inc., Motorola Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Surveillance Camera Market Strategic Shifts
Neural processing unit architectures are fragmenting into specialized inference engines, while regulatory fragmentation across biometric privacy regimes forces parallel product line development. Procurement criteria are hardening around cybersecurity certification and supply chain provenance.
Edge AI inference engines are modularizing into discrete neural processing units with dedicated tensor cores for facial recognition and object detection workloads. Retail chains and educational institutions are standardizing on 30-60 frames per second on-device processing to eliminate cloud latency for security-critical applications. This modularization is compressing the premium commanded by integrated hardware-software bundles, forcing analytics vendors toward standalone software licensing.
GDPR's explicit consent requirements for biometric data capture are reshaping European product specifications, with manufacturers deploying privacy-by-design architectures that process facial templates without persistent storage. The EU AI Act's risk classification system for biometric identification in public spaces is accelerating compliance engineering investments. Transportation hubs and municipal governments in France and Germany are now requiring algorithmic impact assessments as standard procurement documentation.
Outcome-based service contracts are displacing capital expenditure procurement in large-scale municipal deployments, with cities in India and the United States negotiating performance-linked payments for threat detection accuracy. System integrators are capturing recurring revenue streams through managed video analytics services. This shift is most visible in smart city infrastructure projects where operational technology budgets supersede traditional security capital allocations.
AI Surveillance Camera Market Segmentation
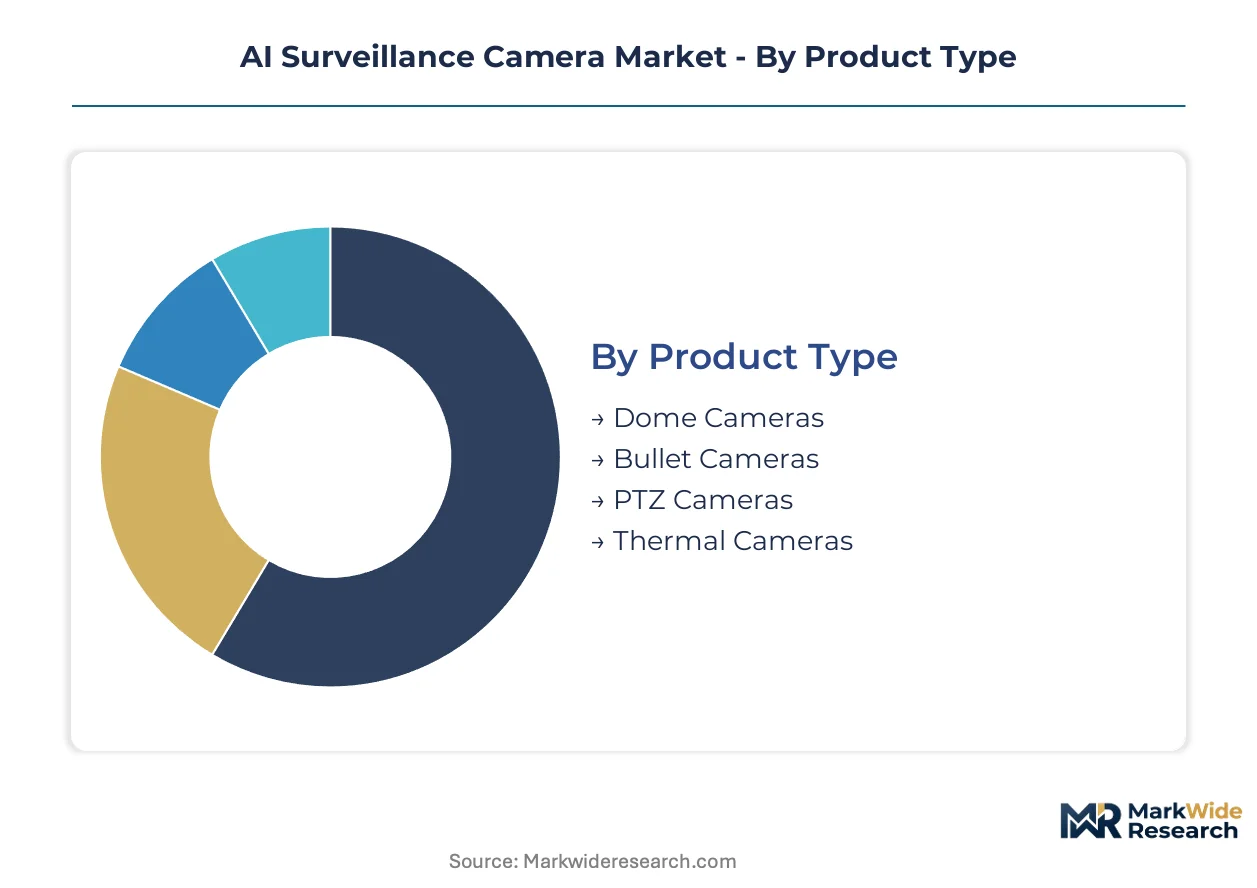
Form factor specifications, processing capabilities, and deployment environments create distinct procurement workflows for municipal buyers and enterprise security teams. Procurement committees evaluate thermal resilience, neural processing latency, and regulatory compliance across divergent installation scenarios.
Product Type:
Buyers prioritize environmental durability and optical coverage range when selecting housing configurations for continuous outdoor operation.
- Dome Cameras:Vandal-resistant hemispherical housings enclose varifocal lenses for 360-degree coverage in retail chains and educational institutions. Demand concentrates in China and India where educational facility upgrades prioritize discrete ceiling-mounted surveillance with edge AI processing at 30-60 frames per second.
- Bullet Cameras:Cylindrical weather-sealed enclosures mount on exterior walls for perimeter defense with extended infrared range. Government agencies in the United States specify these for critical infrastructure monitoring where FCC-certified radio modules ensure federal installation eligibility.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms enable operator-directed tracking across wide areas.
- Thermal Cameras:Uncooled microbolometer sensors detect heat signatures through darkness, smoke, and foliage for perimeter applications.
Dome cameras lead on scale; thermal cameras lead on momentum.
Technology:
Processing workload distribution between edge and cloud architectures determines total cost of ownership for large-scale deployments.
- Facial Recognition:Onboard neural processing units execute real-time biometric template matching with sub-50-millisecond latency for security-critical applications. Transportation hubs in China mandate this layer for automated threat detection in public squares, though GDPR constraints block equivalent deployment in France and Germany without explicit consent frameworks.
- Object Detection:Convolutional neural networks classify vehicles, weapons, and abandoned packages without biometric privacy exposure. Retail chains in India deploy this capability for loss prevention where behavioral analysis algorithms flag suspicious activity patterns.
- Video Analytics:Rule-based and machine-learning algorithms aggregate metadata for forensic search and operational intelligence.
- Night Vision:Near-infrared illuminators and starlight sensors extend operational hours for continuous monitoring.
Object detection leads on scale; facial recognition leads on momentum.
Installation Type:
Environmental sealing ratings and mounting hardware specifications drive replacement cycles for legacy analog infrastructure.
- Outdoor Cameras:IP67-rated enclosures withstand temperature extremes and precipitation for perimeter defense and critical infrastructure. Demand concentrates in the United States where municipal governments retrofit smart city infrastructure with weather-hardened edge AI systems.
- Indoor Cameras:Compact form factors with lower ingress protection prioritize acoustic concealment and aesthetic integration. Healthcare facilities in China specify these for patient monitoring corridors where GB standards compliance ensures government procurement eligibility.
- Wall-Mounted Cameras:Bracket assemblies position lenses for corridor coverage and entry point monitoring.
- Ceiling-Mounted Cameras:Recessed and surface-mount configurations maximize field of view in open-plan spaces.
Outdoor cameras lead on scale; indoor cameras lead on momentum.
End User:
Budget authority and regulatory exposure shape feature roadmaps across public and private procurement channels.
- Government Agencies:Municipal, transportation, and defense buyers mandate cybersecurity certification, supply chain provenance, and algorithmic impact assessments. Procurement in France and Germany now requires EU AI Act compliance documentation for biometric identification in public spaces.
- Retail Chains:Loss prevention and customer analytics teams prioritize open-platform architectures that integrate third-party video analytics software. Deployment concentrates in India where urban safety initiatives accelerate procurement of thermal and bullet camera form factors.
- Healthcare Facilities:Patient privacy regulations constrain recording capabilities while requiring continuous monitoring for safety.
- Educational Institutions:Campus security departments balance threat detection with student privacy protections.
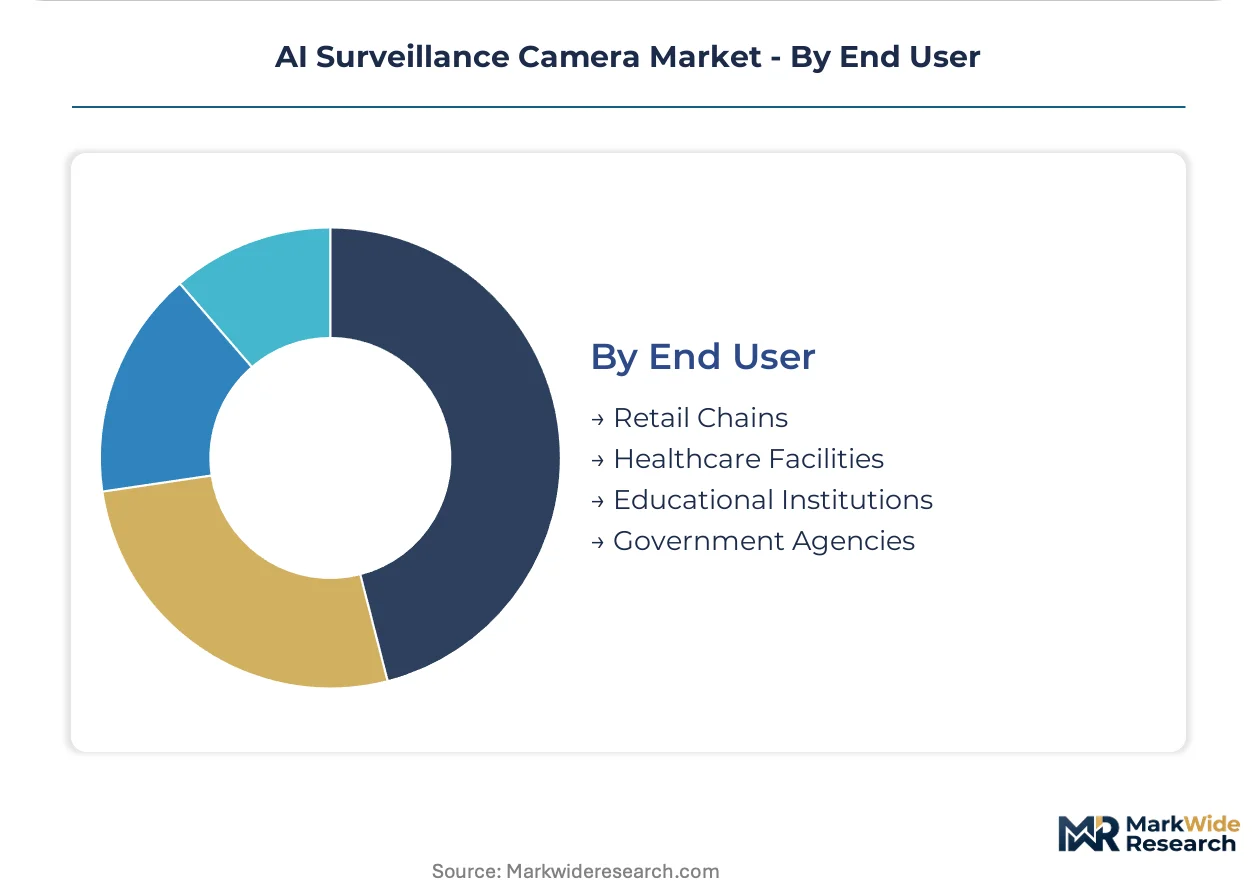
Government agencies lead on scale; retail chains lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hangzhou anchors the world's densest concentration of AI surveillance camera manufacturing, with municipal procurement in China, the United States, and India collectively driving two-thirds of installed base expansion through 2035.
China
Smart city infrastructure projects in Hangzhou, Shenzhen, and Beijing accelerate municipal procurement of facial recognition-enabled systems for public squares and transportation hubs. GB standards compliance and network security regulations under MIIT mandate domestic sourcing for government agency installations. The Yangtze River Delta cluster houses vertically integrated production facilities controlling component costs across dome and bullet camera lines.
United States
Critical infrastructure monitoring and federal installation eligibility requirements concentrate demand in Texas, California, and the Northeast Corridor. FCC certification adds six-to-nine month lead times for radio frequency and electromagnetic interference testing, constraining market access for non-domestic suppliers. Chicago and New York City municipal governments retrofit legacy analog networks with weather-hardened edge AI systems for perimeter defense.
India
Urban safety initiatives and public safety network expansion create procurement channels for thermal and bullet camera form factors in Maharashtra, Karnataka, and Delhi-NCR. BIS certification requirements shape product specifications for educational facility upgrades and retail chain loss prevention deployments. Mumbai and Bangalore educational institutions prioritize discrete ceiling-mounted surveillance with edge AI processing at 30-60 frames per second.
Germany
ETSI cybersecurity standards and GDPR explicit consent frameworks constrain facial recognition deployment in public spaces without algorithmic impact assessments. The EU AI Act's risk classification system accelerates compliance engineering investments in Bavaria and North Rhine-Westphalia. Frankfurt and Munich transportation hubs now require privacy-by-design architectures that process facial templates without persistent storage.
United Kingdom
London and Southeast England municipal governments balance threat detection mandates with student privacy protections in educational institutions. The Information Commissioner's Office enforces biometric data capture limitations that reshape product specifications for campus security departments. Birmingham and Manchester retail chains deploy open-platform architectures integrating third-party video analytics software for customer analytics and loss prevention.
AI Surveillance Camera Market Competitive Environment
Global majors compete with regional champions across cybersecurity certification and supply chain provenance, creating tiered procurement access where FCC-certified and ETSI-compliant vendors capture federal and EU municipal contracts. The vendor base stratifies between integrated hardware-software bundles and standalone component suppliers. Three archetypes dominate: vertically integrated Chinese manufacturers with captive semiconductor design, European open-platform specialists, and North American system integrators. Competitive moves concentrate on strategic partnerships with municipal system integrators and geographic expansion through localized certification compliance.
Within the vertically integrated tier, Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. represent Chinese manufacturing scale with in-house component cost control. Axis Communications AB exemplifies the European open-platform archetype. These three occupy positions across divergent regulatory compliance vectors—GB standards, FCC certification, and ETSI cybersecurity standards—forcing parallel product line development to capture procurement in China, the United States, and Germany respectively.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Axis Communications AB |
| Bosch Security and Safety Systems GmbH |
| Honeywell International Inc. |
| Hanwha Vision Co., Ltd. |
| Milestone Systems A/S |
| Genetec Inc. |
| Motorola Solutions, Inc. |
| Others |
Value Chain & Pricing Dynamics
Municipal government procurement committees in China, the United States, and India command the dominant share of volume purchases, compressing hardware margins through competitive tendering while favoring suppliers with captive semiconductor design and vertically integrated production facilities.
Pricing Analysis
Silicon wafer and edge AI processor costs pass through directly to dome and bullet camera ASPs, with three-tier pricing structure across premium, standard, and economy levels separating FCC-certified federal contractors from uncertified regional vendors. Price differentiation hinges on cybersecurity certification tier and geographic delivery logistics, with ETSI-compliant firmware architectures commanding substantial premiums in EU municipal contracts. Pricing pressure stems from Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. leveraging in-house component production to undercut modular competitors. Retail chains in India exhibit the highest price sensitivity, while government agencies in the United States prioritize certification compliance over unit cost.
Supply Chain Analysis
Embedded systems engineers with neural processing unit design expertise concentrate in the Yangtze River Delta, Shenzhen, and Bangalore, constraining capacity expansion for thermal camera manufacturers seeking continuous outdoor deployment capabilities. Supply chains draw from Taiwan for advanced node semiconductors, Japan for optical sensors, and domestic Chinese foundries for mature edge AI chips. Single-source vulnerability in silicon carbide substrate supply creates exposure for wide-bandgap thermal camera production. Distribution runs through municipal system integrators in smart city infrastructure projects, with outcome-based service contracts displacing direct hardware procurement in large-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
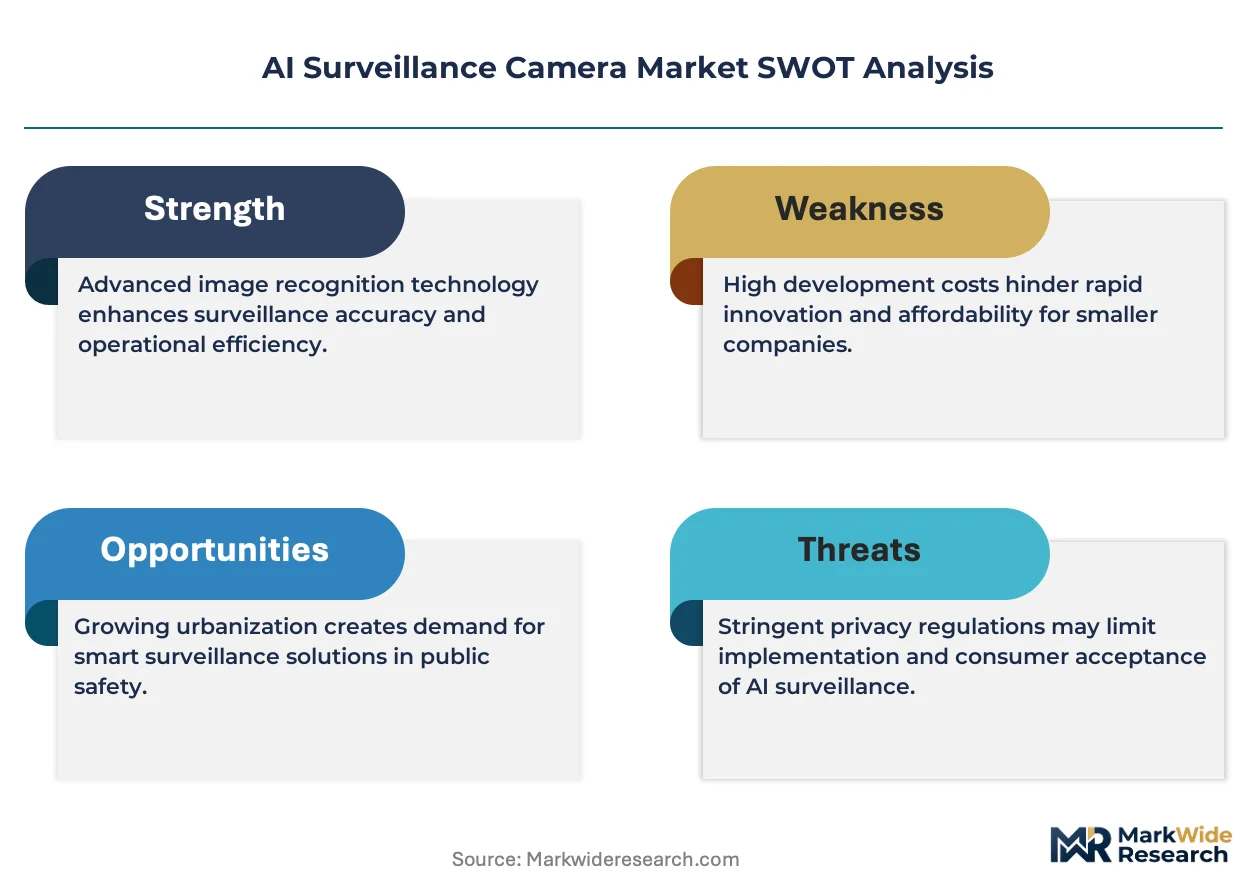
The AI surveillance camera market functions as a stable compounder, with smart city infrastructure mandates across municipal governments providing recurring procurement visibility that dampens demand volatility.
For Market Incumbents: Anticipate margin compression from open-platform analytics convergence by deepening software licensing revenue streams and securing exclusive municipal system integrator partnerships. Defend against neural processing unit talent scarcity by anchoring R&D facilities in Bangalore and Shenzhen where embedded systems engineering pipelines remain deepest. Prioritize parallel certification tracks for FCC, ETSI, and GB standards to capture procurement across all three demand centers without product line fragmentation. For New Entrants and Emerging Players: Launch via outcome-based managed video analytics services rather than hardware-centric models, targeting educational institutions in India where BIS certification requirements remain less stringent than government agency tiers. White-space opportunities concentrate in behavioral analysis layers for retail loss prevention and acoustic concealment-optimized indoor cameras for healthcare corridors. Bypass incumbent strongholds by bundling third-party video analytics software with commodity dome camera hardware sourced from Zhejiang province contract manufacturers. For Investors and Strategic Acquirers: System integrators with municipal smart city infrastructure relationships are the most active acquirer in this space, consolidating video analytics capabilities to capture recurring managed services revenue. Long-term viability centers on vendors with demonstrated compliance engineering across GDPR, EU AI Act, and FCC regulatory vectors. Monitor algorithmic impact assessment requirements in France and Germany as the inflection signal for biometric identification deployment permissibility.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | ETSI and FCC compliance unlocks federal and EU municipal procurement channels. |
| Edge AI Processor Integration | Silicon carbide-based designs reduce power draw for continuous outdoor thermal deployment. |
| Outcome-Based Service Contracts | Performance-linked payments displace capex procurement in India and United States cities. |
| Open-Platform Analytics Partnership | Third-party software bundling escapes hardware margin compression from Chinese vertically integrated manufacturers. |
| Neural Processing Unit Talent Acquisition | Embedded systems engineers in Bangalore and Shenzhen anchor R&D scalability for on-chip AI accelerators. |
Study Parameters
Coverage spans China, the United States, India, Germany, and the United Kingdom, with primary inputs from each combining interviews with municipal procurement officers, system integrator technical directors, edge AI semiconductor engineers, and cybersecurity compliance consultants. Secondary validation draws from FCC equipment authorization databases, ETSI cybersecurity standards documentation, MIIT GB standards filings, and municipal smart city infrastructure tender records. Bottom-up unit shipment estimates triangulate against top-down procurement budget analysis across transportation hubs and educational institutions.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon, with analytical frameworks modeling form factor specifications, processing capability tiers, installation environment ratings, and end-user regulatory exposure as core segmentation dimensions. CAGRs derive from fitted adoption curves calibrated to municipal budget cycle timing and infrastructure replacement wave patterns. Forecast inputs incorporate edge AI chip cost compression trajectories and evolving biometric privacy legislation enforcement intensity across jurisdictions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt GDPR enforcement escalation or sudden export control restrictions on wide-bandgap semiconductors. Forecasts reflect assumptions regarding continued municipal smart city infrastructure commitment and stable neural processing unit talent availability in Yangtze River Delta manufacturing clusters. Material deviation in EU AI Act risk classification implementation or FCC certification timeline extensions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Brazil Video Surveillance Market
Video Surveillance Systems
Global Mobile Video Surveillance Market
Video Surveillance Systems
Night Vision Camera Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
Latin America Video Surveillance Storage Market
Video Surveillance Systems
Latin America Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Storage Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
Middle East and Africa Surveillance Analog Camera Market
Video Surveillance Systems
Cellular Interception Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
Europe Video Surveillance Storage Market