
 Combat Helmet Market | 2026-2036
Combat Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
Combat Helmet Market Analysis
Military procurement channels is rewriting how combat helmet contracts flow from defense ministries to prime contractors. Gentex Corporation leverages its long-standing relationship with the U.S. Department of Defense to sustain preferred supplier status across multiple helmet programs. BAE Systems anchors European demand through its position on the British Army's Virtus soldier system. MKU Limited competes aggressively in emerging markets with cost-optimized ballistic solutions manufactured at its India facility.
A combat helmet is a personal protective equipment item engineered to absorb kinetic energy from ballistic projectiles, fragmentation, and blunt impact, typically constructed from layered aramid fibers, UHMWPE composites, or hybrid matrices and rated against specific threat levels under NIJ or STANAG protocols. Its primary purpose is to reduce traumatic brain injury incidence while serving as a mounting platform for night vision devices, communication headsets, and situational awareness systems. Ballistic helmets dominate value capture given their complex certification requirements and higher unit economics, while tactical helmets with modular rail systems represent the fastest-growing configuration as end users prioritize accessory integration. Carbon fiber and UHMWPE material segments are displacing traditional Kevlar in next-generation programs where weight reduction directly correlates with operator endurance and cognitive performance.
The U.S. Army's Program Executive Office Soldier, NIJ, and NATO's STANAG 2920 framework collectively shape product standards, testing protocols, and market access conditions for helmet manufacturers seeking defense contracts. The EU's REACH regulation and emerging restrictions on hazardous substances in protective equipment are forcing material substitutions across European supply chains. Stakeholders must monitor how dual-use export controls and evolving ballistic threat specifications reshape sourcing strategies and qualification timelines.
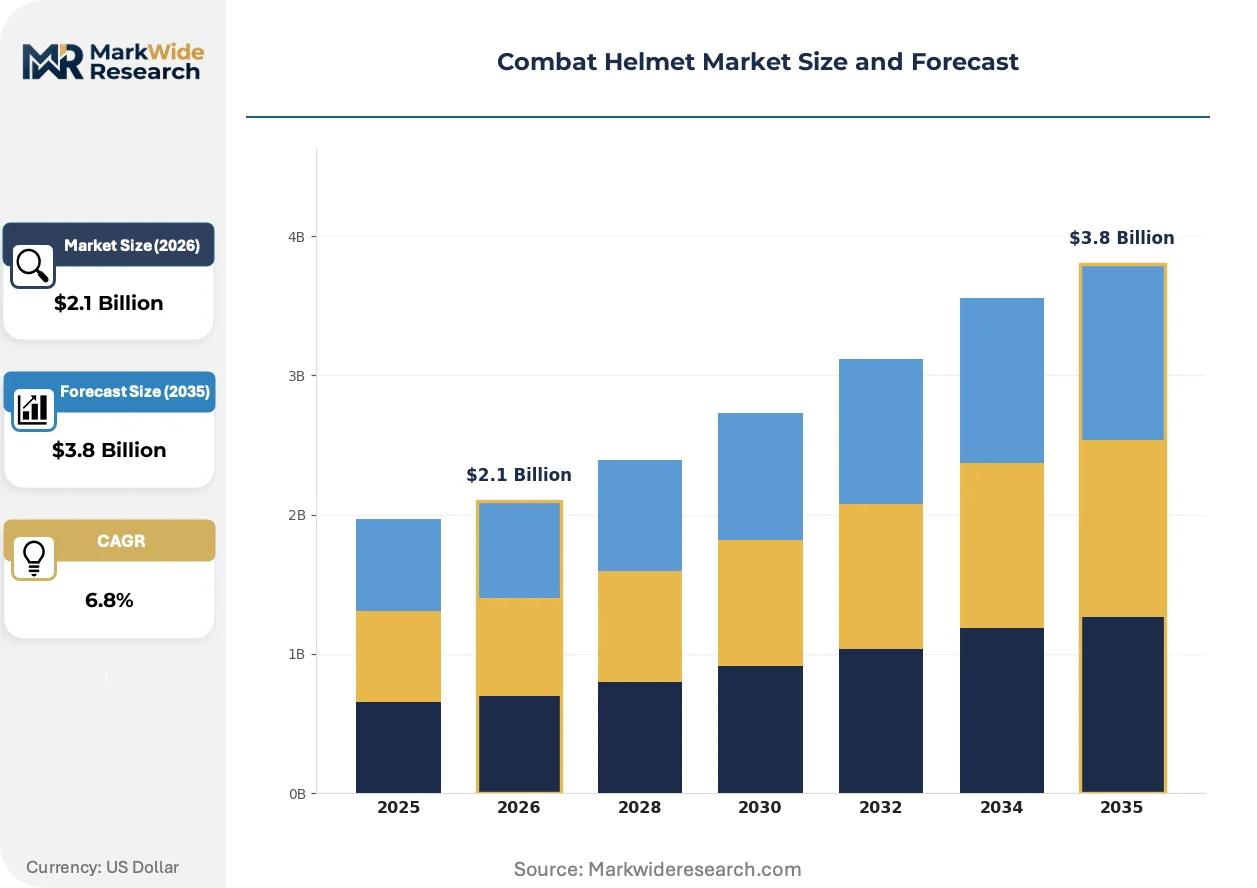
Market Dynamics
Material substitution from aramid to ultra-high-molecular-weight polyethylene is compressing weight-to-protection ratios while NATO procurement agencies consolidate specifications under unified STANAG frameworks.
Growth Catalysts
- NIJ ballistic standard upgrades:The U.S. Department of Defense's Enhanced Combat Helmet program mandates Level IIIA protection at reduced mass, forcing material innovation cycles.
- Integrated soldier systems:Mounting platforms for night vision devices and communication headsets transform helmets into hub equipment, expanding unit economics beyond pure ballistic function.
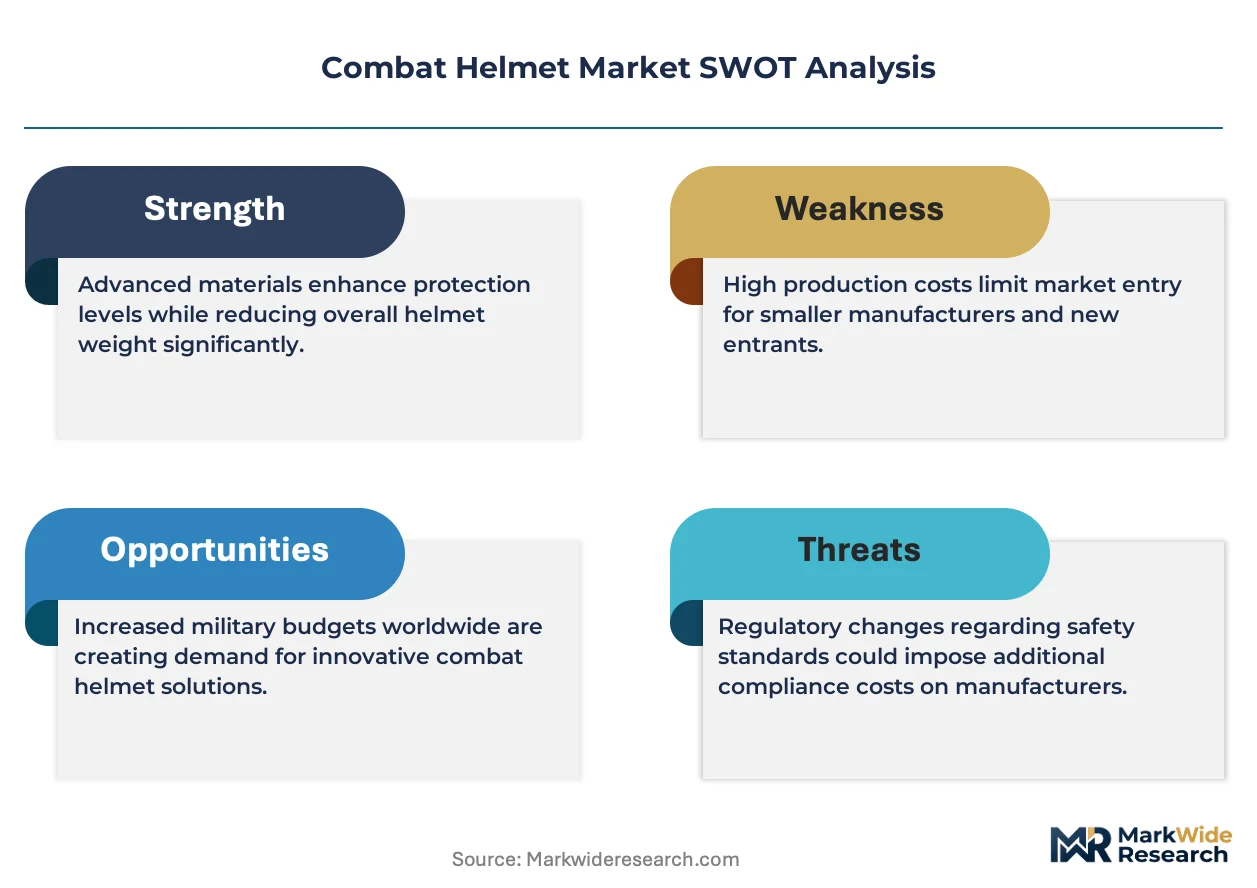
- Domestic manufacturing mandates:Buy American provisions in U.S. defense appropriations channel procurement toward domestic supply chains, insulating established producers from offshore competition.
Market Restraints
- UHMWPE feedstock concentration:High-performance fiber production clusters in the United States and the Netherlands, creating single-source vulnerability for European and Asian assemblers.
- REACH substance restrictions:ECHA regulations on hazardous chemicals in protective equipment force reformulation of resin systems and bonding agents, extending qualification timelines.
- Ballistic ceramic substitution:Face shield and add-on armor systems using boron carbide and silicon carbide capture marginal protection upgrades that helmet shells cannot achieve alone.
Strategic Opportunities
- Modular rail ecosystem expansion:Universal accessory mounting standards (MIL-STD-1913 derivatives) enable aftermarket component sales with recurring revenue profiles.
- Indian defense modernization:The country's Ministry of Defence indigenization push under the Make in India framework opens local production partnerships for foreign technology licensors.
- Law enforcement crossover:Counter-terrorism units and special response teams in municipal police departments adopt military-grade headgear, broadening addressable demand beyond defense ministries.
Industry Challenges
- Ballistic testing backlog:NIJ-certified laboratory capacity constraints extend new product qualification from 18 to 36 months, freezing development pipelines.
- Legacy inventory incompatibility:Existing helmet stocks lack rail geometry and suspension geometry for modern optics and communication systems, forcing complete system replacement rather than incremental upgrade.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combat Helmet Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Helmets, Tactical Helmets, Bump Helmets, Specialized Helmets Material: Kevlar, Carbon Fiber, Polycarbonate, Nylon End User: Military, Law Enforcement, Private Security, Civilian Feature: Bullet Resistance, Impact Protection, Communication System, Night Vision Compatibility |
| Companies Covered | BAE Systems, Gentex Corporation, 3M Company, Avon Protection plc, Safariland LLC, ArmorSource LLC, Honeywell International Inc., Revision Military, MKU Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combat Helmet Market Emerging Trajectories
Helmet architecture is converging with wearable electronics and biometric monitoring, transforming passive protection into active soldier system nodes. This integration demands new competencies in antenna design, power management, and data security.
Hybrid composite construction is hybridizing aramid and UHMWPE layers with thermoplastic matrices to achieve multi-hit performance against fragment simulating projectiles. Special operations forces in NATO member states are fielding these configurations for dismounted patrols exceeding 12 hours. The approach is compressing the performance gap between legacy Kevlar helmets and next-generation polyethylene systems.
REACH substance restrictions in the European Union are forcing reformulation of phenolic resins and solvent-based prepregs used in helmet shell manufacturing. German and French defense contractors face 18-24 month requalification cycles for alternative bonding systems. The regulatory pressure is accelerating adoption of thermoplastic composites that eliminate volatile organic compound emissions during cure.
Defense procurement agencies are consolidating orders under multi-year indefinite delivery contracts with single-source ceiling prices. The U.S. Army's PEO Soldier has shifted from competitive buys to negotiated extensions with incumbent suppliers. This concentration is most visible in the United States, where the Enhanced Combat Helmet program now runs through 2028 with options for two additional years.
Combat Helmet Market Segmentation
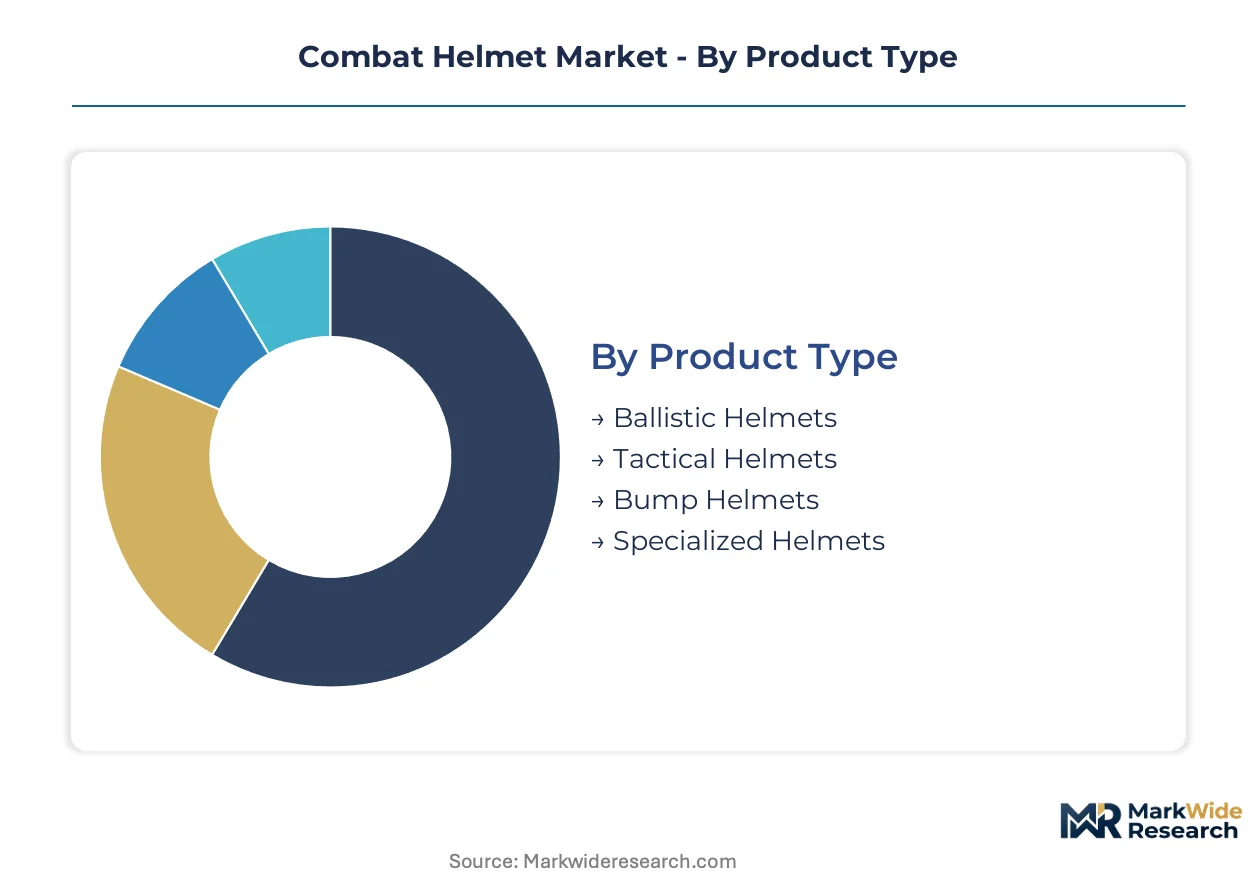
Combat helmet procurement channels diverge sharply across end-use applications, with military specifications demanding NIJ Level IIIA certification while law enforcement and security sectors prioritize modularity over ballistic rating. Material selection and integrated electronics now determine contract awards more than base shell protection alone.
Product Type:
Mature ballistic platforms anchor defense procurement budgets while emerging tactical configurations capture the steepest technology refresh cycles.
- Ballistic Helmets:Multi-layer aramid or UHMWPE composite shells rated against NIJ Level IIIA threats and fragmentation simulating projectiles under STANAG 2920. U.S. Army Program Executive Office Soldier channels the bulk of domestic procurement through sole-source indefinite delivery contracts with incumbent suppliers.
- Tactical Helmets:Modular rail-equipped designs prioritizing accessory integration over maximum ballistic protection. NATO special operations forces drive specification evolution here, mandating universal mounting geometry for night vision devices and communication headsets.
- Bump Helmets:Lightweight polymer shells for training, vehicle crew, and low-threat environments where blunt impact protection suffices.
- Specialized Helmets:Aviator, marine, and CBRN-specific configurations with integrated breathing apparatus interfaces.
Ballistic helmets retain volume leadership; tactical helmets hold the steepest expansion curve.
Material:
Cost tiers separate legacy fiber systems from next-generation composites, with performance premiums widening as weight-to-protection ratios tighten.
- Kevlar:DuPont's aramid fiber dominates legacy inventories and refurbishment programs. U.S. Marine Corps and reserve component procurements sustain demand despite polyethylene displacement in frontline units.
- Carbon Fiber:Hybrid matrices combining carbon layers with thermoplastic resins achieve multi-hit performance against fragment threats. German and French defense contractors face REACH-mandated reformulation cycles for phenolic resin alternatives.
- Polycarbonate:Injection-molded shells for bump helmets and training configurations where ballistic rating is secondary.
- Nylon:Suspension system webbing and retention hardware, not primary shell material.
Kevlar retains installed base dominance; carbon fiber composites gain share fastest in new procurement cycles.
End User:
Customer type determines specification stringency, with military channels enforcing full NIJ certification while adjacent markets accept lower-tier protection.
- Military:Department of Defense and NATO defense ministries mandate STANAG-compliant systems with integrated soldier architecture compatibility. Buy American provisions channel U.S. orders toward domestic manufacturing.
- Law Enforcement:Counter-terrorism units and special response teams adopt military-grade specifications, creating crossover demand beyond defense budgets.
- Private Security:Executive protection and high-risk facility contractors prioritize threat-appropriate protection without full military certification overhead.
- Civilian:Competitive shooting and preparedness segments drive modest volume in non-ballistic and lower-tier configurations.
Military end users command procurement volume; law enforcement represents the fastest-climbing adjacent channel.
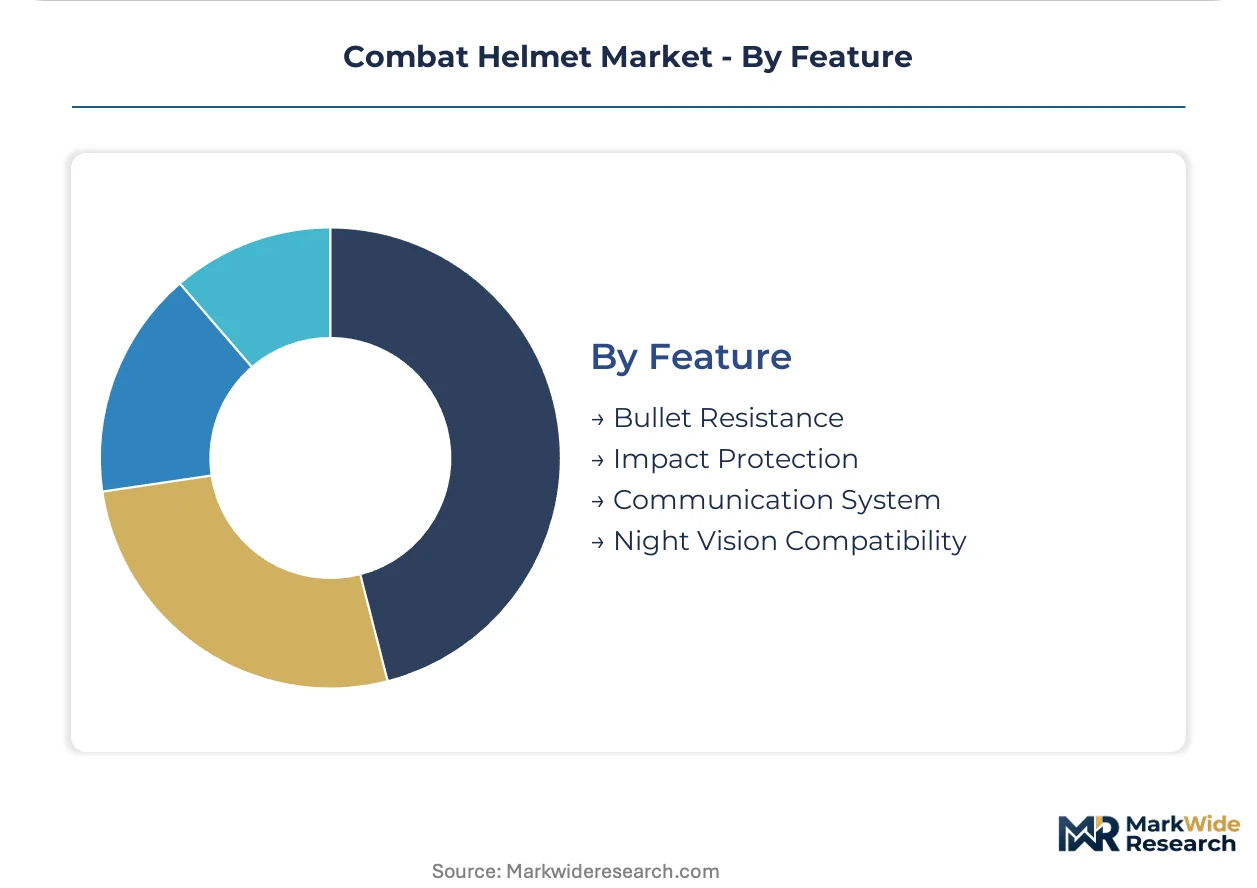
Feature:
Application context dictates feature prioritization, with dismounted patrol requirements diverging from vehicle crew and static security postures.
- Bullet Resistance:Core ballistic rating against handgun and fragmentation threats, certified through NIJ laboratory testing with 18-36 month qualification backlogs.
- Impact Protection:Blunt trauma absorption for vehicle rollovers, falls, and secondary collision injuries. Bump helmet configurations emphasize this over projectile defense.
- Communication System:Integrated bone conduction or earmuff-compatible headsets transforming helmets into network nodes. PEO Soldier's Integrated Visual Augmentation System requirements accelerate this specification.
- Night Vision Compatibility:Shroud geometry and power routing for image intensification and thermal devices. Universal standards prevent proprietary lock-in to single optic suppliers.
Bullet resistance remains the baseline specification; communication system integration offers the steepest value-add trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buy American provisions in U.S. defense appropriations channel procurement toward domestic manufacturing, insulating established producers from offshore competition. The U.S. Army's Enhanced Combat Helmet program and evolving NIJ ballistic standards are accelerating material upgrades from aramid to ultra-high-molecular-weight polyethylene. Military procurement agencies across NATO member states are expanding orders for integrated headgear systems.
United States
The U.S. Army's Program Executive Office Soldier drives specification evolution through sole-source indefinite delivery contracts. NIJ ballistic standard upgrades mandate Level IIIA protection at reduced mass, forcing material innovation cycles. Domestic manufacturing requirements and sole-source contracting practices in the United States favor established suppliers concentrated around defense industrial clusters.
United Kingdom
BAE Systems anchors European demand through its position on the British Army's Virtus soldier system. The UK's defense procurement framework emphasizes integrated soldier architecture compatibility across NATO STANAG protocols. Industrial activity clusters in southern England where prime contractors coordinate with Ministry of Defence qualification laboratories.
Germany
ECHA regulations on hazardous chemicals in protective equipment force reformulation of phenolic resins and solvent-based prepregs. German defense contractors face extended requalification cycles for alternative bonding systems. Manufacturing concentration in Bavaria and Baden-Württemberg supports hybrid composite construction for multi-hit performance against fragment threats.
India
The Ministry of Defence indigenization push under the Make in India framework opens local production partnerships for foreign technology licensors. MKU Limited competes aggressively in emerging markets with cost-optimized ballistic solutions manufactured at its India facility. Industrial capacity concentrates in Uttar Pradesh and Maharashtra where defense manufacturing corridors attract technology transfer agreements.
Netherlands
UHMWPE feedstock production clusters in the Netherlands, creating supply concentration for European and Asian assemblers. REACH substance restrictions accelerate adoption of thermoplastic composites that eliminate volatile organic compound emissions during cure. The Eindhoven region hosts advanced fiber production facilities serving NATO defense supply chains.
Combat Helmet Market Vendor Landscape
On the supply side, the industry is consolidating under multi-year indefinite delivery contracts with single-source ceiling prices. The U.S. Army's PEO Soldier has shifted from competitive buys to negotiated extensions with incumbent suppliers. Three archetypes dominate: legacy defense primes with sole-source relationships, cost-optimized emerging market specialists, and integrated soldier system architects. Competitive moves concentrate on strategic partnerships for technology licensing and geographic expansion through local production agreements.
Among U.S.-based defense contractors, Gentex Corporation and ArmorSource LLC exemplify the established supplier archetype sustained by long-standing Department of Defense relationships. BAE Systems represents the European prime contractor model anchoring national soldier modernization programs. MKU Limited occupies a position as the emerging market specialist leveraging cost-optimized manufacturing for price-sensitive procurement channels.
| Leading Market Players |
|---|
| BAE Systems |
| Gentex Corporation |
| 3M Company |
| Avon Protection plc |
| Safariland LLC |
| ArmorSource LLC |
| Honeywell International Inc. |
| Revision Military |
| MKU Limited |
| Others |
Supply Flow & Price Mechanics
UHMWPE fiber production clusters in the United States and the Netherlands capture upstream margin pools, while downstream helmet assemblers in Europe and Asia face compressed bargaining power against concentrated feedstock suppliers. Defense procurement agencies consolidate orders under multi-year sole-source contracts, insulating established domestic manufacturers from price competition while locking out offshore rivals.
Pricing Analysis
Volume-discount tiering structures dominate defense procurement, with sole-source indefinite delivery contracts awarding preferential unit economics to incumbents meeting minimum annual volume thresholds. Price differentiation hinges on NIJ certification grade and integrated electronics bundling, with Level IIIA-plus-communication configurations commanding substantial premiums over baseline ballistic shells. Pricing pressure stems from REACH-mandated material reformulations extending qualification timelines and inflating compliance costs. Law enforcement crossover segments exhibit highest price sensitivity, while U.S. military channels under Buy American provisions show lowest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for electronics components and carbon fiber precursors. Raw material dependencies center on UHMWPE fibers from the Netherlands and the United States, aramid from DuPont's domestic facilities, and phenolic resin systems facing ECHA restriction. Single-source vulnerability pervades high-performance fiber production, with European and Asian assemblers tethered to limited qualified suppliers. Distribution runs through prime contractor-direct-to-defense-agency channels, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Combat helmet procurement fragmentation creates niche opportunities as NATO member states diverge on STANAG implementation timelines and national soldier system architectures. Modular rail ecosystem expansion and law enforcement crossover demand reward specialized entrants over generalist defense primes.
For Market Incumbents: Pre-empt UHMWPE supply disruption by securing long-term fiber offtake agreements with Dutch and U.S. producers before qualification backlogs worsen. Anchor sole-source relationships through integrated soldier system bundling, combining helmet procurement with night vision shrouds and communication headsets to raise switching costs for defense agencies. For New Entrants and Emerging Players: Build out law enforcement and private security channels where NIJ certification overhead is lower and procurement cycles are faster than military defense budgets. Target Indian defense modernization through Make in India joint ventures, licensing polyethylene molding technology to local partners for cost-optimized ballistic solutions. Lead with modular rail compatibility as the go-to-market wedge against legacy helmet stocks lacking accessory mounting geometry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed defense component specialists holding NIJ laboratory relationships but lacking integrated soldier system positioning. Five-to-ten year viability hinges on successful navigation from pure ballistic shell manufacturing to electronics-integrated hub equipment. Watch for STANAG specification consolidation announcements as the inflection signal triggering incumbent consolidation waves.| Strategic Initiative | Industry Significance |
|---|---|
| NIJ Laboratory Capacity Expansion | Reduces 36-month qualification backlogs that freeze development pipelines for new entrants. |
| UHMWPE Fiber Supply Agreement | Locks in feedstock security against single-source vulnerability for European and Asian assemblers. |
| Modular Rail Ecosystem Partnership | Captures recurring aftermarket revenue through universal MIL-STD-1913 accessory compatibility. |
| Make in India Joint Venture | Unlocks Ministry of Defence indigenization contracts via local production partnerships. |
| REACH-Compliant Resin Reformulation | Accelerates thermoplastic composite adoption eliminating volatile organic compound emissions. |
Methodological Framework
Desk research of defense procurement databases, NIJ certification registries, and NATO STANAG documentation preceded structured interviews with Program Executive Office Soldier officials, helmet manufacturing engineers, UHMWPE fiber procurement leads, and law enforcement equipment buyers. Secondary validation drew from U.S. Department of Defense budget justifications, ECHA substance restriction filings, and customs trade data. Bottom-up unit economics modeling triangulated against top-down defense expenditure allocations.
Assumption sets held fixed NATO STANAG 2920 ballistic threat specifications and REACH substance restriction timelines while varying U.S. defense appropriation levels and Indian indigenization policy intensity across the analysis window. Segmentation dimensions modeled included helmet product type, material composition, end-user channel, and integrated feature bundling. CAGRs derived from shipment volume trajectories weighted by unit price bands, incorporating UHMWPE material substitution elasticities and sole-source contract renewal probabilities as industry-specific inputs.
Stress conditions across UHMWPE feedstock disruption, NIJ laboratory capacity constraints, and REACH regulatory acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding defense budget continuity and standardization protocol adoption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Public Address and Voice Alarm Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
US Negative Pressure Escape Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Mask Particulate Market
Safety Equipment and Personal Protective Equipment (PPE)
Armoured Thermocouple Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Monitoring and Dosimeter Badges Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Lancet Market
Safety Equipment and Personal Protective Equipment (PPE)
Digital Camlock Market