
 Head Guards Market | 2026-2036
Head Guards Market Size, Share, and Industry Trends Forecast 2026-2036
Head Guards Market Analytics
Subscription-based protective equipment monitoring is restructuring how industrial buyers procure head guards, shifting capital expenditure into recurring service contracts. MSA Safety Incorporated leverages connected sensor platforms to anchor its position in smart hard hat systems. Adidas AG competes through specialized sports helmet lines tied to league certification requirements. Honeywell International Inc. dominates industrial distribution channels with broad SKU coverage and direct corporate procurement relationships.
Head guards are engineered protective enclosures designed to absorb, disperse, or deflect kinetic energy from impacts, blows, falling objects, or projectile hazards, typically incorporating suspension systems, energy-absorbing liners, and chin retention assemblies. Polycarbonate shells deliver optical clarity and impact resistance for full face shield applications, while fiberglass-reinforced composites sustain higher thermal loads in emergency response scenarios. Sports helmets command premium positioning through league-specific certification tiers, whereas safety caps for light industrial use occupy commoditized volume segments with thinner margin pools. ABS plastic formulations balance cost and durability across construction applications where replacement cycles run shorter.
OSHA mandates hard hat compliance across US construction and manufacturing sites, while the EU's CE marking framework and PPE Regulation enforce uniform safety thresholds for European market access. Japan's METI coordinates JIS standard updates that govern industrial helmet performance testing, directly shaping product development cycles for exporters. Stakeholders must monitor evolving material substitution trends and certification reciprocity agreements between major trading blocs to anticipate sourcing and compliance cost shifts.
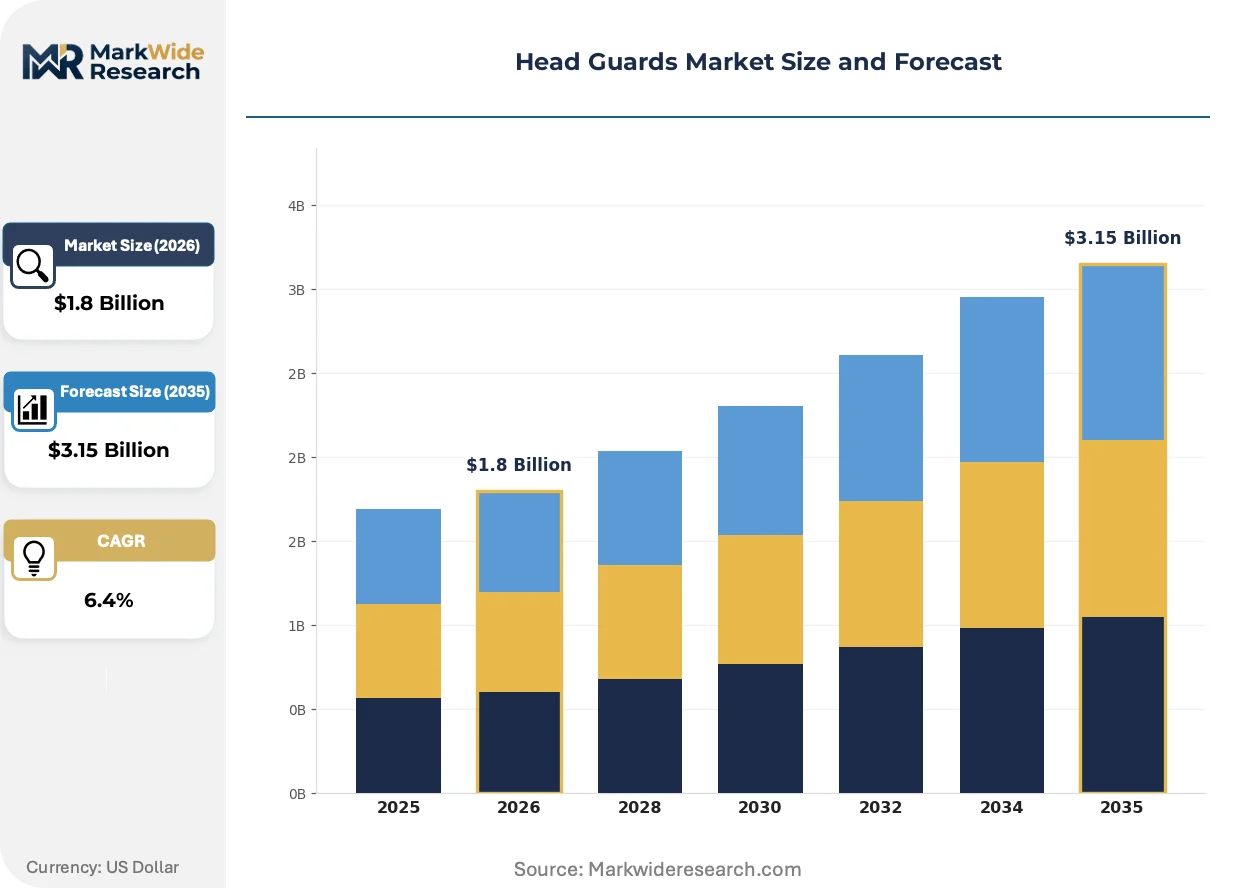
Market Dynamics
Subscription-based protective equipment monitoring is restructuring how industrial buyers procure head guards, shifting capital expenditure into recurring service contracts anchored by connected sensor platforms.
Growth Catalysts
- OSHA workplace safety mandates:US construction and manufacturing employers must provide certified hard hats, compelling replacement cycles and compliance-driven procurement volume.
- Combat sports participation:Amateur and professional boxing, MMA, and football leagues require league-specific helmet certifications, expanding addressable demand across athletic segments.
- East Asian manufacturing concentration:Factory automation and heavy industrial output in China, South Korea, and Japan sustain baseline consumption for JIS-standard industrial helmets.
Market Restraints
- Petrochemical feedstock volatility:Polycarbonate and ABS resin prices fluctuate with crude oil markets, compressing margins for shell manufacturers.
- Chinese supply concentration:Over half of global liner foam and suspension component production clusters in Zhejiang and Guangdong provinces, exposing buyers to single-source risk.
- Certification reciprocity gaps:CE marking and OSHA standards lack mutual recognition, forcing dual testing protocols for exporters.
Strategic Opportunities
- India industrial corridor buildout:BIS certification requirements for construction PPE expand addressable market as infrastructure investment accelerates.
- Wearable sensor convergence:Integration of impact detection, biometric monitoring, and connectivity protocols enables premium positioning in industrial and sports segments.
- Direct-to-corporate procurement platforms:Bypassing traditional distribution layers captures margin and data relationships with enterprise safety managers.
Industry Challenges
- Multi-standard certification timelines:Simultaneous pursuit of ANSI Z89.1, EN 397, and JIS T 8131 approvals extends product launch cycles by 8-14 months.
- Legacy ERP integration friction:Connected helmet platforms require API compatibility with incumbent workplace safety management systems, complicating enterprise adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Head Guards Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Face Shield, Hard Hat, Sports Helmet, Safety Cap Material: Polycarbonate, ABS Plastic, Polyethylene, Fiberglass End User: Construction Workers, Athletes, Industrial Workers, Firefighters Application: Sports, Construction, Manufacturing, Emergency Response |
| Companies Covered | Adidas AG, Everlast Worldwide, Inc., Fairtex, Storelli Sports LLC, Rival Boxing Gear Inc., 3M Company, Honeywell International Inc., MSA Safety Incorporated, Bullard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Head Guards Market Evolving Landscape
Material science advances and connectivity integration are compressing product lifecycles while elevating performance thresholds across both industrial and athletic applications.
Multi-layer energy-absorbing liner systems incorporating non-Newtonian shear-thickening fluids and expanded polypropylene foam are consolidating protective performance into thinner, lighter form factors. Professional football programs and elite boxing gyms in the United States and Germany are adopting these systems at replacement-cycle pace. The technology is consolidating market share at the premium certification tier by enabling compliance with emerging rotational-impact standards that legacy foam constructions cannot meet.
Japan's METI has accelerated JIS T 8131 revision cycles to incorporate IoT-enabled helmet performance monitoring, mandating data logging for impact events above threshold force levels. Industrial safety managers must now specify connected hard hats to satisfy audit requirements in automotive and heavy machinery plants. Japanese exporters to ASEAN markets face pressure to preload compliance with these standards ahead of anticipated regional harmonization.
Enterprise procurement teams are unbundling after-sales service from equipment purchase, negotiating separate multi-year sensor monitoring and replacement agreements. Industrial distributors in the US Midwest and German Ruhr region face disintermediation as manufacturers establish direct corporate accounts. This pattern is most visible in construction and logistics verticals where safety managers prioritize total cost of ownership over upfront unit pricing.
Head Guards Market Segmentation
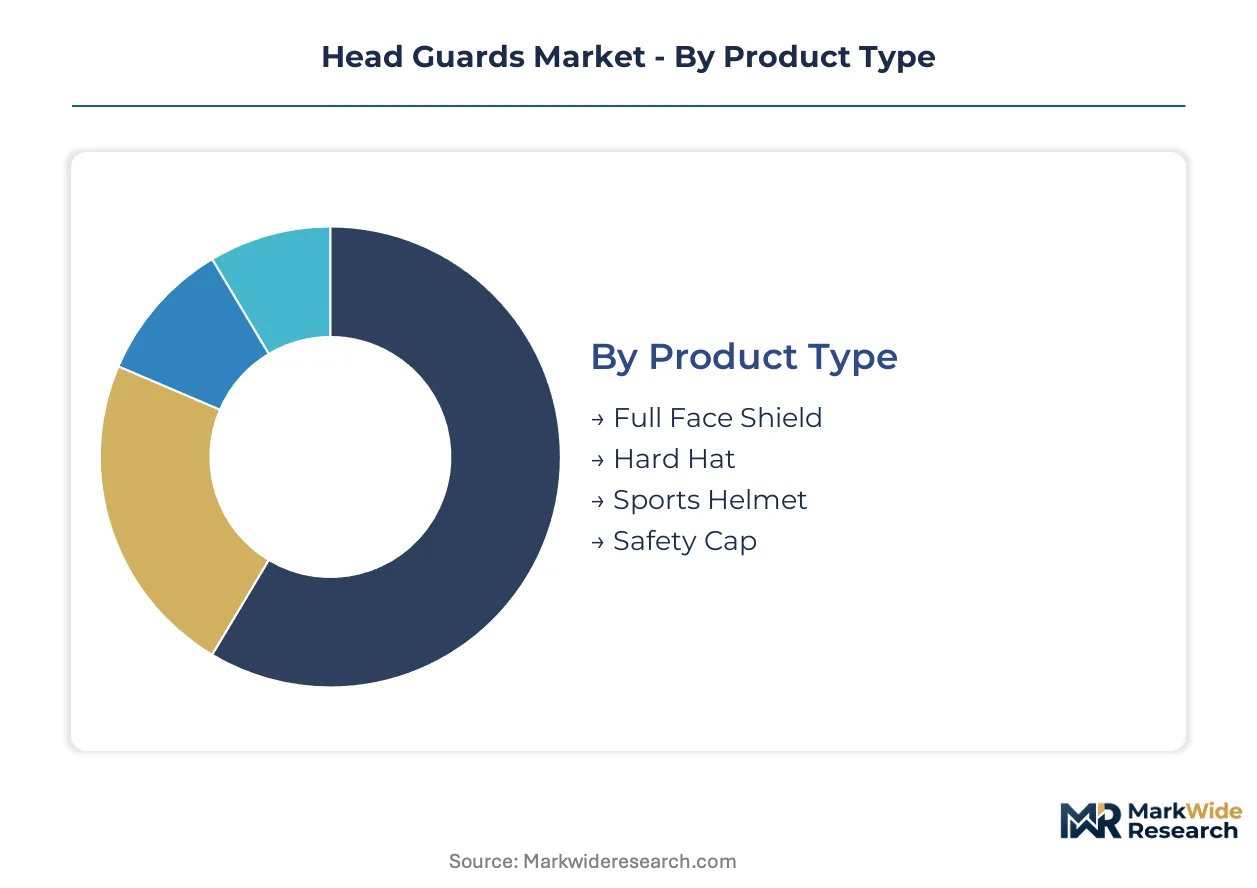
Head guard procurement diverges sharply between standalone personal equipment and integrated safety systems, with material specifications and certification tiers determining integration depth across industrial and athletic environments. Product positioning, supply chain configuration, and end-user compliance requirements all vary by segment alignment.
Product Type:
Standalone protective equipment dominates procurement volume, while embedded sensor-integrated systems are penetrating premium tiers through connected workplace platforms.
- Full Face Shield:Optical-grade polycarbonate visors with anti-fog coatings and scratch-resistant surfaces protect against chemical splash and projectile hazards. Demand concentrates in US chemical processing corridors and German pharmaceutical manufacturing clusters where OSHA and CE marking mandate facial coverage alongside respiratory protection.
- Hard Hat:Suspension-equipped shells with energy-absorbing liners meet ANSI Z89.1 and EN 397 standards for construction and heavy industry. Volume placements track North American infrastructure spending and East Asian shipbuilding activity, with replacement cycles tied to mandatory expiration dating.
- Sports Helmet:League-certified designs for boxing, MMA, and football incorporate multi-density foam and rotational-impact mitigation systems.
- Safety Cap:Lightweight bump caps for low-clearance environments offer basic impact protection without suspension systems, serving warehousing and light assembly where hard hat standards exceed hazard levels.
Volume placements concentrate in Hard Hat; the faster expansion belongs to Sports Helmet.
Material:
Cost-to-performance ratios stratify material selection, with thermal and optical requirements driving specification divergence across end-use environments.
- Polycarbonate:Amorphous thermoplastic delivers optical clarity and UV resistance for face shields and visor applications. Demand clusters in automotive painting operations and outdoor construction sites across the United States and Japan where transparency and impact resistance must coexist.
- ABS Plastic:Acrylonitrile-butadiene-styrene balances moldability, cost, and durability for standard hard hats in construction and general industry. Volume consumption tracks Chinese and Indian infrastructure buildouts where price sensitivity shapes procurement.
- Polyethylene:High-density formulations provide chemical resistance and low-temperature toughness for cold-storage and chemical handling environments.
- Fiberglass:Reinforced composite shells sustain elevated thermal loads and electrical insulation for emergency response and electrical utility applications.
ABS Plastic captures the highest unit placements; Fiberglass is climbing the fastest on thermal performance premiums.
End User:
Compliance mandates and liability exposure create divergent purchasing behaviors across occupational categories, with enterprise procurement dominating industrial segments.
- Construction Workers:Mandatory hard hat programs across OSHA-regulated US sites and emerging economy infrastructure projects drive baseline consumption. Procurement runs through contractor safety programs with specified ANSI or local standard compliance.
- Athletes:Amateur and professional combat sports participants require league-specific helmet certifications, with replacement cycles tied to equipment damage protocols and concussion management policies. US collegiate programs and German boxing federations set certification benchmarks.
- Industrial Workers:Manufacturing and logistics operations specify head protection by hazard assessment, spanning bump caps to full hard hat systems.
- Firefighters:Thermal and impact-rated helmets meeting NFPA 1971 and EN 443 standards serve structural firefighting and technical rescue, with integrated communication systems penetrating premium tiers.
Construction Workers anchor volume demand; Athletes are gaining share fastest on participation growth and certification tightening.
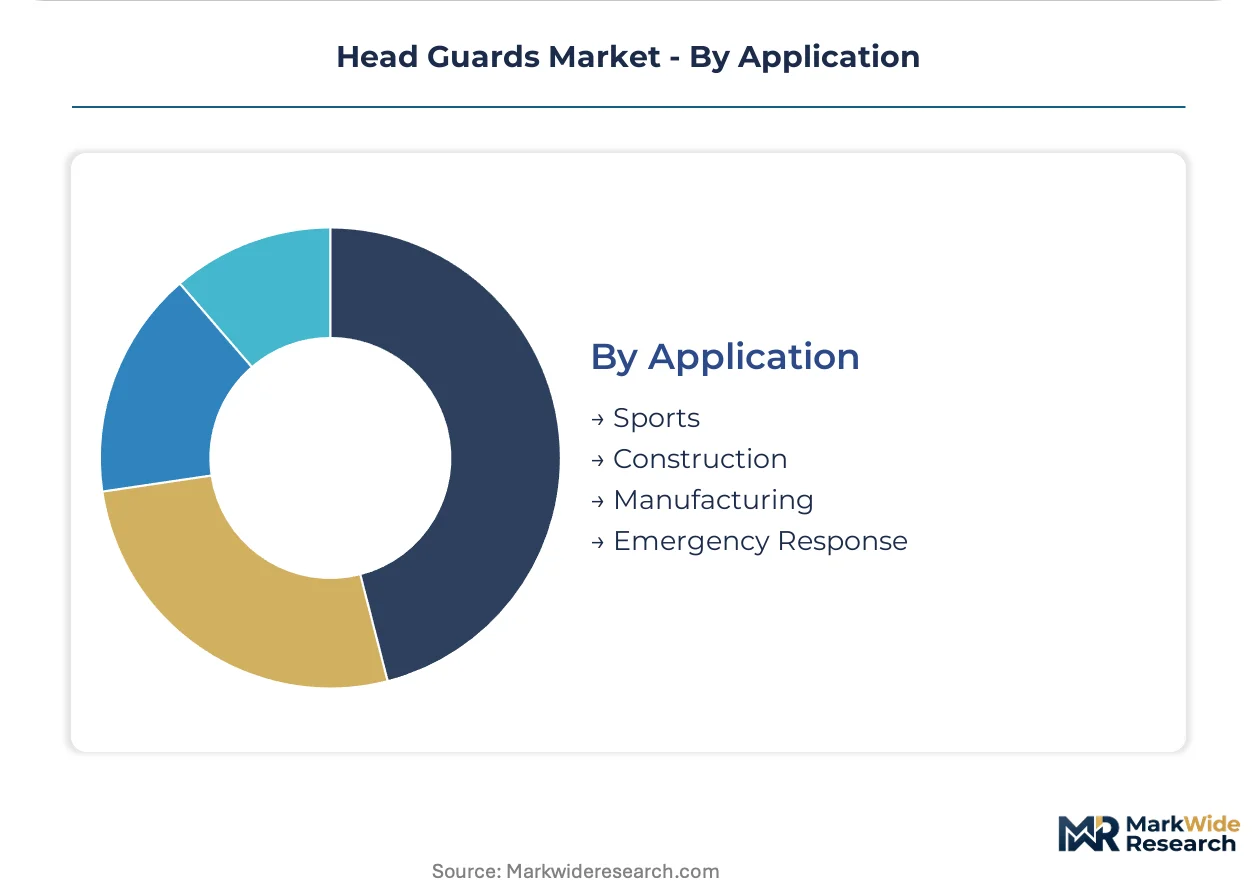
Application:
Hazard taxonomy and regulatory jurisdiction segment application requirements, with sports and emergency response commanding premium pricing against commoditized industrial baseline.
- Sports:League certification tiers for boxing, football, and hockey mandate specific impact attenuation and retention system performance, with premium positioning through rotational-impact standards. US and German athletic programs drive specification evolution.
- Construction:OSHA-mandated hard hat compliance across US sites creates replacement-driven demand, with similar national requirements in Japan and emerging BIS enforcement in India.
- Manufacturing:Hazard-specific selection from bump caps to face shields serves diverse industrial environments, with JIS-standard helmets dominating Japanese automotive and machinery plants.
- Emergency Response:Firefighting and technical rescue helmets integrate thermal protection, communication systems, and SCBA compatibility at premium price points.
Construction holds the largest installed base; Emergency Response shows the steepest expansion trajectory on integrated system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian component clusters while consumption splits between mature regulatory markets and emerging infrastructure corridors. Manufacturing of liners and suspension systems dominates Zhejiang and Guangdong provinces in China. Procurement volume aligns with OSHA enforcement zones, EU construction activity, and Indian industrial corridor development.
United States
Construction spending across Texas and Florida drives hard hat replacement cycles tied to OSHA ANSI Z89.1 compliance audits. The Department of Labor enforces mandatory head protection across federally funded infrastructure projects. Safety managers in Houston's petrochemical corridor specify connected helmet platforms with impact logging capabilities.
Germany
Industrial output in the Ruhr region and Bavarian automotive clusters sustains demand for EN 397-certified helmets with integrated communication systems. The EU's PPE Regulation and CE marking framework govern market access and product liability standards. Frankfurt's logistics hubs deploy lightweight bump caps for warehouse operations below hard hat threshold hazards.
Japan
METI-coordinated JIS T 8131 revisions mandate IoT-enabled performance monitoring in Toyota and Honda manufacturing plants. Automotive and heavy machinery sectors in Aichi and Kanagawa prefectures preload compliance for anticipated ASEAN harmonization. Tokyo-based safety managers negotiate multi-year sensor monitoring contracts separate from equipment purchase.
India
BIS certification requirements for construction PPE expand addressable demand as infrastructure investment accelerates in Maharashtra and Gujarat. The Bureau of Indian Standards enforces helmet performance testing for public works contractors. Mumbai's metro expansion and Delhi-Mumbai Industrial Corridor projects specify certified head protection for labor compliance.
China
Factory automation in Jiangsu and Shandong provinces sustains baseline consumption for industrial helmets meeting GB standards. The State Administration for Market Regulation coordinates national PPE quality supervision campaigns. Shenzhen's electronics manufacturing clusters import JIS-standard helmets for Japanese-owned automotive supplier facilities.
Head Guards Market Competitive Landscape
Top-tier vendors anchor premium certification tiers, while mid-scale specialists occupy commoditized construction segments. The vendor base stratifies across three functional layers: diversified industrial conglomerates with broad SKU coverage, sports equipment brands leveraging league certification relationships, and regional fabricators serving price-sensitive emerging markets. Two dominant competitive moves are reshaping positioning: direct-to-corporate procurement platform development and connected sensor platform integration into legacy helmet architectures.
Among diversified industrial conglomerates, 3M Company and Honeywell International Inc. occupy positions defined by distribution scale and corporate procurement relationships. Adidas AG exemplifies the sports-specialist archetype, anchoring premium athletic segments through league certification requirements. MSA Safety Incorporated represents the connected-safety vector, with sensor-integrated platforms restructuring industrial buyer procurement patterns toward recurring service contracts.
| Leading Market Players |
|---|
| Adidas AG |
| Everlast Worldwide, Inc. |
| Fairtex |
| Storelli Sports LLC |
| Rival Boxing Gear Inc. |
| 3M Company |
| Honeywell International Inc. |
| MSA Safety Incorporated |
| Bullard |
| Others |
Value Network & Pricing Analysis
Skilled foam-molding technicians in Zhejiang province command wage premiums that compress margin spreads between economy hard hats and sensor-integrated premium units. Labor-cost differentials between coastal Chinese manufacturing clusters and emerging Southeast Asian alternatives feed directly into three-tier pricing stratification across construction, industrial, and connected-safety segments.
Pricing Analysis
Price erosion across ABS plastic hard hats traces to resin cost volatility and commoditized shell production in Shandong province. Three-tier pricing structure across premium, standard, and economy levels separates IoT-enabled helmets with METI-mandated data logging from basic ANSI Z89.1-compliant units. Certification grade and after-sales service bundling drive price differentiation. Cost-down pressure on economy tiers accelerates because Indian BIS enforcement expands low-cost import competition. Contractor safety programs exhibit highest price sensitivity; automotive OEMs with audit-driven procurement show least.
Supply Chain Analysis
Dual-sourcing requirements from Japanese automotive buyers mandate qualified suppliers in both Guangdong and Jiangsu provinces for liner foam components. Manufacturing concentrates in China, South Korea, and Vietnam for suspension assemblies and sensor modules. Raw material dependencies include polycarbonate resin, expanded polypropylene foam, and copper wiring for connectivity integration. Single-source vulnerability concentrates in Zhejiang province foam production. Distribution runs through industrial safety distributors in the US Midwest and direct-to-corporate procurement platforms in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Head guard supply is tightening around certified sensor-integrated capacity, with JIS T 8131 compliance timelines creating bottlenecks that prop premium pricing. Manufacturers with pre-qualified connected helmet platforms capture disproportionate margin expansion.
For Market Incumbents: Cement market position by accelerating backward integration into liner foam production to offset Chinese supply concentration risk. Invest in dual-certification pipelines for ANSI Z89.1 and EN 397 to compress launch cycles. Channel control through direct corporate procurement relationships defends against distributor disintermediation. For New Entrants and Emerging Players: Direct-to-corporate procurement platforms offer the most penetrable route for bypassing established distribution layers in US construction corridors. Target mid-tier industrial buyers in India's Maharashtra and Gujarat infrastructure corridors where BIS certification requirements are newly enforced. White-space exists in subscription-based sensor monitoring services unbundled from equipment sales. For Investors and Strategic Acquirers: Re-rating potential sits with connected-safety specialists given METI-mandated IoT integration accelerating across Japanese automotive supply chains. Long-term viability favors manufacturers with captive sensor platform development and recurring revenue attachment. Watch JIS-CE reciprocity negotiations as inflection signal for regional expansion economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Liner Foam | Captive supply of expanded polypropylene reduces exposure to Zhejiang province concentration. |
| Dual-Certification Pipeline Investment | Parallel ANSI Z89.1 and EN 397 testing compresses product launch cycles by 8-14 months. |
| Direct-to-Corporate Procurement Platform | Bypasses Midwest industrial distributors to capture margin and safety manager data relationships. |
| Sensor-Integrated Platform Development | METI-mandated IoT logging in Japanese automotive plants creates replacement-cycle pull-through. |
| Subscription Monitoring Service Launch | Unbundles after-sales service from equipment purchase to shift capex into recurring contracts. |
Research Methodology
Independent corroboration across safety equipment procurement managers, plant engineers at automotive OEMs, and regulatory affairs specialists at certification bodies underwrites the qualitative findings. Primary interviews with industrial distributors in Germany's Ruhr region and construction safety directors in Texas and Florida were validated against secondary sources including OSHA enforcement databases, METI JIS standard revision notices, and BIS certification registries. Bottom-up demand modeling from end-use segments was triangulated with top-down market sizing from trade flow analysis.
Comparable-period anchoring to 2016-2021 baseline consumption patterns established trajectory parameters across the projection horizon. The analytical framework modeled segmentation dimensions including product type, material grade, end-user category, and certification tier. CAGRs were derived from regression analysis against construction spending indices, combat sports participation rates, and manufacturing output correlations. Industry-specific inputs included JIS T 8131 revision timelines and Indian BIS enforcement phase-ins.
Inputs from METI regulatory notices and OSHA audit disclosure databases were available through the study window; gaps in real-time connected helmet deployment metrics introduce uncertainty bands around sensor-integrated segment forecasts. Forecasts reflect assumptions regarding certification reciprocity progress and resin price stability. A model refresh is warranted upon material change in ASEAN regulatory harmonization timelines or polycarbonate feedstock cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Supplementary Protectors Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Earmuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Radar Speed Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Americas Reusable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Ship Life-Saving Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsic Safety Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Mask Particulate Market