
 Coffee Grinder Market | 2026-2036
Coffee Grinder Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Grinder Market Analysis
Direct-to-consumer e-commerce channels is reshaping how grinder manufacturers reach end users, bypassing traditional kitchenware distributors. Mahlkönig leverages its commercial reputation to anchor premium positioning in prosumer segments. Eureka competes through Italian manufacturing heritage and compact footprint designs. HARIO sustains its manual grinder dominance across Asian specialty coffee markets.
A coffee grinder is a precision size-reduction device employing rotating burrs or blades to fracture roasted coffee beans into uniform particles for optimal extraction, with burr geometries typically measured in micrometer tolerances and motor torque calibrated to prevent heat degradation of volatile aromatic oils. Burr Grinders command the highest margin pools due to replaceable parts and upgrade paths, while Electric Grinders lead volume through convenience-driven household adoption. Manual Grinders occupy a resilient niche among travel-oriented consumers and minimalists seeking portability without power dependency.
FDA food-contact material standards and EU REACH chemical safety frameworks govern grinder construction materials, with CE marking requirements enforcing electrical safety across European imports. The EU Ecodesign Directive progressively tightens standby power limits for electric models, compelling motor redesigns. Stakeholders must monitor evolving energy efficiency thresholds and material compliance costs as regulatory divergence between jurisdictions intensifies sourcing complexity.
Market Dynamics
The EU Ecodesign Directive's tightening standby power limits are forcing motor redesigns across electric grinder portfolios, while specialty coffee shop density in urban clusters drives equipment refresh cycles.
Growth Catalysts
- Specialty café proliferation:Third-wave coffee culture in Germany, Italy, and the United States accelerates commercial-grade grinder procurement for consistency-driven extraction.
- REACH material compliance:EU chemical safety frameworks elevate stainless steel and ceramic burr specifications, creating upgrade demand from safety-conscious operators.
- Burr geometry advances:Micrometer-tolerance machining improves particle uniformity, enabling roasters to command premium positioning through repeatable brew profiles.
Market Restraints
- Copper and rare-earth motor costs:Electric grinder manufacturers face input volatility from concentrated Chilean copper supply and Chinese rare-earth processing.
- Manual grinder substitution:Portable hand-grinders displace entry-level electric units among travel-oriented minimalists seeking power independence.
- CE marking complexity:Divergent electrical safety testing across EU member states extends certification timelines for imported motor housings.
Strategic Opportunities
- Prosumer segment white space:Home enthusiasts in the United States seek commercial-grade burr sets scaled for residential counter space.
- Direct-to-consumer channels:E-commerce platforms bypass kitchenware distributors, capturing margin previously allocated to wholesale tiers.
- Energy efficiency mandates:EU Ecodesign Directive thresholds reward early motor redesign adopters with preferential retail placement.
Industry Challenges
- Precision machining talent scarcity:Burr grinding expertise concentrates in Italian and German metalworking clusters, constraining new entrant scaling.
- Multi-jurisdiction compliance:FDA food-contact standards diverge from EU REACH material specifications, complicating unified product architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Grinder Market |
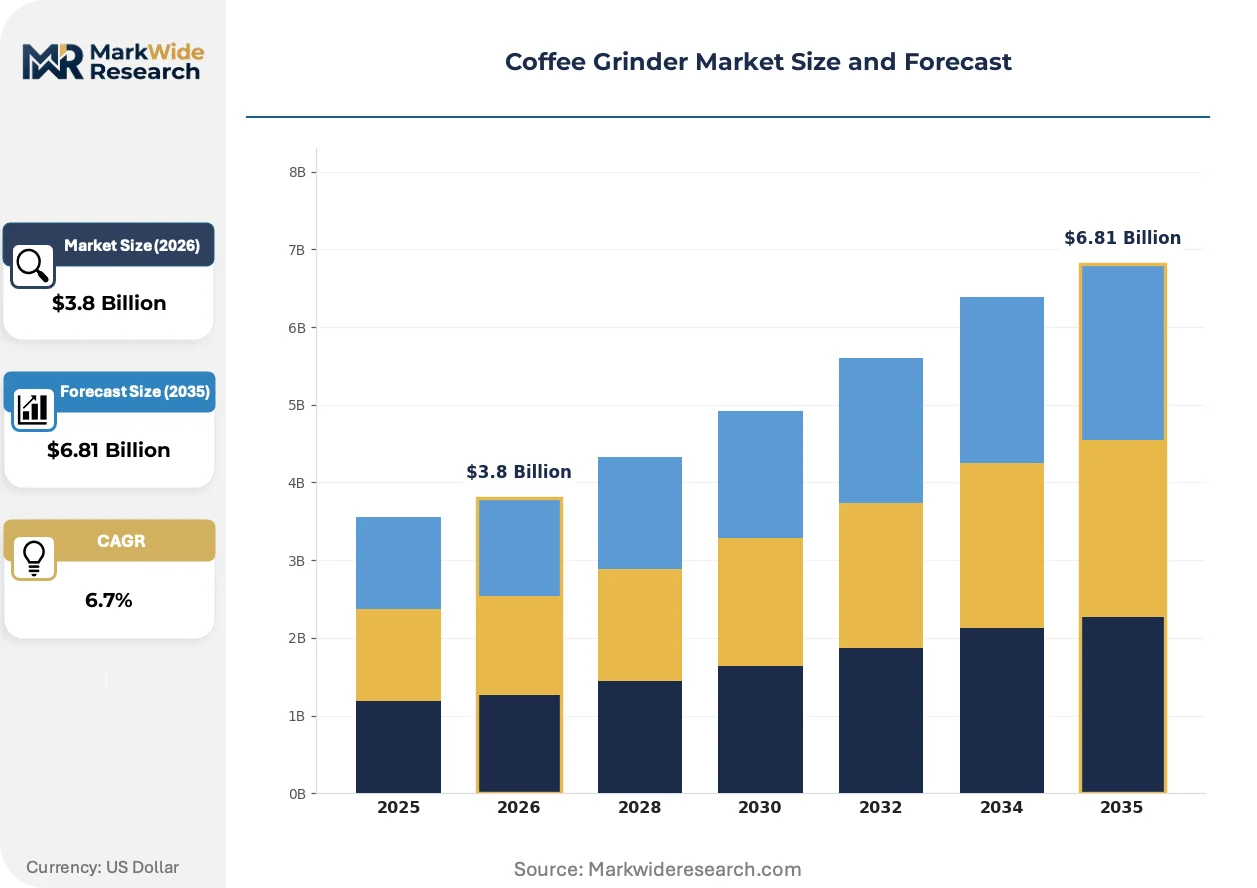
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Burr Grinders, Blade Grinders, Manual Grinders, Electric Grinders End User: Households, Cafes, Restaurants, Roasteries Technology: Conical Burr, Flat Burr, Blade, Manual Capacity: Small, Medium, Large, Commercial |
| Companies Covered | Fiorenzato, Baratza, Mahlkönig, HARIO, BUNN, Ditting, Eureka, Shaoxing Jiehui Electrical Appliances Co., Ltd, Mazzer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Grinder Market Emerging Trajectories
Grinder engineering is hybridizing across manual precision and electric convenience, while regulatory energy thresholds and channel disintermediation compress traditional go-to-market structures.
Stepped-stepless hybrid adjustment mechanisms are hybridizing burr grinder control architectures. High-end home brewers and small-format cafés adopt these systems for repeatable micro-adjustments without full stepless complexity. The technology is hybridizing price-performance tiers, compressing the gap between prosumer and commercial specifications.
EU Ecodesign Directive standby power limits now govern electric grinder motor efficiency. Manufacturers redesign winding configurations and idle-state electronics to meet descending wattage thresholds. Premium electric models targeting German and Italian markets lead compliance investment, while economy segments face margin compression from retrofit costs.
Subscription-integrated grinder procurement is reshaping equipment acquisition patterns. Roasters and café chains bundle grinder leases with bean supply contracts, unbundling capital expenditure into operational budgets. This model concentrates in United States urban markets where specialty coffee chains standardize equipment fleets across multiple locations.
Coffee Grinder Market Segmentation
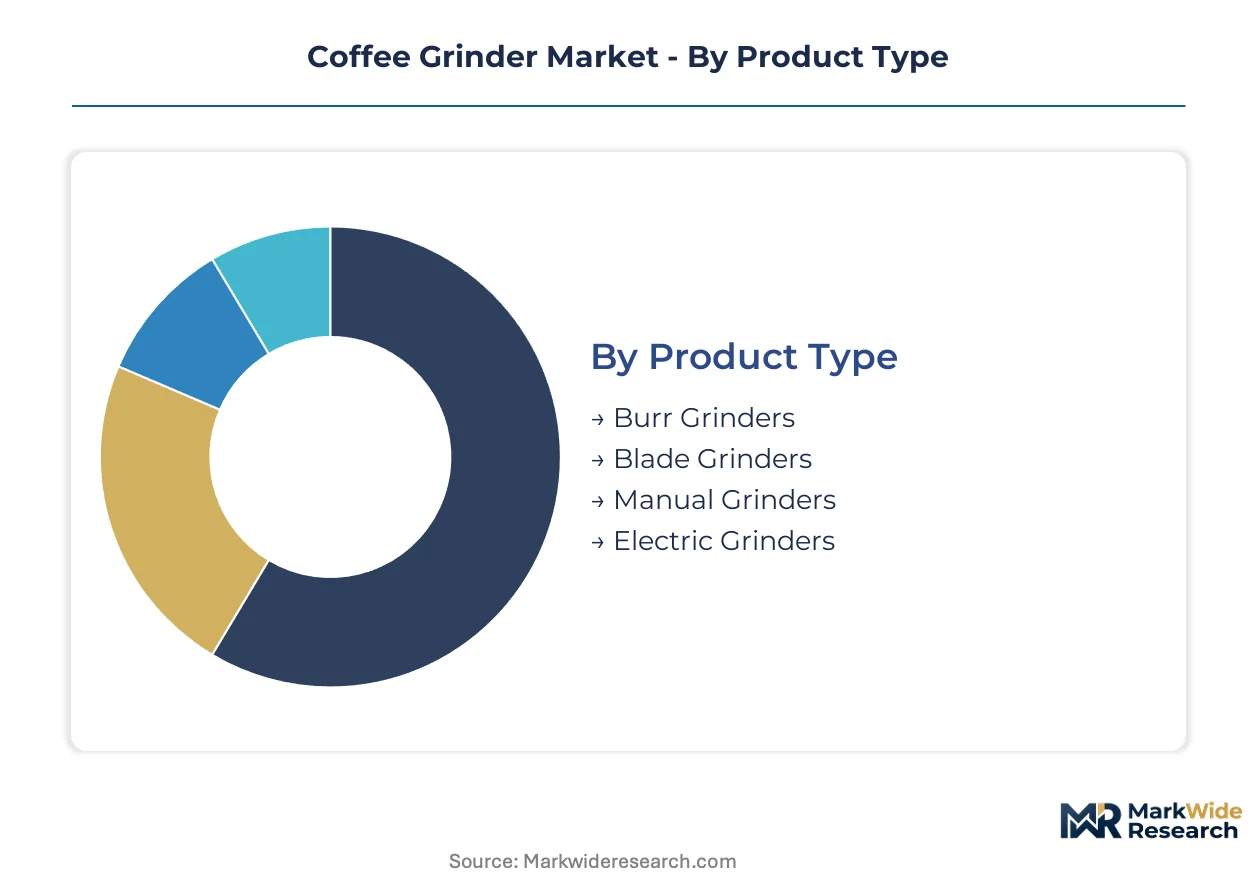
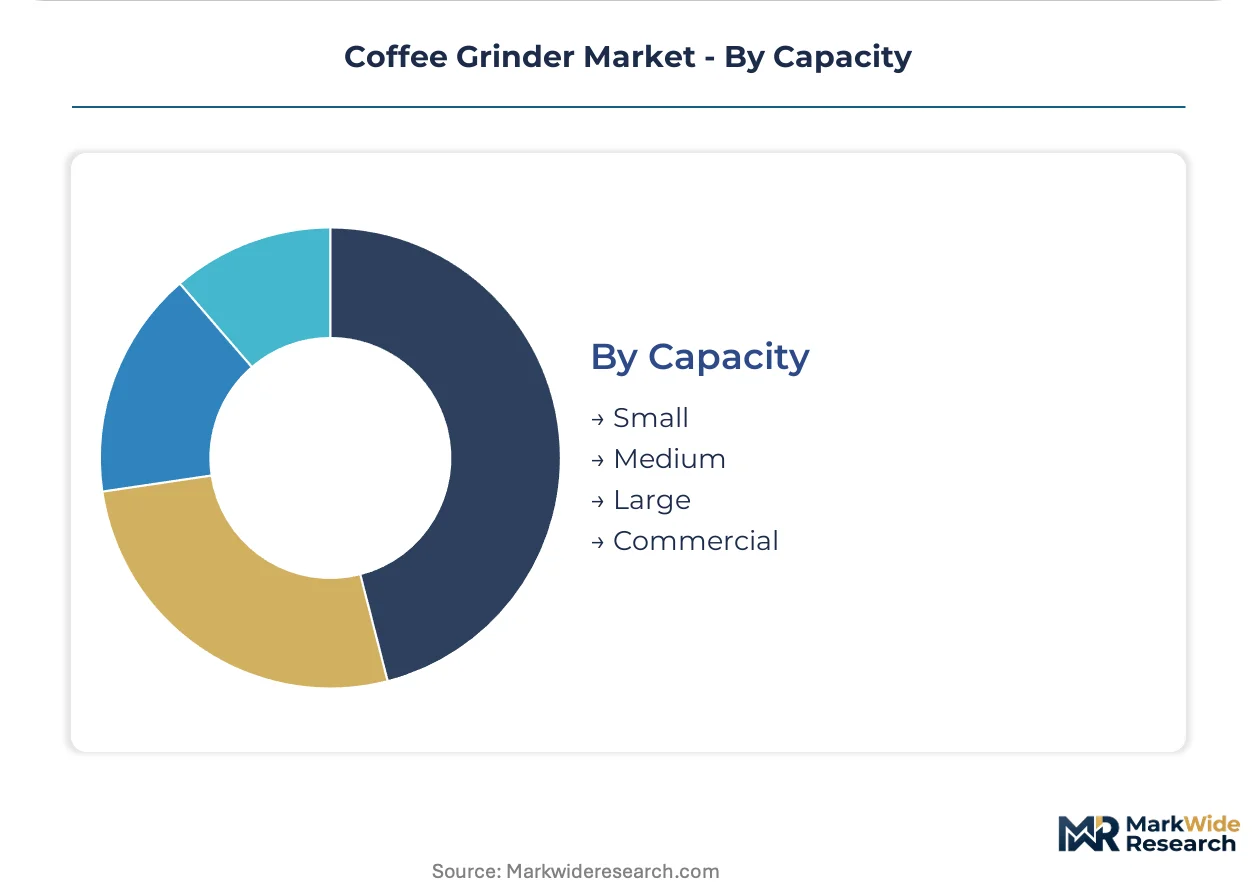
Grinder segmentation reflects divergent performance requirements across extraction precision, throughput volume, and user expertise. Manufacturers optimize burr geometries, motor torque curves, and adjustment mechanisms for distinct operational contexts rather than universal deployment.
Product Type:
Mature electric configurations dominate household penetration while emerging manual formats capture mobility-driven demand.
- Burr Grinders:Precision-machined rotating discs fracture beans between conical or flat geometries measured in micrometer tolerances. Specialty cafés in Germany and Italy specify commercial-grade units for extraction consistency that underpins premium positioning. Replaceable burr sets and upgrade paths sustain aftermarket revenue pools.
- Electric Grinders:Motor-driven units employ induction or DC brushless architectures calibrated to prevent heat degradation of volatile aromatic oils. United States households favor convenience-driven electric adoption where counter space and power access are non-constraints. EU Ecodesign Directive standby power limits now govern motor efficiency redesigns.
- Blade Grinders:Rotary blade systems chop rather than crush beans, producing irregular particle distributions unsuitable for precision extraction.
- Manual Grinders:Hand-cranked burr mechanisms eliminate power dependency for travel-oriented minimalists.
Electric Grinders retain volume leadership; Burr Grinders hold the steepest expansion curve.
End User:
Application intensity spans from occasional home brewing to continuous commercial duty cycles.
- Cafes:High-throughput operations in urban United States clusters demand stepless adjustment and thermal stability for back-to-back extractions. Equipment refresh cycles accelerate where third-wave coffee culture elevates grind consistency to competitive differentiation.
- Roasteries:Bean production facilities require sample grinders with laboratory-grade repeatability for cupping protocols and quality control. REACH material compliance elevates stainless steel burr specifications across EU-facing operations.
- Households:Residential users prioritize compact footprints and reduced noise signatures.
- Restaurants:Food service operations integrate grinders into broader beverage programs with moderate duty requirements.
Households sustain installed base scale; Cafes generate the highest replacement velocity.
Technology:
Grinding mechanics concentrate in burr-based precision while blade systems serve cost-sensitive entry points.
- Conical Burr:Cone-shaped upper burr nests within ring-shaped lower burr to draw beans through progressively narrower gaps. Italian manufacturers dominate high-tolerance machining for this geometry where particle uniformity commands premium pricing. Lower heat generation suits oily dark roasts.
- Flat Burr:Parallel disc alignment produces more uniform particle distribution preferred for espresso extraction. German metalworking clusters concentrate expertise in flat burr production where micrometer tolerances determine cup quality consistency.
- Blade:Propeller-style rotary chopping generates heat and particle inconsistency.
- Manual:Hand-cranked ceramic or steel burr systems serve portability requirements.
Conical Burr maintains installed base dominance; Flat Burr gains share fastest in espresso-specialized channels.
Capacity:
Throughput specifications align motor torque, hopper volume, and duty cycle ratings to operational scale.
- Commercial:Continuous-duty motors with thermal overload protection sustain peak-hour throughput in high-volume cafés. Subscription-integrated procurement models concentrate in United States urban markets where specialty chains standardize equipment fleets across multiple locations.
- Large:Extended duty cycles bridge prosumer and light commercial applications.
- Medium:Moderate batch sizes serve enthusiast home brewers and small-format operations.
- Small:Single-serve portions prioritize compact storage and minimal retention.
Medium capacity captures the broadest user base; Commercial specifications expand most quickly through chain standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European grinder import flows, while the Los Angeles-Long Beach complex handles Pacific Rim manufacturing volumes for North American distribution networks.
United States
Specialty café chains in Seattle and Portland drive commercial-grade procurement for third-wave extraction protocols. FDA food-contact material standards govern stainless steel burr specifications for import clearance. Brooklyn and Austin roasteries anchor prosumer demand for flat burr geometries calibrated for espresso precision.
Germany
EU Ecodesign Directive standby power limits force motor redesigns across electric grinder portfolios entering Hamburg and Bremen ports. CE marking requirements enforce electrical safety testing before retail placement. Stuttgart metalworking clusters concentrate flat burr machining expertise for commercial equipment supply.
Italy
Milan and Rome café density sustains replacement cycles for stepless adjustment grinders in high-throughput operations. REACH chemical safety frameworks elevate ceramic burr specifications for EU-facing manufacturers. Bologna and Turin host precision machining talent pools for conical burr production at micrometer tolerances.
Japan
Tokyo and Osaka specialty coffee scenes import manual grinder formats for pour-over ritual markets. METI energy efficiency guidelines influence electric model specifications for residential adoption. Kyoto roasteries anchor demand for laboratory-grade sample grinders supporting cupping protocols.
China
Shanghai and Shenzhen café proliferation drives mid-range electric grinder adoption among emerging specialty operators. GB standards govern electrical safety for domestic manufacturing and export certification. Zhejiang province concentrates motor winding capacity for grinder OEM supply chains.
Coffee Grinder Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in burr machining and motor supply. The vendor base concentrates among Italian and German metalworking heritage, with Asian manufacturing scaling entry-level electric formats. Three archetypes dominate: heritage European precision houses, Asian volume manufacturers, and prosumer-focused hybrid specialists. Competitive moves center on direct-to-consumer channel bypass and energy efficiency compliance investment ahead of regulatory thresholds.
Within the heritage precision tier, Mahlkönig and Eureka exemplify commercial reputation transfer into residential markets, while HARIO occupies a distinct position in manual grinder formats across Asian specialty channels. These three anchors illustrate divergent geographic manufacturing legacies and channel positioning strategies without overlapping core segments.
| Leading Market Players |
|---|
| Fiorenzato |
| Baratza |
| Mahlkönig |
| HARIO |
| BUNN |
| Ditting |
| Eureka |
| Shaoxing Jiehui Electrical Appliances Co., Ltd |
| Mazzer |
| Others |
Supply Flow & Price Mechanics
Zhejiang province's motor winding capacity anchors electric grinder OEM supply chains, concentrating component bargaining power among a handful of winding houses that feed assembly operations in Germany and Italy. This geographic clustering allows tier-one manufacturers to extract volume discounts while smaller brands absorb premium spot pricing for comparable torque specifications.
Pricing Analysis
Volume-discount tiering structures separate Mahlkönig-grade commercial units from entry-level electric formats, with pricing stratifying across premium, standard, and economy tiers based on burr tolerance certification and motor thermal protection ratings. REACH-compliant stainless steel burr specifications command 15-20% premiums over standard grades in EU-facing channels. Cost compression in economy electric segments is intensifying because Zhejiang motor suppliers are prioritizing higher-margin brushless DC contracts. Café chains exhibit lowest price sensitivity due to subscription-integrated procurement models, while solo roasteries negotiate aggressively on per-unit replacement cycles.
Supply Chain Analysis
Export-control regimes on precision grinding equipment limit flat burr machining technology transfers from German and Italian clusters to emerging Asian manufacturers, constraining supply expansion. Component flows draw from Chilean copper cathode, Chinese rare-earth magnet processing, and Stuttgart-area CNC machining for micrometer-tolerance burr sets. Single-source vulnerability concentrates in Italian conical burr production where Bologna and Turin workshops hold irreplaceable grinding expertise. Distribution runs through Hamburg and Los Angeles-Long Beach port complexes for European and North American retail placement respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coffee grinder market fragmentation creates entry niches as direct-to-consumer channel disintermediation collapses traditional wholesale markup structures and splinters volume across dozens of specialty brands.
For Market Incumbents: Pre-empt prosumer segment encroachment by acquiring manual grinder specialists with Asian distribution footprints before they scale electric hybrid platforms. Mahlkönig and Eureka should tighten backward integration into Stuttgart flat burr machining capacity to defend margin position against Zhejiang motor suppliers expanding upstream. CE marking investment ahead of Ecodesign Directive threshold tightening secures preferential retail placement in German and Italian channels.
For New Entrants and Emerging Players: United States prosumer households seeking commercial-grade burr sets scaled for residential counter space represent the most penetrable entry point, with Brooklyn and Austin roasteries anchoring initial demand validation. Japanese manual grinder ritual markets offer secondary white space through METI-compliant electric hybrid formats. Go-to-market execution should prioritize Instagram-native demonstration content over traditional kitchenware distributor relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because subscription-integrated grinder procurement models concentrate equipment decisions among fewer roaster-café chains with standardized fleet requirements. Target acquisition profiles emphasize Italian and German precision machining houses with captive burr technology and existing CE marking infrastructure. The signal to watch is chain café procurement committee consolidation from decentralized location-level purchasing to centralized fleet management.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Bypasses kitchenware distributor markups, capturing margin previously allocated to wholesale tiers in United States markets. |
| Ecodesign Compliance Investment | Early motor redesign adopters secure preferential retail placement ahead of EU standby power threshold tightening. |
| Burr Machining Acquisition | Captures Stuttgart or Bologna precision grinding expertise that constrains new entrant scaling in commercial segments. |
| Subscription-Integrated Procurement | Converts capital expenditure into operational budgets for United States specialty café chains standardizing equipment fleets. |
| Manual-Electric Hybrid Development | Tokyo and Osaka pour-over ritual markets reward portability without power dependency through METI-guided efficiency specifications. |
Methodological Framework
Initial hypotheses were tested against primary input from café equipment procurement managers, specialty roaster operations directors, burr machining workshop supervisors, and kitchenware distributor category buyers and refined through secondary validation against EU Ecodesign Directive implementation documents, FDA food-contact material standards filings, Hamburg and Los Angeles-Long Beach customs import records, and SEC 10-K disclosures from publicly traded parent companies. Bottom-up demand estimates from end-user segmentation were triangulated against top-down supply capacity assessments from Zhejiang motor winding and Stuttgart metalworking clusters.
Demand-supply balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning product type, end user intensity, burr geometry technology, and capacity throughput tier. CAGRs were derived from installed base replacement velocity and new adoption curve modeling, incorporating EU Ecodesign Directive compliance cost pass-through assumptions and REACH material specification upgrade demand from safety-conscious operators.
Macroeconomic conditions sit as an overlay; deviation in copper and rare-earth magnet pricing, specialty café foot traffic recovery patterns, or transatlantic shipping rate volatility would shift the trajectory. Material shifts in EU Ecodesign Directive implementation timelines or FDA food-contact material standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Espresso Powder Market
Coffee
Coffee Beans Market
Coffee
US Coffee Roaster Market
Coffee
Decaffeinated Coffee Market
Coffee
North America Instant Coffee Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Office Coffee Service (OCS) Market
Coffee
South America Ready-To-Drink (RTD) Coffee Market
Coffee
Middle East Coffee Market
Coffee
US Coffee Machine Market
Coffee
Coffee Extracts Market
Coffee
Mushroom Coffee Market
Coffee
Specialty Coffee Market
Coffee
India Coffee Roaster Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
United States Coffee Pods and Capsules Market