
 UK Coffee Roaster Market | 2026-2036
UK Coffee Roaster Market Size, Share, and Industry Trends Forecast 2026-2036
UK Coffee Roaster Market Insights
The UK's Plastic Packaging Tax is shifting procurement priorities across the coffee roasting supply chain, compelling operators to rethink bean sourcing logistics and retail packaging formats. Origin Coffee leverages direct-trade relationships with East African cooperatives to sustain traceability credentials. Square Mile Coffee anchors its reputation on precision drum roasting for London's specialty café segment. Volcano Coffee Works differentiates through fluid bed roasting technology leadership and B-Corp certification.
A coffee roaster is a thermal processing machine that applies controlled heat between 180°C and 240°C to green coffee beans, triggering Maillard reactions and caramelization to develop aromatic compounds for commercial brewing. Drum roasters dominate the UK installed base due to their batch consistency and operator familiarity across artisan and mid-scale production floors. Fluid bed roasters represent the fastest-growing segment as cafés seek faster roast cycles and reduced carbon footprint per kilogram. Specialty bean origin focus commands premium pricing, while conventional blend roasting occupies volume-driven wholesale channels with thinner margins.
The Food Standards Agency enforces hygiene and labeling standards for roasted coffee sold to UK foodservice operators, while the British Standards Institution certifies equipment safety under BS EN ISO standards. The Environment Agency monitors emissions compliance for roasting facilities in urban air quality management areas. Stakeholders must monitor evolving Extended Producer Responsibility regulations and carbon reporting thresholds that will reshape capital allocation toward cleaner burners and energy recovery systems.
Market Dynamics
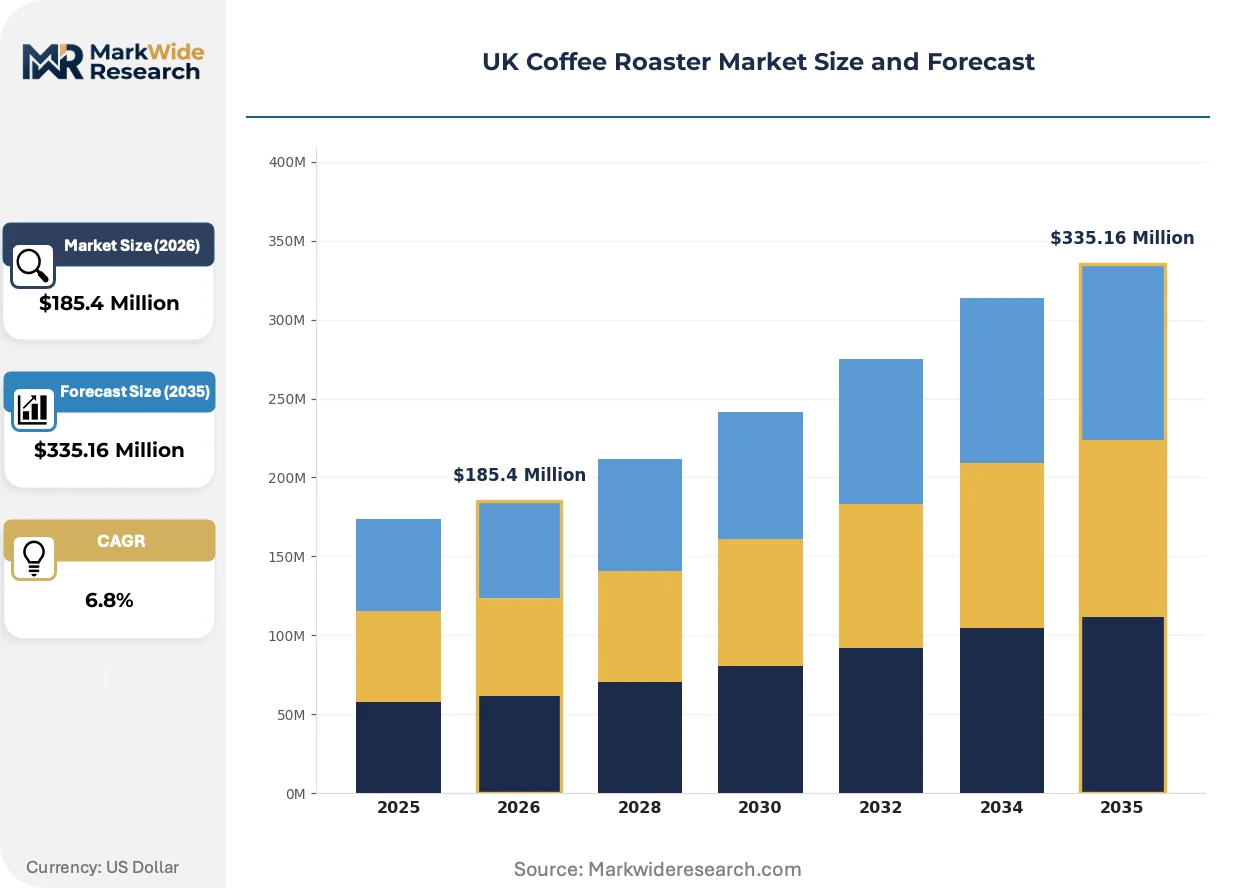
The UK's Plastic Packaging Tax is compressing margins across the coffee roasting value chain while simultaneously accelerating capital flows toward fluid bed roasting systems and compostable packaging infrastructure.
Growth Catalysts
- Extended Producer Responsibility frameworks:The UK's evolving EPR regulations are mandating producer accountability for end-of-life packaging, compelling roasters to invest in circular supply chain partnerships and material recovery systems.
- Specialty café density in England's metropolitan corridor:Artisan roasting operations from London to Leeds are driving equipment replacement cycles as independent cafés seek in-house batch control and origin transparency credentials.
- Fluid bed roasting technology:Hot-air roasting systems reduce cycle times and energy intensity per kilogram, attracting sustainability-focused operators seeking operational differentiation.
Market Restraints
- Green coffee bean price volatility:Arabica futures on ICE exchange expose UK roasters to currency and commodity swings that compress already thin wholesale margins.
- Supply concentration in East African cooperatives:Direct-trade relationships with Ethiopian and Kenyan producers create single-origin dependency risks during harvest disruptions or logistics bottlenecks.
- Urban air quality management area restrictions:The Environment Agency's emissions monitoring in London, Manchester, and Bristol constrains facility siting and burner technology choices for roasting operations.
Strategic Opportunities
- B-Corp certification pathway:The UK's growing sustainability-conscious consumer base rewards verified environmental and social performance with pricing premiums and loyalty lock-in.
- Compostable flexible packaging:Cellulose-based valve bags and home-compostable laminates address Plastic Packaging Tax liability while meeting specialty retail shelf-life requirements.
- Reusable transport container networks:Palletized stainless steel container pooling systems between roasters and foodservice distributors eliminate single-use packaging from B2B logistics.
Industry Challenges
- Roastmaster skill scarcity:Precision profiling for drum and fluid bed systems requires sensory calibration and thermal engineering expertise that outpaces vocational training pipeline output.
- BS EN ISO equipment certification timelines:Third-party safety validation for modified roasting systems delays commercial deployment and ties up working capital in pre-revenue equipment.
- Legacy ERP integration with traceability platforms:Direct-trade origin data and carbon accounting metrics require API connectivity that many mid-scale roasters lack technical capacity to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Coffee Roaster Market |
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $335.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Roaster Type: Drum Roasters, Fluid Bed Roasters, Convection Roasters, Hybrid Roasters Bean Origin Focus: Single-Origin, Blend, Organic, Fair Trade, Specialty End User: Cafés, Restaurants, Hotels, Corporate Offices, Catering Services Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Specialty Stores |
| Companies Covered | Origin Coffee, North Star Coffee Roasters, Balance Coffee, Chipp Coffee Co, White Label Coffee Co, Assembly Coffee, Square Mile Coffee, Coffee Direct, Volcano Coffee Works, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Coffee Roaster Market Trends and Innovations
Electrification of thermal systems and AI-assisted roast profiling are compressing the skill gap between artisan operators and scaled production, while regulatory pressure on packaging waste reshapes material science investment priorities across the supply chain.
Fluid bed roasting technology is expanding into mid-scale production floors previously dominated by drum systems. Independent cafés and micro-roasteries from Bristol to Manchester are retrofitting compact hot-air units that slash roast cycles from fourteen minutes to eight. This acceleration is expanding into wholesale channels where batch consistency and throughput velocity determine contract renewals with multi-site foodservice operators.
The UK's Plastic Packaging Tax is forcing material substitution across bean packaging formats. Compostable valve bags certified to home-compostable standards are displacing conventional plastic laminates in specialty retail channels. Roasters serving the London metropolitan hub are responding fastest, locking in supply agreements with cellulose film converters ahead of anticipated EPR threshold reductions.
Café operators are consolidating supplier relationships around vertically integrated roasters offering origin traceability dashboards. Single-origin procurement with cooperative-level GPS mapping and harvest batch documentation is displacing anonymous commodity blending in premium positioning. This concentration is most visible across England's coffee hub corridor, where independent chains leverage transparency credentials to defend against specialty entrants from Leeds and Manchester.
UK Coffee Roaster Market Segmentation
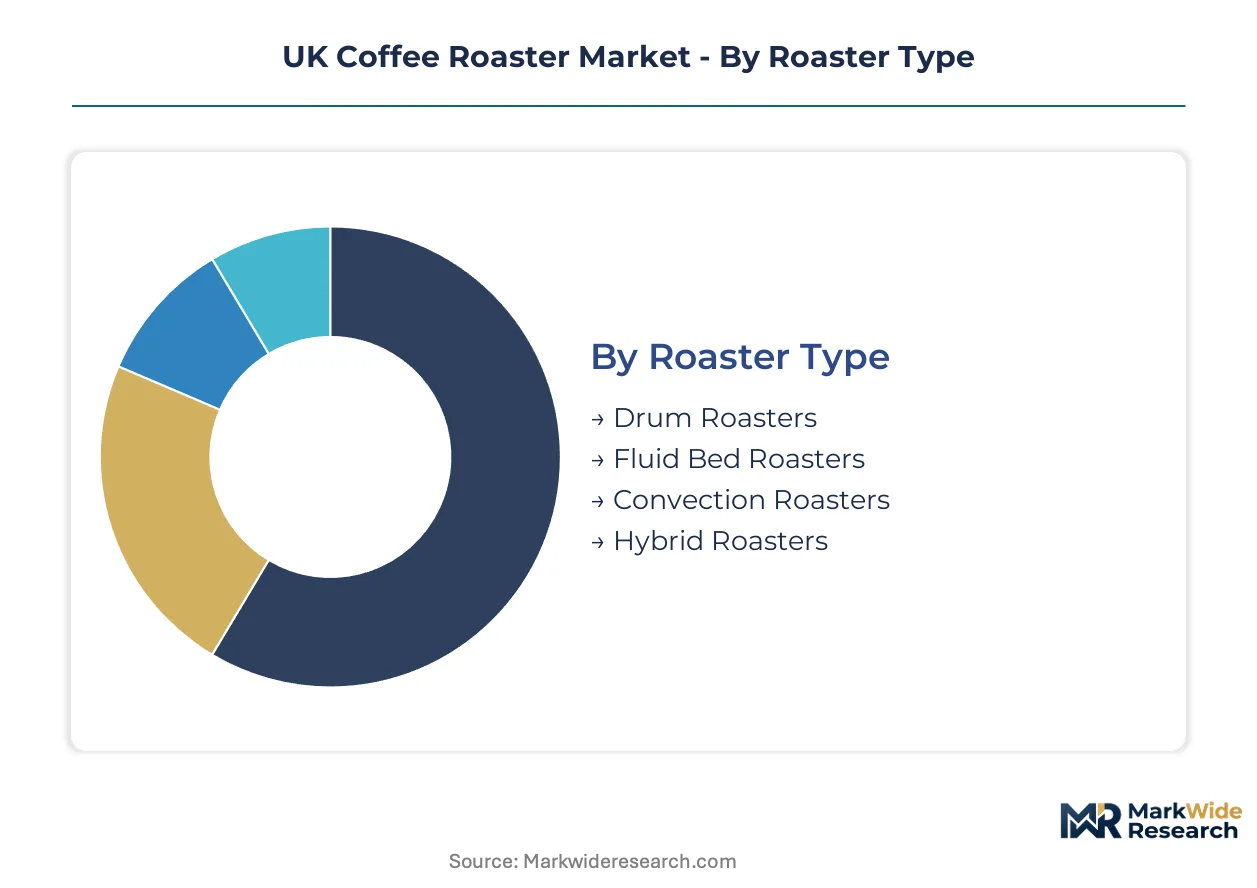
Equipment replacement cycles and origin transparency requirements are fragmenting the UK coffee roaster landscape into distinct procurement tiers. Roastmasters align technology choices with end-use volume profiles and regulatory exposure across England's metropolitan corridor.
Roaster Type:
Upgrade decisions hinge on batch consistency requirements against energy efficiency mandates from the Environment Agency.
- Drum Roasters:Rotating steel drums apply conductive and convective heat for precise Maillard reaction control. Artisan cafés across London's Shoreditch and Manchester's Northern Quarter favor these systems for sensory profiling repeatability.
- Fluid Bed Roasters:Hot-air suspension roasting cuts cycle times and carbon intensity per kilogram. Bristol's sustainability-focused micro-roasteries are retrofitting compact units to meet Plastic Packaging Tax-aligned carbon reporting thresholds.
- Convection Roasters:Forced-air circulation systems dominate mid-scale production floors serving hotel chains.
- Hybrid Roasters:Dual-mode thermal systems allow operators to switch between drum precision and fluid bed speed.
Drum Roasters sits at the top of the volume ranking, with Fluid Bed Roasters climbing the fastest.
Bean Origin Focus:
Procurement patterns split between traceability premiums and commodity volume plays across wholesale channels.
- Single-Origin:Unblended lots from named cooperatives carry GPS-mapped harvest documentation. Independent chains along the London-Leeds corridor leverage these credentials to defend against specialty entrants.
- Blend:Multi-origin recipes optimize cost and flavor consistency for foodservice contracts. Volume-driven roasting for corporate offices and catering services depends on these formulations for margin protection.
- Organic:Certified chemical-free cultivation meets Soil Association standards for health-conscious retail segments.
- Fair Trade:Minimum price guarantees to producer cooperatives attract ethically positioned hospitality operators.
- Specialty:Q-graded lots above 80 points command pricing premiums in direct-trade relationships.
Blend captures the largest share of kilograms roasted, while Single-Origin gains share fastest in revenue terms.
End User:
Customer scale determines equipment sizing and service intensity from roastmaster technical support.
- Cafés:Independent operators from Bristol to Leeds drive in-house roasting adoption for batch control. These accounts prioritize compact footprint machines with origin traceability dashboards.
- Restaurants:Fine-dining and casual dining groups specify consistent roast profiles for espresso program reliability.
- Hotels:Multi-site hospitality groups centralize procurement around vertically integrated roasters offering volume discounts.
- Corporate Offices:Workplace coffee programs favor pre-ground portion packs with minimal equipment complexity.
- Catering Services:Mobile and event operators require shelf-stable packaging for off-site brewing logistics.
Cafés anchor the installed base by unit count, with Hotels expanding capacity most aggressively.
Distribution Channel:
Channel selection reflects customer technical sophistication and packaging format requirements.
- Direct Sales:Roaster-owned account teams serve large foodservice operators with customized roast profiles. These relationships lock in multi-year supply agreements with technical training components.
- Online Retail:E-commerce platforms connect artisan roasters to home consumers seeking subscription freshness. Compostable valve bag formats dominate this channel to satisfy Plastic Packaging Tax compliance.
- Wholesale Distributors:Broadline foodservice distributors aggregate demand from restaurants and hotels for consolidated delivery.
- Specialty Stores:Independent retail grocers and delis curate regional roaster selections for discovery-oriented shoppers.
Wholesale Distributors handles the greatest tonnage, with Online Retail expanding most quickly in transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK's coffee roasting tradition traces to eighteenth-century London trading houses, with industrial-scale drum roasting consolidating during the Victorian era before specialty micro-operations re-emerged across England's metropolitan corridor.
London and the Southeast
Independent cafés in Shoreditch and Brixton drive in-house roasting adoption for batch control and origin transparency. The Environment Agency enforces emissions monitoring under urban air quality management area designations. Artisan clusters in Hackney and Peckham retrofit compact fluid bed systems to meet carbon reporting thresholds.
The Midlands
Mid-scale production floors in Birmingham and Nottingham serve hotel chains and foodservice distributors with volume-driven blend roasting. The British Standards Institution certifies equipment safety under BS EN ISO standards across manufacturing zones. Leicester's industrial estates host roasting facilities upgrading to electrified thermal systems.
North England
Manchester's Northern Quarter anchors specialty café density with precision drum roasting for sensory profiling repeatability. Extended Producer Responsibility frameworks mandate producer accountability for end-of-life packaging across Greater Manchester. Leeds emerges as a secondary hub with independent chains leveraging transparency credentials.
Southwest England
Bristol's sustainability-focused micro-roasteries adopt fluid bed technology and B-Corp certification pathways. The Plastic Packaging Tax accelerates compostable valve bag adoption among cellulose film converters. Bath and Exeter extend the corridor with café operators consolidating around vertically integrated suppliers.
Scotland
Edinburgh and Glasgow develop specialty roasting capabilities serving premium hospitality and retail channels. Scottish Environmental Protection Agency emissions guidelines constrain burner technology choices in urban centers. Highland and Islands operations experiment with small-batch single-origin roasting for tourism-adjacent retail.
UK Coffee Roaster Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the UK coffee roaster landscape. Vertically integrated roasters with captive roasting equipment and direct-trade sourcing relationships occupy differentiated positions against wholesale-dependent cafés outsourcing production. Three archetypes dominate: origin-specialist micro-roasteries, scale-driven contract manufacturers, and equipment-integrated café chains. Competitive intensity concentrates on B-Corp certification races and compostable packaging supply lock-ins.
Among London-based specialty operators, Square Mile Coffee and Volcano Coffee Works exemplify technology-differentiated positioning, while Origin Coffee anchors the direct-trade archetype with cooperative-level sourcing relationships. These three occupy distinct competitive vectors: precision drum roasting leadership, fluid bed innovation with B-Corp credentials, and East African traceability focus respectively.
| Leading Market Players |
|---|
| Origin Coffee |
| North Star Coffee Roasters |
| Balance Coffee |
| Chipp Coffee Co |
| White Label Coffee Co |
| Assembly Coffee |
| Square Mile Coffee |
| Coffee Direct |
| Volcano Coffee Works |
| Others |
Pricing and Supply Chain Analysis
Independent cafés across England's metropolitan corridor from London to Leeds concentrate procurement power, anchoring a contract-based pricing structure where multi-year supply agreements lock in roast profile customization and technical training bundles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the UK coffee roaster landscape. Premium tiers command higher pricing through Soil Association organic certification and B-Corp environmental credentials, while economy tiers serve volume-driven foodservice contracts with thinner margins. Cost compression in wholesale blend roasting is intensifying because green coffee bean price volatility on ICE Arabica futures exposes operators to currency swings. Corporate office and catering service buyers exhibit the highest price sensitivity, whereas specialty cafés prioritize origin traceability over per-kilogram cost.
Supply Chain Analysis
Reusable transport container networks between roasters and foodservice distributors are eliminating single-use packaging from B2B logistics flows. Green coffee supply concentrates in Ethiopian and Kenyan cooperative channels, with Brazilian and Colombian origins supplementing volume requirements. The UK roasting sector draws from drum roasting equipment manufactured in Italy and Germany alongside fluid bed systems from Nordic engineering houses. Single-origin dependency in East African cooperatives creates harvest disruption vulnerability. Distribution runs through vertically integrated roaster-owned account teams for large foodservice operators, supplemented by broadline wholesale distributors aggregating restaurant and hotel demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
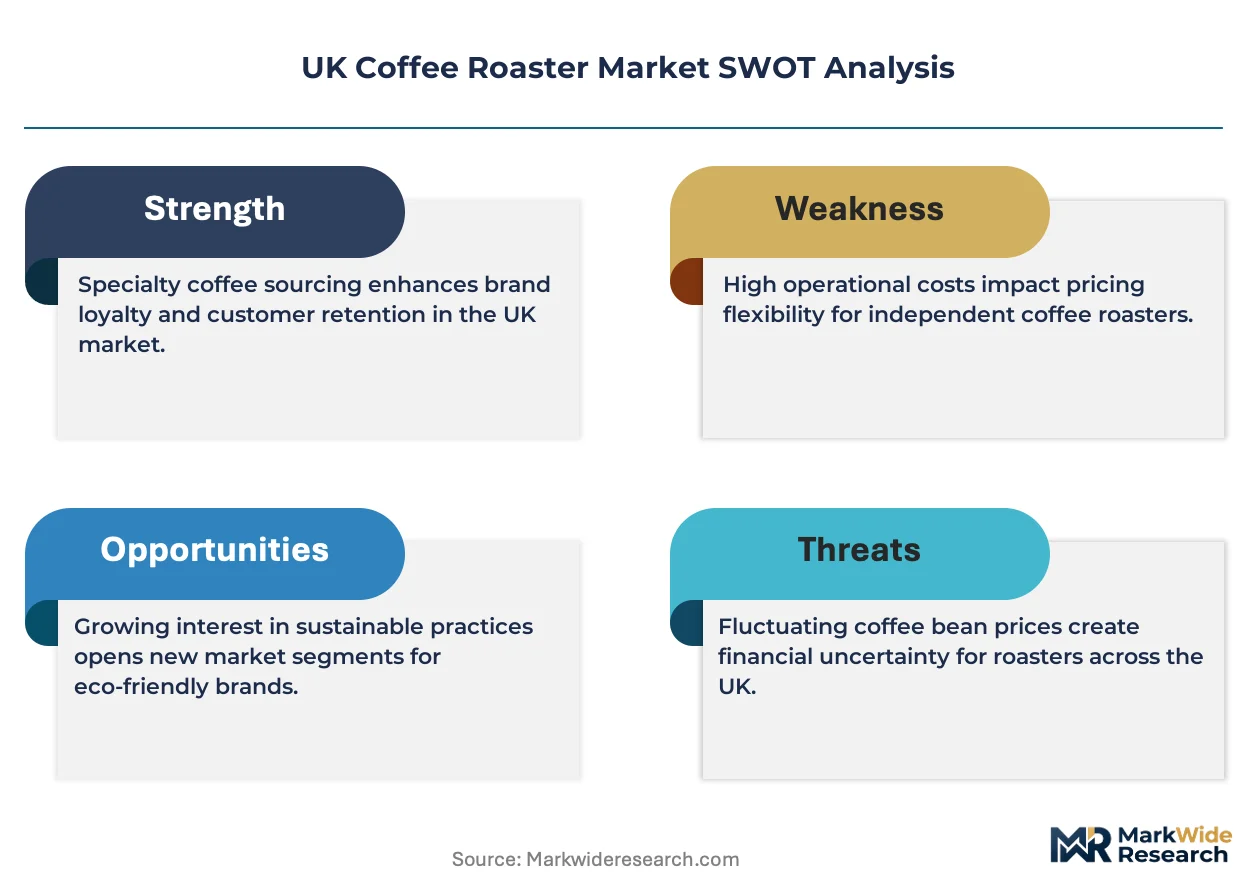
The UK coffee roaster market offers margin expansion through compostable packaging substitution and B-Corp certification premiums that offset Plastic Packaging Tax liability.
For Market Incumbents: Lock in cellulose film converter supply agreements ahead of anticipated Extended Producer Responsibility threshold reductions. Deepen backward integration into direct-trade cooperative relationships to defend against fluid bed roasting entrants from Manchester and Leeds. Prioritize roastmaster apprenticeship pipelines to address skill scarcity constraining drum system expansion. For New Entrants and Emerging Players: Capture Bristol's sustainability-focused micro-roastery segment through compact fluid bed retrofit offerings paired with home-compostable valve bag formats. Target hotel chain procurement committees in the Midlands with electrified thermal systems that satisfy Environment Agency emissions guidelines. Lead with carbon reporting dashboard integration as your go-to-market differentiator. For Investors and Strategic Acquirers: Vertically integrated café chains with captive roasting equipment are the most active acquirer in this space, consolidating independent roasters to secure origin traceability credentials. Acquisition target archetypes include B-Corp-certified fluid bed specialists and cellulose packaging converters with Food Standards Agency compliance pathways. Monitor Environment Agency air quality management area designations for facility siting constraint signals.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Packaging Transition | Cellulose-based valve bags eliminate Plastic Packaging Tax exposure for specialty retail channels. |
| Fluid Bed Technology Retrofit | Hot-air roasting systems reduce cycle times and carbon intensity per kilogram for Bristol operators. |
| B-Corp Certification Pathway | Verified environmental credentials unlock pricing premiums from sustainability-conscious London consumers. |
| Direct-Trade Cooperative Lock-in | East African GPS-mapped harvest documentation defends against specialty entrants along the London-Leeds corridor. |
| Electrified Thermal System Upgrade | Clean burner technology satisfies Environment Agency monitoring in urban air quality management areas. |
Research Methodology
Coverage spans England's metropolitan corridor, Scotland's central belt, and Southwest England's sustainability clusters, with primary inputs from each. The research combines structured interviews with roastmaster operators, café procurement managers, and foodservice distributor category buyers alongside secondary validation through British Standards Institution equipment certification records, Environment Agency emissions filings, and Soil Association organic certification databases. Bottom-up demand modeling from café and hotel equipment replacement cycles triangulates against top-down value chain analysis of green coffee import flows.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. The analytical framework segments by roaster type, bean origin focus, end user scale, and distribution channel intensity, with regional regulatory cluster overlays for Environment Agency air quality management areas. CAGRs derive from equipment replacement cycle analysis and specialty café density metrics, incorporating fluid bed technology adoption curves and compostable packaging substitution rates as industry-specific inputs.
Underlying measurement precision varies by segment; drum roaster installed base estimates carry tighter precision than fluid bed retrofit projections. Forecasts reflect assumptions regarding Extended Producer Responsibility implementation timelines and green coffee commodity price stability. Practitioners should monitor Environment Agency emissions guideline revisions and Plastic Packaging Tax threshold adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Espresso Tamper Market
Coffee
Singapore Coffee Roaster Market
Coffee
Australia Coffee Market
Coffee
Coffee Concentrate Market
Coffee
Office Coffee Service (OCS) Market
Coffee
Espresso Coffee Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Take Out Coffee Market
Coffee
GCC Instant Coffee Market
Coffee
Vietnam Coffee Market
Coffee
Global Automatic Coffee Machines Market
Coffee
Encapsulated Caffeine Market
Coffee
Portable Espresso Machines Market
Coffee
Saudi Arabia Coffee Roaster Market