
 Canned Coffee Market | 2026-2036
Canned Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Coffee Market Intelligence
Demand from fitness enthusiasts for functional, low-sugar options is collapsing the traditional focus on office workers seeking a simple caffeine boost. This shift favors brands that can innovate with ingredients like protein and adaptogens. Starbucks Corporation leverages its global cafe presence and brand equity to dominate premium segments. The Coca-Cola Company extends its vast distribution network to place products in high-traffic retail locations, while Suntory Beverage & Food specializes in unique flavor profiles tailored to Asian consumer palates.
Canned coffee is a commercially sterilized, ready-to-drink beverage sealed in an airtight container to ensure shelf stability. The process often involves retort sterilization or nitrogen flushing to preserve the aromatic compounds and prevent oxidation, delivering a consistent taste profile. While ready-to-drink remains the core product type, cold brewed coffee represents the fastest-growing category due to its smoother taste. Convenience stores and vending machines constitute the primary distribution channels, though online retailers are expanding access to specialty and craft offerings.
Product formulation and market access are shaped by national food safety regulations. In the United States, the FDA governs caffeine content disclosure and nutritional labeling. Concurrently, the EU Green Deal's packaging waste reduction targets influence material choices, favoring recyclable aluminum. Vendor success will hinge on balancing divergent regional consumer preferences for sweetness with evolving sustainability mandates for packaging materials.
Market Dynamics
The canned coffee market is defined by a central tension between mass-market convenience and the demand for premium, functional beverages. This dynamic pits high-volume, low-margin products against innovative formulations with ingredients like protein and adaptogens, fundamentally altering product development and channel strategies.
Growth Catalysts
- Functional Ingredients:Demand from health-conscious consumers for beverages with added benefits like protein for muscle recovery or adaptogens for stress reduction is creating new premium product categories.
- Distribution Infrastructure:The high density of vending machines, particularly in Japan, provides an unparalleled distribution channel that ensures widespread product availability and drives high consumption volumes.
- Preservation Technology:Advances in techniques such as nitrogen flushing and improved retort sterilization methods better preserve the delicate aromatic compounds of coffee, enhancing taste and extending shelf life.
Market Restraints
- Input Cost Volatility:The market is highly exposed to fluctuations in the global price of green coffee beans, a primary raw material, which can compress manufacturer margins and lead to price instability for consumers.
- Packaging Regulations:The EU Green Deal's targets for packaging waste reduction impose stringent recyclability requirements, increasing compliance costs and forcing investment in alternative materials like aluminum.
- Substitution Threat:A growing culture of specialty coffee and the proliferation of sophisticated home-brewing equipment present a significant substitution threat, pulling consumers away from ready-to-drink formats.
Strategic Opportunities
- Geographic Expansion:Significant opportunity exists in North American and European markets where the cold brew and specialty RTD coffee segments are less mature compared to Asia, offering white space for new brand entry.
- Plant-Based Formulations:Developing canned coffee products using plant-based milk alternatives, such as oat, almond, and soy, can capture a growing consumer base seeking vegan and dairy-free options.
- Direct-to-Consumer Channels:Online subscription models offer a route to market that bypasses traditional retail, allowing craft and specialty brands to build direct relationships and secure recurring revenue.
Industry Challenges
- Quality Consistency:Maintaining a uniform taste profile across vast production batches and diverse geographic regions presents a major operational challenge, requiring stringent quality control over the entire coffee bean supply chain.
- Regulatory Navigation:Managing divergent international food labeling laws, such as the FDA's requirements for caffeine disclosure and the EU's nutritional information standards, adds complexity and cost to global operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Coffee Market |
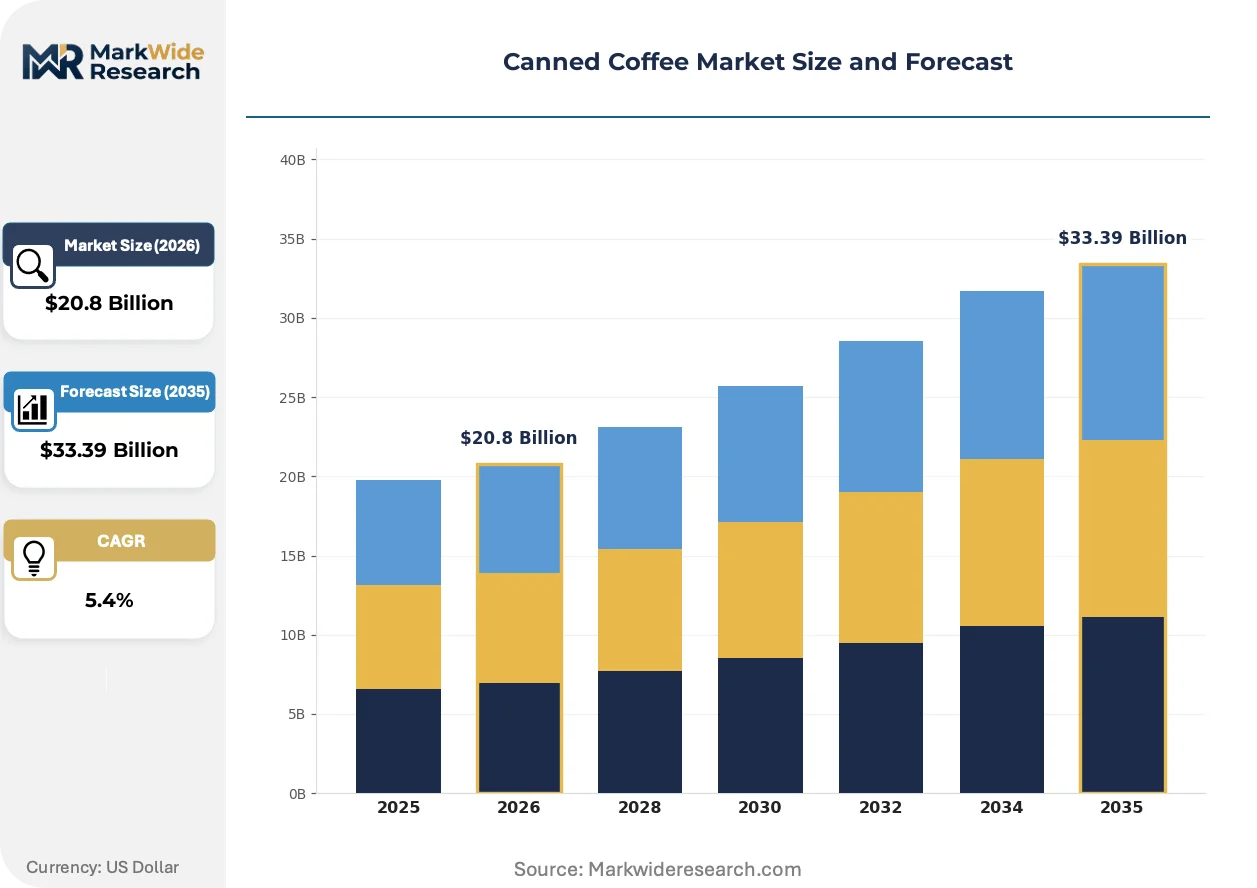
| Market Size in 2026 | $20.8 Billion |
| Market Size in 2035 | $33.39 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Drink, Hot Brewed, Cold Brewed, Espresso Blend, Flavored Coffee Packaging Type: Aluminum Can, Steel Can, Eco-friendly Pack, Glass Bottle, Plastic Bottle Distribution Channel: Supermarkets & Hypermarkets, Convenience Stores, Online Retailers, Vending Machines, Specialty Cafés Consumer Segment: Office Workers, Students, Fitness Enthusiasts, Commuters, Hospitality Sector |
| Companies Covered | Keurig Dr Pepper, PepsiCo, Nestlé S.A., Starbucks Corporation, Asahi Group Holdings, The Coca-Cola Company, Ueshima Coffee, Lotte Chilsung Beverage, Suntory Beverage & Food, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Coffee Market Strategic Shifts & Innovations
Product innovation is moving beyond simple caffeine delivery toward functional beverages and premium taste profiles. This shift reflects a deeper consumer interest in health benefits and a more sophisticated coffee experience, influencing everything from ingredient sourcing to processing technology.
Cold brew extraction technology creates a coffee concentrate with significantly lower acidity and a smoother, less bitter taste compared to traditional hot-brewed methods. Health-conscious consumers and coffee aficionados are rapidly adopting these products for their superior flavor. The smoother profile of cold brew is displacing the harsher taste of conventional retort-sterilized canned coffee, establishing a new benchmark for quality in the ready-to-drink category.
The European Union's Green Deal, through its Circular Economy Action Plan, mandates increased recyclability and recycled content for beverage packaging. This policy directly impacts material choices, favoring single-material containers like aluminum over complex, multi-layered plastics or cartons. Canned beverage producers targeting the EU are most affected, accelerating their transition to aluminum cans and investing in closed-loop recycling partnerships to meet compliance.
A notable behavioral shift involves the transition from impulse buys to planned, routine consumption, especially for functional coffee products. This trend disrupts the dominance of single-can purchases in convenience stores, favoring bulk procurement through online retailers and subscription services. This pattern is most pronounced among fitness-focused consumers in North America and Europe, who integrate protein-enhanced or no-sugar canned coffees into their daily wellness regimens.
Canned Coffee Market Segmentation
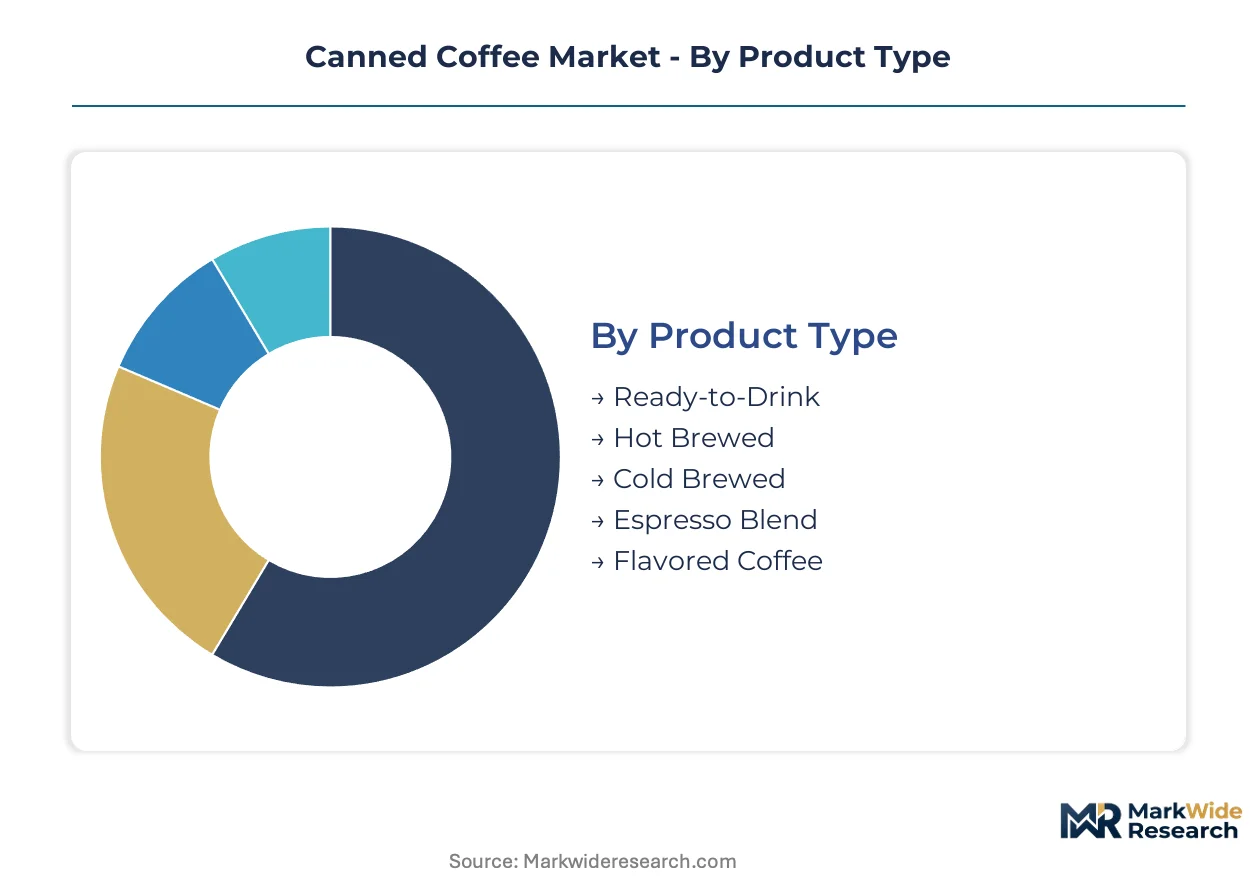
Understanding the varied segments within the canned coffee market is crucial for vendors to tailor product offerings and distribution strategies effectively. The market's segmentation reflects diverse consumer preferences, technological advancements in packaging, and the evolving landscape of retail and digital commerce.
Product Type:
Product type segmentation reveals a clear geographic divide in consumption patterns, with traditional hot-brewed options dominating in some Asian markets while cold-brewed varieties gain traction in North America.
- Ready-to-Drink:These pre-packaged beverages offer immediate consumption without preparation, providing convenience for consumers with active lifestyles. Demand for ready-to-drink options is particularly high in Japan, driven by extensive vending machine networks and urban commuting patterns.
- Cold Brewed:This coffee is steeped in cold water for an extended period, resulting in a smoother, less acidic taste profile. Cold brewed coffee experiences significant demand growth among health-conscious consumers in the United States, who appreciate its lower bitterness and natural sweetness.
- Hot Brewed:Traditional coffee prepared by brewing with hot water and then canned, often through retort sterilization for shelf stability.
- Espresso Blend:Canned coffee products formulated with a higher concentration of coffee solids, mimicking the intensity of espresso shots.
- Flavored Coffee:Beverages infused with various flavorings such as vanilla, caramel, or mocha, appealing to consumers seeking diverse taste experiences.
Ready-to-Drink holds the largest share; momentum sits with Cold Brewed.
Packaging Type:
Packaging innovation significantly impacts product shelf life and consumer convenience, with material choices increasingly influenced by sustainability mandates. Cost-effectiveness and material availability often dictate packaging decisions across different regions.
- Aluminum Can:These lightweight, recyclable containers provide excellent barrier properties against light and oxygen, preserving coffee freshness. The EU Green Deal's circular economy mandates favor aluminum cans due to their high recyclability rates and reduced environmental impact.
- Eco-friendly Pack:This category encompasses packaging solutions designed with reduced environmental footprint, often featuring recycled content or biodegradable materials. Consumer demand in Germany for sustainable packaging drives innovation in this segment, pushing manufacturers toward responsible material sourcing.
- Steel Can:Robust and durable metal containers offering good product protection, commonly used for larger volume canned coffee products.
- Glass Bottle:Transparent packaging providing a premium aesthetic and excellent product visibility, often chosen for specialty or artisanal coffee offerings.
- Plastic Bottle:Lightweight and shatter-resistant containers, offering convenience for on-the-go consumption, though facing increasing regulatory scrutiny regarding recyclability.
Aluminum Can maintains the largest market presence; Eco-friendly Pack is gaining share fastest.
Distribution Channel:
The efficacy of distribution channels varies significantly by region, with established vending machine networks dominating in some areas, while online platforms expand access in others. Customer purchasing habits directly influence channel strength and development.
- Vending Machines:Automated retail units providing immediate access to canned coffee, particularly prevalent across urban centers in Japan. Their high density ensures widespread product availability and convenience for commuters.
- Convenience Stores:Small retail outlets offering quick shopping experiences and extended operating hours, serving as a primary point of sale for impulse purchases. These stores are crucial for market penetration in the United States, capitalizing on grab-and-go consumer behavior.
- Supermarkets & Hypermarkets:Large retail formats offering a wide range of products, including bulk purchases of canned coffee, catering to routine grocery shopping.
- Online Retailers:E-commerce platforms enabling direct-to-consumer sales, providing access to specialty brands and subscription models for planned consumption.
- Specialty Cafés:Establishments focused on high-quality coffee and artisanal preparations, sometimes offering their own branded canned coffee for retail.
Vending Machines secure the largest sales volume; Online Retailers are expanding most quickly.
Consumer Segment:
Consumer segments are delineated by their distinct needs and purchasing motivations, ranging from functional benefits to convenience. Tailoring product formulations and marketing messages to these specific groups optimizes market penetration.
- Fitness Enthusiasts:Individuals seeking functional beverages that support their active lifestyles, often prioritizing protein-enriched or low-sugar canned coffee. This segment's demand for performance-enhancing ingredients drives product innovation in North America.
- Office Workers:Professionals seeking a quick and convenient caffeine boost during their workday, often prioritizing accessibility and consistent taste. This traditional segment represents a stable demand base across developed economies.
- Students:Young consumers seeking affordable and accessible energy drinks for study sessions or social activities.
- Commuters:Individuals requiring ready-to-drink options for consumption during travel, valuing portability and speed of access.
- Hospitality Sector:Businesses such as hotels, restaurants, and catering services purchasing canned coffee for guest amenities or beverage service.
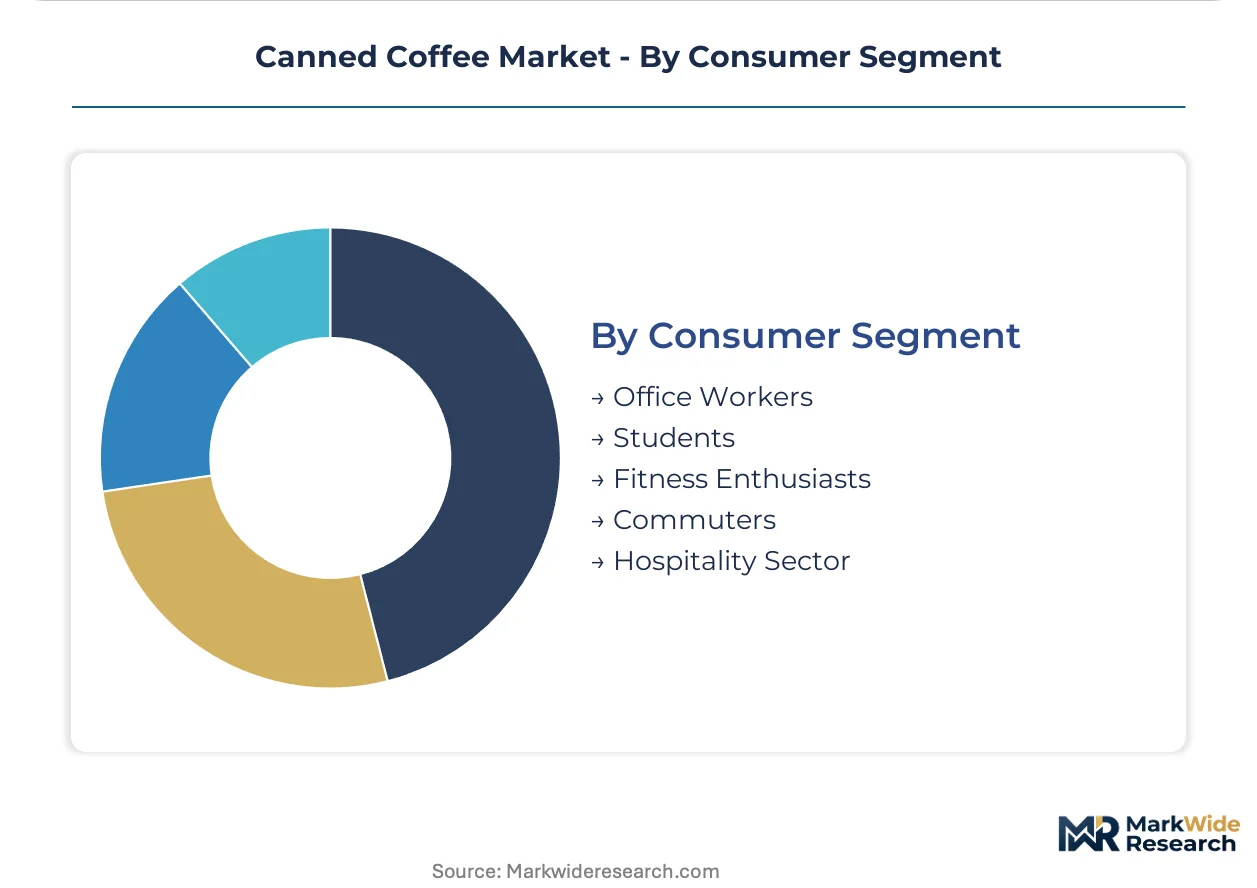
Office Workers hold the largest consumption base; Fitness Enthusiasts demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's extensive vending machine network drives significant canned coffee consumption, influencing product development across Asian markets. Exports of specialized formulations from Japan increasingly flow into Southeast Asian buyer geographies. This trade corridor facilitates the diffusion of unique flavor profiles and packaging innovations.
Japan
Demand for convenience and diverse flavor profiles drives the Japanese market, particularly among urban commuters. The Ministry of Economy, Trade and Industry (METI) promotes innovation in food and beverage technology, encouraging new product development. Tokyo's extensive urban centers concentrate vending machine density, ensuring high product availability and driving frequent consumption rates.
United States
Health-conscious consumers in the United States seek functional and low-sugar canned coffee options, particularly the cold brew variety. The FDA governs caffeine content disclosure and nutritional labeling for all ready-to-drink beverages. New York City's diverse consumer base fuels demand for premium cold brew and specialty offerings, often found in convenience stores.
Germany
Consumer preference in Germany for sustainable packaging significantly influences material choices for canned coffee products. The EU Green Deal's circular economy mandates target increased recyclability across the beverage sector, favoring aluminum. Hamburg's port facilities serve as a crucial entry point for imported coffee beans, directly impacting local production and distribution costs.
China
Rapid urbanization in China fuels demand for convenient, ready-to-drink coffee formats, especially among younger demographics. The SAMR regulates food safety standards and labeling requirements for imported and domestic products, ensuring consumer protection. Shanghai's metropolitan area exhibits strong growth in premium and flavored canned coffee consumption, reflecting evolving taste preferences.
Canned Coffee Market Key Industry Players
Listed leaders compete with private specialists across distribution reach and product innovation within the canned coffee market. The market exhibits a tiered structure, with global beverage giants dominating mass-market segments through extensive networks. Smaller, agile brands often focus on niche segments like cold brew or functional formulations, leveraging direct-to-consumer channels. Competitive moves include geographic expansion into underserved regions and strategic partnerships for ingredient sourcing.
Global beverage conglomerates like The Coca-Cola Company represent the scale-driven end of the market, leveraging vast distribution networks to reach mass consumers across multiple geographies. Starbucks Corporation occupies a premium position, extending its brand equity from cafes into ready-to-drink formats, particularly in North American and European markets. Nestlé S.A. exemplifies broad portfolio diversification, offering various coffee products across different price points and consumer segments, from instant to canned options. These entities anchor market strategies around brand recognition and established market access, often shaping consumer preferences through marketing efforts.
| Leading Market Players |
|---|
| Keurig Dr Pepper |
| PepsiCo |
| Nestlé S.A. |
| Starbucks Corporation |
| Asahi Group Holdings |
| The Coca-Cola Company |
| Ueshima Coffee |
| Lotte Chilsung Beverage |
| Suntory Beverage & Food |
| Others |
Cost & Logistics Intelligence
The material shift from plastic to aluminum cans reshapes the canned coffee supply geography and influences pricing economics. This substitution dynamic impacts both raw material procurement and downstream distribution costs across various markets.
Pricing Analysis
The pricing gap between conventional retort-sterilized canned coffee and advanced cold-brew formulations reflects differing production costs and consumer value perceptions. Pricing stratifies across premium, standard, and economy tiers, driven by ingredient quality and brand equity. Input cost volatility, particularly for green coffee beans, is forcing price adjustments across all segments. Fitness enthusiasts exhibit lower price sensitivity for functional, premium options, while office workers remain highly sensitive to standard product pricing.
Supply Chain Analysis
Maintaining consistent inventory levels for canned coffee products requires careful management of international shipping lead times. Supply concentrates significantly in Japan, with notable sourcing from Brazil and Vietnam for green coffee beans. The market relies heavily on aluminum for packaging, creating a dependency on global metal markets. Commodity price volatility for coffee beans and aluminum poses a significant structural risk. Distribution runs through extensive vending machine networks and convenience stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The canned coffee market is undergoing a buyer-power shift, driven by the fragmentation of consumer preferences toward functional and specialty offerings. This diversification challenges mass-market players to adapt quickly or risk losing share.
For Market Incumbents: Compound brand equity by expanding into the cold brew and functional beverage segments, which mitigates the substitution threat from home-brewing equipment. Invest in advanced retort sterilization R&D to preserve delicate flavor profiles, countering the quality perception gap. Control distribution channels through strategic partnerships with online retailers, addressing the shift from impulse buys to planned consumption. Starbucks Corporation and The Coca-Cola Company can leverage their existing networks for this expansion.
For New Entrants and Emerging Players: Anchor in plant-based formulations and eco-friendly packaging to target health-conscious consumers in North American and European markets. The underpenetrated specialty RTD coffee segment offers significant white space for innovation. Focus on direct-to-consumer online subscription models to build direct relationships and secure recurring revenue. This strategy bypasses traditional retail barriers and cultivates a loyal customer base.
For Investors and Strategic Acquirers: Capital is best deployed toward agile, mid-sized brands specializing in functional cold brew or sustainable packaging solutions for long-term viability. These targets offer strong growth potential over the next five to ten years, particularly in markets with evolving regulatory landscapes. An acquisition target archetype includes innovators with proprietary cold brew extraction technologies or established plant-based product lines. The signal to watch is sustained growth in online subscription volumes.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Development | Establishes direct customer relationships and secures recurring revenue streams. |
| Plant-Based Product Line Expansion | Captures growing demand from vegan and dairy-free consumer segments. |
| Advanced Cold Brew Technology Investment | Delivers smoother taste profiles, improving product quality and consumer appeal. |
| Recyclable Packaging Material Transition | Ensures compliance with EU Green Deal mandates and enhances brand sustainability. |
| Geographic Expansion into North America | Accesses less mature specialty RTD segments, offering white space for growth. |
Research Approach
Initial hypotheses were tested against primary input from brand managers, procurement leads, distribution channel partners, and regulatory affairs specialists, and refined through iterative analysis. This involved combining insights from in-depth interviews with extensive secondary validation. Secondary data sources included government trade statistics, company annual reports, and food safety agency guidelines like those from the FDA and SAMR. Bottom-up and top-down triangulation ensured data integrity.
Variance decomposition identified key drivers impacting market growth across the analysis window, including consumer preferences and regulatory shifts. Segmentation dimensions modeled included product type, packaging type, distribution channel, and consumer segment, alongside regional consumption patterns. Compound annual growth rates were derived from historical trends and projected market dynamics. Forecast inputs specifically considered green coffee bean prices and aluminum material costs.
Decision-makers should treat outputs as directional under current macroeconomic stability and foreseen regulatory frameworks; material deviation would warrant model refresh. Unforeseen global supply chain disruptions or significant shifts in consumer health trends could alter projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Italy Coffee Market
Coffee
Take Out Coffee Market
Coffee
Decaffeinated Coffee Market
Coffee
Global Coffee Machine Market
Coffee
Nitrogenated Coffee Market
Coffee
Europe Coffee Market
Coffee
Coffee Concentrate Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Crystal Market
Coffee
Roast to Order Coffee Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Single-Serve Coffee Containers Market
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Flavored Cold-Brew Coffee Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
Europe Coffee Pods and Capsules Market