
 Cast Stretch Packaging Films Market | 2026-2036
Cast Stretch Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Cast Stretch Packaging Films Market Outlook
E-commerce fulfillment is expanding its share of cast stretch film consumption as automated pallet-wrapping systems replace manual operations in distribution centers. Berry Global Inc. leverages its North American manufacturing footprint to supply high-volume machine stretch grades. Sigma Plastics Group anchors its position through backward integration into resin compounding. Intertape Polymer Group competes on specialty pre-stretched formulations that reduce material usage per pallet.
Cast stretch packaging films are linear low-density polyethylene (LLDPE) films produced via flat-die extrusion and chill-roll casting, typically exhibiting 200-300% elongation at break to secure palletized loads during transit and storage. The 20 Micron and 30 Micron thickness categories dominate volume due to their balance of puncture resistance and material economy in automated wrapping lines. LLDPE-based machine stretch films command the largest value share, while pre-stretched films represent the fastest-expanding product type as warehouses seek to cut wrap cycles and film weight per load.
The EPA oversees resin production emissions from stretch film manufacturing facilities under the Clean Air Act, while ISO 9001 quality management standards govern consistency in gauge control and cling properties. The EU Green Deal's packaging recyclability targets are forcing reformulation toward post-consumer recycled content and mono-material structures. Stakeholders must monitor how California's extended producer responsibility legislation and emerging state-level plastic reduction mandates reshape specification requirements and supplier qualification criteria.
Market Dynamics
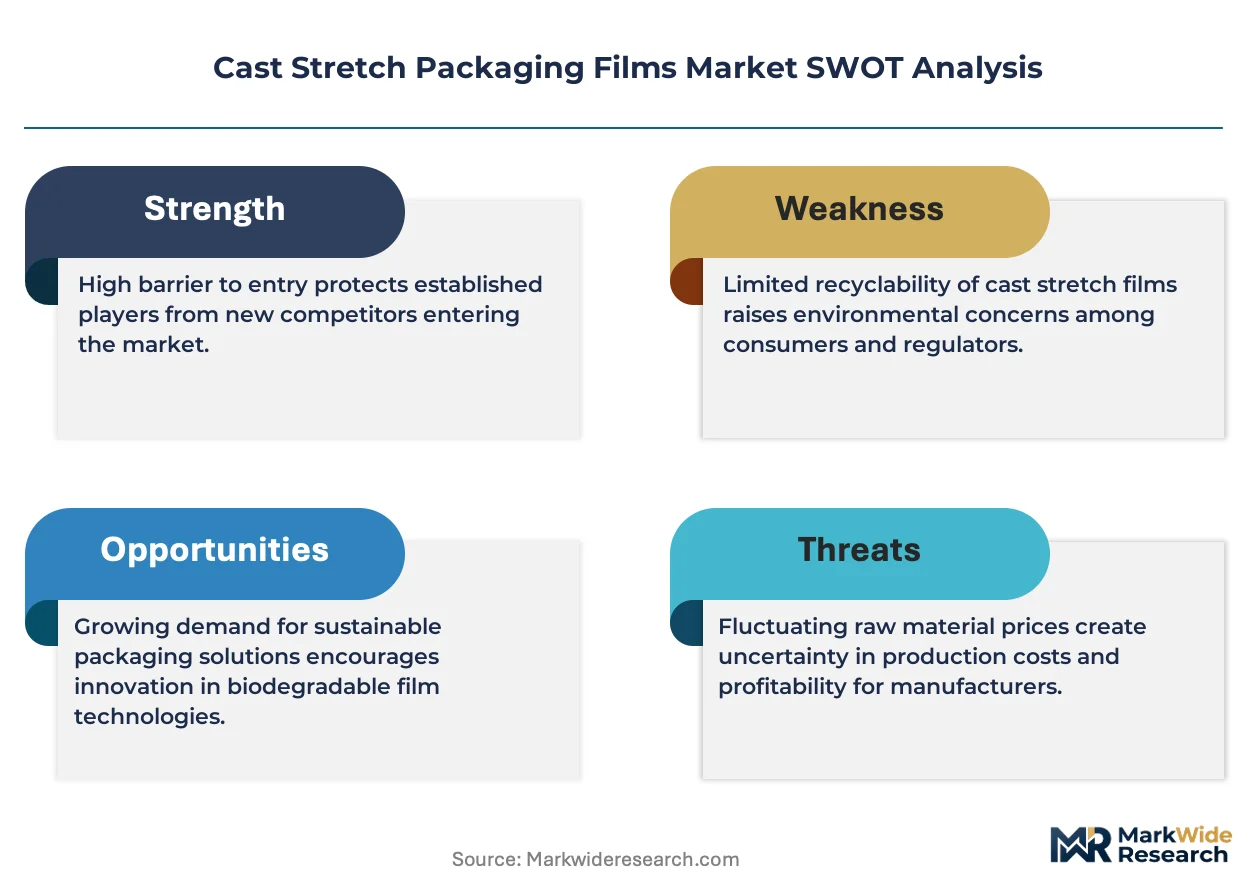
The EU Packaging and Packaging Waste Regulation is forcing resin reformulation across the value chain, compelling manufacturers to redesign multi-layer films into mono-material structures compatible with mechanical recycling infrastructure.
Growth Catalysts
- E-commerce Fulfillment Automation:Distribution centers in the United States are replacing manual pallet-wrapping with automated stretch-wrapping lines, pulling machine-grade LLDPE films into high-throughput operations.
- REACH Chemical Compliance:European formulators are accelerating development of bio-based cling additives that satisfy ECHA registration requirements while maintaining optical clarity for barcode scanning.
- Pre-stretched Film Technology:Warehouse operators are adopting pre-stretched rolls that reduce material consumption per pallet by 30-40% without sacrificing load containment force.
Market Restraints
- Ethylene Feedstock Volatility:LLDPE resin prices track naphtha and ethane markets, squeezing converter margins when upstream petrochemicals spike.
- Asian Supply Concentration:Chill-roll casting equipment and specialized die systems concentrate among German and Japanese machinery suppliers, creating procurement bottlenecks for new capacity.
- Mechanical Recycling Limitations:Multi-layer cast films with EVOH barrier layers resist separation in standard recycling streams, limiting circular economy participation.
Strategic Opportunities
- Post-consumer Recycled Content Mandates:California's extended producer responsibility legislation creates specification pull for films incorporating 30% PCR content by 2030.
- Cold-chain Pharmaceutical Logistics:Temperature-sensitive biologics distribution requires puncture-resistant stretch films that maintain integrity through freeze-thaw cycles.
- Digital Printing Integration:Inline QR-code printing on stretch film surfaces enables pallet-level traceability without secondary labeling.
Industry Challenges
- Extrusion Die Engineering Talent:The flat-die design expertise required for gauge uniformity across 2-meter widths resides with a shrinking cohort of senior polymer engineers.
- ISO 9001 Certification Timelines:New market entrants face 12-18 month quality management system audits before qualifying for automotive supplier programs.
- Legacy Winding Equipment Retrofit:Pre-stretched film production demands tension-controlled winding systems incompatible with conventional cast line configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cast Stretch Packaging Films Market |
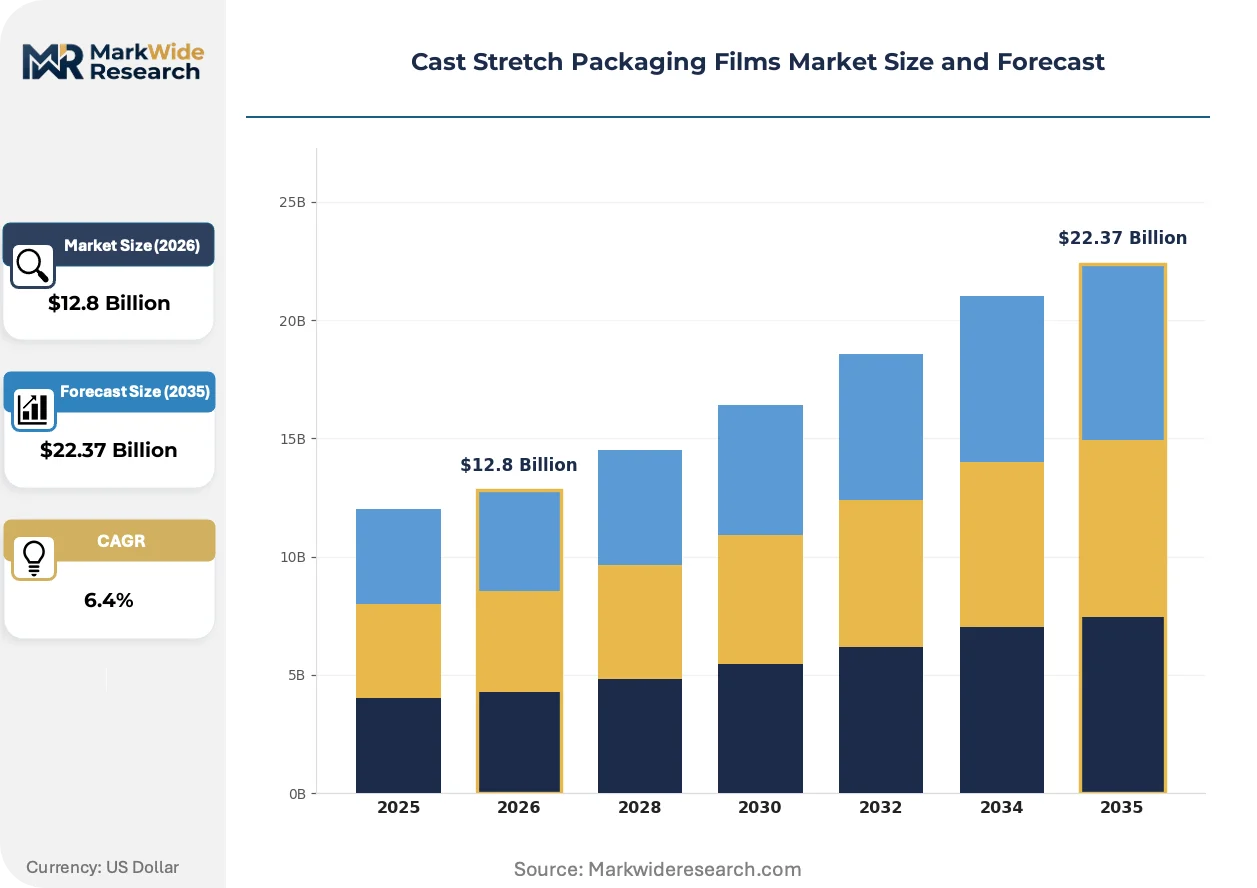
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Stretch, Machine Stretch, Pre-Stretched, Mixed Material: LLDPE, LDPE, PVC, Others Thickness: 15 Micron, 20 Micron, 30 Micron, 50 Micron End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics |
| Companies Covered | Berry Global Inc., Sigma Plastics Group, Intertape Polymer Group, Paragon Films, Manuli Stretch, AEP Industries, Inteplast Group, Amcor plc, Scientex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cast Stretch Packaging Films Market Strategic Shifts
Active reformulation toward circular-compatible materials is compressing product development cycles while automated wrapping intelligence is reshaping equipment-film interface specifications.
Metallocene-catalyzed LLDPE resins with enhanced puncture resistance are consolidating market share in automated high-speed wrapping applications. Food and beverage distributors in Germany are specifying these grades for pallet loads with sharp-cornered secondary packaging. The technology is consolidating supplier relationships around resin producers capable of consistent metallocene catalyst control.
REACH restrictions on phthalate-based cling additives are forcing migration to polyisobutylene and tackifier alternatives. Film converters serving European automotive exports must validate new additive packages through ECHA substance evaluation. Machine stretch film grades for industrial palletization bear the highest compliance burden due to load containment performance requirements.
Outcome-based film supply contracts are replacing transactional purchasing in large retail distribution networks. Third-party logistics providers in the United States are contracting for cost-per-pallet-wrapped rather than per-kilogram film pricing. This model concentrates volume with converters capable of on-site technical service and wrap-parameter optimization.
Cast Stretch Packaging Films Market Segmentation
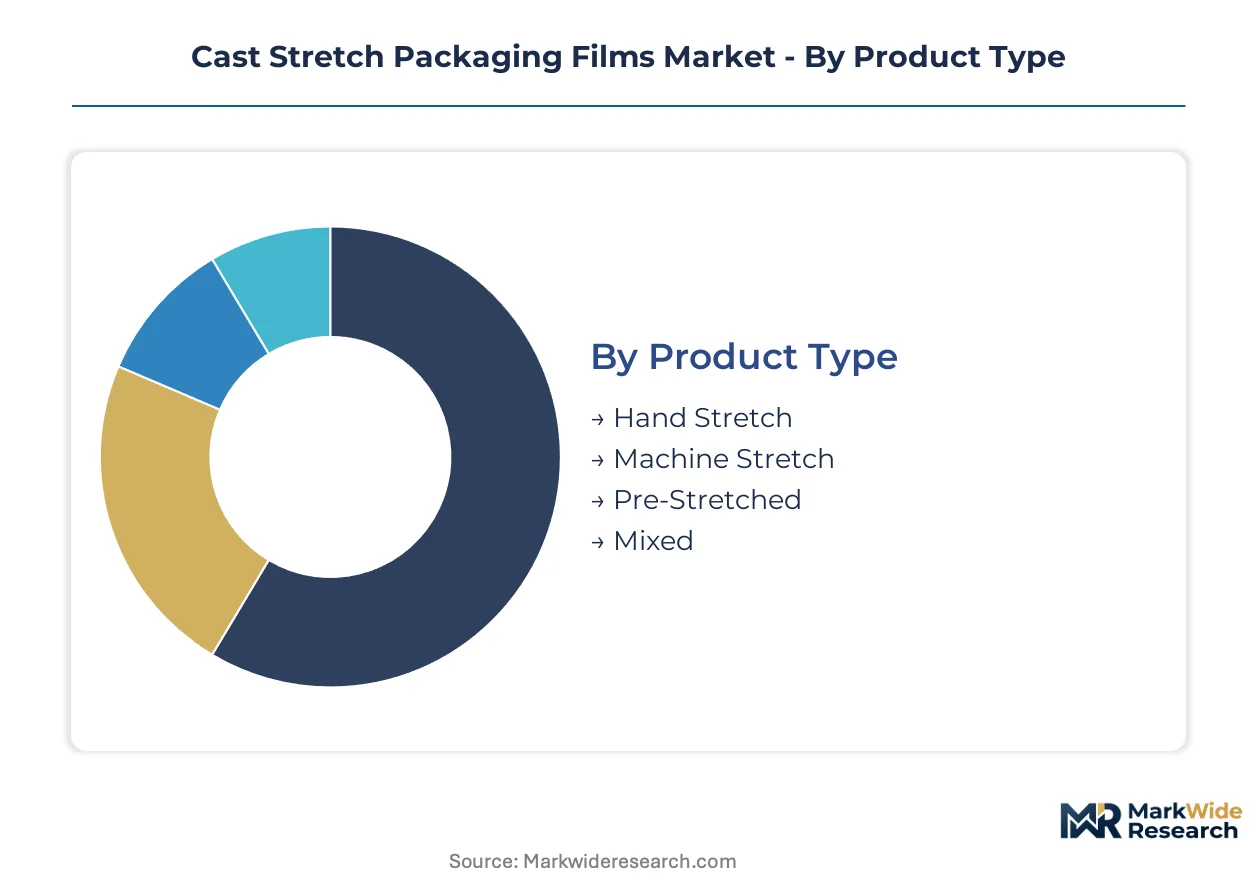
Cast stretch packaging films segment across application requirements, material specifications, and operational workflows. Understanding these divisions reveals how converter investments and end-user procurement criteria diverge across the value chain.
Product Type:
Application method and labor intensity define this axis, separating manual operations from automated lines.
- Machine Stretch:High-tensile LLDPE formulations engineered for automated turntable and rotary arm wrappers. German automotive component suppliers specify these grades for 24/7 production environments where wrap consistency reduces transit damage claims.
- Pre-Stretched:Films pre-elongated during manufacturing to 80-90% of ultimate stretch capacity. Warehouse operators in the United States adopt these rolls to cut material consumption and eliminate operator-dependent tension variation.
- Hand Stretch:Thicker, more forgiving grades for manual pallet wrapping in low-volume operations. Small freight forwarders and regional distributors rely on these for flexibility without capital equipment investment.
- Mixed:Hybrid rolls combining hand and machine compatibility for facilities with intermittent automation. Third-party logistics providers use these to standardize inventory across multiple customer sites.
Mature deployment sits with Machine Stretch. Newer deployment is concentrated in Pre-Stretched.
Material:
Resin selection governs mechanical performance, recyclability credentials, and converter margin structure.
- LLDPE:Linear low-density polyethylene dominates through superior puncture resistance and elongation characteristics. Metallocene-catalyzed grades from Dow and ExxonMobil command premium positioning in high-speed automated applications.
- LDPE:Lower crystallinity resins offering softer hand feel and easier unwind for manual wrapping. European converters blend LDPE with LLDPE to optimize cling properties for food contact applications.
- PVC:Legacy material retained in specific cling-film applications where optical clarity exceeds polyethylene performance. REACH compliance costs have displaced PVC from most pallet wrap specifications.
- Others:Bio-based PE from sugarcane feedstock and post-consumer recycled content grades. California's extended producer responsibility mandates are accelerating specification pull for these alternatives.
Volume concentrates in LLDPE. Specification diversity is expanding fastest in Others.
Thickness:
Gauge selection balances material economy against load containment force and puncture resistance.
- 20 Micron:The workhorse specification for general palletized goods, offering optimal cost-performance for uniform loads. German food distributors specify this grade for bottled beverage shipments where puncture risk is moderate.
- 30 Micron:Heavy-duty gauge for irregular loads with sharp corners or abrasive surfaces. Automotive parts manufacturers in the United States use these films for metal component shipments.
- 15 Micron:Ultra-thin grades for lightweight, uniform loads where pre-stretch technology compensates for reduced base thickness. E-commerce fulfillment centers deploy these for parcel consolidation pallets.
- 50 Micron:Extreme-duty specification for export shipments and harsh handling environments. Cold-chain pharmaceutical logistics specify these for temperature-sensitive biologics requiring maximum puncture resistance.
Standard deployment centers on 20 Micron. Performance-critical applications are driving fastest expansion in 50 Micron.
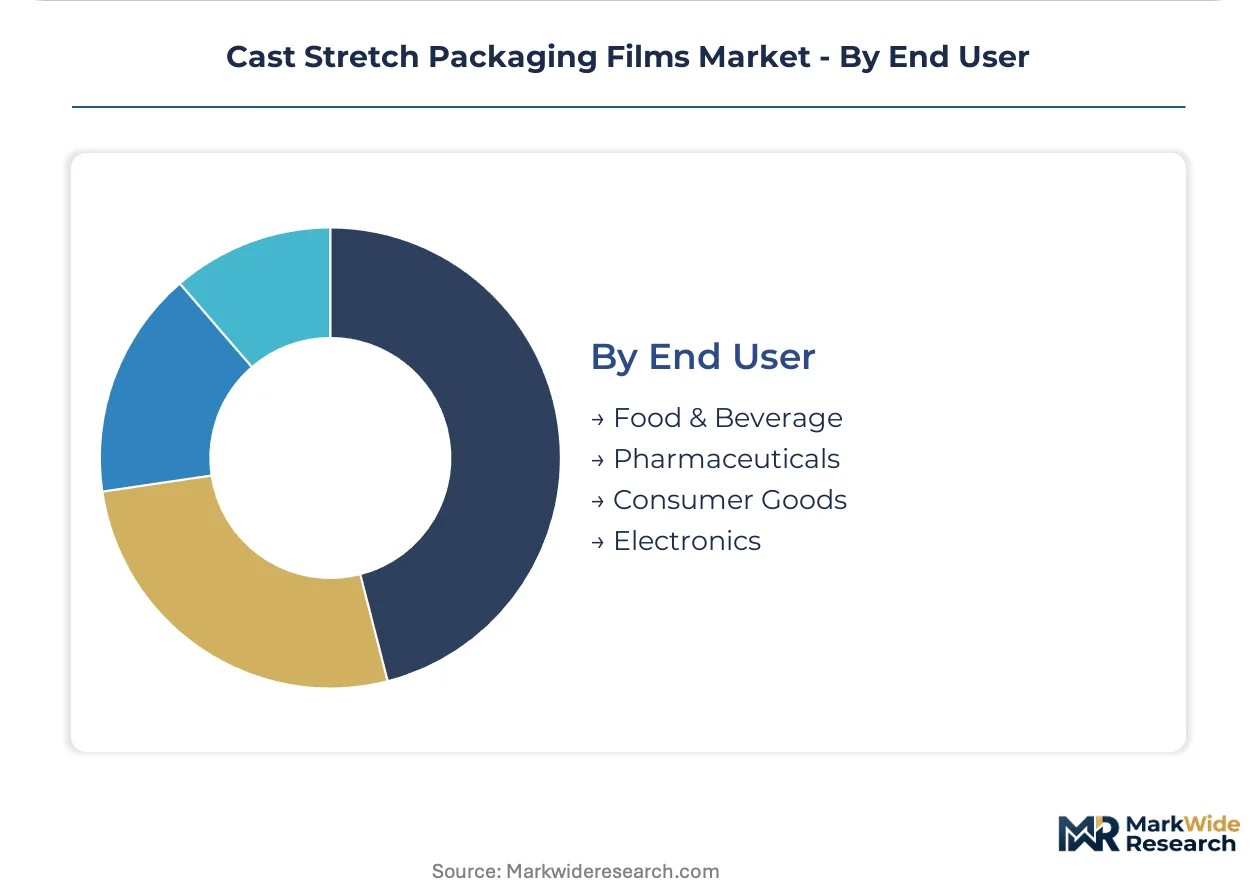
End User:
Industry-specific handling requirements and regulatory exposure shape procurement specifications.
- Food & Beverage:The largest consumption segment, spanning bottled water, dairy, and processed food distribution. German retailers specify EFSA-compliant cling additives and optical grades supporting barcode scanning.
- Consumer Goods:Diverse applications from household products to personal care with moderate performance requirements. Private-label manufacturers prioritize cost optimization over technical specifications.
- Pharmaceuticals:Stringent demands for cleanliness, traceability, and temperature stability. FDA-registered converters supply validated grades for drug distribution with full batch documentation.
- Electronics:Static-dissipative and cleanroom-compatible formulations for semiconductor and device shipments. Japanese electronics manufacturers specify JIS-compliant films for component exports.
Established volume resides in Food & Beverage. Regulatory complexity is intensifying fastest in Pharmaceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam and Mexico are drawing cast stretch film extrusion investment through tariff-advantaged export platforms. These zones concentrate new capacity near automotive assembly clusters and electronics manufacturing corridors.
United States
E-commerce fulfillment centers in Texas and Georgia are installing automated stretch-wrapping lines at record pace. The EPA's Clean Air Act enforcement shapes resin production facility siting decisions. Chicago's logistics corridor hosts third-party logistics providers contracting for outcome-based film supply models.
Germany
Automotive component exports through Hamburg and Bremerhaven drive specification of high-tensile machine stretch grades. The EU Packaging and Packaging Waste Regulation forces mono-material redesign of multi-layer films. Bavaria's industrial belt concentrates metallocene-grade compounding capacity for puncture-resistant formulations.
China
Yangtze River Delta electronics manufacturers specify static-dissipative stretch films for semiconductor shipments. MIIT's dual carbon goals accelerate specification of bio-based PE alternatives. Shenzhen's port logistics cluster demands optical-grade films supporting automated barcode scanning systems.
Japan
Pharmaceutical cold-chain distribution requires 50-micron extreme-duty films for temperature-sensitive biologics. METI's circular economy roadmaps push post-consumer recycled content integration. Osaka's chemical corridor hosts resin producers developing metallocene catalyst systems for enhanced puncture resistance.
Mexico
Nearshoring automotive assembly in Nuevo León pulls machine-grade film consumption for component shipments. The country's national environmental regulator enforces emissions standards on extrusion facilities. Tijuana's maquiladora corridor concentrates hand-stretch film consumption for cross-border freight consolidation.
Cast Stretch Packaging Films Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with resin-integrated players commanding premium positioning in automated wrapping grades while regional converters compete on logistics proximity. The vendor base concentrates among North American and European film specialists with captive resin supply relationships. Three archetypes dominate: vertically integrated resin-to-film producers, toll-conversion specialists serving private-label brands, and regional distributors with localized slitting and warehousing. Capacity expansion and backward integration into resin compounding represent the dominant competitive vectors.
Within the integrated-resin tier, Berry Global Inc. and Sigma Plastics Group exemplify scale-driven positioning through manufacturing footprint breadth. Intertape Polymer Group occupies a specialty niche focused on pre-stretched formulations. These three anchors represent divergent strategic bets on automation adoption, material efficiency, and technical service intensity.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Sigma Plastics Group |
| Intertape Polymer Group |
| Paragon Films |
| Manuli Stretch |
| AEP Industries |
| Inteplast Group |
| Amcor plc |
| Scientex |
| Others |
Value Chain & Pricing Dynamics
Third-party logistics providers in the United States and automotive component buyers in Germany dominate procurement volume, anchoring contract-based pricing with cost-per-pallet-wrapped structures that reward technical service intensity over spot transactions.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard contract terms as e-commerce fulfillment centers in Texas and Georgia prioritize inventory velocity over unit economics. Three-tier pricing structure across premium metallocene grades, standard LLDPE formulations, and economy blended resins separates automotive suppliers from food distributors from freight forwarders. Price differentiation hinges on certification tier (ISO 9001 validation for automotive programs) and volume scale (annual offtake commitments above 500-ton thresholds). Cost compression in standard machine grades is intensifying because Asian resin imports are expanding converter capacity faster than domestic demand growth. Small regional distributors exhibit highest price sensitivity, while pharmaceutical cold-chain operators absorb premiums for validated batch documentation.
Supply Chain Analysis
Polymer engineering talent shortages in Germany and chill-roll casting equipment bottlenecks from Japanese machinery suppliers are extending new capacity timelines beyond historical norms. Manufacturing concentrates in the United States, Germany, and China, with each hub serving distinct regional demand clusters. Raw material flows draw from ethylene crackers along the US Gulf Coast, naphtha-fed complexes in Rotterdam-Antwerp, and coal-to-olefins operations in Ningbo. Single-source vulnerability sits with metallocene catalyst systems controlled by Dow and ExxonMobil. Distribution runs through converter-direct relationships for automotive OEMs and layered distributor networks for small freight forwarders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cast stretch packaging films is becoming a backward-integration race as converters pursue captive resin compounding to defend margin structure against ethylene feedstock volatility.
For Market Incumbents: Lock in metallocene catalyst supply agreements and expand slitting capacity in Nuevo León to capture nearshoring automotive demand. Defend against Asian resin import pressure by embedding on-site technical service teams at major third-party logistics providers. Prioritize ISO 9001 certification maintenance for automotive supplier program retention. For New Entrants and Emerging Players: E-commerce fulfillment centers in secondary US markets represent the most penetrable white-space target, as incumbent coverage thins outside Chicago and Dallas logistics corridors. Pursue specialty pre-stretched formulations with 30-40% material reduction claims to differentiate from commodity machine grades. Build go-to-market through direct digital procurement platforms serving mid-sized regional distributors. For Investors and Strategic Acquirers: The window for entry favors resin-integrated mid-cap specialists with existing automotive certifications and underutilized extrusion capacity. Long-term viability hinges on PCR content compliance readiness for California extended producer responsibility mandates. Watch EU Packaging and Packaging Waste Regulation enforcement timelines as inflection indicator for mono-material redesign investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive LLDPE supply insulates margins from naphtha price spikes at Rotterdam-Antwerp hubs. |
| Pre-Stretched Film Capacity Expansion | Material efficiency claims align with warehouse operator cost-per-pallet targets in US distribution. |
| Post-Consumer Recycled Content Scale-Up | California EPR mandates create specification pull for 30% PCR grades by decade's end. |
| Metallocene Catalyst Partnership | Puncture-resistant formulations secure automotive component supplier relationships in Bavaria. |
| Nearshoring Manufacturing Footprint | Nuevo León extrusion lines capture automotive assembly demand from US-Mexico trade corridors. |
Study Parameters
Trade databases, SEC 10-K filings from packaging converters, and EU regulatory submissions formed the secondary backbone, supplemented by primary interviews with extrusion plant managers, automotive Tier 1 procurement leads, and third-party logistics category buyers. Bottom-up and top-down triangulation validated volume estimates across machine stretch, pre-stretched, and hand stretch product categories.
Bottom-up modeling anchored forecasts in regional production capacity, resin price trajectories, and end-use demand elasticity across food distribution, automotive component shipping, and pharmaceutical cold-chain applications. Top-down verification cross-checked against customs trade flows and extrusion equipment installation records. CAGRs derived from elasticity-adjusted demand projections and capacity utilization trends throughout the forecast period.
The model holds under stable ethylene feedstock pricing and gradual regulatory phase-in; deviation in naphtha volatility spikes or accelerated EU recyclability mandates would shift volume trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Silicone-Coated PET Films Market
Poly film
Polyethylene Film Market
Poly film
Poly Coated Kraft Paper Market
Poly film
PVC Films Market
Poly film
Polylaminate Capsules Market
Poly film
High Density Polyethylene Film Market
Poly film
Egypt Plastic Packaging Films Market
Poly film
Lidding Films Market
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
Polycoated Packaging Market
Poly film
PVC Film for Medical Market
Poly film
PP Laminating Films Market
Poly film
MOPP Packaging Films Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
Resealable Films Market
Poly film
Nylon Films Market